
 Canada Nematicides Market | 2026-2036
Canada Nematicides Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Nematicides Market Outlook
Health Canada's Pest Management Regulatory Agency re-evaluation of chlorpyrifos and other organophosphate chemistries is hardening compliance requirements across the nematicides sector. Bayer CropScience anchors its position through deep R&D pipelines in biological alternatives. Syngenta Group competes with integrated seed-treatment-plus-nematicide bundles. BASF SE differentiates via specialized formulation expertise for cold-climate application windows.
Nematicides are crop protection agents engineered to suppress or eliminate plant-parasitic nematodes through contact, systemic, or fumigant action, typically formulated as granules, liquids, or seed treatments with active concentrations ranging from single-digit to high-percentage loads. Their primary commercial purpose is protecting root architecture and yield integrity in high-value row crops and specialty vegetables. Chemical formulations still dominate volume in Prairie grain operations, while biological nematicides represent the fastest-expanding margin pool as organic acreage and export-certified production expand. Liquid formulations lead in horticulture and greenhouse channels where precision application equipment prevails, whereas granular products sustain their hold in broad-acre agriculture through compatibility with existing planting equipment.
Health Canada's PMRA governs active ingredient registration and maximum residue limits, while the Fertilizers Act and provincial environmental farm plans shape on-farm application protocols and buffer requirements. These frameworks elevate product development costs but simultaneously create competitive moats for registrants with established regulatory dossiers. Stakeholders must monitor PMRA's accelerated timeline for novel biological active substance approvals and the Prairie provinces' evolving integrated pest management mandates.
Market Dynamics
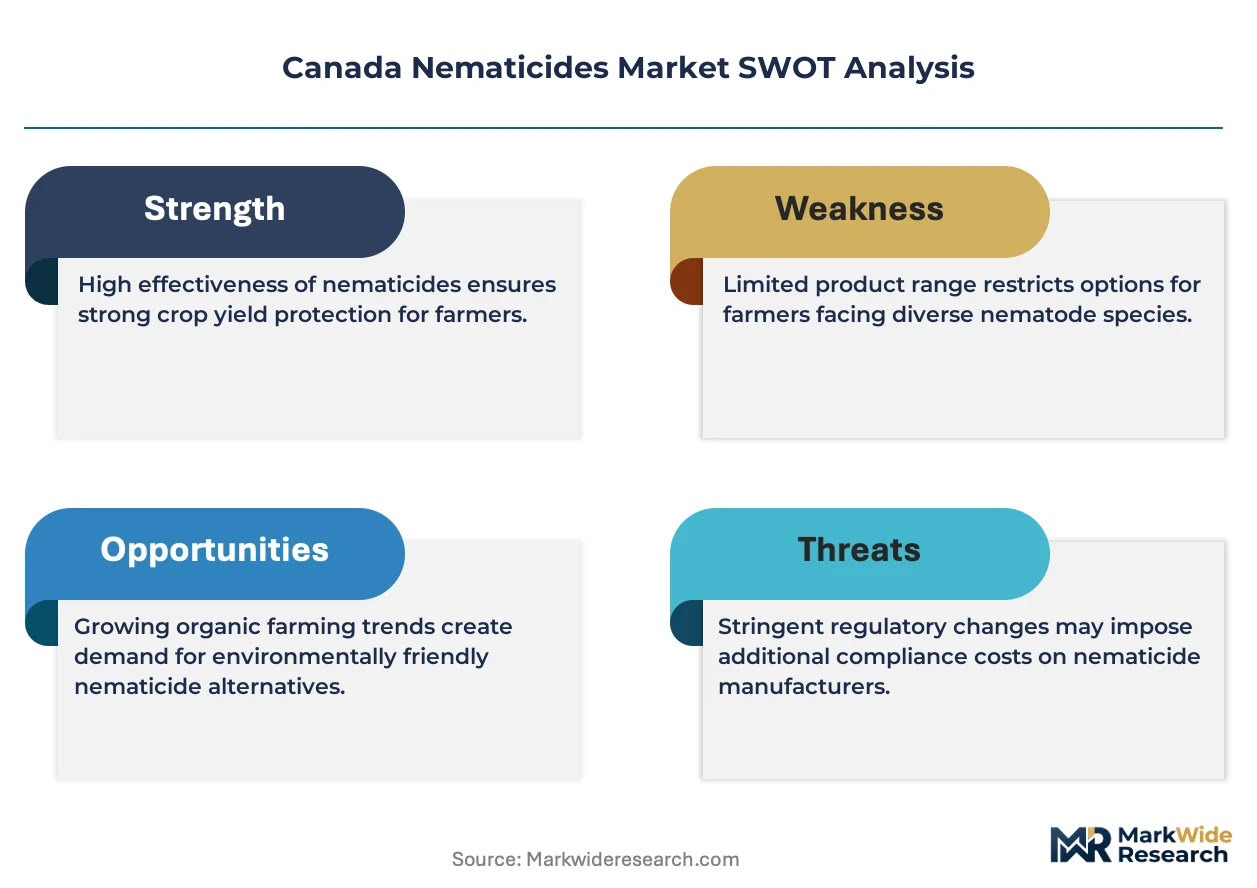
Health Canada's PMRA re-evaluation of organophosphate chemistries is forcing rapid portfolio restructuring across Canadian nematicide suppliers, compressing product development timelines while elevating biological registration priorities.
Growth Catalysts
- PMRA Accelerated Biological Pathway:Health Canada's streamlined approval framework for novel active biological substances reduces registration timelines for microbial nematicides. Prairie pulse growers gain earlier access to Bacillus-based formulations.
- Prairie Oilseed Expansion:Saskatchewan and Manitoba canola acreage is extending nematicide demand into previously untreated broad-acre rotations. Root lesion nematode pressure in these soils drives first-time chemical adoption.
- Seed-Treatment Integration:Precision application equipment is embedding nematicide delivery directly into planting operations. Ontario vegetable operations reduce labor costs through single-pass treatment systems.
Market Restraints
- Active Ingredient Concentration:Three multinational suppliers control over seventy percent of registered synthetic nematicide actives in Canada. Prairie grain operations face limited supplier choice during seasonal procurement windows.
- Cold-Climate Efficacy Thresholds:Biological nematicides require minimum soil temperatures above ten degrees Celsius for metabolic activation. Early spring application windows in Alberta and Manitoba remain chemically dependent.
- Buffer Zone Expansion:Provincial environmental farm plans under the federal Sustainable Agriculture Strategy are extending aquatic setback requirements. Field-edge acreage becomes economically unviable for treated crops.
Strategic Opportunities
- Quebec Greenhouse Biological Conversion:The province's Residual Materials Management Policy mandates fifty percent reduction in synthetic pesticide use by 2030. Hydroponic tomato and cucumber operations represent concentrated demand for microbial nematicide solutions.
- Pulse Crop Nematide Registration:Lentil and dry bean varieties lack dedicated nematicide labels compared to canola and cereals. PMRA's minor use program offers expedited pathways for crop-specific biological registrations.
- Carbon Credit Stacking:Alberta's carbon offset system and federal Clean Fuel Regulations create dual revenue streams for biological nematicide adoption. Soil health quantification methodologies are maturing for third-party verification.
Industry Challenges
- Biological Formulation Stability:Extended supply chains from European manufacturing sites to Prairie distribution hubs degrade microbial viability. Cold-chain infrastructure gaps in Saskatchewan and Manitoba limit shelf-life guarantees.
- Integrated Pest Management Certification:Provincial agronomist licensing requirements for nematode scouting and prescription writing lag behind product availability. Ontario and Quebec face certified advisor shortages during peak soil sampling periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Nematicides Market |
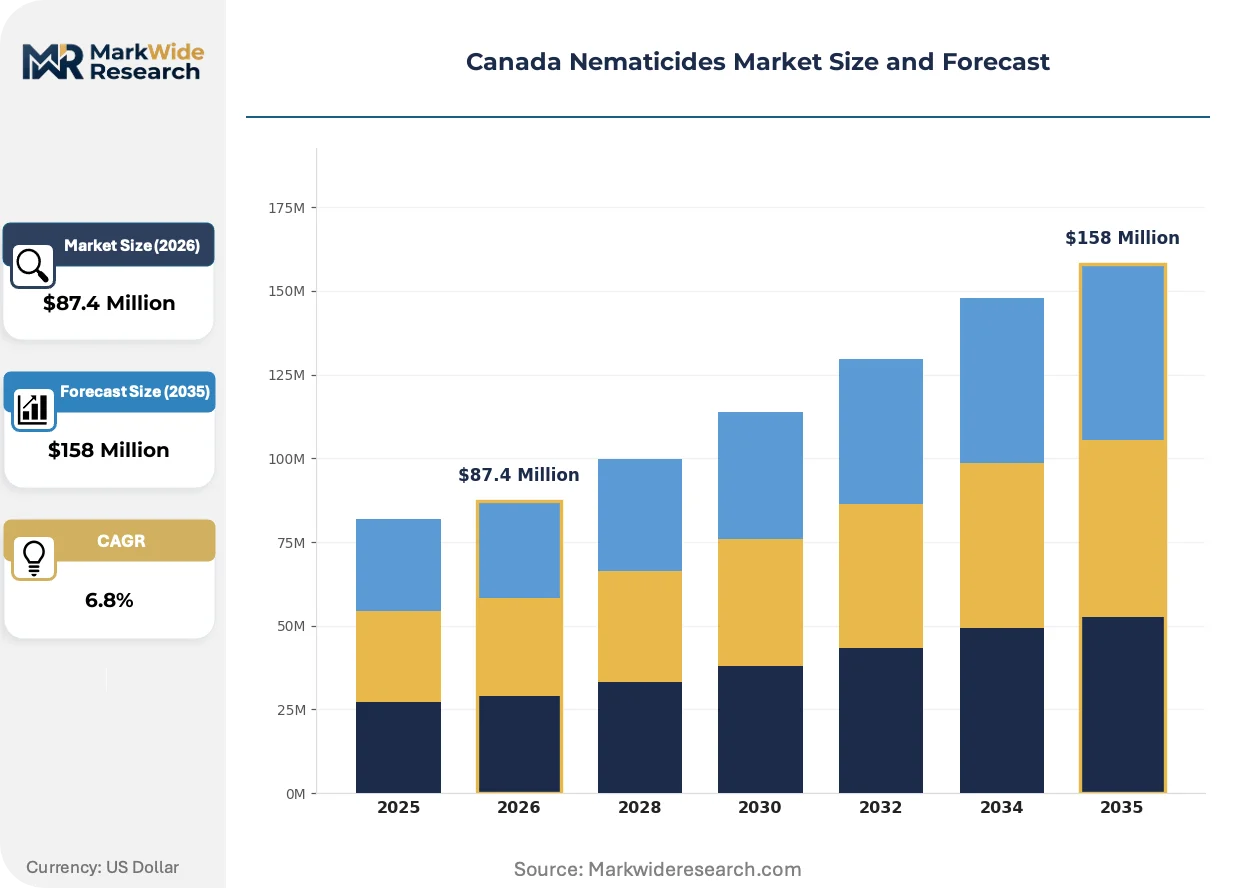
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical, Biological, Granular, Liquid Application: Agriculture, Turf, Horticulture, Greenhouse End User: Farmers, Agronomists, Wholesale Distributors, Fertilizer Retailers Formulation: Ready-to-Use, Concentrate, Soluble, Emulsifiable |
| Companies Covered | BASF SE, Bayer CropScience AG, Syngenta Group, FMC Corporation, Corteva Agriscience, UPL Limited, American Vanguard Corporation, Valent Biosciences Corp, Marrone Bio Innovations Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Nematicides Market Strategic Shifts
Biological active substance development is overtaking chemical synthesis as the primary R&D expenditure category, driven by PMRA registration incentives and export-market residue requirements.
RNA interference technology is decentralizing nematode control from broad-spectrum soil treatments to sequence-specific genetic disruption. Greenhouse cucumber and tomato growers in Leamington and Niagara are piloting dsRNA formulations against root-knot species. This precision mechanism is decentralizing product development from agrochemical conglomerates toward biotechnology specialists with genomics capabilities.
Health Canada's PMRA re-evaluation framework for organophosphates is compressing the commercial lifespan of legacy chemistries. Chlorpyrifos cancellation orders triggered immediate inventory drawdowns across Ontario potato operations. Vegetable processors supplying US export markets are accelerating biological transition timelines to preempt FDA residue enforcement actions.
Buyer consolidation among Prairie grain elevators is compressing procurement decision cycles from annual to seasonal timing. Large Saskatchewan pulse handlers now negotiate nematicide supply contracts alongside seed and fertilizer bundles. This bundling behavior is most pronounced in the Red River Valley, where processor-backed agronomy services specify approved input lists for contracted acreage.
Canada Nematicides Market Segmentation
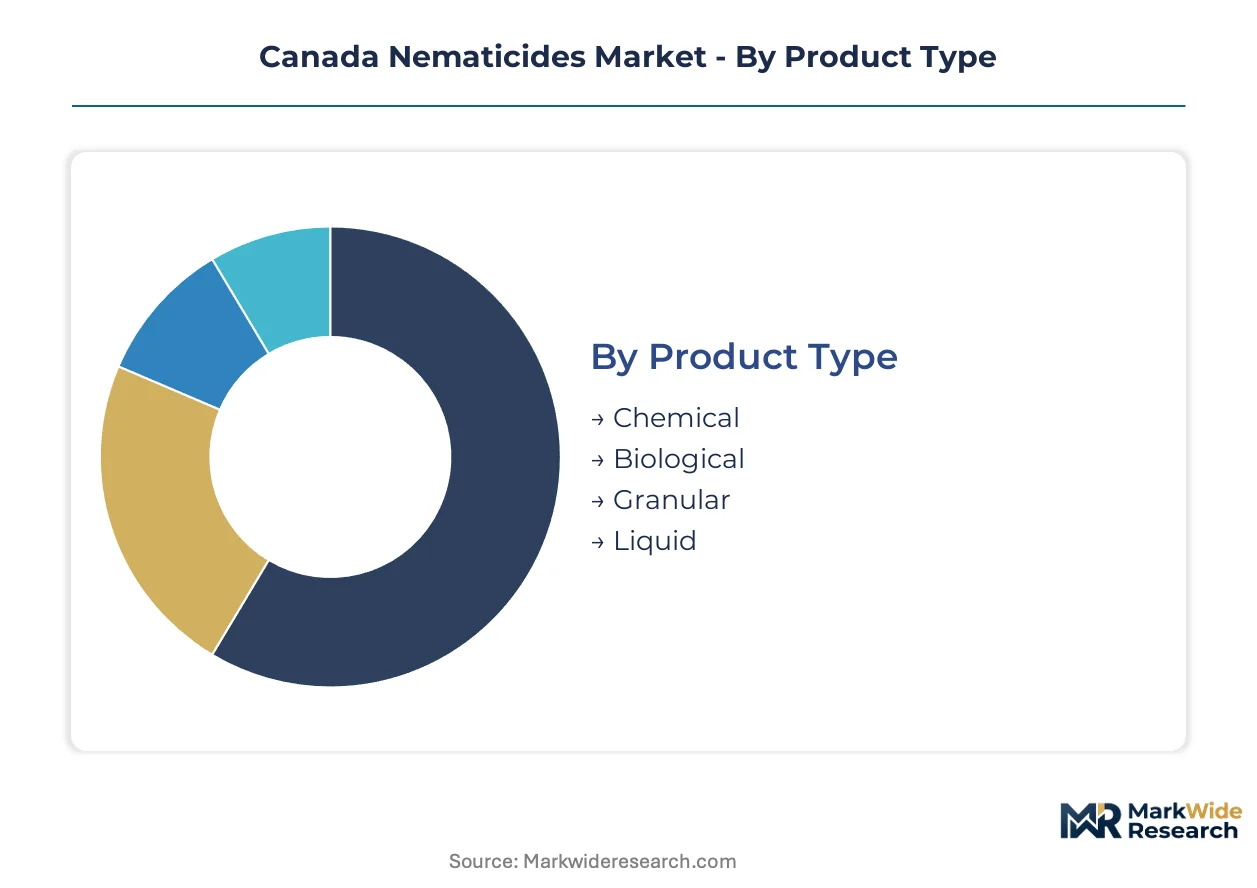
Nematicide purchasing in Canada splits sharply between broad-acre Prairie operations prioritizing cost efficiency and high-value Ontario-Quebec operations accepting premium pricing for residue compliance. Segmentation reveals how formulation chemistry and application setting dictate margin structures across the market.
Product Type:
Chemical formulations dominate Prairie volume while biological alternatives command premium positioning in export-facing operations.
- Chemical:Organophosphate and carbamate chemistries remain standard for root lesion nematode suppression in Saskatchewan canola rotations. Health Canada PMRA re-evaluations are compressing available active ingredient options, forcing growers toward pre-registration inventory builds.
- Biological:Microbial formulations utilizing Bacillus firmus and Purpureocillium lilacinum spores target cyst nematodes in organic potato acreage. Quebec vegetable operations lead adoption due to provincial pesticide reduction mandates and US export residue thresholds.
- Granular:Clay-based carrier systems enable mechanical incorporation during seeding passes in Alberta cereal production.
- Liquid:Aqueous suspensions facilitate fertigation injection in British Columbia greenhouse cucumber operations.
Mature deployment sits with Chemical. Newer deployment is concentrated in Biological.
Application:
Field-scale agriculture generates baseline volume while controlled-environment horticulture drives formulation innovation.
- Agriculture:Open-field row crops in Manitoba and Saskatchewan require nematicide protection against Pratylenchus and Heterodera species in cereal-pulse rotations. Root architecture damage in canola triggers yield penalties exceeding treatment costs at infestation thresholds above 500 nematodes per 100cc soil.
- Horticulture:Ontario's Niagara Peninsula vegetable operations deploy precision application equipment for root-knot nematode management in carrot and onion production. Processing contracts with US distributors mandate residue testing protocols that exclude certain chemical actives.
- Turf:Golf course maintenance in British Columbia's Lower Mainland addresses Anguina pacificae infestations in bentgrass greens.
- Greenhouse:Hydroponic tomato and cucumber producers in Leamington utilize recirculating irrigation systems requiring nematicide compatibility with biological filter media.
Volume concentration centers on Agriculture. Steepest expansion trajectory belongs to Greenhouse biological integration.
End User:
Procurement authority is fragmenting between direct farm purchases and processor-mandated input specifications.
- Farmers:Prairie grain operations in Alberta and Saskatchewan negotiate nematicide supply alongside seed and fertilizer bundles through elevator-procurement programs. Individual acreage decisions increasingly follow processor-approved input lists for contracted pulse production.
- Agronomists:Certified crop advisors in Ontario prescribe nematicide treatments based on fall soil sampling results and rotational nematode population modeling. Licensing requirements for nematode identification lag behind product availability, creating advisory bottlenecks during spring application windows.
- Wholesale Distributors:Saskatchewan-based ag-retail networks manage inventory positioning across extended supply chains from European manufacturing sites.
- Fertilizer Retailers:Manitoba co-operatives bundle nematicide offerings with custom application services in the Red River Valley.
Traditional purchasing authority rests with Farmers. Emerging specification control is shifting toward Agronomists under integrated pest management mandates.
Formulation:
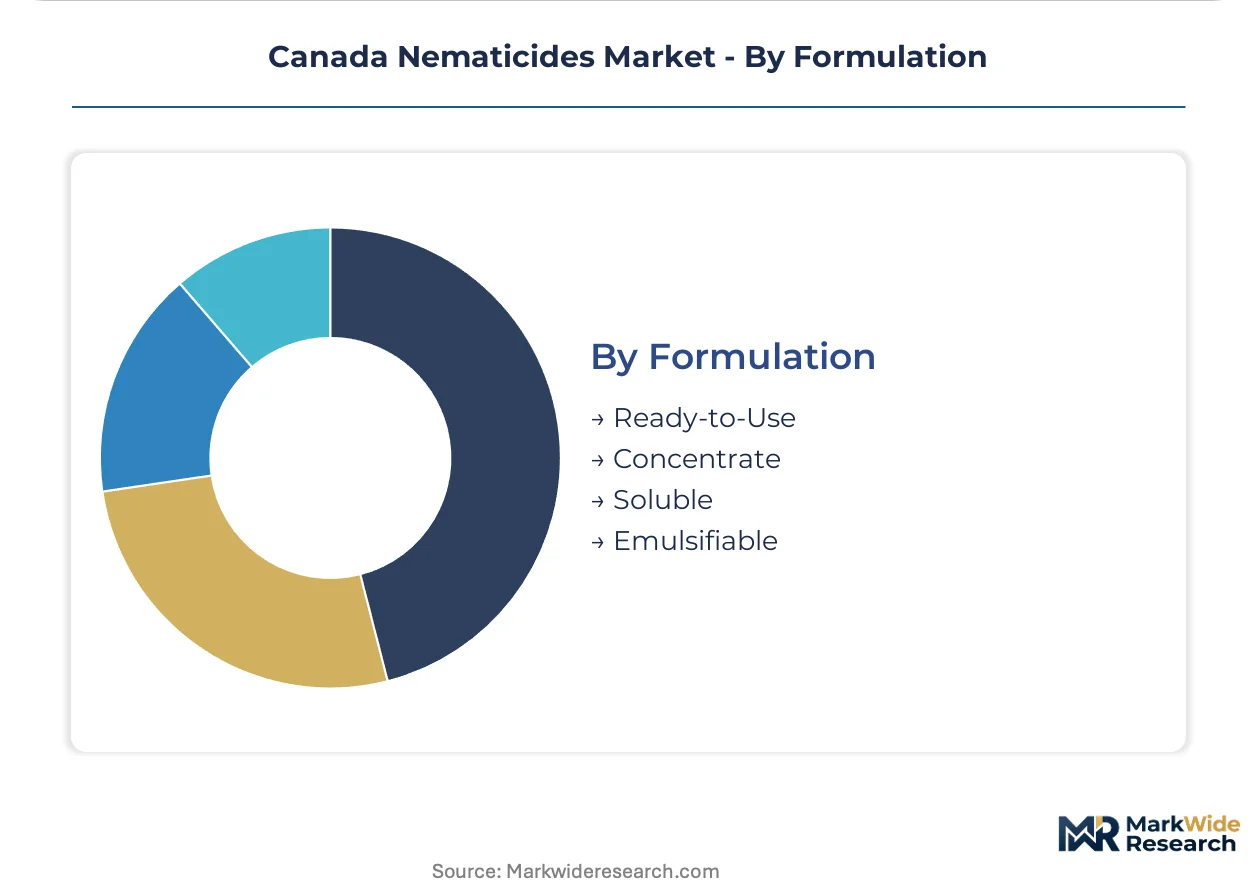
Application equipment compatibility and storage stability dictate formulation selection across Canadian climatic conditions.
- Ready-to-Use:Pre-mixed aqueous solutions eliminate on-farm handling requirements for greenhouse operations with limited chemical storage infrastructure. British Columbia hydroponic facilities prioritize formulations requiring no dilution calculations.
- Concentrate:High-active-load formulations reduce freight costs for Prairie broad-acre applications where tank-mixing with liquid fertilizer occurs at planting. Alberta operations favor concentrates compatible with air-seeder delivery systems.
- Soluble:Powder formulations enable precise dosing in small-scale Ontario vegetable operations with backpack sprayer equipment.
- Emulsifiable:Oil-based carriers improve penetration in heavy clay soils prevalent in Manitoba's Parkland region.
Freight-optimized Concentrate formulations dominate Prairie procurement. Ready-to-Use solutions are gaining fastest in controlled-environment channels with labor constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leamington anchors Canadian nematicide demand through its concentration of hydroponic greenhouse operations serving export vegetable markets. The Windsor-Essex corridor processes over half of national greenhouse tomato and cucumber output. Regional specialization across Canadian provinces creates distinct formulation preferences tied to crop mix and climatic constraints.
Ontario
Potato and vegetable growers in the Holland Marsh and Niagara Peninsula drive biological nematicide adoption for residue-sensitive export contracts. Health Canada's PMRA re-evaluation of organophosphates accelerates grower transitions toward microbial alternatives. Processing facilities in Leamington now mandate approved input lists that exclude legacy chemistries for US-bound shipments.
Quebec
Greenhouse cucumber and tomato operations face provincial mandates for synthetic pesticide reduction under residual materials management policy. Saint-Rémi and L'Assomption clusters pilot Bacillus-based nematicide integration in recirculating hydroponic systems. The province's organic acreage expansion creates concentrated demand for microbial formulations in vegetable seedling production.
Alberta
Cereal and canola rotations in the Edmonton-Calgary corridor encounter root lesion nematode pressure previously untreated in Prairie soils. Early spring application windows remain chemically dependent due to biological efficacy thresholds below ten degrees Celsius. Carbon offset quantification methodologies under Alberta's system create dual revenue streams for biological adoption.
Saskatchewan
Pulse crop expansion into previously uncultivated Parkland region soils exposes lentil and dry bean plantings to cyst nematode infestations. PMRA's minor use program offers expedited registration pathways for crop-specific biological actives lacking dedicated labels. Elevator-procurement programs now bundle nematicide supply with seed and fertilizer contracts.
British Columbia
Lower Mainland greenhouse operations and Vancouver Island turf maintenance generate specialized demand for ready-to-use formulations compatible with limited chemical storage infrastructure. Hydroponic facilities prioritize aqueous suspensions requiring no dilution calculations for fertigation injection. Golf course superintendents address Anguina pacificae infestations in bentgrass greens through precision application protocols.
Canada Nematicides Market Competitive Environment
The competitive structure tilts toward multinational agrochemical conglomerates with established regulatory dossiers and deep R&D pipelines. Three suppliers control over seventy percent of registered synthetic nematicide actives in Canada, creating procurement bottlenecks during seasonal application windows. Strategic archetypes divide between biological innovation specialists and integrated seed-treatment platform operators. Dominant competitive moves include portfolio restructuring around PMRA compliance timelines and bundling nematicide supply with precision agriculture services.
Among Germany-based conglomerates, BASF SE and Bayer CropScience AG occupy positions exemplifying formulation expertise and biological alternative development respectively. Syngenta Group anchors the integrated bundle archetype through seed-treatment-plus-nematicide combination offerings. These three entities represent the consolidated tier whose regulatory infrastructure investments create competitive moats against mid-scale entrants lacking comparable compliance capabilities.
| Leading Market Players |
|---|
| BASF SE |
| Bayer CropScience AG |
| Syngenta Group |
| FMC Corporation |
| Corteva Agriscience |
| UPL Limited |
| American Vanguard Corporation |
| Valent Biosciences Corp |
| Marrone Bio Innovations Inc |
| Others |
Value Chain & Pricing Dynamics
Processor-mandated input specifications for US-bound vegetable shipments are forcing Prairie grain elevators to consolidate procurement decisions, compressing supplier negotiation windows and elevating price premiums for residue-compliant biological formulations. This buyer-side consolidation funnels pricing power toward registrants with established Health Canada PMRA dossiers.
Pricing Analysis
Yield-protection value anchors Canadian nematicide pricing, with growers calculating treatment costs against projected canola or potato revenue loss from nematode damage. Three-tier pricing structure across premium biological, standard chemical, and economy generic tiers reflects certification grade and cold-climate formulation stability. Cost compression in the chemical tier is intensifying as PMRA re-evaluations narrow active ingredient availability. Prairie pulse operations exhibit highest price sensitivity, while Ontario greenhouse producers accept premium positioning for export compliance.
Supply Chain Analysis
Specialized fermentation technician shortages in Germany and the Netherlands constrain biological active substance manufacturing capacity for Canadian-bound shipments. Supply concentrates in these European jurisdictions for microbial formulations, while chemical synthesis draws from US and Chinese production hubs. Formulation stability risks escalate across extended cold-chain routes to Saskatchewan distribution hubs. Distribution runs through elevator-procurement programs in the Prairie provinces and direct-to-grower channels in Ontario-Quebec horticulture clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active ingredient registration bottlenecks at Health Canada PMRA prop pricing stability for established registrants, constraining supply expansion faster than biological demand growth.
For Market Incumbents: To counter biological formulation stability degradation across Prairie cold-chain infrastructure, deepen captive supply of temperature-controlled logistics partnerships and accelerate cold-climate efficacy validation for microbial candidates. Prioritize PMRA minor use program submissions for pulse crop-specific labels ahead of Saskatchewan acreage expansion. For New Entrants and Emerging Players: Launch via certified crop advisor channel partnerships in Ontario, bypassing direct farmer procurement consolidation. Target greenhouse biological conversion in Quebec under provincial pesticide reduction mandates. White-space availability concentrates in lentil and dry bean nematicide registrations lacking dedicated labels. For Investors and Strategic Acquirers: The window for entry favors biological fermentation specialists with validated cold-chain protocols. Long-term viability hinges on PMRA registration infrastructure amortization across multi-crop label portfolios. Watch for Alberta carbon offset methodology finalization as biological adoption inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| PMRA Minor Use Registration | Expedited label expansion for Saskatchewan pulse crops addresses untreated acreage. |
| Cold-Chain Infrastructure Partnership | Temperature-controlled distribution secures biological viability to Prairie hubs. |
| Seed-Treatment Bundle Integration | Single-pass application systems reduce Ontario vegetable grower labor costs. |
| Carbon Credit Quantification Methodology | Alberta offset system creates dual revenue streams for biological adoption. |
| Greenhouse Biological Formulation Development | Quebec hydroponic compatibility opens residue-compliant export channels. |
Study Parameters
Multi-period observation of Health Canada PMRA registration timelines, Prairie elevator procurement consolidation, and Quebec greenhouse input specification changes anchored the trend analysis, supplemented by interviews with certified crop advisors, Saskatchewan ag-retail procurement managers, Ontario vegetable processing facility agronomists, and biological formulation R&D directors. Secondary validation drew from PMRA regulatory decision documents, provincial environmental farm plan amendments, and Agriculture and Agri-Food Canada crop rotation surveys. Bottom-up acreage-by-acreage treatment modeling triangulated against top-down supplier shipment data.
Segment-weighting across chemical versus biological formulation chemistry, Prairie broad-acre versus Ontario-Quebec horticulture application settings, and farm-direct versus processor-mandated procurement authority shaped the analytical framework. CAGRs were derived from treatment intensity projections by crop type across the analysis window. Forecast inputs incorporated PMRA accelerated biological pathway approval velocity and Prairie oilseed rotation expansion rates.
PMRA registration timeline delays, Prairie cold-chain infrastructure investment shortfalls, and Quebec greenhouse policy implementation pace are the dominant revision risks to forecast assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global SDHI Fungicide Market
Crop Protection
India Insecticide Market
Crop Protection
Grain and Cereal Crop Protection Market
Crop Protection
Tebuconazole Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
Global Home and Garden Pesticides Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
North America Crop Protection Chemicals Market
Crop Protection
IPM Pheromones Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
Global Crop Growth Regulators Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Metamifop Market
Crop Protection
Fosthiazate Market
Crop Protection
Global Chlorpyrifos Market