
 Larvicides Market | 2026-2036
Larvicides Market Size, Share, and Industry Trends Forecast 2026-2036
Larvicides Market Outlook
Subscription-based monitoring and re-treatment scheduling is realigning how larvicide value gets captured, shifting revenue from one-time chemical sales to recurring service contracts tied to surveillance data. BASF SE leverages its global formulation network to sustain premium positioning in emulsifiable concentrate portfolios. Bayer AG anchors its competitive stance through biological larvicide R&D pipelines targeting resistance-prone mosquito populations. Syngenta AG competes on manufacturing scale in granular formulations for agricultural irrigation systems.
Larvicides are biologically active agents or chemical compounds designed to interrupt the immature developmental stages of insects, typically applied at concentrations measured in parts per billion to achieve species-specific mortality thresholds in aquatic breeding habitats. Their primary commercial purpose centers on preemptive vector suppression before adult emergence, reducing downstream reliance on adulticide fogging campaigns. Biological formulations command expanding margin pools as regulatory pressure on organophosphate residuals intensifies across agricultural and public health applications. Insect Growth Regulators represent the fastest-expanding product category, with juvenile hormone analogs displacing neurotoxic chemistries in sensitive watershed zones. Liquid formulations dominate volume throughput in mechanized aerial and ground spray operations, though solid briquettes sustain longer residual windows in static water bodies.
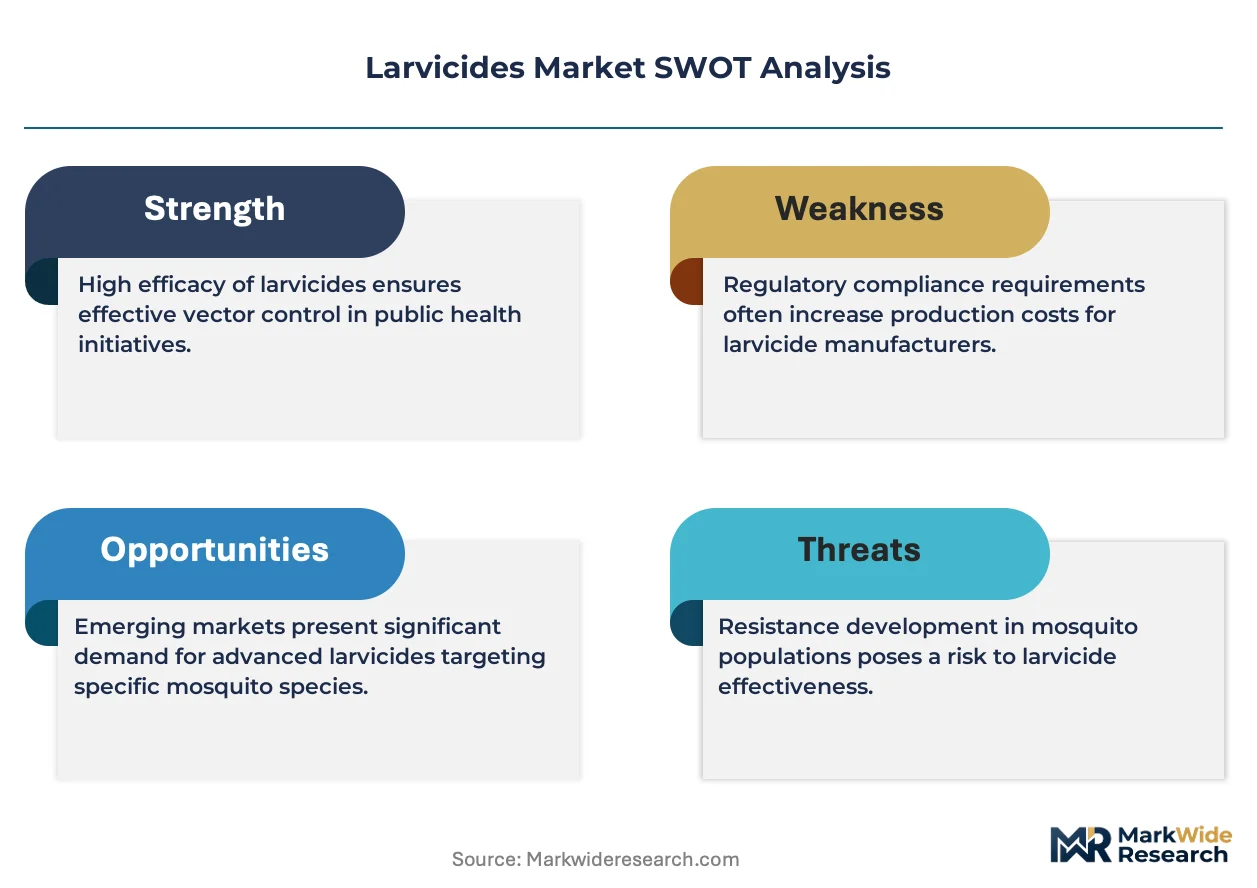
The EPA governs active-ingredient registration and tolerance setting under FIFRA, while the EU REACH framework restricts persistent organic pollutant classifications that affect chemical larvicide import and formulation. Brazil's ANVISA and India's CDSCO impose parallel residue monitoring protocols that shape export-oriented manufacturer compliance investments. WHO prequalification standards for vector-control products create a parallel gatekeeping layer for public procurement eligibility in malaria-endemic jurisdictions. Stakeholders must monitor resistance surveillance networks and regulatory reclassification timelines to align portfolio transitions with shifting tolerances for biological versus synthetic chemistries.
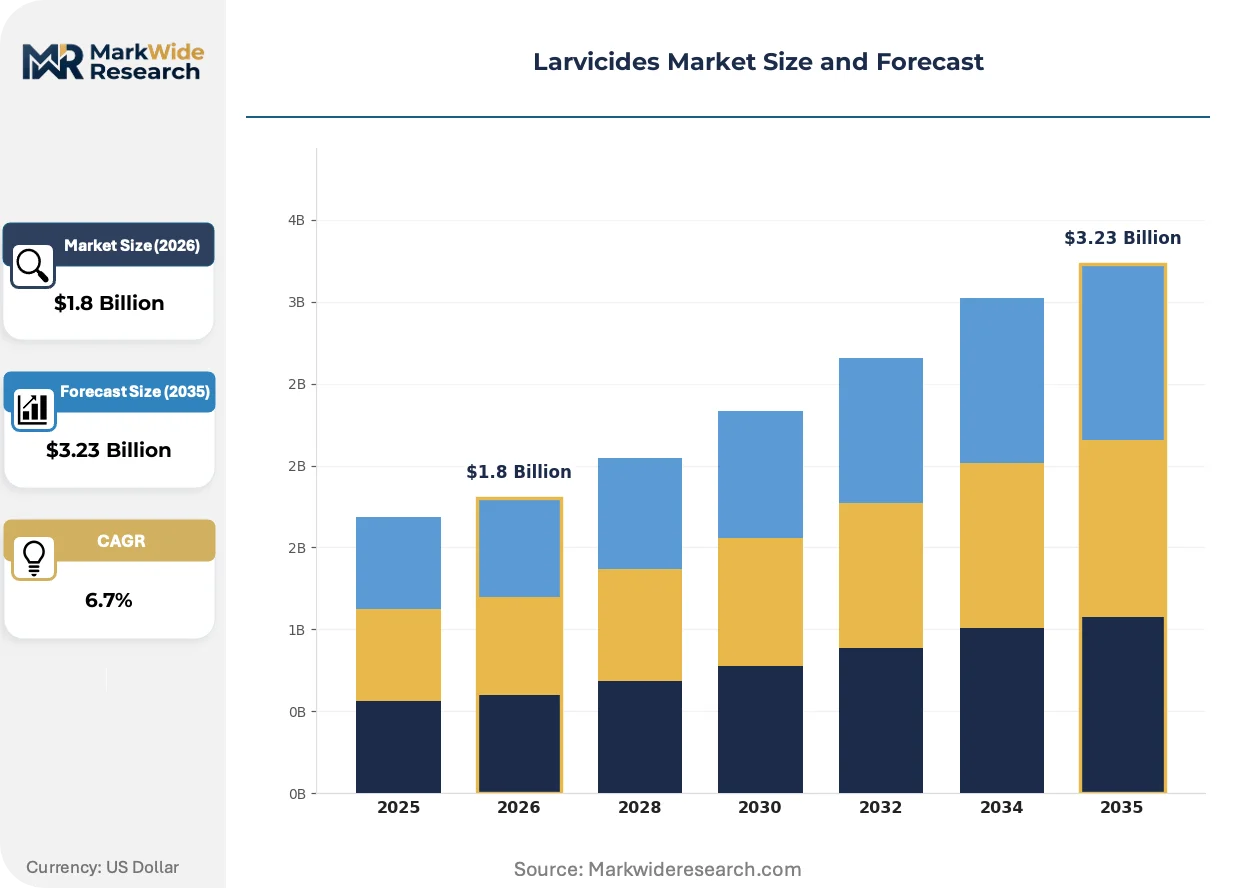
Market Dynamics
Regulatory pressure on neurotoxic chemistries is compressing formulation pipelines while accelerating biological larvicide substitution across vector-control programs and agricultural watersheds.
Growth Catalysts
- WHO Prequalification Standards:Public procurement eligibility in malaria-endemic jurisdictions now hinges on WHO vector-control product certification, creating a compliance-driven demand floor for registered manufacturers.
- Brazil ANVISA Catch-Basin Mandates:Municipal vector-control programs in São Paulo and Rio de Janeiro are scaling larvicide-treated infrastructure deployment under federal public health directives.
- Juvenile Hormone Analogs:Insect Growth Regulators targeting resistance-prone mosquito populations are displacing organophosphates in sensitive aquatic ecosystems.
Market Restraints
- EU REACH Persistent Organic Pollutant Restrictions:Chemical larvicide import and formulation face reclassification risk under tightening ECHA tolerance frameworks, elevating compliance costs for synthetic portfolios.
- Pyrethroid Resistance Surveillance Burden:Vector population monitoring requirements in Southeast Asia rice belts strain public health budgets and delay treatment cycles.
- Biological Formulation Scale Constraints:Bacillus thuringiensis israelensis production capacity concentrates among specialized fermentation facilities, creating supply bottlenecks during peak dengue seasons.
Strategic Opportunities
- India CDSCO Biological Registration Pathway:Accelerated approval timelines for microbial larvicides under India's central drug regulator create first-mover positioning in subcontinental vector-control tenders.
- Subscription-Based Monitoring Contracts:Revenue models are pivoting from chemical volume sales to recurring service agreements tied to surveillance data and re-treatment scheduling.
- Precision Agriculture Integration:Larvicide dosing systems converging with IoT-enabled irrigation infrastructure enable automated release in agricultural water management.
Industry Challenges
- Resistance Surveillance Talent Scarcity:Entomological field teams capable of vector population genotyping remain concentrated in academic and WHO-affiliated institutions, limiting commercial program scale.
- Multi-Jurisdiction Registration Synchronization:Divergent residue monitoring protocols across EPA, EU REACH, and national regulators like ANVISA and CDSCO fragment product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Larvicides Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biological, Chemical, Insect Growth Regulators, Granular Application: Agricultural, Urban Pest Control, Public Health, Aquaculture Formulation: Liquid, Solid, Aerosol, Emulsifiable Concentrate Distribution Channel: Online Retailers, Agricultural Suppliers, Distributors, Direct Sales |
| Companies Covered | BASF SE, Bayer AG, Syngenta AG, Sumitomo Chemical, Certis Biologicals, Valent BioSciences, Central Life Sciences, Gowan Company, UPL Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Larvicides Market Strategic Shifts
Formulation chemistry is pivoting toward species-specific delivery mechanisms while digital infrastructure restructures how vector-control services are procured and monetized.
Microencapsulated Insect Growth Regulators are overtaking emulsifiable concentrate formats in municipal spray programs. Brazilian and Thai health departments are adopting these slow-release formulations for extended residual control in urban catch basins. The technology is overtaking conventional neurotoxic chemistries by compressing application frequency requirements and reducing operator exposure liability.
EPA FIFRA tolerance reclassification timelines are compressing active-ingredient windows for organophosphate larvicides. Manufacturers face accelerated portfolio transitions as the agency tightens aquatic toxicity thresholds for agricultural runoff zones. Biological larvicide registrations are absorbing displaced synthetic volumes, particularly in Florida and California watershed protection districts.
Integrated Vector Management procurement protocols now bundle larvicide supply with entomological surveillance services. Southeast Asian ministries of health are unbundling chemical purchases from fogging contracts, favoring vendors with captive monitoring capabilities. Vietnam and Indonesia exhibit the fastest channel restructuring, with provincial health offices consolidating vendor relationships under multi-year service agreements.
Larvicides Market Segmentation
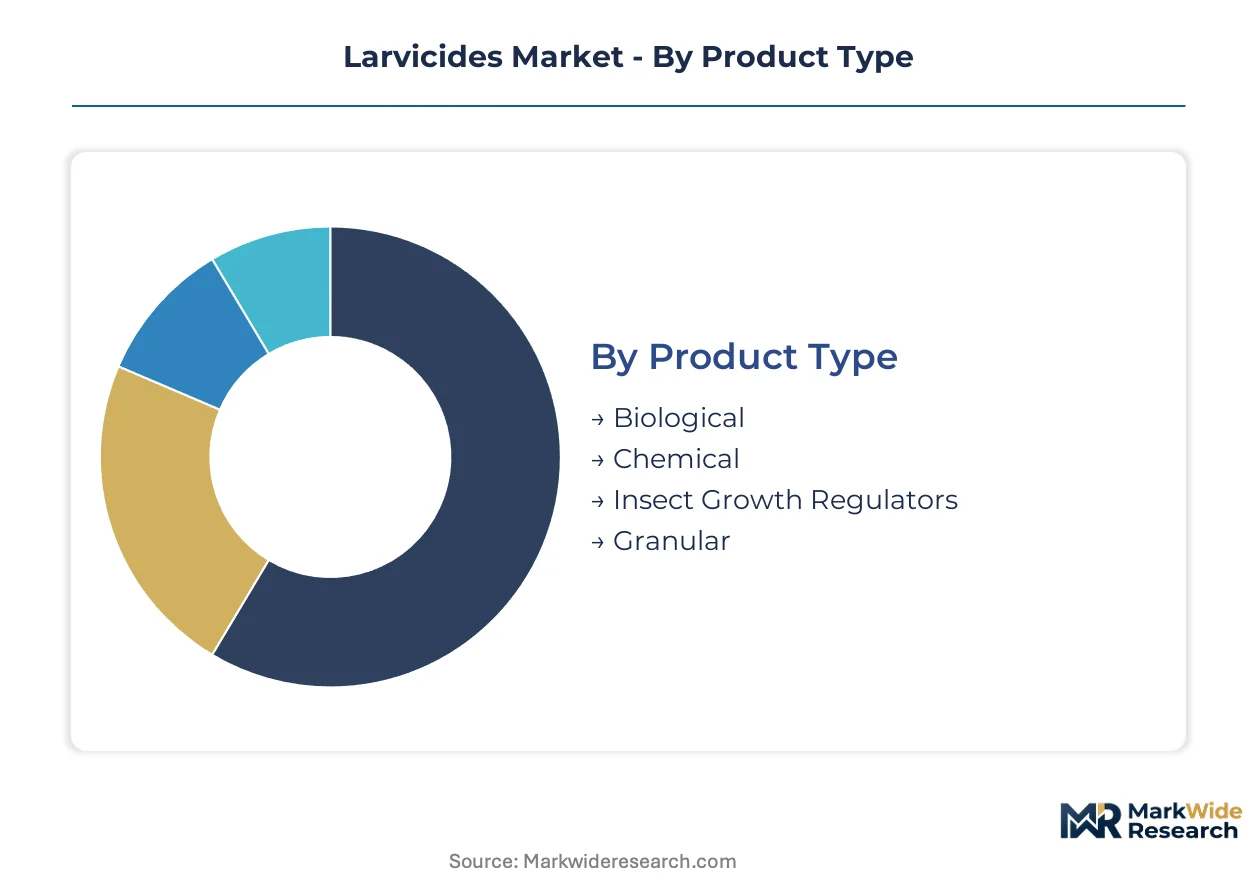
Larvicide market segmentation reflects divergent technical requirements across vector-control programs and agricultural watersheds. Product chemistry, application environment, and formulation stability determine procurement specifications and regulatory compliance burdens for end-users.
Product Type:
Technology specifications differentiate active-ingredient platforms by mode of action, residual persistence, and ecological safety profile.
- Biological:Microbial agents derived from Bacillus thuringiensis israelensis fermentation disrupt larval midgut function through protein crystal ingestion. Demand concentrates in Florida and California watershed protection districts where EPA FIFRA aquatic toxicity thresholds restrict synthetic alternatives.
- Chemical:Organophosphate and pyrethroid formulations deliver rapid mortality through neurotoxic action at parts-per-billion concentrations. Brazil's ANVISA catch-basin mandates sustain volume in municipal vector-control programs despite tightening EU REACH persistent organic pollutant restrictions.
- Insect Growth Regulators:Juvenile hormone analogs arrest metamorphosis without acute toxicity, gaining share in resistance-prone Southeast Asian rice belts.
- Granular:Slow-release matrices extend residual windows in static water bodies, preferred for remote agricultural irrigation systems.
Chemical formulations lead on scale; Insect Growth Regulators lead on momentum.
Application:
End-use environments impose distinct performance specifications around dosing precision, non-target organism safety, and re-treatment frequency.
- Agricultural:Rice paddy and irrigation canal applications in Vietnam and Indonesia require species-specific toxicity profiles against Anopheles vectors without fish mortality. WHO prequalification standards govern tender eligibility for malaria-endemic agricultural zones.
- Urban Pest Control:São Paulo and Rio de Janeiro municipal programs deploy larvicide-treated catch basins under federal public health directives, prioritizing operator safety and extended residual control.
- Public Health:National malaria and dengue control programs in Thailand and India bundle larvicide supply with entomological surveillance services under multi-year service agreements.
- Aquaculture:Shrimp and fish farming operations in Southeast Asia demand biological formulations with zero withdrawal period constraints.
Public Health commands the largest procurement budgets; Aquaculture shows the steepest expansion trajectory.
Formulation:
Physical delivery mechanisms determine application equipment compatibility, residual persistence, and operator exposure risk.
- Liquid:Mechanized aerial and ground spray operations dominate volume throughput in Brazilian and Thai municipal programs. Microencapsulated variants compress application frequency requirements in urban catch basins.
- Solid:Briquettes and tablets sustain month-long residual windows in static water bodies, reducing labor costs for remote agricultural sites.
- Aerosol:Ultra-low volume thermal fogging of larvicide-oil mixtures targets cryptic breeding habitats in dense urban informal settlements.
- Emulsifiable Concentrate:Oil-in-water formulations enable rapid dilution for backpack sprayer deployment in public health emergency response.
Liquid formulations dominate current volume; Solid formats gain share in cost-sensitive remote applications.
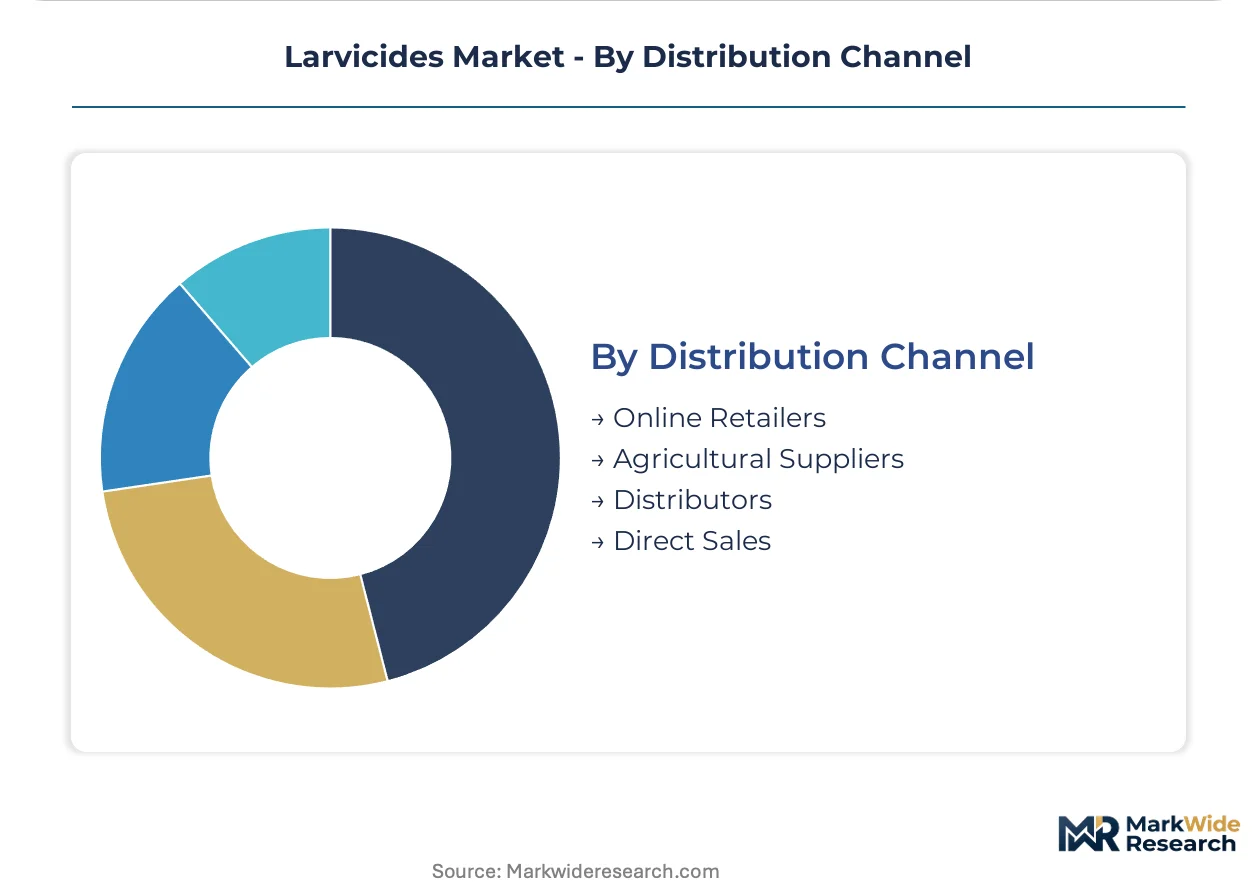
Distribution Channel:
Channel structure reflects customer scale, technical support requirements, and procurement centralization trends in vector-control programs.
- Online Retailers:Small-scale agricultural operators and residential consumers access biological larvicides through e-commerce platforms, bypassing traditional supply chain markups.
- Agricultural Suppliers:Cooperative and independent retail networks serve rice-cultivation belts with formulation advice and application equipment bundling.
- Distributors:Regional chemical wholesalers manage inventory and credit terms for municipal procurement offices in Brazil and India.
- Direct Sales:Manufacturers with captive surveillance capabilities contract directly with Vietnam and Indonesia provincial health offices for integrated vector management service agreements.
Direct Sales capture premium-margin service contracts; Online Retailers expand fastest in fragmented smallholder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's municipal catch-basin mandates and India's CDSCO registration pathways are outpacing European regulatory constraints in shaping near-term deployment volumes. Southeast Asian rice belts sustain concentrated procurement budgets despite surveillance capacity gaps. Divergent tolerance frameworks across EPA FIFRA, EU REACH, and national regulators fragment manufacturer compliance investments.
United States
Florida and California watershed protection districts drive biological larvicide substitution as EPA FIFRA tightens aquatic toxicity thresholds for agricultural runoff. State-level vector-control programs in Texas and Louisiana prioritize operator safety in mechanized aerial spray operations. Microencapsulated Insect Growth Regulators displace emulsifiable concentrates in municipal procurement.
Brazil
São Paulo and Rio de Janeiro municipal programs scale larvicide-treated infrastructure under ANVISA federal public health directives. Urban dengue suppression commands sustained budget allocation through subnational health secretariats. Granular formulations dominate deployment in informal settlement catch-basin networks.
India
Maharashtra and Gujarat agricultural belts demand species-specific toxicity profiles for Anopheles vector management in rice paddy systems. CDSCO accelerated approval timelines for microbial larvicides create first-mover positioning in subcontinental tenders. National malaria control programs bundle supply with entomological surveillance services.
Thailand
Central plains rice cultivation sustains concentrated public health procurement for juvenile hormone analog applications. Provincial health offices consolidate vendor relationships under multi-year Integrated Vector Management service agreements. Resistance-prone mosquito populations drive substitution away from organophosphate chemistries.
Germany
BASF SE leverages formulation networks from Ludwigshafen to sustain premium positioning in emulsifiable concentrate portfolios. EU REACH persistent organic pollutant reclassifications elevate compliance costs for synthetic active-ingredient imports. Biological larvicide registrations absorb displaced chemical volumes across member-state agricultural watersheds.
Larvicides Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational agrochemical conglomerates commanding premium-tier public health contracts while regional fermentation specialists capture biological formulation volumes. The vendor base concentrates around three strategic archetypes: integrated agrochemical majors with captive surveillance capabilities, microbial fermentation specialists with Bti production scale, and regional distributors with municipal procurement relationships. Competitive positioning hinges on multi-jurisdiction registration synchronization and backward integration into active-ingredient synthesis.
Within the integrated agrochemical tier, BASF SE, Bayer AG, and Syngenta AG exemplify divergent strategic postures. BASF SE anchors premium formulation positioning through its global emulsifiable concentrate network. Bayer AG occupies a position emphasizing biological larvicide research pipelines. Syngenta AG represents manufacturing scale concentration in granular formats for agricultural irrigation deployment.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta AG |
| Sumitomo Chemical |
| Certis Biologicals |
| Valent BioSciences |
| Central Life Sciences |
| Gowan Company |
| UPL Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between WHO-prequalified biological formulations and commodity chemical larvicides manifests in both pricing premiums and supply chain complexity. Premium-tier manufacturers command margin multiples through captive fermentation capacity and multi-jurisdiction registration portfolios, while standard-tier suppliers compete on volume throughput through regional distributor networks.
Pricing Analysis
Capacity additions in India and Brazil are reshaping price floors for microbial larvicide formulations as CDSCO and ANVISA accelerate domestic biological registrations. Three-tier pricing structure across premium, standard, and economy levels reflects WHO prequalification status, formulation stability specifications, and bundled surveillance service inclusion. Cost compression in commodity chemical tiers intensifies because EU REACH persistent organic pollutant reclassifications strand legacy organophosphate inventories. Public health procurement offices exhibit lowest price sensitivity due to multi-year service contract structures, while smallholder agricultural operators drive volume through online retail channels.
Supply Chain Analysis
Regional distribution centers in Ludwigshafen, Mumbai, and São Paulo anchor hub-and-spoke patterns for formulated product delivery to municipal vector-control programs. Active-ingredient supply concentrates in Germany, India, and China, with Bacillus thuringiensis israelensis fermentation drawing from specialized biotechnology facilities in Denmark and the United States. Supply chain risk centers on single-source vulnerability for juvenile hormone analog precursors. Distribution runs through direct sales channels for integrated service contracts and agricultural supplier networks for rice-belt smallholders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The larvicides market compounds steadily as regulatory pressure on neurotoxic chemistries creates durable substitution demand for biological alternatives. Vector-control program budget stickiness in dengue-endemic jurisdictions sustains recurring revenue visibility.
For Market Incumbents: Deepen backward integration into Bti fermentation capacity to defend margin position against emerging microbial specialists in India. Lock in multi-year surveillance service contracts with Southeast Asian provincial health offices before CDSCO registration pathways mature for domestic competitors. Prioritize juvenile hormone analog formulation patents as organophosphate tolerances compress under EPA FIFRA timelines.
For New Entrants and Emerging Players: Municipal procurement offices in secondary Brazilian cities represent the most penetrable channel partner type for biological larvicide specialists lacking WHO prequalification. Target Vietnam and Indonesia aquaculture segments where zero-withdrawal-period constraints exclude chemical competitors. Lead with IoT-enabled dosing system partnerships to differentiate from incumbent formulation-only suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction registration portfolios concentrate among legacy agrochemical majors facing biological substitution. The market supports long-term compounder framing through regulatory tailwinds and public health budget resilience. Acquisition target archetype: regional Bti fermentation specialists with captive strain libraries and ANVISA or CDSCO approvals. Watch EPA FIFRA tolerance reclassification announcements as inflection indicators for portfolio transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive Bti production insulates margin from biological supply bottlenecks during peak dengue seasons. |
| Multi-Jurisdiction Registration Synchronization | Parallel EPA, EU REACH, and CDSCO filings compress product launch timelines in vector-control tenders. |
| Subscription-Based Service Contract Conversion | Recurring surveillance and re-treatment revenue displaces transactional chemical volume dependence. |
| IoT-Enabled Precision Dosing Partnerships | Integration with automated irrigation infrastructure opens agricultural water management applications. |
| Juvenile Hormone Analog Patent Portfolio | Insect Growth Regulator formulation patents capture share as resistance-prone populations displace organophosphates. |
Study Parameters
Direct dialogue with vector-control program directors, municipal procurement officers, biological fermentation facility managers, and entomological surveillance contractors grounded qualitative findings in operational reality. Secondary validation drew from EPA FIFRA registration databases, WHO prequalification product lists, ANVISA public health directives, and CDSCO approval timelines. Customs trade data for Bti active-ingredient shipments and municipal tender documentation from São Paulo, Rio de Janeiro, and Bangkok provided volume anchors. Bottom-up segment sizing triangulated against top-down public health expenditure flows.
Segmentation outputs across product chemistry, application environment, formulation type, and distribution channel fed analytical framework construction over the projection horizon. CAGRs derived from regression against historical procurement volumes, regulatory phase-out schedules, and resistance surveillance network expansion rates. Modeled inputs included EPA tolerance reclassification timelines, CDSCO biological registration acceleration curves, and Southeast Asian rice-cultivation belt budget allocation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to resistance mutation patterns and unscheduled regulatory reclassifications. Outputs reflect documented assumptions around WHO prequalification eligibility expansion and biological fermentation capacity scaling. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Organic Pesticides Market
Crop Protection
Poland Crop Protection Chemicals Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Fumigation Market
Crop Protection
Fogger Market
Crop Protection
Pest Control Products Market
Crop Protection
Grain Fumigants Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Grain and Cereal Crop Protection Market
Crop Protection
Dicamba Market
Crop Protection
Europe Insecticides Market
Crop Protection
Fosthiazate Market
Crop Protection
Global Algaecides Market
Crop Protection
Agricultural Pheromones Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Propiconazole Market