
 Satellite Data Analytics Services Market | 2026-2036
Satellite Data Analytics Services Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Data Analytics Services Market Outlook
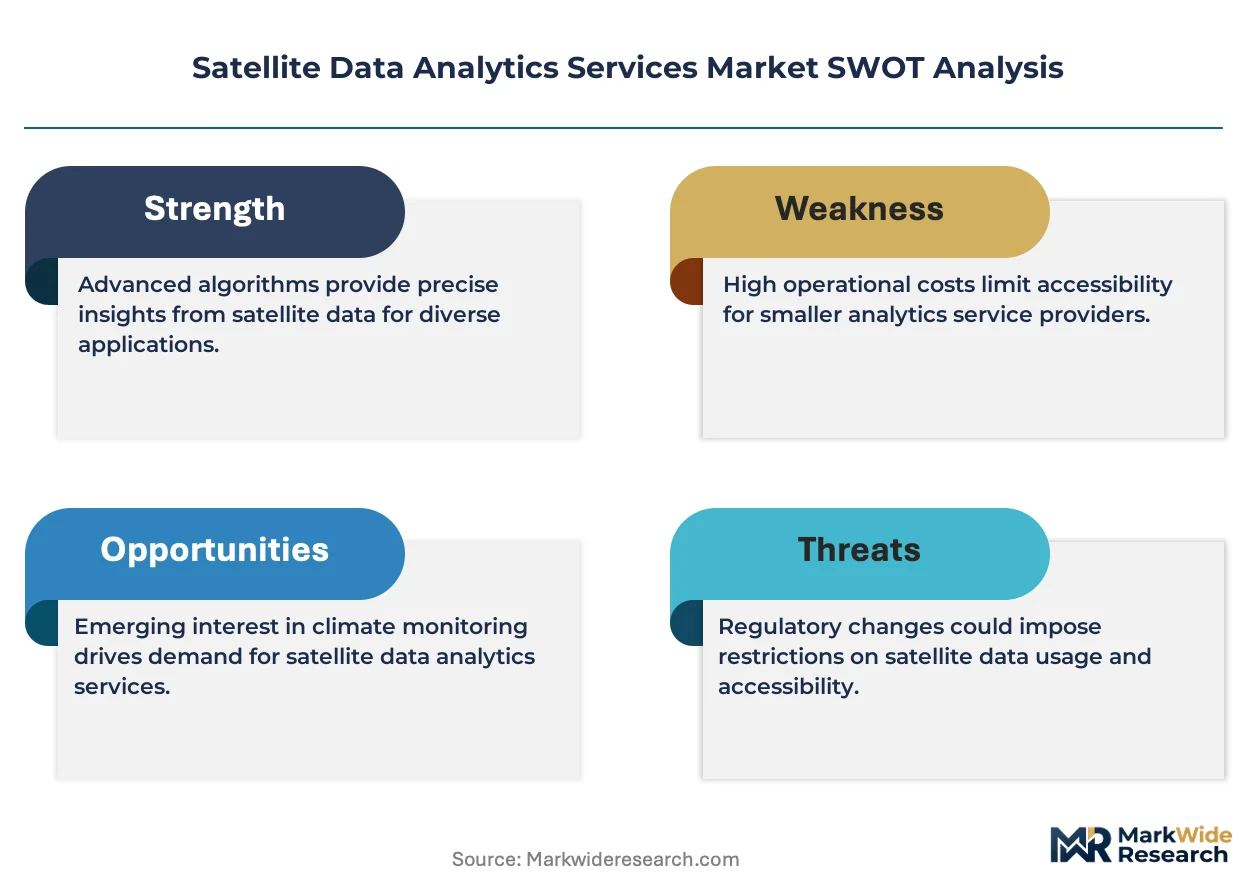
Raw imagery distribution is rewriting margin economics across the satellite value chain. Maxar Technologies leverages its high-resolution constellation heritage to anchor premium analytics contracts with defense and intelligence agencies. Planet Labs sustains competitive differentiation through daily global coverage and open data partnerships that extend its reach into climate monitoring applications. ICEYE specializes in synthetic aperture radar analytics, operating a unique all-weather, day-night imaging capability that controls niche segments in maritime surveillance and disaster response.
Satellite data analytics services transform raw orbital sensor outputs into decision-ready intelligence through automated feature extraction, change detection algorithms, and multi-spectral classification at sub-meter resolution. These services enable precision agriculture yield forecasting, infrastructure integrity monitoring, and illegal activity detection across vast geographic areas. Image analysis and predictive modeling command expanding margin pools as end users shift from purchasing raw pixels to subscribing to actionable intelligence layers. Machine learning and remote sensing technologies dominate capability investment, while cloud computing architectures reduce delivery latency and enable scalable processing of petabyte-class archives.
The National Oceanic and Atmospheric Administration and the Federal Aviation Administration shape US market access through licensing frameworks for commercial remote sensing and orbital debris mitigation standards. The EU AI Act and GDPR impose algorithmic transparency and data residency requirements on European-deployed analytics platforms, redirecting vendor infrastructure investment toward sovereign cloud environments. Stakeholders must monitor evolving export control classifications for geospatial AI models and assess whether dual-use technology restrictions fragment cross-border data sharing architectures.
Market Dynamics
Defense procurement of AI-enhanced satellite imagery is compressing delivery timelines and forcing analytics providers to reconfigure cloud infrastructure for classified workloads. This demand surge is restructuring competitive priorities around sovereign data residency and real-time processing capacity.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for geospatial AI are redirecting vendor investment toward explainable machine learning architectures, creating procurement preference for certified analytics platforms.
- Precision agriculture yield forecasting:Automated multi-spectral classification at sub-meter resolution enables crop stress detection and irrigation optimization, pulling satellite analytics into farm management software stacks.
- Maritime surveillance demand:Synthetic aperture radar analytics for illegal fishing detection and vessel tracking is expanding coast guard and naval intelligence budgets across littoral states.
Market Restraints
- Launch capacity bottlenecks:Limited heavy-lift vehicle availability constrains constellation refresh cycles, extending replacement timelines for aging optical and radar assets.
- GDPR data residency requirements:Cross-border transfer restrictions on processed imagery fragment cloud infrastructure deployment, forcing redundant regional data center investment.
- High-resolution optical substitution:Stratospheric pseudo-satellite platforms and long-endurance drones capture comparable imagery at lower orbital cost for persistent regional monitoring.
Strategic Opportunities
- Climate monitoring carbon credit verification:Forest carbon stock measurement and deforestation early warning systems open subscription revenue from environmental compliance markets.
- Disaster response rapid activation:Automated flood extent mapping and infrastructure damage assessment create emergency procurement channels outside standard defense and agriculture verticals.
- India's National Geospatial Policy:Liberalized remote sensing data access rules enable foreign analytics providers to establish domestic processing nodes and direct government contracts.
Industry Challenges
- Geospatial AI talent scarcity:Shortage of remote sensing scientists capable of training production-grade feature extraction models constrains platform development velocity.
- Dual-use export control complexity:Evolving Commerce Department classifications for automated target recognition algorithms create licensing uncertainty for international service delivery.
- Legacy ground station integration:Downlink compatibility with existing antenna networks requires sustained capital allocation to aging S-band and X-band receiver infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Data Analytics Services Market |
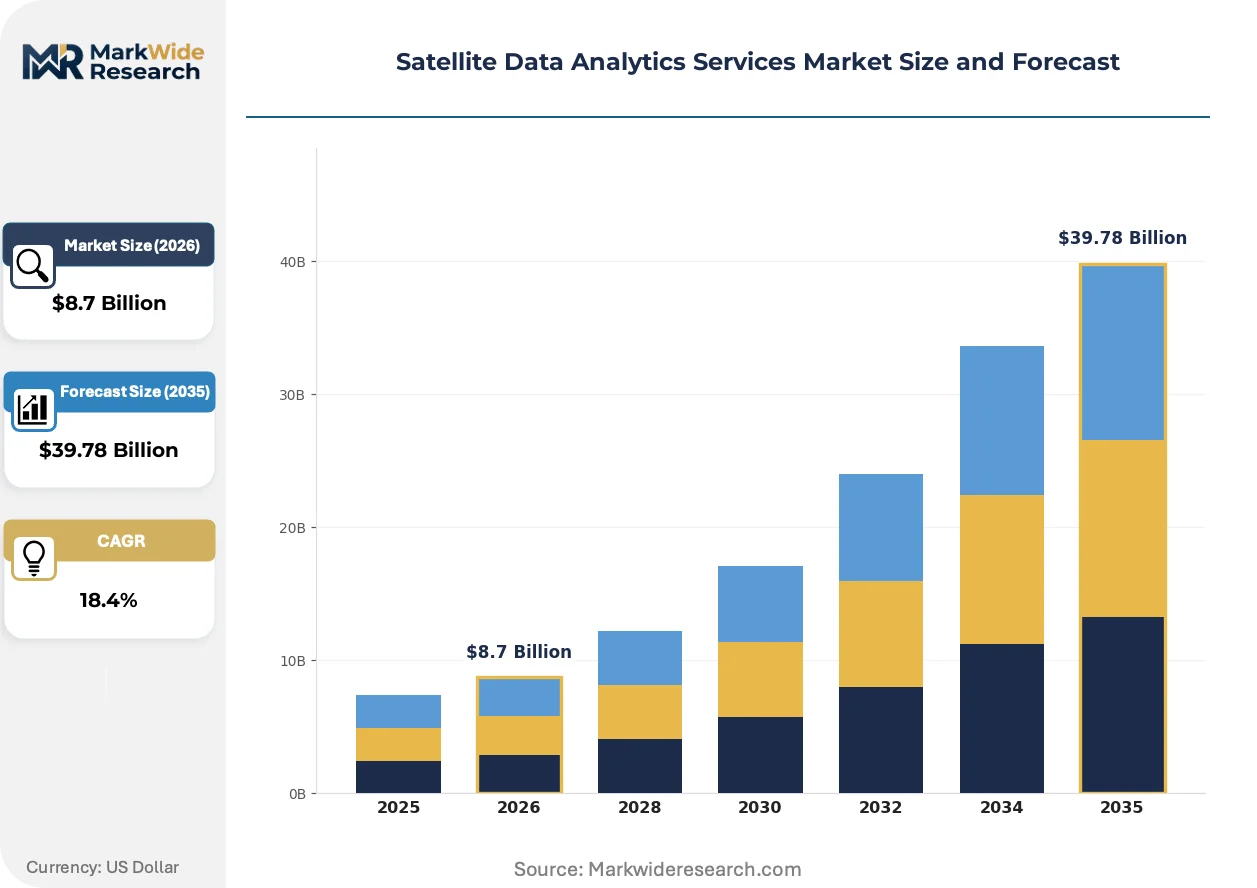
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Processing, Image Analysis, Predictive Modeling, Analytics as a Service End User: Aerospace, Agriculture, Defense, Energy Technology: Machine Learning, Remote Sensing, GIS, Cloud Computing Application: Your Environment Monitoring, Disaster Management, Urban Planning, Resource Exploration |
| Companies Covered | Maxar Technologies, Planet Labs, Airbus, L3Harris Technologies, ICEYE, BlackSky, Capella Space, EOS Data Analytics, Ursa Space Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Data Analytics Services Market Strategic Shifts
Orbital sensor proliferation and edge computing deployment are collapsing the latency between image capture and actionable intelligence delivery. These shifts are redefining competitive advantage around processing speed rather than raw spatial resolution.
Edge computing architectures are virtualizing analytics workflows by deploying inference engines directly on satellite buses and relay spacecraft. Defense and emergency response agencies are piloting these capabilities for immediate threat alerts without ground station handoff. This compression of the analytics pipeline is virtualizing traditional ground segment economics and reducing dependency on centralized cloud processing for time-critical applications.
The EU AI Act's algorithmic transparency requirements are mandating documentation standards for training data provenance and model decision boundaries in geospatial AI systems. Vendors serving European defense and civil government markets must now maintain audit trails for automated feature extraction workflows. Commercial analytics platforms are responding by segregating EU-deployed infrastructure into sovereign cloud environments with localized model training and inference operations.
Subscription-based intelligence layers are displacing per-image licensing across agriculture and infrastructure monitoring verticals. Buyers now expect continuous change detection feeds rather than transactional archive access, compressing vendor revenue recognition cycles. This behavioral shift is most pronounced in United States federal contracting, where multi-year enterprise licenses for automated monitoring services are replacing task-order-based imagery procurement.
Satellite Data Analytics Services Market Segmentation
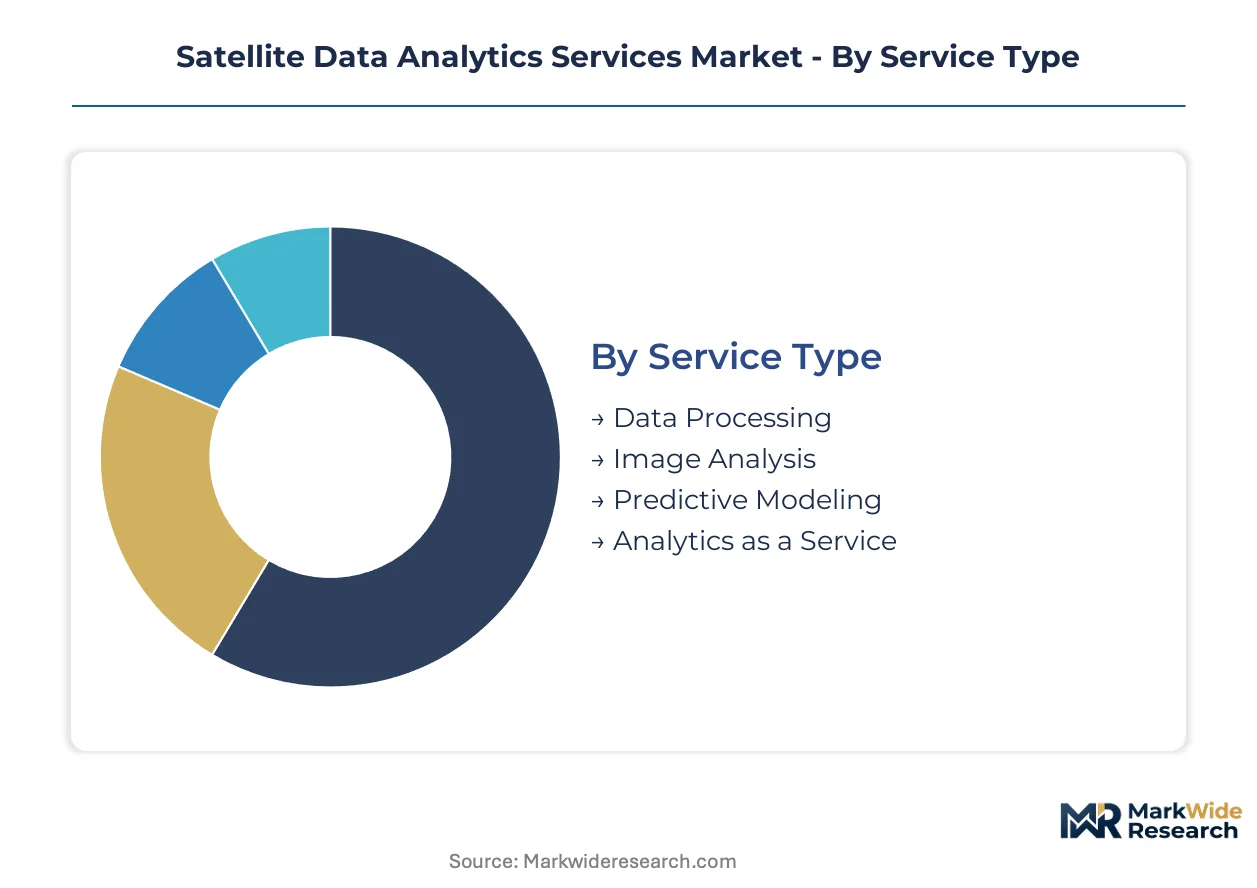
Service differentiation in satellite data analytics separates providers by processing latency, model sophistication, and integration depth with customer decision systems. Segmentation reveals where margin pools concentrate and which capability investments command procurement preference.
Service Type:
Turnaround velocity varies dramatically across service tiers, with automated platforms compressing delivery from days to minutes while boutique consulting engagements extend over weeks.
- Data Processing:Raw sensor calibration, orthorectification, and atmospheric correction pipelines transform orbital captures into analysis-ready datasets. Defense agencies and weather services drive procurement of high-throughput processing chains that handle petabyte-class archives with sub-hour latency requirements.
- Image Analysis:Automated feature extraction, change detection algorithms, and multi-spectral classification deliver object identification and boundary mapping. Agriculture cooperatives and infrastructure operators subscribe to continuous monitoring feeds rather than transactional imagery purchases.
- Predictive Modeling:Forecasting services project crop yields, coastal erosion patterns, and urban heat island expansion through time-series satellite data fusion.
- Analytics as a Service:Cloud-native platforms expose API-accessible geospatial intelligence layers without requiring customer-side infrastructure investment.
Data Processing anchors the volume base while Image Analysis gains share at the steepest rate.
End User:
Customer procurement sophistication spans from standardized SaaS subscriptions to classified contract vehicles with customized security architectures.
- Defense:National security agencies procure AI-enhanced imagery for border surveillance, automated target recognition, and threat detection with real-time processing mandates. The EU AI Act and export control classifications shape vendor selection for European and cross-border deployments.
- Agriculture:Precision farming operations deploy multi-spectral analytics for irrigation optimization, crop stress detection, and yield forecasting. Farm management software stacks integrate satellite intelligence through embedded API partnerships.
- Energy:Pipeline operators and renewable developers monitor infrastructure integrity and site selection through terrain analysis and vegetation encroachment detection.
- Aerospace:Satellite operators and launch providers leverage analytics for orbital debris tracking, constellation optimization, and space situational awareness.
Defense commands the premium pricing tier while Agriculture delivers the broadest addressable base.
Technology:
Capability investment concentrates where processing speed and model accuracy determine competitive survival.
- Machine Learning:Deep learning architectures train on labeled satellite imagery to automate feature extraction with minimal human analyst intervention. Explainable AI requirements under the EU AI Act redirect vendor development toward interpretable model architectures.
- Cloud Computing:Distributed processing infrastructure enables scalable ingestion of constellation data streams with elastic compute allocation during surge events. Sovereign cloud deployments satisfy GDPR data residency mandates for European government contracts.
- Remote Sensing:Physics-based radiometric correction and sensor fusion techniques underpin all downstream analytics quality.
- GIS:Geospatial information systems provide the cartographic and analytical framework for overlaying satellite-derived layers with cadastral and infrastructure databases.
Machine Learning absorbs the largest R&D allocation while Cloud Computing expands most quickly as sovereign deployment requirements proliferate.
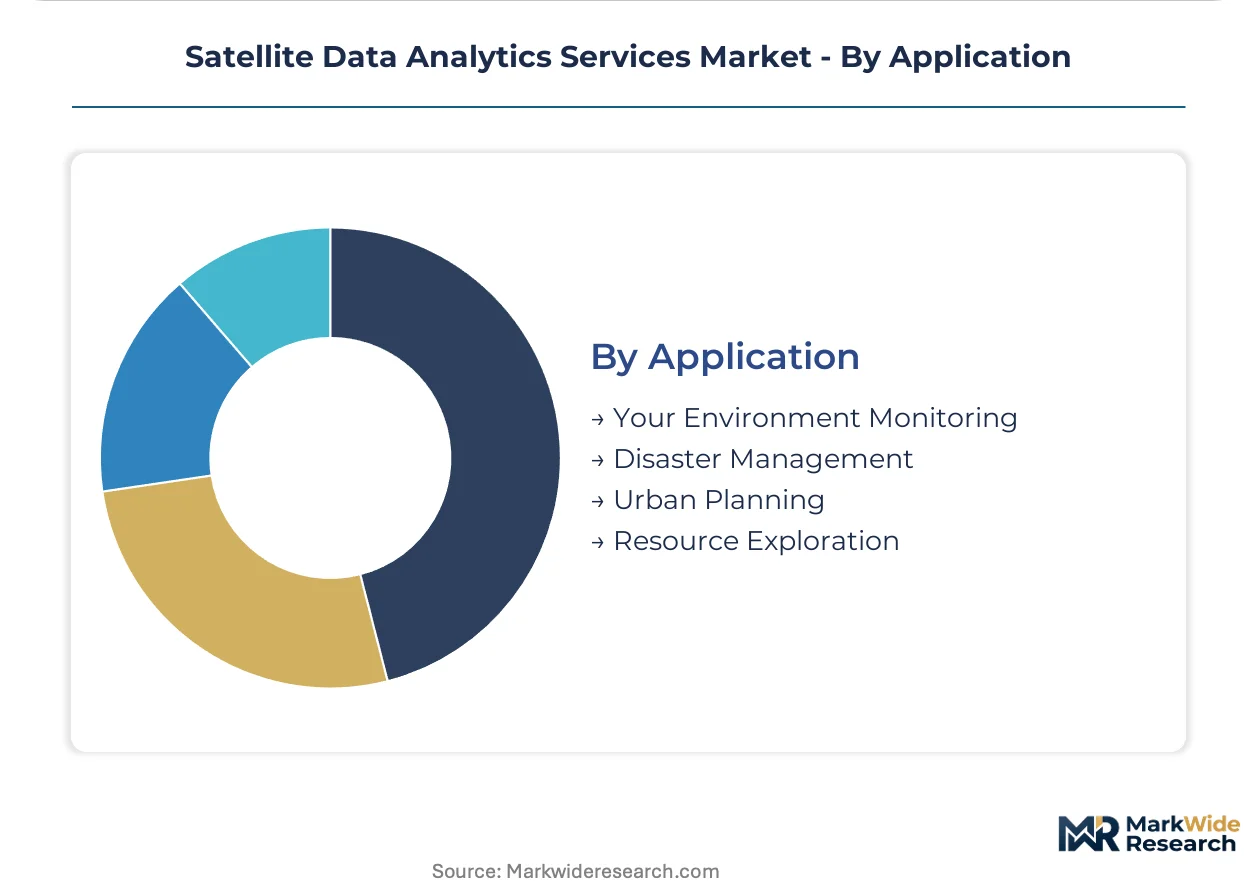
Application:
Use case maturity ranges from operationalized commercial services to emerging procurement categories still defining technical specifications.
- Disaster Management:Automated flood extent mapping and infrastructure damage assessment activate emergency procurement channels outside standard contracting timelines. Coast guard and naval intelligence budgets expand for synthetic aperture radar analytics in maritime surveillance.
- Environment Monitoring:Forest carbon stock measurement and deforestation early warning systems generate subscription revenue from environmental compliance markets. Carbon credit verification protocols require auditable satellite-derived biomass estimates.
- Urban Planning:Settlement expansion tracking and informal settlement detection support municipal zoning enforcement and infrastructure investment prioritization.
- Resource Exploration:Geological feature mapping and mineral prospecting guide extraction industry site selection with spectral anomaly detection.
Environment Monitoring anchors recurring revenue streams while Disaster Management exhibits the steepest expansion trajectory as climate-related event frequency rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement patterns diverge sharply across geographies, with the United States prioritizing real-time AI-enhanced surveillance while European states emphasize GDPR-compliant sovereign cloud architectures for geospatial intelligence.
United States
The FAA and NOAA license commercial remote sensing operations while federal space budgets sustain analytics platform deployment. The National Geospatial-Intelligence Agency contracts drive demand for automated target recognition and border surveillance capabilities. Greater Denver hosts a dense concentration of defense analytics contractors serving classified workloads with specialized security architectures.
Germany
Industrial precision agriculture and automotive supply chain monitoring absorb substantial analytics capacity for yield forecasting and infrastructure integrity assessment. The EU AI Act mandates algorithmic transparency documentation for geospatial AI systems deployed across federal and state agencies. Munich anchors a cluster of remote sensing specialists developing explainable machine learning architectures for European defense applications.
United Kingdom
Maritime surveillance and coast guard intelligence budgets expand for synthetic aperture radar analytics in North Atlantic vessel tracking. The UK Space Agency coordinates orbital debris mitigation standards that shape commercial launch and analytics service licensing. Harwell Science and Innovation Campus concentrates satellite data processing facilities serving both civil government and defense intelligence requirements.
India
National Geospatial Policy liberalization enables foreign analytics providers to establish domestic processing nodes and direct government contracts for disaster response and urban planning. BIS standards govern remote sensing data quality for infrastructure monitoring and resource exploration applications. Bengaluru hosts ISRO-affiliated analytics startups developing automated flood extent mapping and agricultural yield forecasting services.
Japan
METI coordinates disaster response rapid activation protocols that compress procurement timelines for automated infrastructure damage assessment. JIS standards and export control frameworks regulate dual-use geospatial AI model transfers to international partners. Tokyo-Osaka corridor concentrates climate monitoring analytics providers serving carbon credit verification markets across Asia-Pacific environmental compliance regimes.
Satellite Data Analytics Services Market Competitive Environment
Capability concentration sits with heritage constellation operators possessing high-resolution imaging archives; scale advantage sits with cloud-native platforms processing daily global coverage. The market structures around three tiers: legacy defense contractors with classified infrastructure certifications, commercial constellation operators with differentiated sensor modalities, and software-centric analytics pure-plays with API-first delivery models. Dominant competitive moves include sovereign cloud infrastructure deployment for GDPR compliance and strategic partnerships embedding satellite intelligence into farm management and logistics software stacks.
Within the heritage imaging tier, Maxar Technologies and Planet Labs occupy positions reflecting divergent capability investments—one anchored in premium resolution archives for defense intelligence, the other in daily global coverage extending into climate monitoring applications. ICEYE exemplifies the specialized sensor modality approach through synthetic aperture radar analytics. These three represent distinct competitive archetypes: archive-depth defense positioning, coverage-scale commercial subscription, and all-weather niche segmentation.
| Leading Market Players |
|---|
| Maxar Technologies |
| Planet Labs |
| Airbus |
| L3Harris Technologies |
| ICEYE |
| BlackSky |
| Capella Space |
| EOS Data Analytics |
| Ursa Space Systems |
| Others |
Value Chain & Pricing Dynamics
Heavy-lift launch vehicle manufacturing concentrates in United States, Russia, and China, anchoring upstream cost structures that propagate through constellation deployment economics and reshape margin distribution across analytics service tiers.
Pricing Analysis
Long-term enterprise licensing contracts dominate defense and agriculture procurement, compressing spot-market transactional volume to legacy archive access tiers. Price differentiation hinges on processing latency guarantees and sovereign cloud certification status under GDPR and EU AI Act frameworks. Cost compression in standardized data processing tiers is intensifying as cloud-native platforms automate ingestion pipelines. Agriculture cooperatives exhibit highest price sensitivity, while classified defense workloads accept premium multiples for air-gapped infrastructure and sub-minute delivery mandates.
Supply Chain Analysis
Extended payment terms from defense prime contractors cascade through ground station equipment vendors, compressing working capital cycles for antenna and receiver manufacturers. Satellite bus and sensor assembly draws from specialized aerospace clusters in United States, Germany, and Japan, with focal plane arrays and precision optics sourcing from constrained supplier bases. Single-source vulnerability concentrates in synthetic aperture radar componentry and radiation-hardened computing modules. Distribution runs through direct federal contracting vehicles for classified workloads and API-integrated SaaS marketplaces for commercial subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as sovereign data residency mandates splinter procurement requirements, creating defendable niches for regional analytics platforms with localized model training and inference infrastructure.
For Market Incumbents: Insulate classified contract positions by embedding explainable AI architectures that satisfy EU AI Act audit trail requirements. Prioritize backward integration into edge computing hardware for satellite bus deployment, neutralizing latency advantages from emerging orbital analytics competitors. Lock in agriculture subscription renewals through API partnerships with dominant farm management software stacks.
For New Entrants and Emerging Players: Pursue India's liberalized National Geospatial Policy environment for domestic processing node establishment and direct government disaster response contracting. Target carbon credit verification services in Asia-Pacific environmental compliance markets, where auditability requirements favor new platform architectures over legacy archive providers. Lead with automated flood extent mapping capabilities that compress emergency procurement timelines outside standard defense sales cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-centric analytics pure-plays as cloud infrastructure commoditizes processing pipelines. Over the medium-term horizon, acquisition value concentrates in specialized sensor modality operators with synthetic aperture radar or hyperspectral capabilities that resist rapid commoditization. Monitor EU AI Act certification timelines as inflection indicator for vendor competitive positioning in European defense and civil government markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Deployment | GDPR and EU AI Act compliance enables European defense contract access for certified platforms. |
| Edge Computing Satellite Integration | On-orbit inference engines compress threat alert delivery without ground station dependency. |
| Farm Management Software API Partnership | Embedded satellite intelligence locks in agriculture subscription renewals through workflow integration. |
| Synthetic Aperture Radar Capacity Expansion | All-weather imaging capability controls maritime surveillance and disaster response procurement channels. |
| Explainable AI Architecture Investment | Algorithmic transparency documentation satisfies EU AI Act mandates for European government contracts. |
Study Parameters
Desk research of satellite operator technical specifications, defense procurement databases, and regulatory filing precedents preceded structured interviews with remote sensing scientists, defense intelligence procurement officers, cloud infrastructure architects, and precision agriculture operations managers. Secondary validation drew from FAA commercial remote sensing licenses, EU AI Act implementation guidance, NOAA data distribution policies, and constellation operator SEC disclosures. Bottom-up service tier sizing and top-down geospatial AI investment flow analysis were triangulated against federal budget appropriation documents.
Forecast assumptions held fixed the current EU AI Act enforcement trajectory and United States federal space budget authorization levels, while varying launch cost decline curves and edge computing adoption rates across the projection horizon. The analytical framework modeled service type, end user vertical, core technology stack, and geographic deployment pattern as primary segmentation dimensions. CAGRs were derived from trend extrapolation of subscription revenue recognition patterns and defense contract award velocities, with cross-checks against cloud infrastructure capex allocation and geospatial AI talent pipeline expansion.
Macroeconomic conditions sit as an overlay; deviation in federal discretionary spending cycles or launch vehicle availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and constellation refresh timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
ASEAN Satellite Imagery Services Market
Satellite
Italy Satellite Imagery Services Market
Satellite
France Satellite-Based Earth Observation Market
Satellite
GEO Satellite Market
Satellite
South Korea Satellite Communication Market
Satellite
North America Military Satellite Market
Satellite
India Satellite-Based Earth Observation Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
UAE Satellite Communication Market
Satellite
4K Satellite Broadcasting Market
Satellite
Commercial Satellite Launch Service Market
Satellite
Europe Small Satellite Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Satellite Payload Market
Satellite
Middle East Satellite-Based Earth Observation Market
Satellite
Satellite Attitude and Orbit Control System Market