
 Asia-Pacific Military Satellite Market | 2026-2036
Asia-Pacific Military Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Military Satellite Market Insights
Modular payload architectures is rebalancing procurement decisions across Asia-Pacific defense ministries, allowing militaries to upgrade sensor suites without replacing entire satellite buses. China Aerospace Science and Technology Corporation leverages its vertical integration across launch vehicles and spacecraft manufacturing to dominate domestic supply. Thales competes through specialized encryption and signal-intelligence payloads for allied nations. Mitsubishi Electric Corporation anchors Japan's position with advanced optical sensor technology for reconnaissance platforms.
Asia-Pacific military satellites are spacecraft engineered for defense applications, typically operating in low Earth orbit at altitudes between 300 and 2,000 kilometers with hardened electronics against radiation and jamming, designed to provide secure communications, navigation, and intelligence-gathering functions for national security operations. Communications satellites command the largest share of current procurement budgets as navies and air forces demand uninterrupted beyond-line-of-sight connectivity across dispersed theaters. Earth observation satellites represent the fastest-expanding category, driven by optical and radar technology investments for maritime domain awareness in contested waters. Reconnaissance satellites concentrate margin pools where hyperspectral imaging and synthetic aperture radar differentiation justify premium pricing.
China's MIIT and SAMR enforce GB standards and dual-use export controls that shape domestic satellite component sourcing and foreign market access for military-grade systems. India's ISRO and DRDO coordinate with BIS certification requirements to channel military satellite development toward indigenous suppliers and controlled technology transfer. Japan's METI and defense procurement guidelines steer Mitsubishi Heavy Industries and subcontractors toward allied interoperability standards. Stakeholders must monitor how each national regulator calibrates civil-military technology boundaries as commercial space capabilities blur traditional acquisition categories.
Market Dynamics
Modular payload architectures are compressing satellite replacement cycles across Asia-Pacific defense ministries, enabling militaries to refresh sensor capabilities without deorbiting entire spacecraft buses. This structural shift is redrawing procurement economics and vendor relationships throughout the region.
Growth Catalysts
- MIIT dual-use export controls:China's tightened GB standards on satellite components are accelerating domestic substitution programs and channeling procurement toward indigenous suppliers.
- Maritime domain awareness requirements:Naval forces across contested waters are driving procurement of synthetic aperture radar and hyperspectral imaging payloads for persistent surveillance.
- ISRO launch capacity expansion:India's increasing indigenous launch cadence is reducing cost barriers for dedicated military satellite constellations.
Market Restraints
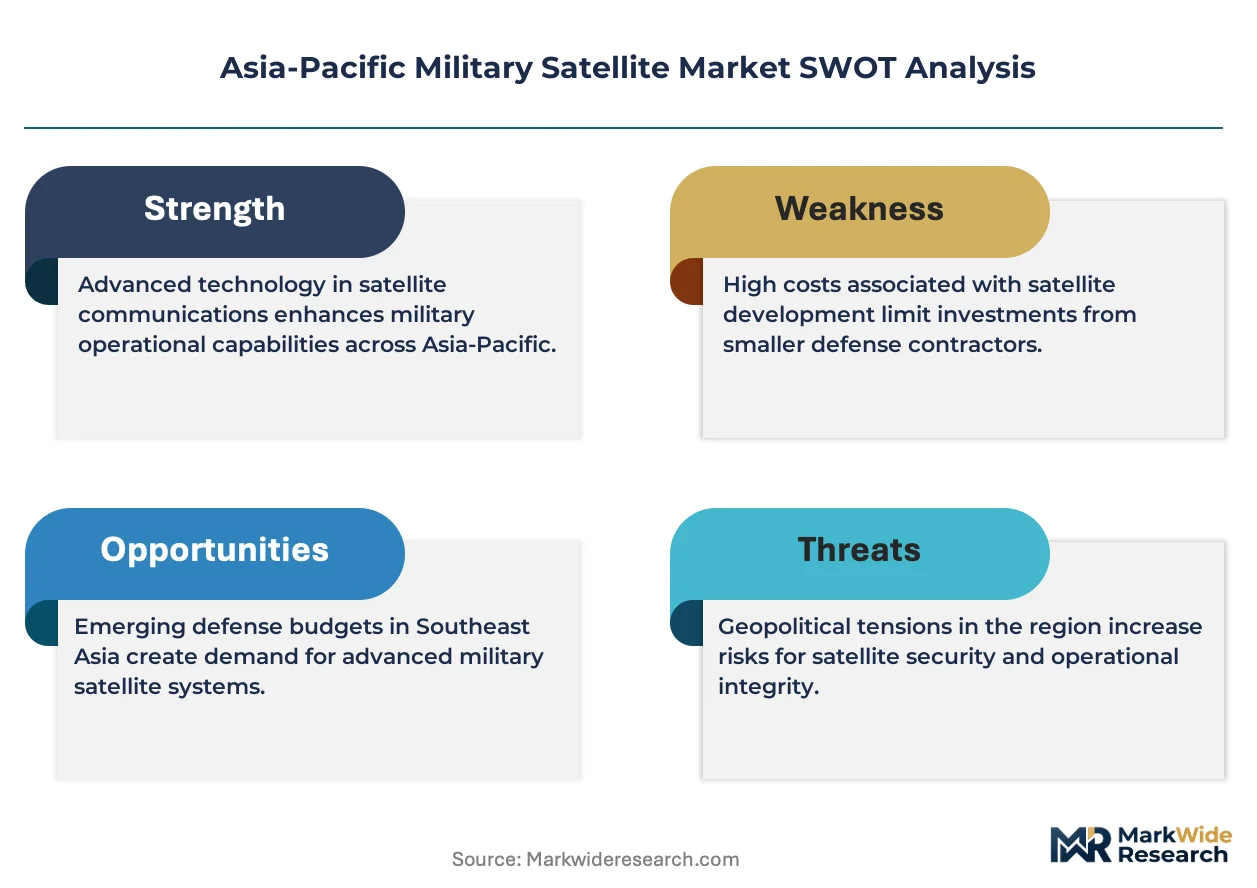
- Radiation-hardened electronics supply:Concentrated sourcing of qualified semiconductors from limited foundries creates input bottlenecks for spacecraft manufacturing.
- BIS certification timelines:India's controlled technology transfer requirements extend development cycles for foreign contractors seeking defense satellite contracts.
- Optical sensor export restrictions:Allied technology control regimes limit access to advanced focal plane arrays for non-allied nations.
Strategic Opportunities
- Vietnam and Philippines maritime surveillance:Underpenetrated Southeast Asian markets present white space for coastal monitoring satellite services.
- Quantum-encrypted optical links:Convergence of photonic integration and quantum key distribution enables next-generation secure communications architectures.
- Japan's METI defense procurement guidelines:Allied interoperability standards create channel access for qualified foreign payload suppliers.
Industry Challenges
- Space-qualified engineering talent:Specialized skills in thermal management and radiation effects remain scarce across the region's aerospace workforce.
- Legacy ground system integration:New satellite constellations must interface with existing command-and-control infrastructure, complicating deployment.
- ITAR-compliant supply chain reconfiguration:Contractors face friction in restructuring component sourcing to meet multiple national export control regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Military Satellite Market |
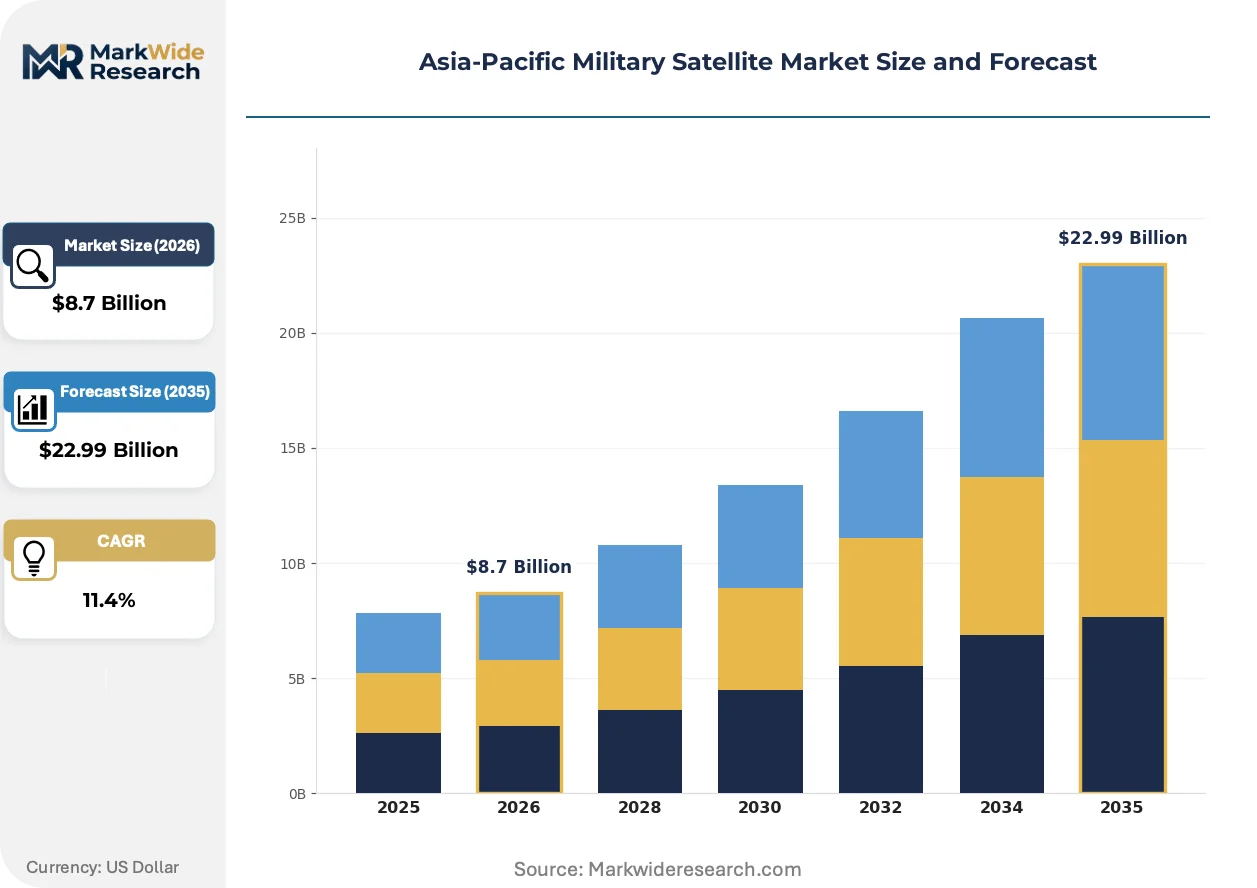
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communications Satellites, Earth Observation Satellites, Reconnaissance Satellites, Navigation Satellites End User: Defense Forces, Government Agencies, Military Contractors, Aerospace Companies Technology: Optical, Radar, Hyperspectral, RF Deployment: Low Earth Orbit, Medium Earth Orbit, Geostationary Orbit, Highly Elliptical Orbit |
| Companies Covered | China Aerospace Science and Technology Corporation (CASC), Indian Space Research Organisation (ISRO), Airbus SE, Thales, Mitsubishi Heavy Industries, Mitsubishi Electric Corporation, Korea Aerospace Industries Ltd., Innovative Solutions in Space BV, Lockheed Martin, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Military Satellite Market Trends and Innovations
Software-defined payload architectures are displacing fixed-function hardware across Asia-Pacific military satellite programs, compressing capability refresh cycles from decade-long bus replacements to incremental firmware and module upgrades.
Modular open systems architecture for satellite payloads is modularizing how defense agencies procure space capabilities. Japan's defense ministry is mandating open interface standards for new reconnaissance platforms. This approach is compressing vendor lock-in and enabling faster sensor swaps without spacecraft replacement.
China's GB standards enforcement through SAMR is tightening domestic content requirements for military-grade satellite components. Foreign contractors face expanded compliance documentation for dual-use technologies. Indian manufacturers are responding by accelerating BIS certification for indigenous alternatives.
Fleet managers across Asia-Pacific navies are consolidating satellite service contracts under longer-term managed service arrangements rather than discrete satellite procurement. Traditional equipment vendors are repositioning as capability providers with guaranteed availability metrics. This shift is most visible in Australian and Japanese maritime patrol programs.
Asia-Pacific Military Satellite Market Segmentation
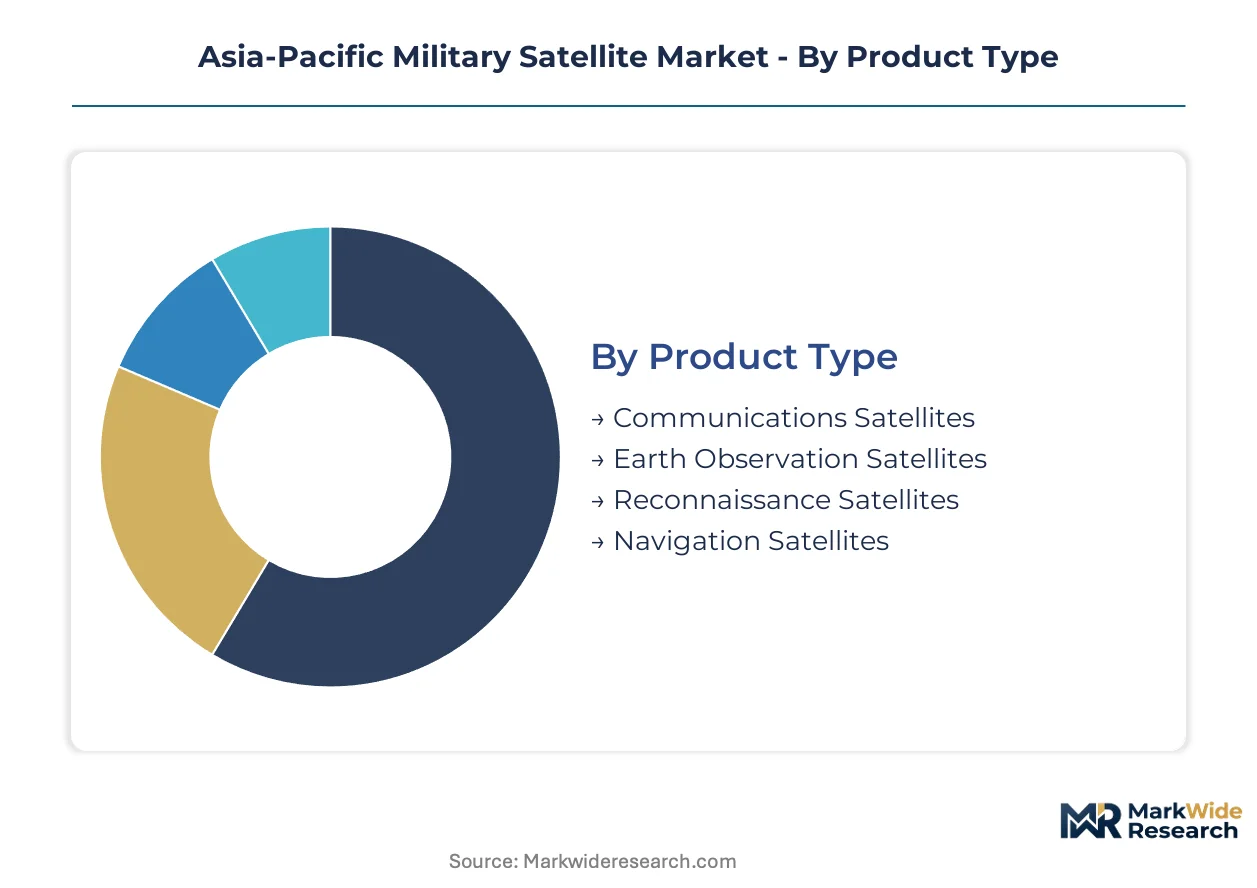
Defense procurement patterns across Asia-Pacific reveal distinct certification burdens and technical specifications governing each segment category. Procurement officers weigh orbital mechanics, payload sensitivity, and end-user classification against MIIT export controls, BIS certification timelines, and METI interoperability mandates when allocating satellite budgets.
Product Type:
GB standards enforcement through SAMR and BIS certification requirements create tiered compliance obligations across product categories, with communications payloads facing the most stringent encryption validation and reconnaissance platforms subject to dual-use technology transfer reviews.
- Communications Satellites:These spacecraft carry hardened transponders and cross-band repeaters for beyond-line-of-sight tactical networks. Demand concentrates in Indian Navy and Japan Maritime Self-Defense Force programs seeking uninterrupted connectivity across the Indian Ocean and East China Sea, constrained by radiation-hardened electronics sourcing bottlenecks from qualified foundries.
- Earth Observation Satellites:Platforms integrate synthetic aperture radar and multispectral sensors for maritime domain awareness. Procurement is accelerating in Vietnam and Philippines coastal surveillance programs responding to contested waterway monitoring requirements, though optical sensor export restrictions limit focal plane array access for non-allied nations.
- Reconnaissance Satellites:Hyperspectral imaging and signals intelligence payloads serve strategic intelligence collection missions.
- Navigation Satellites:Precise positioning and timing services support precision-guided munitions and asset tracking.
Leading the category by volume: Communications Satellites. Growing fastest: Earth Observation Satellites.
End User:
Customer type determines contract structure, with defense forces commanding dedicated procurement channels and military contractors absorbing technology transfer compliance costs that extend development cycles.
- Defense Forces:Service branches operate sovereign satellite constellations with classified ground segments.
- Government Agencies:Civil-military coordination bodies manage dual-use satellite procurement under national security directives.
- Military Contractors:System integrators like Mitsubishi Heavy Industries and domestic Chinese suppliers absorb BIS and GB standards compliance overhead, channeling foreign partnerships toward joint ventures with indigenous manufacturers to satisfy local content thresholds.
- Aerospace Companies:Prime contractors coordinate payload integration across subcontractor networks.
Highest procurement authority: Defense Forces. Fastest contract velocity: Military Contractors.
Technology:
Payload modality shapes supplier qualification requirements, with optical and hyperspectral systems facing stricter export control scrutiny than RF architectures.
- Optical:Visible and near-infrared imaging systems provide high-resolution reconnaissance.
- Radar:Synthetic aperture radar penetrates cloud cover and darkness for all-weather surveillance.
- Hyperspectral:Fine spectral resolution enables material identification and anomaly detection, with demand concentrating in Chinese and Japanese maritime intelligence programs where MIIT and METI guidelines steer procurement toward domestic sensor foundries.
- RF:Radio frequency payloads support communications and electronic intelligence.
Dominant installed base: RF. Steepest expansion trajectory: Hyperspectral.
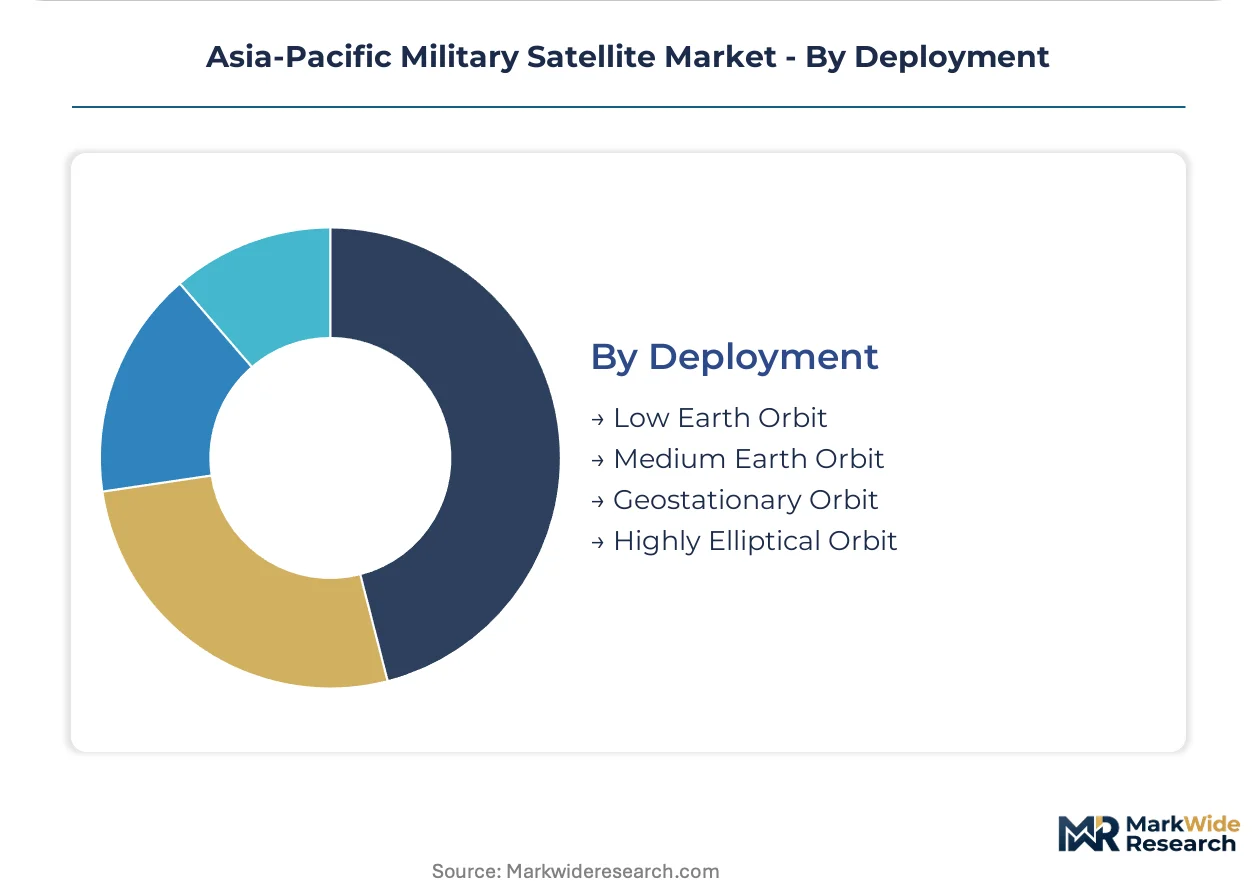
Deployment:
Orbital altitude determines launch cost economics and revisit frequency trade-offs that procurement officers weigh against mission endurance requirements.
- Low Earth Orbit:Altitudes between 300 and 2,000 kilometers enable high-resolution imaging and low-latency communications, with ISRO's expanding launch capacity reducing cost barriers for Indian military constellation deployment.
- Medium Earth Orbit:Intermediate altitudes balance coverage and signal latency for navigation services.
- Geostationary Orbit:Fixed-position satellites provide persistent regional communications coverage.
- Highly Elliptical Orbit:Elongated paths maximize dwell time over high-latitude territories.
Most deployed altitude: Low Earth Orbit. Gaining share fastest: Highly Elliptical Orbit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's vertically integrated aerospace complexes while consumption spreads across naval modernization programs from India to Southeast Asia. China's domestic launch capacity absorbs most indigenous satellite output, leaving limited exportable surplus. India's ISRO launch expansion is redirecting regional procurement patterns toward indigenous supply.
China
Naval fleet expansion and contested waterway surveillance drive procurement of synthetic aperture radar platforms. MIIT enforces GB standards and dual-use export controls that channel component sourcing toward domestic foundries. Shanghai and Xi'an aerospace clusters host CASC manufacturing complexes producing sovereign satellite constellations with minimal foreign technology dependence.
India
Indian Navy beyond-line-of-sight connectivity requirements and DRDO signals intelligence programs accelerate dedicated military constellation deployment. BIS certification timelines and controlled technology transfer rules extend foreign contractor development cycles. Bengaluru and Hyderabad host ISRO integration facilities and private sector satellite manufacturing campuses drawing venture investment.
Japan
Japan Maritime Self-Defense Force maritime patrol aircraft and destroyer fleets demand persistent satellite relay coverage across the East China Sea. METI defense procurement guidelines steer Mitsubishi Heavy Industries toward allied interoperability standards. Nagoya and Tokyo aerospace corridors concentrate optical sensor foundries and spacecraft bus assembly.
South Korea
Korea Aerospace Industries and defense ministry programs seek indigenous reconnaissance capabilities reducing dependence on foreign intelligence sharing. National security directives accelerate domestic satellite component certification. Daejeon and Seoul metropolitan areas host satellite integration facilities and ground control infrastructure development.
Australia
Royal Australian Navy and air force programs prioritize sovereign satellite communications for Indo-Pacific dispersed operations. Defense procurement guidelines emphasize allied supply chain integration over indigenous manufacturing. Adelaide and Canberra defense technology clusters concentrate on payload integration and ground segment operations rather than full spacecraft production.
Asia-Pacific Military Satellite Market Competitive Landscape
The competitive structure tilts toward state-backed vertical integrators with captive launch capacity. China's CASC and India's ISRO dominate procurement through sovereign launch infrastructure and domestic content mandates. Three archetypes define positioning: state-owned aerospace conglomerates with end-to-end manufacturing, specialized payload vendors with encryption or sensor expertise, and allied foreign primes serving interoperability requirements. Consolidation through state-directed merger activity and strategic partnership formation for technology access represent the dominant competitive moves.
Among state-backed integrators, China Aerospace Science and Technology Corporation exemplifies the vertically integrated archetype spanning launch vehicles through spacecraft manufacturing. Thales occupies a position representing specialized payload expertise in encryption and signal intelligence for allied nations. Mitsubishi Electric Corporation anchors Japanese supplier networks with advanced optical sensor capabilities for reconnaissance platforms.
| Leading Market Players |
|---|
| China Aerospace Science and Technology Corporation (CASC) |
| Indian Space Research Organisation (ISRO) |
| Airbus SE |
| Thales |
| Mitsubishi Heavy Industries |
| Mitsubishi Electric Corporation |
| Korea Aerospace Industries Ltd. |
| Innovative Solutions in Space BV |
| Lockheed Martin |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals and national security directives gate qualified supply for radiation-hardened electronics and premium-tier satellite pricing access, compressing vendor pools to certified domestic foundries while elevating procurement costs for foreign contractors navigating MIIT export controls and BIS certification timelines.
Pricing Analysis
Cost-down pressure on reconnaissance payloads accelerates because optical sensor export restrictions from allied technology control regimes constrain focal plane array supply. Pricing stratifies across sovereign-class communications satellites, allied-interoperable reconnaissance platforms, and economy-tier earth observation services. Price differentiation hinges on GB standards compliance grade and ISRO launch integration bundling. Defense forces exhibit lowest price sensitivity for signals intelligence missions, while Southeast Asian coastal surveillance programs absorb highest budget elasticity.
Supply Chain Analysis
Specialized workforce availability in Bengaluru, Shanghai, and Nagoya aerospace corridors constrains spacecraft bus manufacturing throughput. Geographic supply concentration centers on China's vertically integrated CASC complexes, India's ISRO-adjacent private campuses, and Japan's Mitsubishi Electric sensor foundries. Raw material dependencies rest on radiation-hardened semiconductors from qualified foundries, space-grade aluminum-lithium alloys, and precision optical glass substrates. Single-source vulnerability in qualified semiconductor sourcing creates structural risk. Distribution runs through sovereign procurement channels and allied interoperability frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific military satellite market sits in a software-defined payload transition, with modular open systems architecture displacing fixed-function hardware that locked defense agencies into decade-long replacement cycles.
For Market Incumbents: Anchor sovereign launch capacity and captive radiation-hardened electronics supply to defend against ISRO's expanding indigenous launch cadence eroding foreign contractor access. Deepen backward integration into optical sensor foundries to offset allied export control restrictions on focal plane arrays. Prioritize METI interoperability certification to maintain channel position in Japanese defense procurement. For New Entrants and Emerging Players: Quantum-encrypted optical link technology offers a technology-first wedge into secure communications architectures as defense forces confront electronic warfare threats. Target Vietnam and Philippines maritime surveillance white space with coastal monitoring satellite services. Pursue joint venture structures with Indian BIS-certified manufacturers to satisfy local content thresholds and compress development timelines. For Investors and Strategic Acquirers: ISRO's dedicated military constellation deployment acceleration is the leading indicator that indigenous launch capacity will reshape regional procurement patterns within a five-to-ten year viability window. Acquisition targets should emphasize software-defined payload specialists with modular architecture IP. Monitor MIIT dual-use export control calibration as the critical inflection signal for foreign market access contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Payload Architecture Adoption | Enables sensor refresh without spacecraft replacement, compressing procurement cycles for Indian and Japanese defense ministries. |
| Sovereign Launch Capacity Expansion | ISRO's increasing cadence reduces cost barriers for dedicated military constellations across South Asian naval programs. |
| Quantum-Encrypted Optical Link Development | Converges photonic integration with quantum key distribution for next-generation secure communications in contested theaters. |
| BIS Certification Acceleration | Indian manufacturers compress foreign contractor development cycles through indigenous alternative qualification. |
| Allied Interoperability Standard Alignment | METI guidelines steer Mitsubishi Heavy Industries toward channel access for qualified foreign payload suppliers. |
Research Methodology
Document review covered defense procurement databases, satellite manufacturing trade flows, and regulatory filings from MIIT, BIS, and METI, complemented by interviews with spacecraft program directors, radiation-hardened electronics procurement leads, launch vehicle integration engineers, and defense ministry satellite acquisition officers. Secondary sources included customs records for space-grade component trade, ISRO annual reports, and national security directive documentation. Bottom-up capacity modeling and top-down demand aggregation provided triangulation validation.
Segmented outputs across product type, end user, technology, and deployment altitude dimensions generated volume and value trajectories over the projection horizon. CAGRs derived from historical launch cadence patterns, procurement budget allocation trends, and technology substitution curves. Industry-specific inputs incorporated orbital mechanics constraints, payload sensitivity classifications, and national content requirement evolution.
Several conditions sit outside the modeled scope, including classified intelligence satellite specifications, undisclosed military ground segment investments, and abrupt export control regime revisions. Forecasts reflect documented assumptions regarding ISRO launch reliability maturation and sustained allied technology sharing frameworks. A small set of named triggers warrants ongoing watch: MIIT dual-use control expansion, BIS certification timeline compression, and quantum communications technology maturation inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Communication System Market
Satellite
Satellite Transponder Market
Satellite
United Kingdom Satellite Communications Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Satellite Operation Service Market
Satellite
Europe Small Satellite Market
Satellite
Germany Satellite Communications Market
Satellite
Germany Satellite Connectivity Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
Satellite Services Market
Satellite
Optical Satellite Communication Market
Satellite
Europe Satellite Attitude and Orbit Control System Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
North America Military Satellite Market
Satellite
Electric Propulsion Satellite Market