
 Micro Tactical Ground Robot Market | 2026-2036
Micro Tactical Ground Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Tactical Ground Robot Market Intelligence
The US Department of Defense's mandate for open architecture standards is decoupling proprietary hardware from software control systems, altering the cost of entry. This shift allows new entrants to compete on software and AI capabilities. Teledyne FLIR leverages its expertise in thermal imaging sensors to maintain a strong position. Meanwhile, Ghost Robotics specializes in legged robot platforms for difficult terrain navigation, differentiating itself through mobility.
A micro tactical ground robot is a compact, man-portable unmanned system, often weighing less than 50 pounds, designed for close-quarters reconnaissance. Its primary function is to provide real-time video and sensor data from hazardous areas, increasing operator safety. While the military end-user segment constitutes the largest share, demand from law enforcement for urban operations is accelerating. The control system segment shows a clear trend away from pure teleoperation toward semi-autonomous platforms with obstacle avoidance and waypoint navigation.
Compliance with military-grade standards, such as MIL-STD-810 for environmental durability, is a prerequisite for defense contracts in the United States and NATO countries. In Europe, CE marking for electromagnetic compatibility and adherence to radio frequency regulations governed by national authorities are critical for market access. The central strategic decision for developers is determining the optimal level of onboard autonomy versus retaining human-in-the-loop control for complex tactical scenarios.
Market Dynamics
The central force shaping the market is the standardization of open architecture frameworks, mandated by defense agencies like the US Department of Defense. This decouples hardware platforms from proprietary software, lowering barriers to entry and shifting competitive value toward AI-driven control systems and sensor integration.
Growth Catalysts
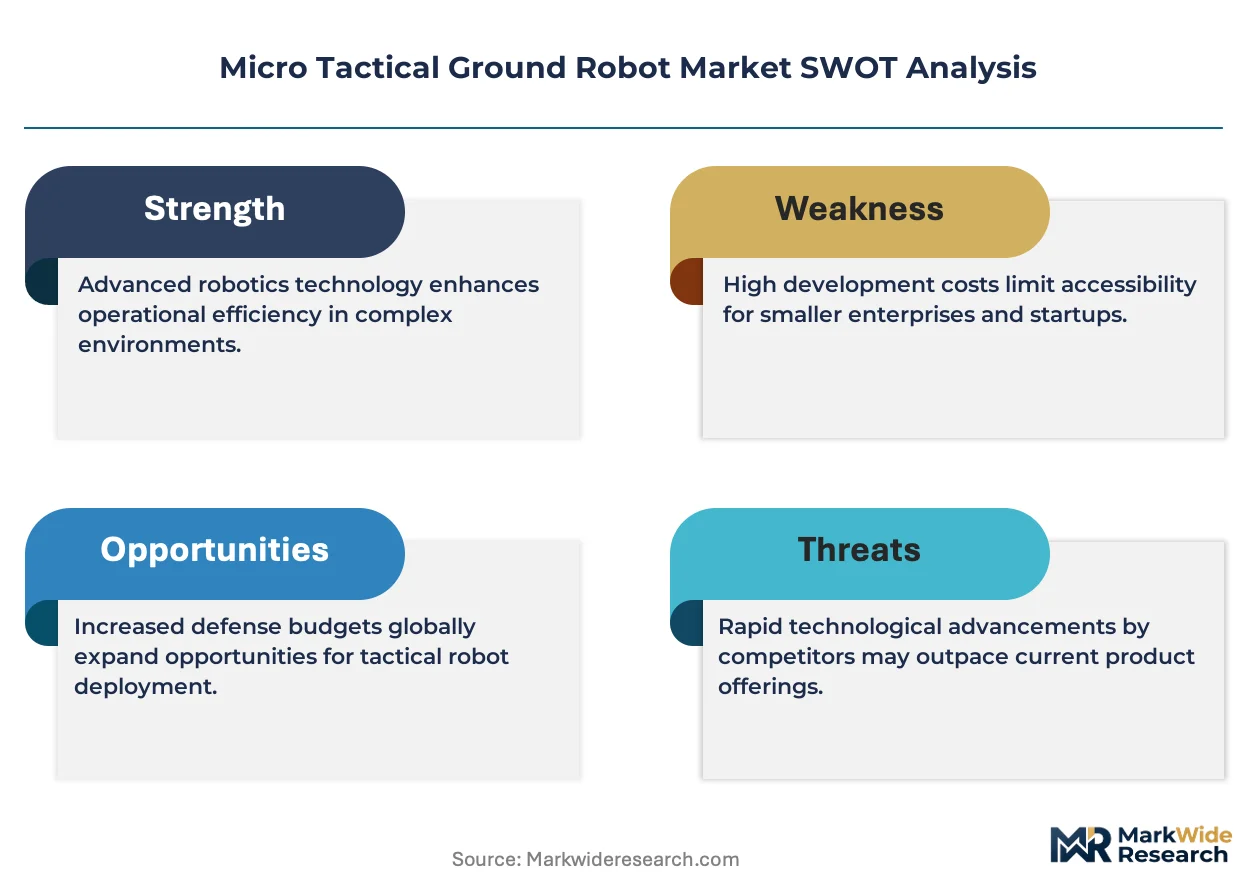
- Advancements in AI Navigation:The integration of AI and machine learning for autonomous navigation and target recognition enhances robot effectiveness in complex urban terrain, increasing demand from special operations forces and police tactical units for reconnaissance missions.
- Defense Modernization Programs:Concentrated procurement through large-scale defense modernization initiatives in the United States and Israel provides a stable, long-term demand signal for next-generation man-portable robotic systems.
- Urban Security Imperatives:A heightened focus on urban warfare and domestic counter-terrorism by law enforcement and national guard units is creating new requirements for compact robots capable of indoor and subterranean surveillance.
Market Restraints
- High Component Costs:The expense of military-grade components, including hardened chassis, radiation-tolerant electronics, and high-resolution thermal sensors, constrains broader adoption, particularly among smaller law enforcement agencies with limited budgets.
- Power Source Limitations:Limited battery life and low power density remain a significant technical barrier, restricting the operational endurance and payload capacity of micro tactical robots, especially for extended surveillance missions.
- Export Control Regulations:Stringent regulations, such as the International Traffic in Arms Regulations (ITAR) in the United States, limit the sale of advanced robotic systems to foreign governments, restricting the total addressable market for manufacturers.
Strategic Opportunities
- Critical Infrastructure Security:An emerging application is the inspection and security of critical infrastructure, such as nuclear power plants and petrochemical facilities, where robots can perform patrols and detect anomalies in hazardous environments.
- Technology Convergence:Combining advanced legged mobility platforms with multi-modal sensor fusion (e.g., LiDAR, thermal, acoustic) creates opportunities for systems that can navigate previously inaccessible terrain for search and rescue or reconnaissance.
- New Geographic Markets:Nations across Eastern Europe and Southeast Asia are increasing defense spending on border security and surveillance technologies, representing underpenetrated markets for ruggedized ground robot systems.
Industry Challenges
- Systems Integration Complexity:A primary operational challenge is ensuring seamless integration of new robotic platforms with legacy command and control (C2) software and communication networks used by military and police forces.
- Certification Timelines:The lengthy and expensive process of obtaining mandatory certifications, such as MIL-STD-810 for environmental resilience and CE marking for electromagnetic compatibility in Europe, can delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Tactical Ground Robot Market |
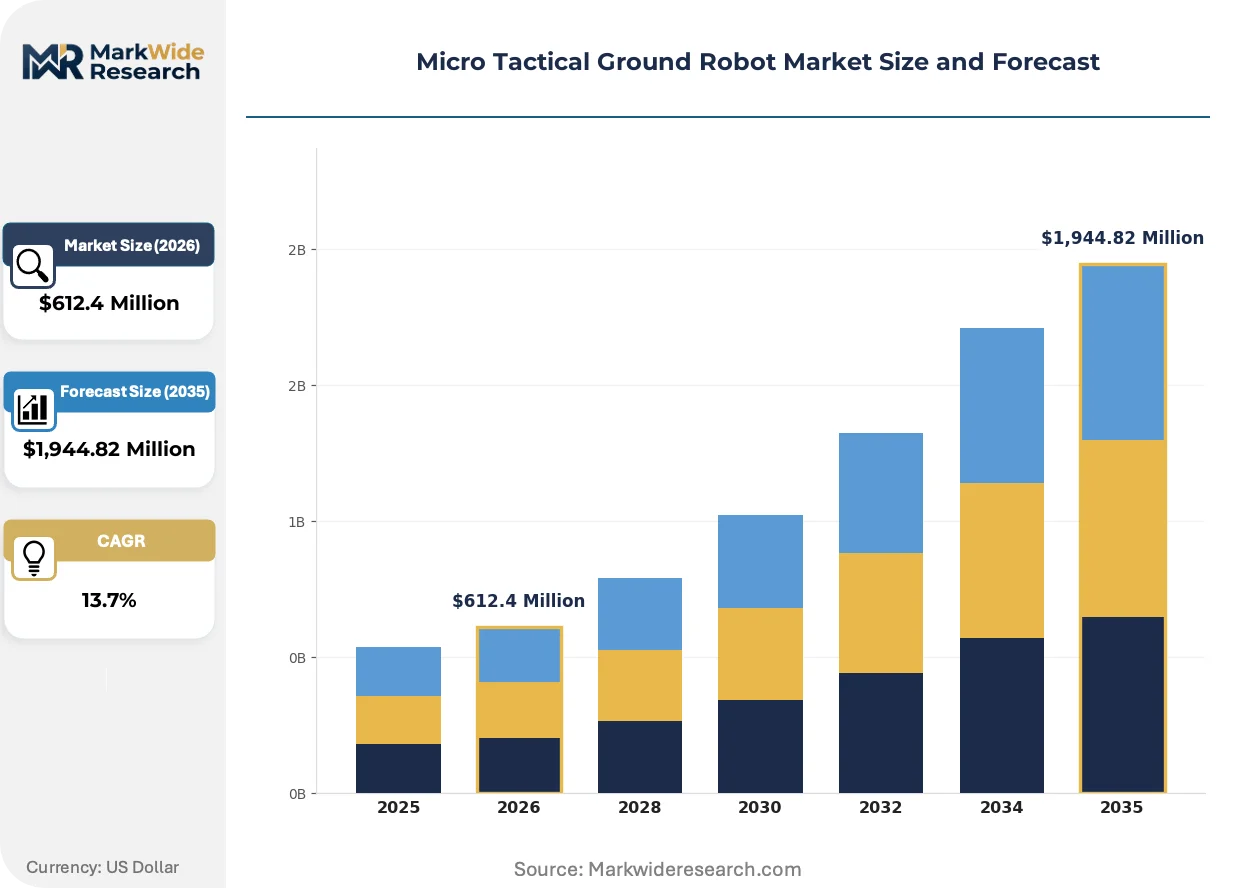
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,944.82 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unmanned Ground Vehicles, Surveillance Robots, Reconnaissance Robots, Bomb Disposal Robots End User: Military, Law Enforcement, Civil Defense, Research Institutions Control System: Remote Control, Autonomous, Semi-Autonomous, Teleoperation Application: Surveillance, Search and Rescue, Hazardous Material Handling, Training Simulations |
| Companies Covered | Roboteam, Teledyne FLIR, ReconRobotics, QinetiQ Group, Ghost Robotics, Northrop Grumman, Boston Dynamics, Thales, Clearpath Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Tactical Ground Robot Market Strategic Shifts & Innovations
A fundamental shift from hardware-defined performance to software-centric capabilities is underway. This evolution is driven by the convergence of open system architectures and rapid advancements in onboard artificial intelligence, redefining what constitutes a tactical advantage in unmanned ground systems.
On-device AI processing for autonomous functions is a key technological evolution. Military and law enforcement special teams are the primary adopters, seeking to reduce the cognitive load on operators during high-stress missions. This capability is decentralizing tactical awareness, enabling individual robots to navigate, identify threats, and adapt to dynamic environments without constant human intervention.
The European Union's AI Act introduces a risk-based framework that will govern the use of artificial intelligence. This policy creates stringent transparency and compliance obligations for high-risk systems, including those deployed for law enforcement and defense. The control system segment is most affected, as developers targeting the EU must now build for auditable decision-making and robust data governance.
A transition toward modular, payload-agnostic platform acquisition is altering buying behavior. This model displaces the purchase of single-vendor, fully integrated systems, enabling agencies to source the best-in-class chassis, sensors, and software from different specialist suppliers. This trend is most pronounced in the United States and Israel, where open architecture mandates from defense departments are accelerating the unbundling of system components.
Micro Tactical Ground Robot Market Segmentation
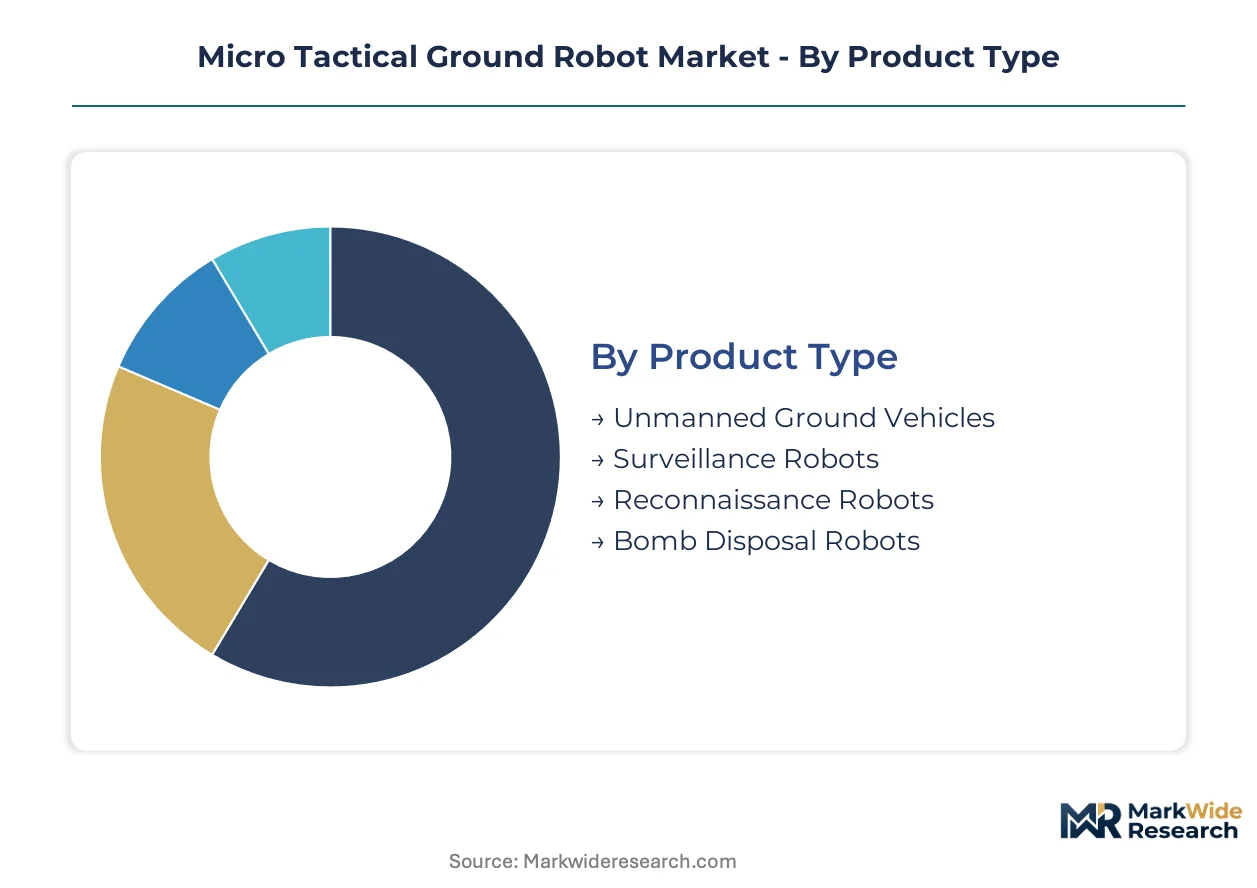
The micro tactical ground robot market's segmentation provides a granular view of product specialization, end-user requirements, technological advancements in control, and diverse operational applications. Understanding these distinct segments is crucial for developers to align product roadmaps with specific demand signals and for procurers to identify optimal solutions.
Product Type:
The product type segmentation highlights the spectrum from highly standardized, multi-purpose platforms to specialized, mission-specific robotic designs.
- Surveillance Robots:These compact systems are equipped with high-resolution cameras, thermal imagers, and acoustic sensors for intelligence gathering in confined or hazardous spaces. Demand from law enforcement agencies for urban reconnaissance missions is accelerating.
- Unmanned Ground Vehicles:This broad category encompasses man-portable robotic platforms designed for various ground-based tasks, often serving as a base chassis for different payloads. Defense modernization programs in the United States and Israel are driving procurement of these versatile systems.
- Reconnaissance Robots:These robots specialize in gathering visual and sensor data from dangerous or inaccessible areas, providing operators with real-time situational awareness.
- Bomb Disposal Robots:Highly specialized platforms designed to remotely identify, disarm, or neutralize explosive ordnance, prioritizing operator safety in high-risk scenarios.
Leading the category by volume: Unmanned Ground Vehicles. Growing fastest: Surveillance Robots.
End User:
End-user categories exhibit varying budget constraints and procurement processes, influencing the cost-tiering of adopted micro tactical ground robot systems.
- Military:This segment represents the largest share, procuring advanced robots for reconnaissance, IED detection, and force protection in combat zones. Military-grade standards like MIL-STD-810 are prerequisite for procurement within NATO countries.
- Law Enforcement:Police tactical units and domestic counter-terrorism agencies utilize these robots for urban surveillance, hostage situations, and hazardous environment assessment. Demand for compact robots in urban operations is accelerating.
- Civil Defense:These organizations deploy robots for disaster response, structural assessments after collapses, and monitoring hazardous incidents to protect human responders.
- Research Institutions:Academic and governmental research entities use micro tactical robots for developing new autonomous behaviors, sensor fusion techniques, and human-robot interaction studies.
Military end-users command the largest share of the market, while law enforcement agencies represent a significant and expanding demand pool.
Control System:
The evolution of control systems reflects a progression from basic operator intervention to sophisticated onboard intelligence, defining technology maturity levels within the market.
- Autonomous:These systems operate with minimal human intervention, utilizing onboard AI for navigation, obstacle avoidance, and target recognition in dynamic environments. Special operations forces are primary adopters seeking reduced operator cognitive load.
- Semi-Autonomous:Platforms combine human oversight with automated functions like waypoint navigation and obstacle avoidance, balancing operator control with enhanced efficiency. The control system segment shows a clear trend toward these platforms.
- Remote Control:Operators directly manipulate robot movement and functions via a tethered or wireless connection, offering precise control but requiring constant human attention.
- Teleoperation:This method provides real-time sensory feedback to the operator, allowing for more intuitive control, often used in complex manipulation tasks.
The market is clearly transitioning towards more autonomous and semi-autonomous control systems to enhance operational efficiency and reduce operator cognitive load.
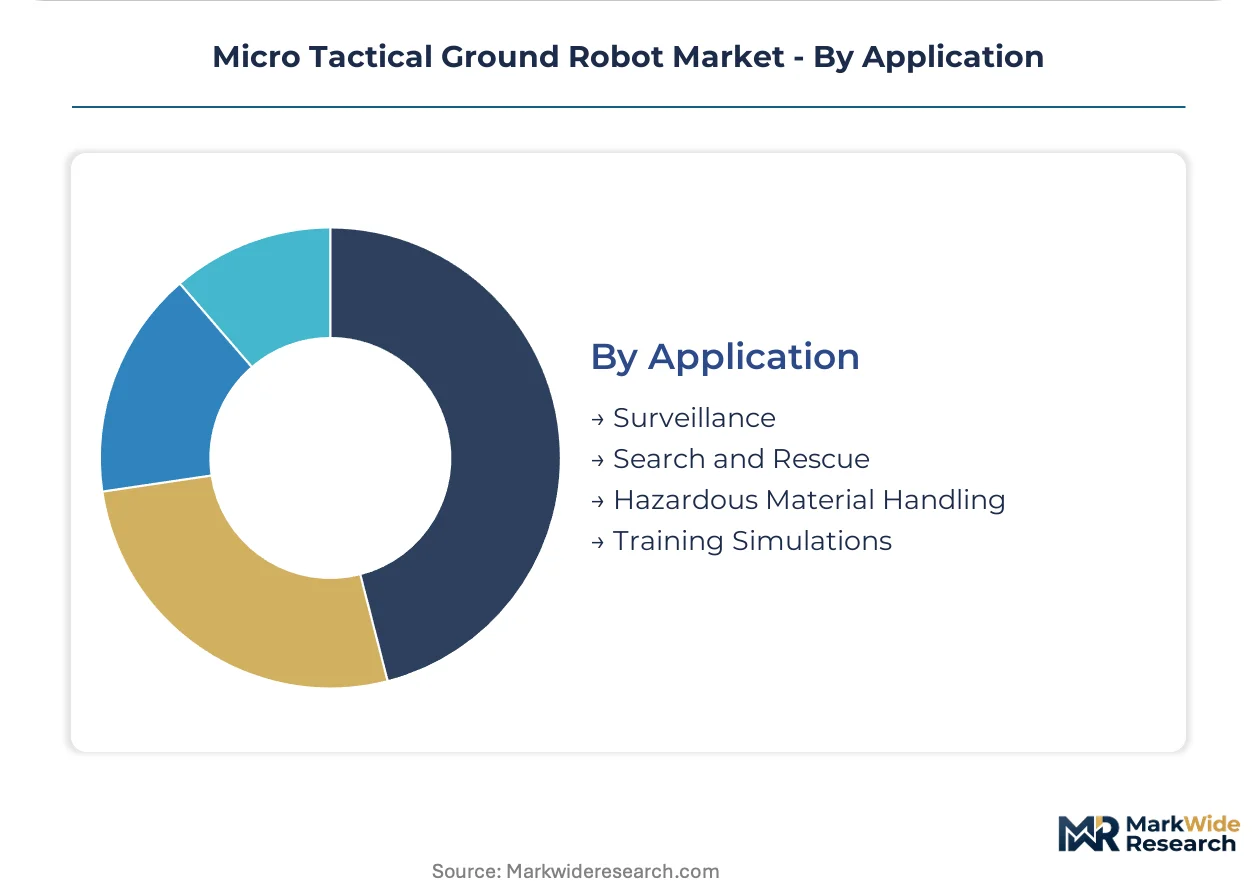
Application:
Application segments differentiate micro tactical ground robots by their direct impact on operator safety and mission efficiency across diverse operational environments.
- Surveillance:This primary application involves gathering visual, audio, and thermal intelligence from dangerous or inaccessible areas to provide situational awareness. Urban security imperatives drive demand for these capabilities.
- Search and Rescue:Robots navigate complex debris fields or hazardous environments to locate survivors, assess damage, and deliver vital supplies in disaster scenarios. Technology convergence with legged mobility platforms enhances capabilities in this area.
- Hazardous Material Handling:Specialized robots are deployed to inspect, contain, or neutralize dangerous substances without exposing human personnel to risk. Critical infrastructure security presents an emerging application.
- Training Simulations:Robots serve as dynamic targets or role players in military and law enforcement training exercises, offering realistic scenarios for tactical response.
Surveillance applications remain the core utility, but versatility in hazardous material handling and search and rescue expands the operational footprint of these robotic systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Strategic defense modernization programs, particularly within the United States and Israel, create concentrated procurement hubs for micro tactical ground robots. These initiatives establish robust demand signals, driving innovation and investment in advanced unmanned systems. Emerging markets in Eastern Europe and Southeast Asia also present new growth opportunities for ruggedized robotic platforms.
United States
The United States drives significant demand for micro tactical ground robots through its defense modernization programs and law enforcement needs. Compliance with MIL-STD-810 for environmental durability is a prerequisite for defense contracts. The Department of Defense, centered in areas like Northern Virginia, dictates open architecture standards, influencing technological development.
Israel
Israel's defense establishment actively procures micro tactical ground robots for urban security and reconnaissance missions. National security imperatives shape specific procurement policies and rapid integration cycles. Tel Aviv's vibrant defense technology cluster fosters innovation in robotics and autonomous systems.
Germany
German defense forces and critical infrastructure operators seek micro tactical ground robots for reconnaissance and hazardous material handling. Adherence to CE marking for electromagnetic compatibility is essential for market entry. Robotics research centers in Munich and Stuttgart contribute to advancements in autonomous navigation.
Poland
Polish defense spending on border security and surveillance technologies creates new demand for micro tactical ground robots. Compliance with NATO standards and European radio frequency regulations is critical. Warsaw's emerging defense industry supports the integration of advanced robotic capabilities.
Singapore
Singapore focuses on urban security and critical infrastructure protection, driving demand for compact surveillance robots. The nation's defense procurement policies emphasize high-tech solutions and operational efficiency. Research and development hubs in areas like Fusionopolis advance robotics and AI integration.
Micro Tactical Ground Robot Market Key Industry Players
United States producers anchor one tier, emphasizing advanced AI and open architecture integration; European specialists hold another, focusing on regulatory compliance and diverse applications. The market structure exhibits a tiered approach, with established defense contractors operating alongside agile robotics startups. Key strategic archetypes include platform specialists, sensor integration experts, and software-centric solution providers. Competitive moves involve technology licensing and strategic partnerships to integrate best-in-class components.
Specialists in specific technology domains, such as Teledyne FLIR, leverage their expertise in thermal imaging sensors to maintain a strong market position. Ghost Robotics exemplifies innovation in legged robot platforms, differentiating through enhanced mobility for difficult terrain navigation. QinetiQ Group, a defense technology company, represents a broader approach, integrating various robotic solutions for military and security applications. These companies contribute to the market's evolution toward modular, payload-agnostic systems.
| Leading Market Players |
|---|
| Roboteam |
| Teledyne FLIR |
| ReconRobotics |
| QinetiQ Group |
| Ghost Robotics |
| Northrop Grumman |
| Boston Dynamics |
| Thales |
| Clearpath Robotics |
| Others |
Cost & Logistics Intelligence
Military-grade standards, such as MIL-STD-810 for environmental durability, gate qualified supply and enable premium-tier pricing access for compliant systems. This regulatory hurdle impacts both component sourcing and final product validation, influencing cost structures across the market.
Pricing Analysis
Lead-time-driven contracts command premium pricing for micro tactical ground robots, especially for urgent defense modernization programs. The dominant pricing model remains per-unit transactional, though long-term contract-based offtake is common for large military procurements. Price differentiation stems from the inclusion of military-grade components and the level of customization for specific mission profiles. Pricing pressure stems from the shift towards open architecture, which lowers barriers to entry for software-centric solutions. Smaller law enforcement agencies exhibit the highest price sensitivity, while defense departments typically prioritize capability over cost.
Supply Chain Analysis
Dual-sourcing requirements from defense agencies often mandate multi-supplier qualification for critical components, enhancing supply chain resilience. Geographic supply concentration includes specialized component manufacturing in the United States, Israel, and Germany. The supply chain relies heavily on hardened chassis, radiation-tolerant electronics, and high-resolution thermal sensors. Export control regulations, such as ITAR in the United States, represent a significant structural risk, limiting the total addressable market. Distribution primarily runs through direct sales channels to military and law enforcement end-users, augmented by specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with on-device AI processing replacing pure teleoperation as the core capability. This shift redefines tactical advantages for unmanned ground systems.
For Market Incumbents: Hedge against the commoditization of hardware platforms by acquiring agile software-centric startups specializing in AI and autonomy. Invest in robust R&D for on-device AI processing and advanced sensor fusion to maintain technological leadership. Strategic partnerships with specialized component manufacturers can secure access to next-generation military-grade electronics. Compliance with evolving open architecture standards is crucial to avoid being locked out of major defense procurement cycles.
For New Entrants and Emerging Players: Smaller law enforcement agencies represent an underserved buyer archetype, seeking cost-effective solutions for urban surveillance and hazardous environment assessment. Target critical infrastructure security applications and civil defense for search and rescue operations. Focus on developing modular, payload-agnostic software and AI capabilities that integrate seamlessly with various hardware platforms. A go-to-market angle emphasizing rapid deployment and ease of integration into existing command and control systems will resonate with budget-constrained agencies.
For Investors and Strategic Acquirers: Widespread adoption of open architecture standards outside the United States and Israel is the leading indicator that signals market maturation and increased M&A opportunities. The long-term viability of this market is strong, driven by persistent defense modernization and urban security imperatives. Target acquisition archetypes include specialists in AI-powered autonomous navigation, advanced sensor miniaturization, and legged mobility platforms. Deviation in major defense spending allocations would shift the outlook materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in On-Device AI | Enhances autonomous navigation and threat recognition, reducing operator cognitive load for special operations forces. |
| Develop Modular Platforms | Enables agencies to integrate best-in-class sensors and software, fostering broader adoption by military and law enforcement. |
| Expand Critical Infrastructure Security Offerings | Addresses an emerging application for patrols and anomaly detection in hazardous environments like nuclear power plants. |
| Pursue Strategic Software Partnerships | Accelerates integration with diverse command and control systems, ensuring interoperability for defense and police forces. |
| Target Emerging Geographic Markets | Captures new demand from nations in Eastern Europe and Southeast Asia increasing border security spending. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market insights. Primary interviews with defense procurement officers, law enforcement tactical unit leaders, robotics engineers, and AI developers validated market dynamics. This approach combined bottom-up data collection with top-down market sizing, ensuring comprehensive triangulation. Technology patent databases and military doctrine publications further enriched the secondary research.
Data-stream reconciliation across multiple sources informed the analytical framework, projecting market evolution across the analysis window. Segmentation dimensions modeled included product type, end-user, control system maturity, application, and regional procurement trends. Compound annual growth rates were derived from historical trends, projected technology adoption rates, and anticipated defense budget allocations. Key forecast inputs included defense modernization program timelines and AI advancement roadmaps.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical conflicts, technological breakthroughs, and shifts in defense spending. These forecasts reflect assumptions regarding continued defense modernization and the pace of AI integration into tactical systems. Deviation in export control regulations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Bomb Disposal Robot Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
Maritime Drone Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Drone-In-A-Box Solutions Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
Vetronics Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market
Unmanned Systems
United States ROV Market
Unmanned Systems
North America Hyperloop Technology Market