
 Satellite Payload Market | 2026-2036
Satellite Payload Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Payload Market Intelligence
Project finance and long-term payload leasing is rewriting competitive access in the satellite payload sector. Thales Alenia Space leverages European institutional backing to sustain large geostationary programs. SpaceX anchors its position through in-house manufacturing scale and vertical cost control. Lockheed Martin Corporation differentiates via classified defense payload integration and hardened radiation designs.
A satellite payload comprises the mission-specific instruments, transponders, antennas, and sensor packages integrated into a spacecraft bus, typically operating across radio frequency, optical, or synthetic aperture radar modalities to perform telecommunications, earth observation, or navigation functions. Communication payloads currently dominate revenue as LEO and MEO constellation operators replace aging geostationary capacity. Remote sensing payloads represent the fastest-expanding margin pool, driven by defense intelligence contracts and precision agriculture analytics. Synthetic aperture radar technology is displacing optical systems in all-weather military applications where cloud cover and darkness limit traditional imaging.
The FCC governs spectrum allocation and orbital debris mitigation requirements for U.S.-registered payloads, while the FAA oversees commercial launch licensing that directly gates deployment schedules. ESA procurement rules and ITAR export controls shape transatlantic supplier access and technology transfer boundaries. Stakeholders must monitor evolving debris remediation mandates and dual-use classification shifts that could restructure supplier eligibility and program funding pathways.
Market Dynamics
Defense procurement cycles are compressing as Space Force and NATO allies demand multi-orbit resilience, forcing payload suppliers to reconfigure production lines for rapid reconfigurability rather than bespoke geostationary builds.
Growth Catalysts
- LEO Constellation Deployment:Commercial operators are blanketing low-Earth orbit with broadband nodes, creating sustained demand for miniaturized phased-array antennas and digital transparent processors.
- FCC Streamlined Licensing:The Commission's accelerated approval timelines for non-geostationary systems have collapsed deployment schedules from years to months for U.S.-registered operators.
- Synthetic Aperture Radar:All-weather imaging capabilities are displacing optical systems in defense intelligence contracts where cloud cover renders traditional sensors ineffective.
Market Restraints
- Radiation-Hardened Electronics Supply:Foundry capacity for space-qualified semiconductors concentrates in a handful of U.S. and European facilities, creating bottlenecks for high-volume constellation programs.
- ITAR Export Controls:U.S. State Department classification of advanced payload components restricts technology transfer to allied nations, fragmenting supplier ecosystems across the Atlantic.
- Launch Cost Volatility:Propellant price swings and launch vehicle availability constrain deployment cadence for operators without captive launch capacity.
Strategic Opportunities
- India Manufacturing Localization:ISRO's commercial arm and private sector entrants are building domestic payload integration facilities to serve regional constellation operators.
- Optical Inter-Satellite Links:Laser communication terminals are converging with quantum encryption modules to create ultra-secure backbone networks for government users.
- ESA In-Orbit Servicing Mandates:European debris remediation requirements are opening markets for refuelable and modular payload architectures.
Industry Challenges
- Radiation Effects Engineering Talent:The specialized workforce for single-event upset mitigation and total ionizing dose hardening is thinning as semiconductor industry compensation outpaces aerospace salaries.
- Multi-Orbit Integration Complexity:Operators struggle to harmonize legacy geostationary ground segments with proliferated LEO architectures, forcing expensive middleware development.
- Dual-Use Classification Uncertainty:Payload suppliers face unpredictable export license timelines when civilian earth observation capabilities approach military-grade resolution thresholds.
Report Scope
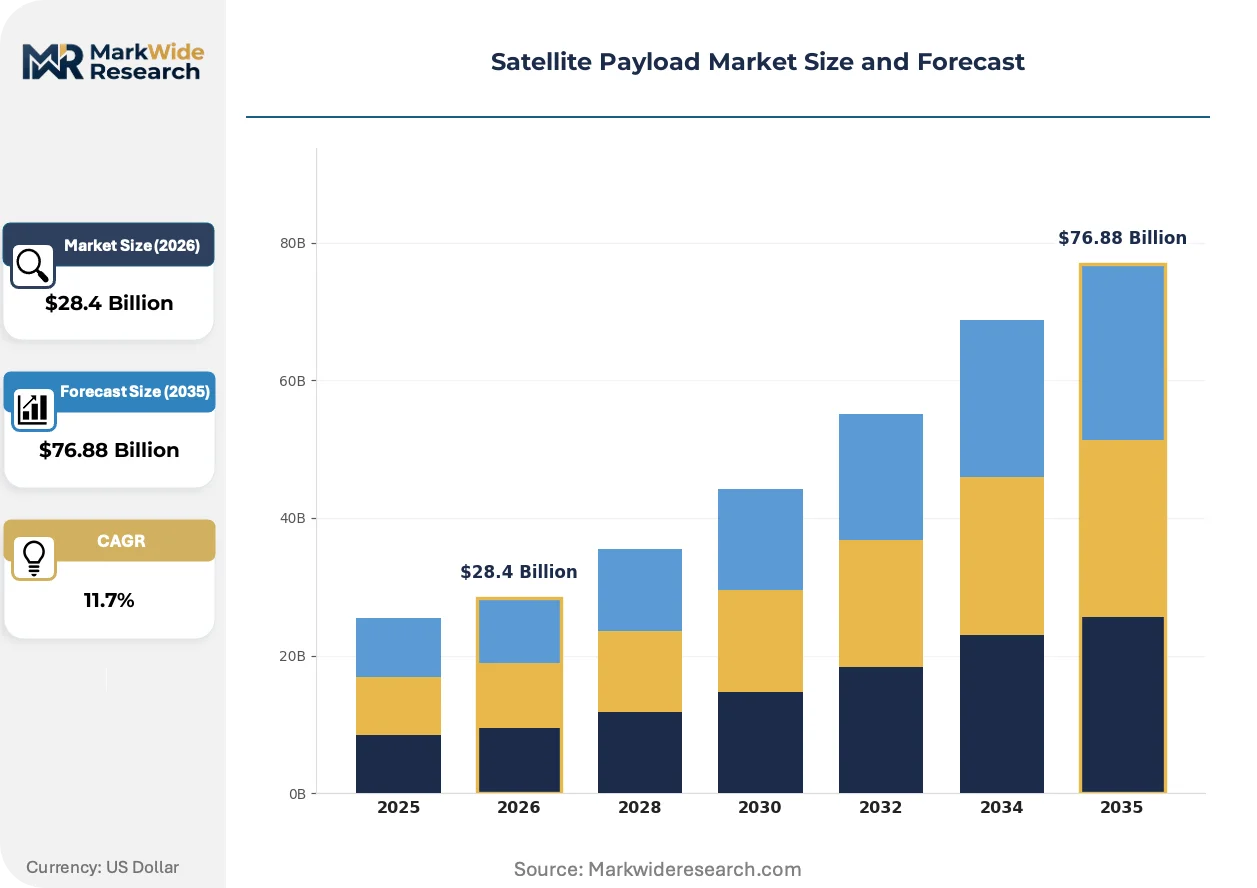
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Payload Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $76.88 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Communication Payloads, Remote Sensing Payloads, Scientific Payloads, Navigation Payloads, Technology Demonstration Payloads Technology: Radio Frequency, Optical, Synthetic Aperture Radar, Hyperspectral Imaging, Infrared Sensors Application: Telecommunications, Earth Observation, Space Science, Positioning and Timing, Disaster Management End User: Government Agencies, Space Research Organizations, Defense Departments, Commercial Enterprises, Academic Institutions |
| Companies Covered | Northrop Grumman Corporation, Thales Alenia Space, SpaceX, Raytheon Technologies Corporation, The Boeing Company, Airbus, L3Harris Technologies Inc, Maxar Technologies Corporation, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Payload Market Strategic Shifts & Innovations
Software-defined architectures are dissolving the boundary between payload and bus, enabling satellite operators to reconfigure mission parameters years after launch through over-the-air updates rather than hardware replacement.
Digital transparent processors are migrating from analog bent-pipe transponders in geostationary platforms to regenerative onboard processing nodes in medium-Earth orbit constellations. Military communications providers are adopting these flexible architectures fastest, driven by jam-resistant waveform requirements. This migration from hardware-defined to software-defined signal chains is compressing payload obsolescence cycles and extending operational lifespans through firmware refresh.
The FCC's updated orbital debris mitigation rules now mandate collision avoidance systems and post-mission disposal reliability thresholds for all U.S.-licensed satellites above six hundred kilograms. Operators must demonstrate ninety percent probability of successful deorbit or graveyard orbit placement within five years of mission end. Small satellite manufacturers in California and Colorado are redesigning propulsion modules to meet these standards, adding mass and complexity to nominally disposable platforms.
Defense agencies are unbundling payload procurement from bus and launch services, creating direct commercial relationships with sensor and transponder specialists. Space Force's proliferated warfighter space architecture contracts now separate mission payload awards from spacecraft integration, bypassing traditional prime contractor markups. This disaggregation is most visible in rapid acquisition pathways for tactical ISR, where government buyers contract synthetic aperture radar and signals intelligence packages directly from payload vendors in Maryland and Massachusetts.
Satellite Payload Market Segmentation
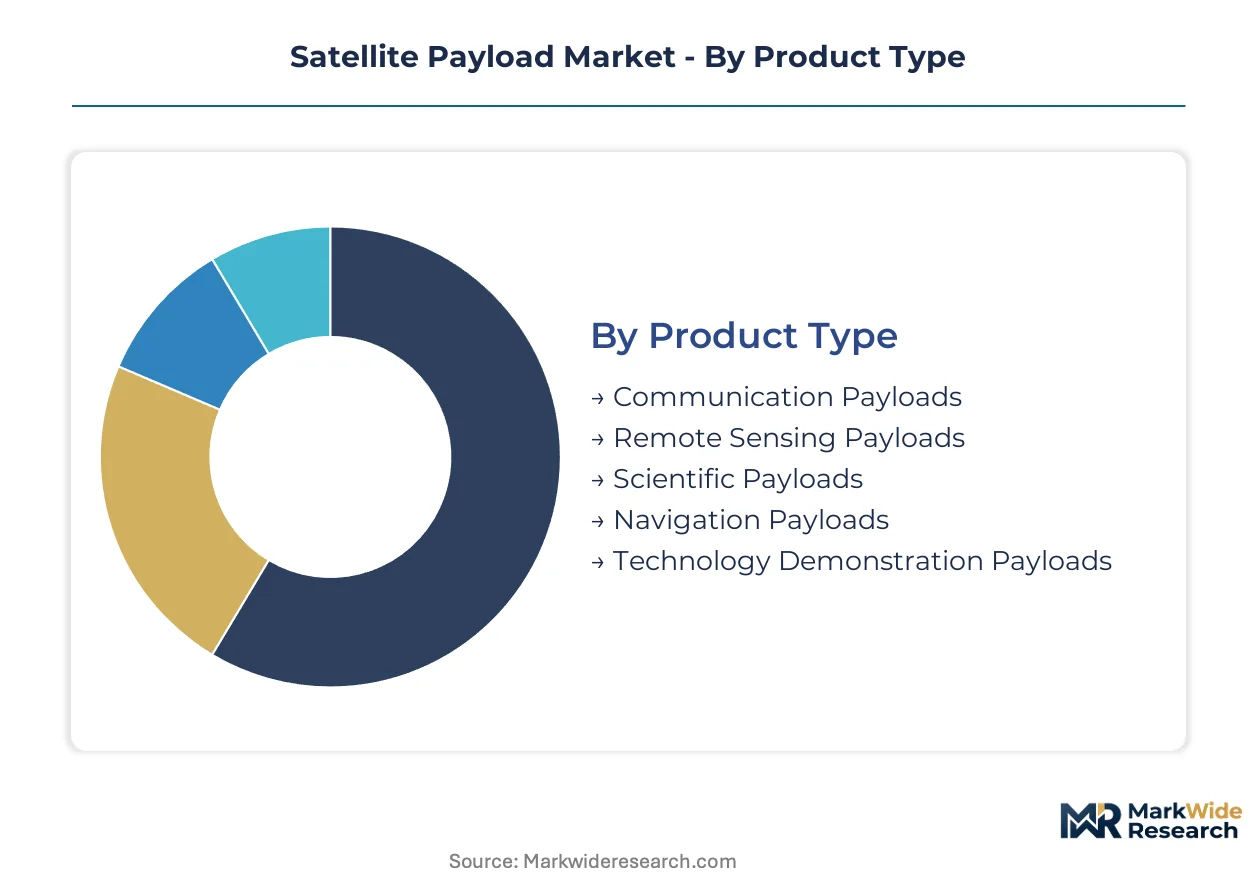
Satellite payload segmentation reveals divergent investment cycles across mission types. Communication payloads turn over rapidly as constellation operators refresh capacity, while scientific instruments endure decade-long development timelines before reaching orbit.
Product Type:
Cycle times vary dramatically: communication payloads refresh every 3-5 years with constellation replenishment, remote sensing platforms operate 7-10 year design lives, and scientific instruments often require 15+ year development-to-deployment horizons.
- Communication Payloads:Digital transparent processors and phased-array antennas handle broadband routing across LEO and MEO constellations. Demand concentrates in the United States where Space Force and commercial operators like Starlink drive procurement of software-defined transponders with rapid reconfiguration capability.
- Remote Sensing Payloads:Synthetic aperture radar and hyperspectral sensors capture terrain data through cloud cover and darkness. Defense intelligence contracts in the United States and precision agriculture analytics in Brazil and Australia concentrate demand for all-weather imaging systems with sub-meter resolution.
- Scientific Payloads:Instruments for astrophysics and heliophysics missions.
- Navigation Payloads:Atomic clocks and signal generators for GNSS constellations.
- Technology Demonstration Payloads:Experimental instruments validating novel sensing or processing architectures.
Communication payloads dominate installed base. Remote sensing payloads are where expansion concentrates.
Technology:
Cost tiers separate mature radio frequency systems from emerging optical and radar modalities with steep qualification expenses.
- Radio Frequency:Established transponder and antenna systems for bent-pipe signal relay. Volume demand from geostationary operators in the United States and European institutional programs sustains production lines for C-band and Ku-band hardware with proven radiation tolerance.
- Synthetic Aperture Radar:Active microwave systems generating terrain imagery independent of illumination or weather. Defense departments in the United States, Germany, and Israel drive procurement for tactical ISR where cloud cover disables optical alternatives.
- Optical:Laser communication terminals for inter-satellite links.
- Hyperspectral Imaging:Sensors capturing contiguous spectral bands for material identification.
- Infrared Sensors:Thermal detection systems for missile warning and environmental monitoring.
Radio frequency systems anchor revenue. Optical terminals are gaining share fastest.
Application:
Customer maturity separates established telecommunications from emerging disaster response use cases with irregular procurement patterns.
- Telecommunications:Broadband and narrowband relay services for consumer and enterprise connectivity. Commercial constellation operators in the United States and United Kingdom deploy thousands of small satellites with miniaturized payloads for global internet coverage.
- Earth Observation:Imagery and geospatial data services for agriculture, insurance, and defense. Government buyers in the United States and France contract directly for synthetic aperture radar and hyperspectral packages, bypassing traditional prime integrators.
- Space Science:Astronomy and solar physics research missions.
- Positioning and Timing:GNSS augmentation and alternative PNT services.
- Disaster Management:Rapid-response imaging and communication restoration.
Telecommunications commands the largest program values. Earth observation shows the steepest expansion trajectory.
End User:
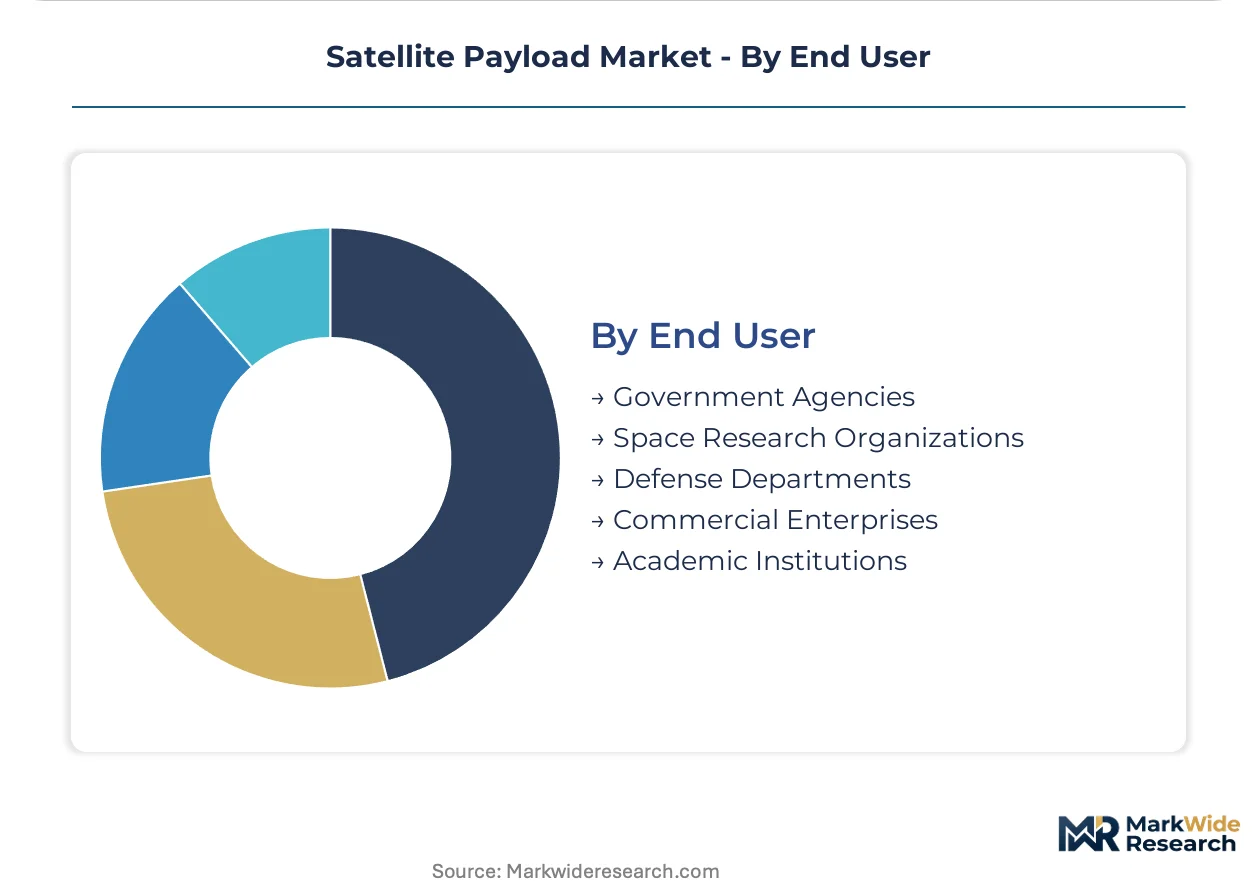
Procurement concentration distinguishes defense buyers with rapid acquisition pathways from academic institutions with extended funding cycles.
- Defense Departments:Classified payload integration for tactical communications and intelligence. The United States Space Force and NATO allies compress procurement timelines through proliferated warfighter architecture contracts that separate payload awards from bus integration.
- Government Agencies:Civilian earth observation and space science missions. NASA and ESA fund large geostationary platforms and deep-space instruments with multi-year appropriations and stringent radiation-hardening requirements.
- Commercial Enterprises:Constellation operators and data analytics firms.
- Space Research Organizations:National laboratories and technology development centers.
- Academic Institutions:University-led CubeSat and small satellite missions.
Defense departments anchor near-term procurement volume. Commercial enterprises are where capacity expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States payload suppliers extract pricing premiums from defense contracts that European competitors cannot match under ESA cost-cap rules. This asymmetry concentrates high-margin manufacturing in Colorado and California while pushing volume production toward lower-cost jurisdictions.
United States
Space Force proliferated warfighter architecture contracts and NASA deep-space missions drive procurement of radiation-hardened processors and synthetic aperture radar packages. The FCC mandates collision avoidance systems and ninety percent deorbit reliability for satellites above six hundred kilograms, adding compliance costs to California and Colorado manufacturing clusters where small satellite builders redesign propulsion modules.
Germany
Tactical ISR requirements from the Bundeswehr and precision agriculture analytics sustain demand for all-weather radar imaging. ESA procurement rules cap program costs and mandate cross-border supplier participation, compressing margins for Bavaria-based payload integrators serving institutional science missions.
France
CNES earth observation programs and military communications modernization fund development of optical inter-satellite links and quantum encryption modules. ITAR restrictions fragment transatlantic technology transfer, forcing Toulouse-area manufacturers to source radiation-hardened components through licensed European foundries rather than U.S. suppliers.
United Kingdom
Commercial constellation operators in Surrey and Oxfordshire deploy miniaturized phased-array antennas for broadband coverage. The UK Space Agency's national space strategy directs funding toward in-orbit servicing capabilities, opening markets for refuelable payload architectures among Harwell Campus ventures.
India
ISRO's commercial arm and private sector entrants build domestic integration facilities to serve regional constellation operators. The country's national space regulator streamlines licensing for non-geostationary systems while the PLI scheme incentivizes local manufacturing of satellite subsystems in Gujarat and Karnataka production zones.
Satellite Payload Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in a structure where defense primes consolidate classified payload awards while commercial suppliers fragment across constellation niches. The vendor base separates into three archetypes: vertically integrated aerospace conglomerates, institutional-backed European champions, and agile commercial constellation operators. Capacity expansion and strategic partnerships dominate competitive moves as players seek to secure launch cadence and spectrum access.
Within the defense prime tier, Northrop Grumman Corporation and Raytheon Technologies Corporation exemplify classified payload integration capabilities. Thales Alenia Space occupies a position representing European institutional-backed champions sustained by ESA and member state programs. SpaceX anchors the commercial operator archetype through in-house manufacturing scale and captive launch capacity that compresses deployment timelines.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Thales Alenia Space |
| SpaceX |
| Raytheon Technologies Corporation |
| The Boeing Company |
| Airbus |
| L3Harris Technologies Inc |
| Maxar Technologies Corporation |
| Lockheed Martin Corporation |
| Others |
Cost & Logistics Intelligence
Single-source dependency on radiation-hardened foundry capacity in the United States and Europe determines both pricing tier spreads and supply chain shape. Defense buyers absorb premium pricing for ITAR-compliant components while commercial constellation operators face margin compression from limited alternative sourcing.
Pricing Analysis
Defense procurement departments anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ITAR certification grade and radiation-hardening qualification level. Cost compression in the commercial tier is intensifying because SpaceX's captive manufacturing sets reference pricing for constellation-scale procurement. Academic and research institutions demonstrate the highest price sensitivity, while classified Space Force programs show minimal elasticity.
Supply Chain Analysis
Tariff exposure between the United States and European Union fragments transatlantic component flows. Geographic supply concentration centers on the United States, Germany, and France for radiation-hardened semiconductors, precision antennas, and optical terminals. Raw material dependencies draw from gallium arsenide substrates, rare earth magnets, and specialty alloys. Single-source vulnerability pervades space-qualified foundry capacity. Distribution runs through prime contractor integration facilities and direct commercial relationships with constellation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The satellite payload market faces substitution pressure from terrestrial 5G networks and high-altitude platform stations that threaten to displace certain communication payload applications. Incumbents must navigate this threat while defending proprietary positions in classified defense and deep-space science segments.
For Market Incumbents: Entrench positions through backward integration into radiation-hardened semiconductor foundry capacity and exclusive long-term supply agreements with Space Force proliferated warfighter architecture programs. Lockheed Martin Corporation and Northrop Grumman Corporation demonstrate this model through classified payload integration capabilities that emerging competitors cannot replicate without security clearance infrastructure.
For New Entrants and Emerging Players: Pursue white-space opportunities in commercial optical inter-satellite links and modular refuelable payload architectures for ESA in-orbit servicing mandates. India's domestic manufacturing localization initiative offers the most penetrable geography for regional constellation operators seeking non-ITAR supply chains. A direct component supplier model bypassing traditional prime integrators provides the strongest go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors component specialists with software-defined architectures and quantum encryption capabilities. Long-term viability over the coming decade hinges on differentiation from commoditized radio frequency transponder production. Acquisition targets should demonstrate proven flight heritage and existing relationships with constellation operators. The signal to monitor is Space Force contract disaggregation velocity as an inflection indicator for direct commercial payload procurement trends.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Payload Architecture | Enables post-launch reconfiguration for Space Force jam-resistant waveform requirements. |
| Radiation-Hardened Foundry Investment | Secures captive supply of space-qualified semiconductors for high-volume constellation programs. |
| Optical Inter-Satellite Link Deployment | Integrates quantum encryption modules for ultra-secure government backbone networks. |
| Modular Refuelable Payload Design | Aligns with ESA debris remediation mandates opening European servicing markets. |
| India Manufacturing Localization | Captures PLI scheme incentives and serves regional operators outside ITAR jurisdiction. |
Research Approach
The analysis maps communication, remote sensing, and navigation payload sub-sectors, each validated through payload engineering directors, constellation procurement leads, and defense program managers. Primary interviews with satellite bus integrators, radiation effects specialists, and FCC licensing attorneys combined with secondary validation from SEC filings, FCC licensing databases, ESA procurement records, and NASA contract announcements. Bottom-up unit economics for constellation deployment programs triangulate against top-down addressable market sizing from government appropriations and commercial operator capex disclosures.
Assumptions held fixed include current ITAR classification thresholds, ESA cost-cap rules, and FCC debris mitigation reliability standards; variables tested include launch cost trajectories, radiation-hardened foundry capacity expansion, and dual-use classification boundary shifts. Segmentation dimensions modeled encompass product type, technology modality, application vertical, and end-user procurement concentration across the projection horizon. CAGRs derive from deployment schedule analysis and replacement cycle assumptions for geostationary versus proliferated low-Earth orbit architectures. Industry-specific forecast inputs include Space Force contract award velocity and Starlink payload refresh cadence.
Macroeconomic conditions sit as an overlay; deviation in defense appropriation levels, launch vehicle availability, or semiconductor foundry investment cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and technology transition timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
North America Military Satellite Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Argentina Satellite Imagery Services Market
Satellite
Germany Satellite Imagery Services Market
Satellite
Small Satellite Market
Satellite
Asia-Pacific Satellite Bus Market
Satellite
United States Satellite Communications Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
US Remote Sensing Technology Market
Satellite
China Satellite Connectivity Market
Satellite
South Korea Satellite Communication Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Asia-Pacific Satellite Manufacturing and Launch Systems Market
Satellite
Global Satellite Propulsion System Market
Satellite
High-Throughput Satellite Market