
 Saudi Arabia Satellite Imagery Services Market | 2026-2036
Saudi Arabia Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Satellite Imagery Services Market Insights
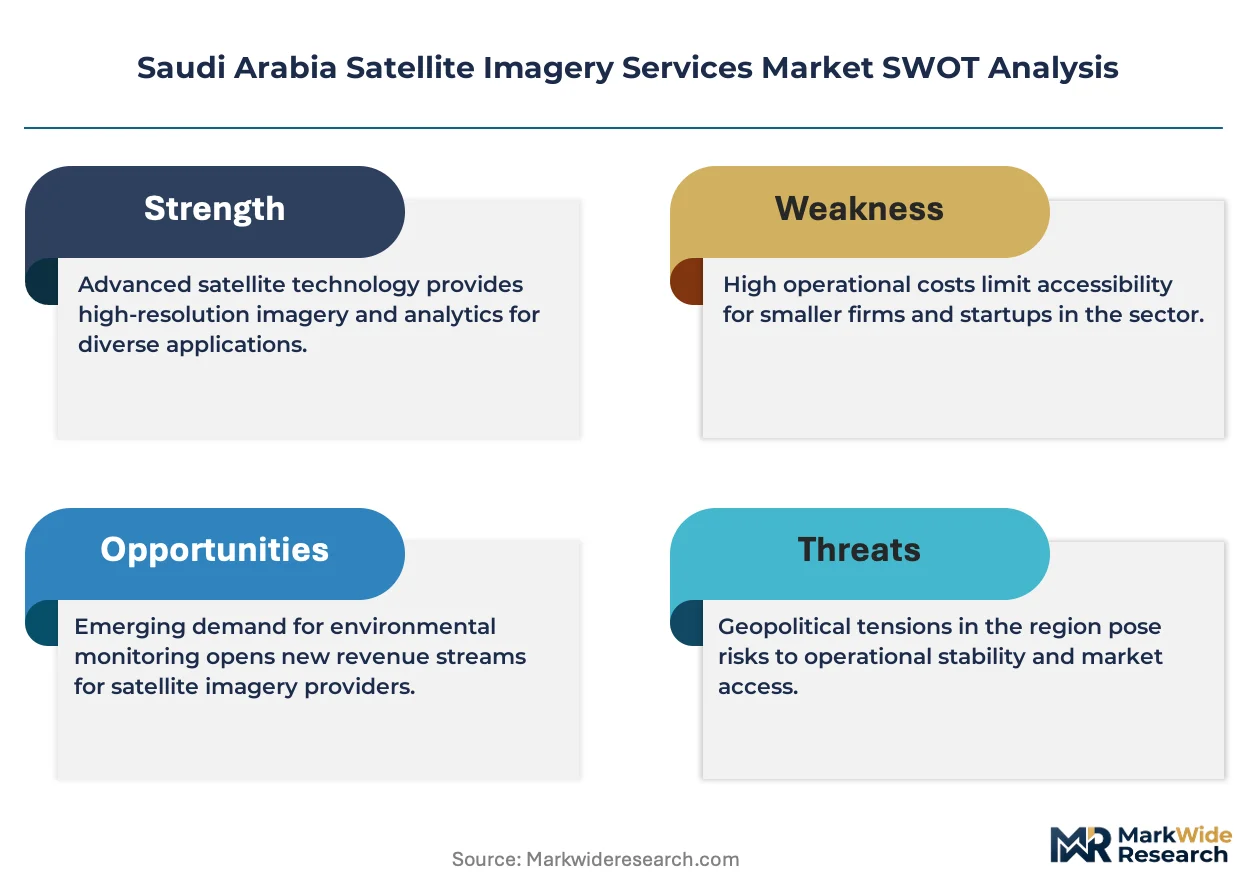
Sub-meter resolution imagery is reorganizing competitive dynamics in Saudi Arabia. Maxar Technologies leverages its constellation scale to anchor government contracts. Airbus sustains technology leadership through synthetic aperture radar capabilities. Planet Labs PBC differentiates via daily revisit frequency for change detection applications.
Satellite imagery services encompass the acquisition, processing, and distribution of Earth observation data captured by orbiting platforms, with spatial resolutions ranging from 30-centimeter panchromatic to 10-meter multispectral bands, primarily serving cadastral mapping, resource exploration, and strategic surveillance functions. Orthophoto and 3D mapping services command premium pricing due to engineering-grade accuracy requirements in NEOM and Red Sea Project developments. Defense and oil and gas applications absorb the majority of procurement budgets, while environmental monitoring segments gain traction from Saudi Green Initiative compliance obligations.
The Saudi Space Commission and the Communications, Space and Technology Commission shape licensing frameworks for foreign imagery providers, with domestic data residency requirements tightening market access for non-local operators. SFDA coordinates health-related geospatial applications, while the National Center for Vegetation Cover Development mandates satellite-derived assessments for afforestation programs. Stakeholders must weigh localization partnerships against direct operational licenses as regulatory thresholds for sovereign data control intensify.
Market Dynamics
The Saudi Space Commission's localization mandates are restructuring market access, forcing foreign imagery providers into domestic joint ventures or technology transfer agreements to retain government contract eligibility.
Growth Catalysts
- NEOM megaproject cadastral demands:The giga-development's engineering-grade mapping requirements are pulling sub-meter resolution contracts from international constellation operators into Saudi procurement pipelines.
- Saudi Green Initiative afforestation mandates:The National Center for Vegetation Cover Development requires satellite-derived biomass assessments for carbon sequestration verification across the Kingdom's desert restoration zones.
- Synthetic aperture radar penetration:All-weather imaging capabilities are unlocking year-round pipeline monitoring contracts for Aramco's Eastern Province infrastructure corridors where optical sensors face dust-storm limitations.
Market Restraints
- Domestic data residency requirements:The Communications, Space and Technology Commission's sovereign data control rules impose server localization costs that compress margins for non-Saudi operators.
- Launch capacity concentration:Ride-share access to sun-synchronous orbits is bottlenecked through US and European launch providers, creating constellation replenishment delays for regional service tiers.
- Optical sensor substitution by aerial drones:Lower-altitude UAV platforms are capturing sub-10cm resolution for Red Sea coastal developments at price points satellite operators cannot match.
Strategic Opportunities
- Red Sea Project tourism infrastructure:The undeveloped coastal zone lacks legacy geospatial archives, creating first-mover advantage for hyperspectral providers establishing baseline environmental monitoring.
- AI-ML fusion with SAR data:Automated change-detection algorithms trained on Saudi desert geologies are opening subscription revenue models for construction progress monitoring.
- SFDA health-geospatial convergence:Disease vector mapping and hospital catchment analysis represent untapped procurement verticals as the health regulator builds spatial epidemiology capabilities.
Industry Challenges
- Geospatial analyst talent scarcity:Domestic universities produce insufficient remote sensing specialists to staff localization requirements, forcing providers to import expertise on restricted visa categories.
- Multi-constellation integration complexity:Government clients demand fused optical-SAR-thermal products requiring proprietary preprocessing pipelines that extend contract fulfillment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Satellite Imagery Services Market |
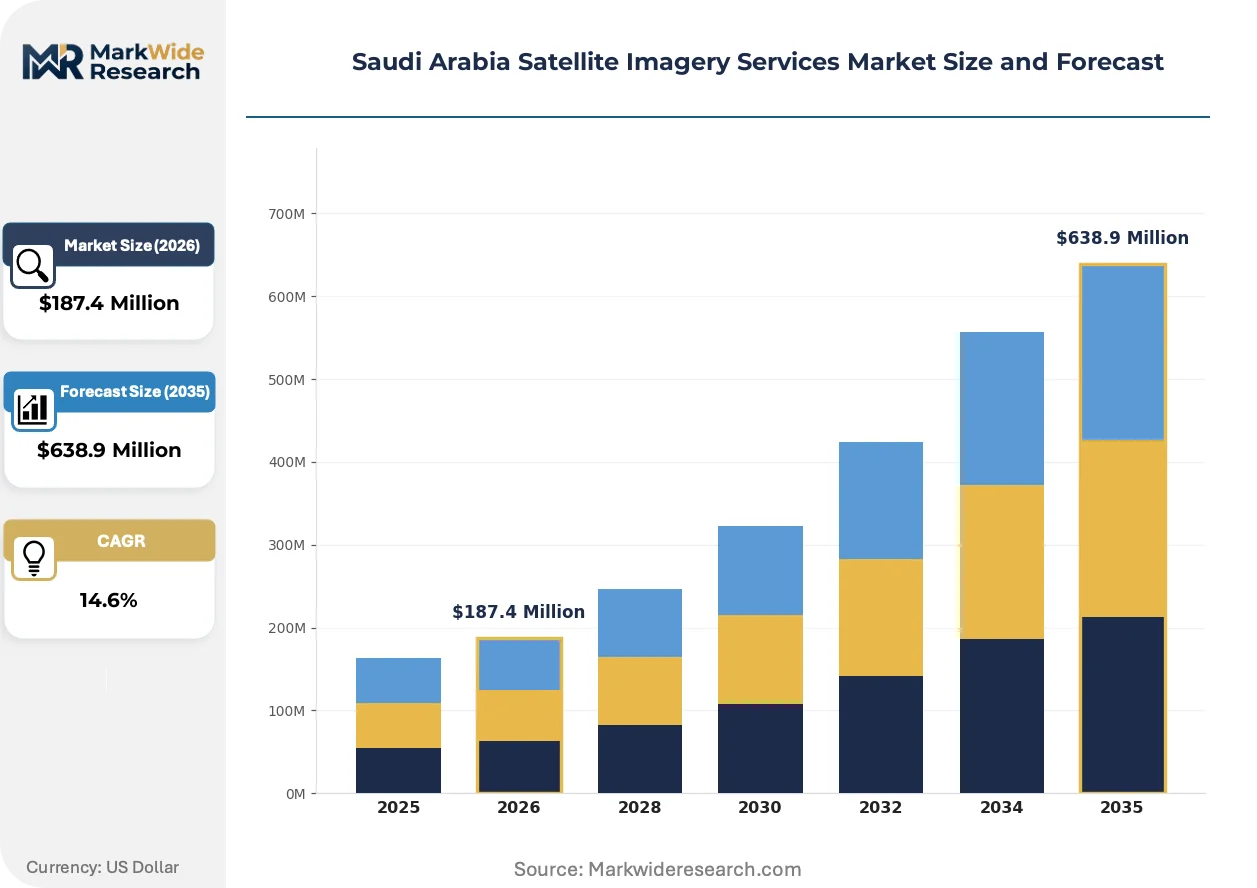
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Orthophoto, 3D Mapping, Aerial Surveying, Remote Sensing Application: Agriculture, Urban Planning, Environmental Monitoring, Defense Technology: Multispectral, Hyperspectral, Radar, LiDAR End User: Government Agencies, Oil & Gas, Construction, Research Institutions |
| Companies Covered | Airbus, Thales, Northstar Saudi Arabia, Space Imaging Middle East, Leonardo S.P.A., Maxar Technologies, Planet Labs PBC, NOVAsat, Serco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Satellite Imagery Services Market Trends and Innovations
Resolution-performance tradeoffs are fragmenting procurement patterns across Saudi Arabia's imagery market, with buyers separating premium analytics from commodity data feeds.
Very high resolution electro-optical sensors are bifurcating the government procurement landscape. The Saudi Space Commission's direct-sensing satellite program is capturing 70cm panchromatic data for defense applications. Commercial providers are retreating toward 1-5 meter resolution bundles for agricultural and insurance clients. This technological split is compressing mid-tier pricing bands as buyers self-select into sovereign-class or commercial-grade service tiers.
Saudi Arabia's domestic space law framework is tightening foreign operator licensing conditions. The Communications, Space and Technology Commission now requires in-country ground station presence for real-time tasking authority. European and American constellation owners are establishing Riyadh-based subsidiaries to maintain contract eligibility. Defense and intelligence applications face the strictest data sovereignty controls, with raw imagery prohibited from offshore processing.
Subscription-based monitoring contracts are displacing one-time image purchases across Saudi infrastructure operators. Aramco and Ma'aden are locking multi-year analytics partnerships with guaranteed revisit frequencies for asset surveillance. This procurement evolution favors providers with guaranteed capacity over spot-market imagery brokers. The Eastern Province's dense energy infrastructure cluster is exhibiting the fastest contract structure conversion.
Saudi Arabia Satellite Imagery Services Market Segmentation
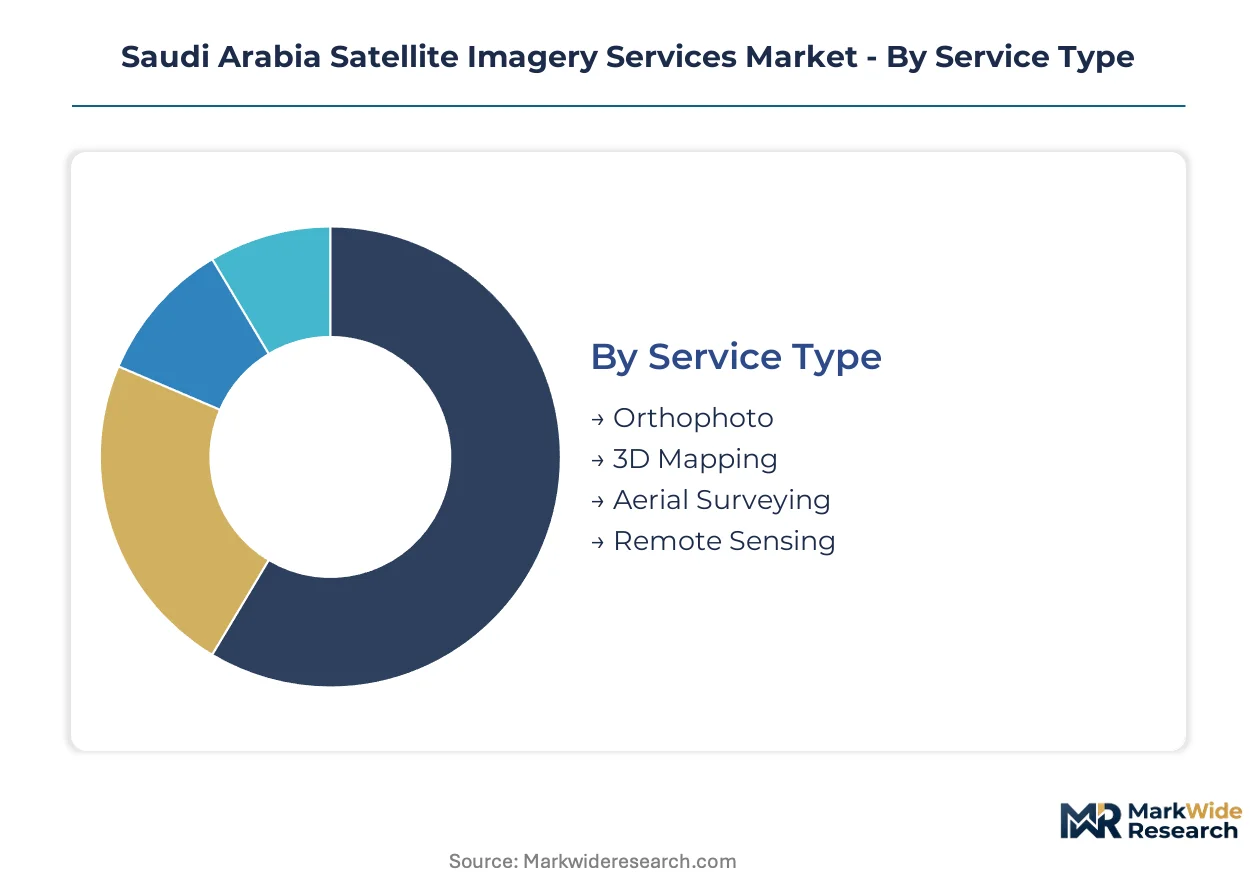
Segmentation in Saudi Arabia's satellite imagery market reveals how regulatory mandates and infrastructure priorities reshape procurement patterns. The Communications, Space and Technology Commission's data residency requirements create divergent compliance costs across service tiers, while NEOM and Red Sea Project investments concentrate demand in specific technical categories.
Service Type:
The Communications, Space and Technology Commission imposes distinct licensing thresholds on each service tier, with real-time tasking authority reserved for operators maintaining domestic ground stations.
- Orthophoto:Geometrically corrected aerial photographs deliver engineering-grade accuracy for cadastral mapping. NEOM's giga-development contracts absorb the majority of high-resolution orthophoto capacity, with Saudi Space Commission localization mandates forcing foreign providers into Riyadh-based joint ventures.
- 3D Mapping:Stereo photogrammetry and interferometric SAR generate digital elevation models for construction progress monitoring. The Eastern Province's dense energy infrastructure cluster exhibits the fastest contract structure conversion toward multi-year analytics partnerships with guaranteed revisit frequencies.
- Aerial Surveying:Manned aircraft and UAV platforms capture sub-10cm resolution for coastal developments at price points satellite operators cannot match.
- Remote Sensing:Satellite-derived data products span vegetation indices, thermal signatures, and change detection analytics for environmental compliance.
Orthophoto handles the majority of throughput; 3D Mapping is expanding most quickly on contract value.
Application:
Cost tier differentiation separates sovereign-priority applications from commercial-grade deployments, with defense and energy budgets commanding premium pricing.
- Defense:Sub-meter resolution imagery supports strategic surveillance and border monitoring. The Saudi Space Commission's direct-sensing satellite program captures 70cm panchromatic data for classified applications, compressing commercial provider access to this segment.
- Oil & Gas:Pipeline surveillance and subsurface monitoring absorb substantial procurement budgets. Synthetic aperture radar penetration unlocks year-round monitoring contracts for Aramco's Eastern Province infrastructure corridors where optical sensors face dust-storm limitations.
- Urban Planning:Municipal authorities utilize medium-resolution bundles for zoning and transportation corridor design.
- Agriculture:Precision farming applications rely on multispectral vegetation indices for irrigation optimization.
Defense commands the highest unit pricing; Oil & Gas shows the steepest expansion trajectory on volume.
Technology:
Volume concentration favors established sensor modalities, while emerging technologies gain traction through specific performance advantages in desert geologies.
- Radar:Synthetic aperture radar delivers all-weather, day-night imaging capability through cloud and dust penetration. Aramco's pipeline monitoring contracts drive the fastest adoption curve as operators replace seasonal optical acquisition with guaranteed year-round coverage.
- Multispectral:Discrete wavelength bands support vegetation mapping and mineral exploration. The National Center for Vegetation Cover Development mandates satellite-derived biomass assessments for Saudi Green Initiative compliance, anchoring steady demand.
- Hyperspectral:Continuous spectral signatures enable material identification and environmental baseline establishment for undeveloped zones.
- LiDAR:Active laser ranging generates precise elevation data for engineering applications with accuracy requirements exceeding photogrammetric methods.
Multispectral handles the majority of throughput; Radar is gaining share fastest on new contract wins.
End User:
Customer type determines procurement channel access, with government agencies operating through distinct tender processes that privilege domestic partnership structures.
- Government Agencies:The Saudi Space Commission and Communications, Space and Technology Commission coordinate sovereign imagery requirements through localized procurement frameworks. Defense and intelligence applications face strictest data sovereignty controls, with raw imagery prohibited from offshore processing.
- Construction:NEOM and Red Sea Project developers demand engineering-grade accuracy with compressed delivery timelines. Subscription-based monitoring contracts displace one-time image purchases across major infrastructure operators.
- Oil & Gas:Aramco and Ma'aden lock multi-year analytics partnerships requiring guaranteed capacity over spot-market flexibility.
- Research Institutions:Academic users access archived imagery through subsidized licensing arrangements with limited real-time tasking privileges.
Government Agencies handle the majority of throughput; Construction is climbing the fastest on project pipeline expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement in Riyadh absorbs premium-priced sub-meter imagery with minimal price elasticity, while agricultural users in peripheral regions exhibit acute sensitivity to per-kilometer acquisition costs. This demand bifurcation concentrates vendor investment in the capital corridor while compressing service margins elsewhere.
Riyadh
The capital anchors the Kingdom's sovereign imagery demand through Saudi Space Commission headquarters and defense ministry procurement. CSTC licensing mandates require foreign operators to maintain domestic ground stations here, forcing joint venture structures with local technology partners. NEOM project coordination offices in Riyadh pull engineering-grade orthophoto contracts into centralized tender processes.
Eastern Province
Aramco's pipeline surveillance requirements dominate commercial imagery volume, with synthetic aperture radar contracts replacing seasonal optical acquisition. The Dammam-Khobar industrial corridor hosts the densest energy infrastructure cluster, driving multi-year subscription partnerships with guaranteed revisit frequencies. Dust-storm geologies here disqualify optical sensors for year-round monitoring applications.
Western Region
Jeddah's port logistics and Red Sea Project tourism developments generate cadastral mapping demand at compressed delivery timelines. Aerial drone substitution threatens satellite operators on coastal sub-10cm resolution requirements where lower-altitude platforms underprice orbital acquisition. Makkah municipality utilizes medium-resolution bundles for transportation corridor planning around religious infrastructure.
NEOM Northwest
The giga-development's undeveloped status creates first-mover advantage for hyperspectral baseline establishment without legacy archive competition. Engineering-grade accuracy requirements for THE LINE and Oxagon developments absorb the majority of high-resolution orthophoto national capacity. Domestic data residency rules force all raw processing into Kingdom-based servers for this strategic zone.
Saudi Arabia Satellite Imagery Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with constellation scale operators anchoring government contracts while agile analytics specialists capture subscription revenue from infrastructure operators. The vendor base organizes around three strategic archetypes: sovereign-class providers with defense clearance, commercial constellation operators with guaranteed capacity, and domestic joint ventures navigating CSTC localization mandates. Competitive dynamics center on M&A activity consolidating analytics capabilities and strategic partnerships securing ground station presence.
Among constellation-scale operators, Maxar Technologies and Planet Labs PBC exemplify divergent technology-cost positioning, with the former representing sovereign-class resolution capabilities and the latter anchoring high-frequency commercial monitoring. Airbus occupies a position spanning both archetypes through synthetic aperture radar differentiation. Domestic market access for these operators depends on joint venture structures with Saudi technology partners to satisfy CSTC licensing thresholds.
| Leading Market Players |
|---|
| Airbus |
| Thales |
| Northstar Saudi Arabia |
| Space Imaging Middle East |
| Leonardo S.P.A. |
| Maxar Technologies |
| Planet Labs PBC |
| NOVAsat |
| Serco |
| Others |
Pricing and Supply Chain Analysis
Aerial drone substitution for coastal cadastral work is simultaneously compressing satellite pricing bands in the Western Region and shifting procurement gravity toward Riyadh-based joint ventures that can absorb CSTC localization costs. This input replacement dynamic forces constellation operators to retreat toward guaranteed-revisit subscription models or surrender sub-10cm resolution markets entirely.
Pricing Analysis
Multi-year analytics partnerships with guaranteed revisit frequencies now anchor lifetime value for Aramco and Ma'aden procurement teams. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-grade sub-meter tasking from commercial agricultural bundles. Cost compression in the mid-resolution tier intensifies because domestic data residency rules impose server localization overhead. Government agencies exhibit minimal price sensitivity; peripheral agricultural users demonstrate acute per-kilometer acquisition cost consciousness.
Supply Chain Analysis
The United States and France anchor optical sensor manufacturing and synthetic aperture radar payload production for Saudi-bound constellations. Ground segment hardware draws from German precision engineering; launch services rest on US and European ride-share providers. Single-source vulnerability concentrates in sun-synchronous orbit access, where replenishment delays threaten guaranteed capacity contracts. Distribution runs through Riyadh-based joint ventures satisfying CSTC real-time tasking authority requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's satellite imagery market sits at a regulatory inflection where CSTC localization mandates are forcibly restructuring competitive access before domestic constellation capacity matures.
For Market Incumbents: Fortify ground station presence in Riyadh through joint venture structures that preserve contract eligibility under tightening data sovereignty rules. Deepen backward integration into SAR preprocessing pipelines to compress fulfillment timelines for multi-constellation fusion demands. Defend against aerial drone substitution by anchoring guaranteed all-weather coverage contracts Aramco cannot replicate with lower-altitude platforms. For New Entrants and Emerging Players: Anchor in the Red Sea Project's undeveloped coastal zone where hyperspectral baseline establishment offers first-mover advantage without legacy archive competition. Target SFDA health-geospatial convergence as the most penetrable vertical, with disease vector mapping representing untapped procurement. Pursue AI-ML fusion partnerships with domestic universities to overcome geospatial analyst talent scarcity. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors analytics specialists with proprietary change-detection algorithms over pure-play constellation operators. Long-term viability hinges on subscription revenue durability rather than spot-image transaction volume. Monitor CSTC licensing threshold adjustments as the signal indicating when domestic joint venture structures become mandatory rather than elective.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Joint Venture Formation | CSTC licensing mandates require Riyadh-based ground stations for real-time tasking authority. |
| SAR Preprocessing Pipeline Investment | Automated change-detection algorithms unlock subscription revenue from Aramco infrastructure monitoring. |
| AI-ML Analytics Partnership | Desert geology-trained algorithms address construction progress monitoring demand from NEOM developers. |
| Hyperspectral Baseline Establishment | Undeveloped Red Sea Project zones lack legacy archives, creating first-mover data ownership. |
| University Talent Pipeline Development | Domestic remote sensing specialist scarcity forces providers to import expertise on restricted visa categories. |
Research Methodology
The analysis maps orthophoto, 3D mapping, aerial surveying, and remote sensing service tiers, each validated through satellite operations directors, CSTC regulatory affairs specialists, Aramco geospatial procurement managers, and NEOM project planning officers. Primary interview findings cross-reference Saudi Space Commission policy documents, Communications Space and Technology Commission licensing records, National Center for Vegetation Cover Development afforestation assessments, and SFDA health-geospatial program disclosures. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Consistency checks validated volume and value outputs against external benchmark data across the projection horizon. The analytical framework models technology modality, application vertical, end-user type, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from fitted growth curves incorporating NEOM project pipeline visibility, Saudi Green Initiative mandate timelines, and Aramco infrastructure surveillance contract renewal patterns.
Decision-makers should treat outputs as directional under sustained CSTC localization enforcement and domestic constellation launch schedules; material deviation in regulatory pace or sovereign satellite deployment would warrant model refresh. Recalibration cycles align with material shifts in Saudi Space Commission direct-sensing program milestones and CSTC data residency rule amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Latin America Satellite Connectivity Market
Satellite
UK Satellite Imagery Services Market
Satellite
France Satellite Imagery Services Market
Satellite
Japan Satellite Connectivity Market
Satellite
Satellite Connectivity Market
Satellite
Satellite Bus Market
Satellite
Satellite Sensor Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
Global Satellite Based Earth Observation Market
Satellite
Satellite Manufacturing Market
Satellite
United Arab Emirates Satellite-Based Earth Observation Market
Satellite
ASEAN Satellite Imagery Services Market
Satellite
China Satellite Imagery Services Market
Satellite
Argentina Satellite-Based Earth Observation Market
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
South Korea Satellite Communication Market