
 Satellite Parts and Components Market | 2026-2036
Satellite Parts and Components Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Parts and Components Market Insights
The EU Green Deal's space sustainability requirements is expanding the addressable market for debris-compliant satellite components. Airbus SE leverages its vertically integrated European manufacturing base to supply radiation-hardened solar arrays for institutional programs. Northrop Grumman Corporation anchors US defense demand through specialized payload integration for protected communications. Thales Group competes across dual-use markets, combining civilian earth observation with signals intelligence capabilities.
Satellite parts and components encompass the electromechanical, electronic, and structural subsystems that enable spacecraft to generate power, maintain attitude, transmit data, and execute orbital maneuvers; these assemblies typically operate across temperature extremes from minus 150 to plus 120 degrees Celsius while withstanding cumulative radiation doses measured in megarads. Propulsion systems and solar arrays command the largest share of product-level value, reflecting the energy-density and delta-v requirements of extended missions and orbital station-keeping. Communication and earth observation technologies are outpacing navigation in growth velocity, driven by constellations requiring high-throughput inter-satellite links and synthetic aperture radar payloads.
FCC orbital debris mitigation rules, EU Space Surveillance and Tracking standards, and ISO 24113 space debris mitigation requirements collectively mandate design-for-demise protocols, propellant passivation, and post-mission disposal reliability above 90 percent. These frameworks elevate qualification costs for new entrants while favoring incumbents with established environmental testing heritage. Stakeholders must monitor evolving national licensing regimes and assess whether captive manufacturing or supplier diversification best addresses compliance fragmentation across jurisdictions.
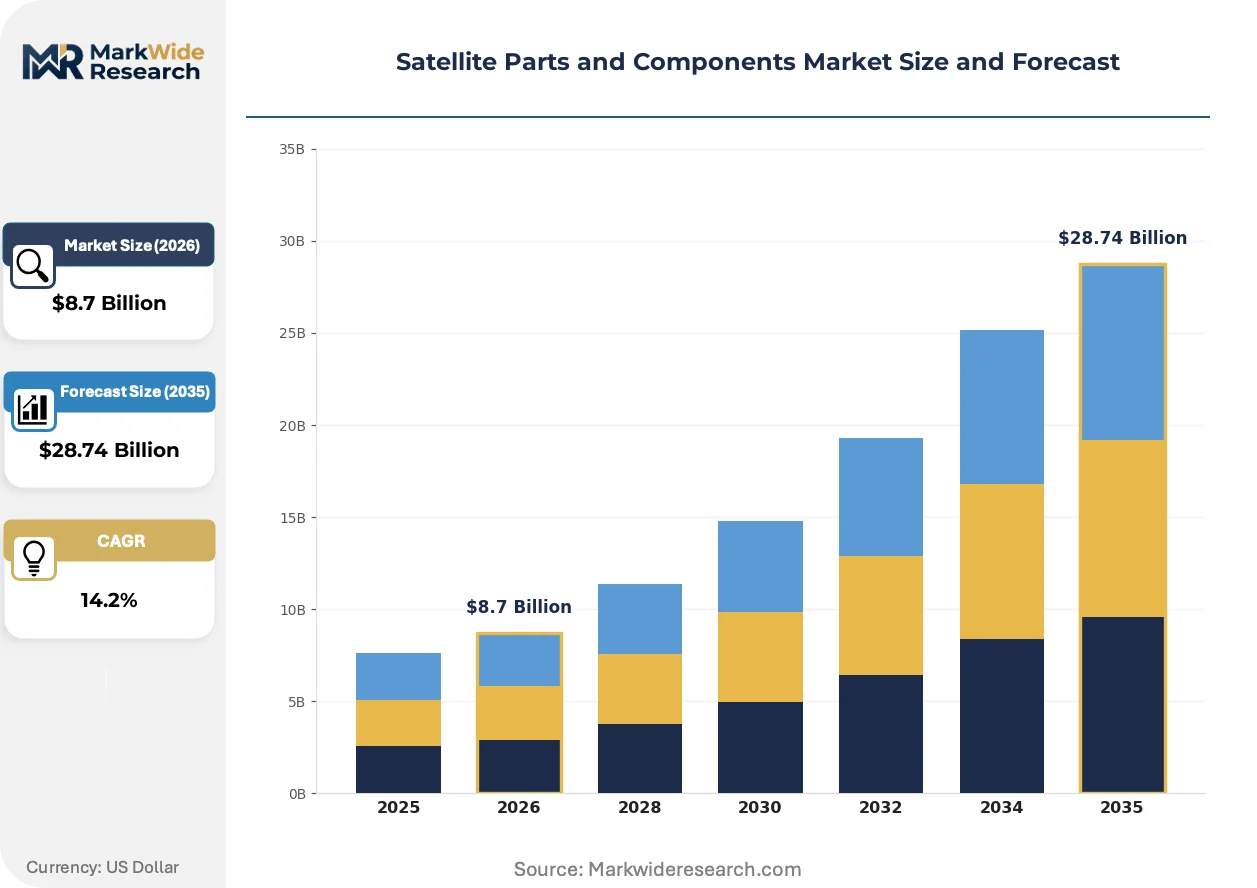
Market Dynamics
Orbital debris mitigation mandates are compressing design cycles and elevating qualification thresholds for satellite parts and components, forcing manufacturers to integrate passive de-orbit mechanisms and demisability protocols into baseline architectures.
Growth Catalysts
- Mega-constellation deployment:Commercial operators in the United States and China are procuring standardized, radiation-hardened subsystems at volume scale for low Earth orbit broadband networks.
- FCC orbital debris rules:The United States regulator now mandates 90% post-mission disposal reliability, creating pull for propulsion systems with verified passivation capabilities.
- Electric propulsion maturation:Hall-effect and gridded ion thrusters are replacing chemical systems for station-keeping, reducing propellant mass fractions and extending mission lifespans.
Market Restraints
- Supply concentration in solar cell substrates:Germanium and gallium arsenide wafer production clusters in China and the United States, exposing procurement to export control volatility.
- Radiation-hardened semiconductor foundry scarcity:Qualified fabrication lines for space-grade integrated circuits number fewer than twelve worldwide, constraining throughput for new entrants.
- REACH compliance burden:The European framework restricts cadmium and hexavalent chromium in surface coatings, forcing reformulation of thermal control materials and connector platings.
Strategic Opportunities
- In-orbit servicing and manufacturing:NASA and ESA demonstration missions are validating robotic refueling and component replacement, opening aftermarket revenue streams for modular subsystems.
- India's Gaganyaan and commercial launch expansion:ISRO procurement programs and private launch vehicle development are creating captive demand for indigenous component qualification.
- Synthetic aperture radar convergence:Integration of phased-array antennas with software-defined radio payloads enables dual-use earth observation platforms serving defense and climate monitoring agencies.
Industry Challenges
- Radiation effects engineering talent scarcity:Specialized expertise in single-event upset modeling and shielding optimization resides primarily with legacy defense contractors and national laboratories.
- Qualification timeline compression:Commercial constellation schedules demand environmental testing cycles of 12-18 months versus traditional 36-month government program timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Parts and Components Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Actuators, Antennae, Solar Arrays, Propulsion Systems Technology: Communication, Remote Sensing, Navigation, Earth Observation End User: Government, Aerospace, Defense, Commercial Application: Telecommunication, Weather Monitoring, Scientific Research, Surveillance |
| Companies Covered | Airbus SE, RTX Corporation, Lockheed Martin Corporation, Mitsubishi Electric Corporation, Maxar Technologies Inc, Northrop Grumman Corporation, Thales Group, Raytheon, The Boeing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Parts and Components Market Trends and Innovations
Active electronically scanned arrays and software-defined payloads are displacing fixed-beam hardware, enabling frequency reconfiguration and beam steering without mechanical articulation.
Optical inter-satellite links using laser communication terminals are decentralizing ground infrastructure dependency for constellation data routing. Operators such as Space Development Agency and commercial broadband providers are deploying these terminals across medium and low Earth orbits. The shift compresses latency and reduces gateway density requirements, altering the value distribution between space and ground segments.
The EU Space Surveillance and Tracking framework now mandates collision avoidance maneuver capability for all new spacecraft above 600 kg. Manufacturers must integrate autonomous navigation sensors and miniature propulsion units that were previously optional. French and German prime contractors are responding by qualifying European-sourced cold gas and resistojet thrusters to reduce dependency on non-European propulsion suppliers.
Consolidated procurement by mega-constellation operators is displacing fragmented national agency buying patterns. Buyers now negotiate multi-year, multi-satellite subsystem contracts with fixed pricing and volume commitments. This concentration is most visible in the United States, where Space Force and commercial broadband programs are converging on common technical standards for bus and payload interfaces.
Satellite Parts and Components Market Segmentation
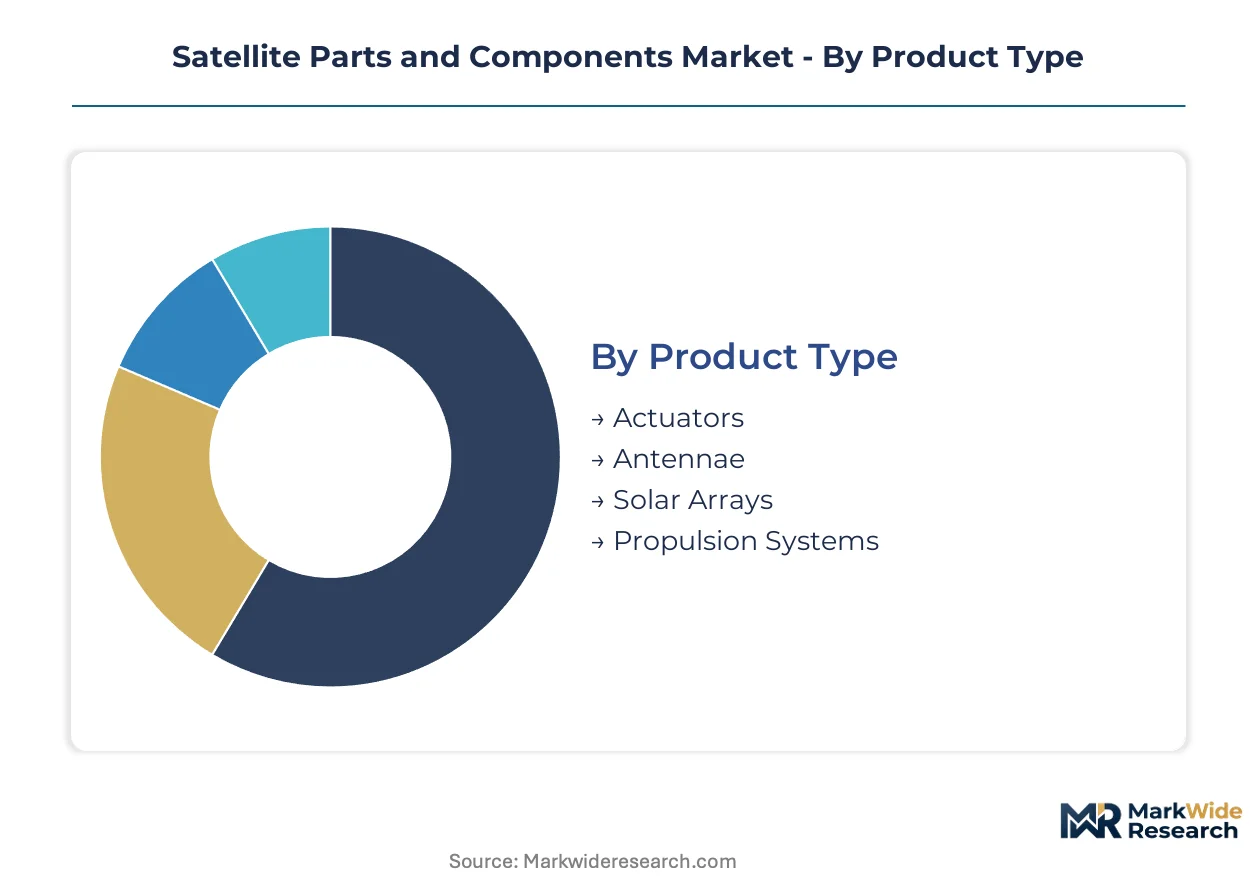
Segmentation in satellite parts and components reveals where capital deployment concentrates and which technical specifications command premium pricing. Distinct qualification requirements, radiation tolerance thresholds, and mission-critical reliability standards create sharp value differentiation across product categories and end-use applications.
Product Type:
Propulsion systems and solar arrays absorb the largest upfront capital commitments due to materials science complexity and environmental testing duration. Actuators and antennae require less foundry infrastructure but demand precision manufacturing heritage.
- Propulsion Systems:Hall-effect thrusters and gridded ion engines utilize xenon propellant and ceramic discharge chambers rated for multi-decade operational life. Demand concentrates in United States mega-constellation programs where FCC mandates 90% post-mission disposal reliability, forcing electric propulsion adoption for de-orbit capability.
- Solar Arrays:Triple-junction gallium arsenide cells bonded to germanium substrates deliver conversion efficiencies above 30% in geostationary orbits. Procurement clusters in France and Germany for institutional programs under ESA direction, with REACH compliance forcing reformulation of substrate bonding agents.
- Antennae:Phased-array architectures with gallium nitride power amplifiers enable electronic beam steering without mechanical gimbals.
- Actuators:Brushless DC motors with redundant winding configurations drive solar array deployment and antenna pointing mechanisms.
Most installed capacity flows through solar arrays. Expansion is steepest in propulsion systems.
Technology:
Application maturity determines which technology segments absorb qualification engineering resources versus commoditized volume production.
- Communication:Optical inter-satellite links and software-defined radios operating across Ka and V bands require radiation-hardened field-programmable gate arrays. United States Space Development Agency procurement drives volume for cross-linked mesh network terminals.
- Earth Observation:Synthetic aperture radar payloads with active electronically scanned arrays penetrate cloud cover for all-weather imaging. China's commercial remote sensing constellation expansion creates pull for indigenous radar component qualification.
- Remote Sensing:Multispectral and hyperspectral imagers demand cooled infrared detector arrays with cryocooler integration.
- Navigation:Atomic clock ensembles and signal generation electronics for GNSS augmentation services face stable demand from existing constellation replenishment cycles.
Communication technology carries the heaviest capital burden per satellite. Earth observation is climbing the fastest.
End User:
Procurement concentration shapes margin structures, with defense programs tolerating cost-plus pricing while commercial operators enforce fixed-price discipline.
- Defense:Protected communications payloads with anti-jam waveforms and nuclear-hardened electronics command qualification timelines exceeding 48 months. United States Space Force budgets prioritize supply chain security over unit cost minimization.
- Commercial:Broadband constellation operators in the United States and China negotiate multi-year subsystem contracts with volume commitments and technical standardization requirements.
- Government:Civil space agencies including ESA, NASA, and national programs procure through competitive tender with heritage requirements favoring established suppliers.
- Aerospace:Prime contractors integrate vertically sourced subsystems for proprietary bus architectures serving niche mission profiles.
Defense end users dominate value capture. Commercial procurement is scaling the fastest.
Application:
Mission duration and orbital environment dictate component specification tiers, with geostationary assets requiring 15-year lifespans versus 5-year replacement cycles for low Earth orbit broadband.
- Telecommunication:High-throughput satellites with digital transparent processors and flexible payload architectures demand regenerative onboard processing. India's NSIL commercialization and expanding Gaganyaan infrastructure create indigenous demand for Ku-band and Ka-band components.
- Surveillance:Signals intelligence and imagery collection platforms require low-observable thermal signatures and encrypted cross-links. French defense procurement programs under Direction Générale de l'Armement specifications drive dual-use component development.
- Weather Monitoring:Microwave sounders and imaging radiometers for meteorological agencies require calibration stability across temperature extremes.
- Scientific Research:Deep space probes and astronomy platforms prioritize mass minimization and extreme radiation tolerance for missions beyond Earth's magnetosphere.
Telecommunication application absorbs the greatest component volume. Surveillance is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Satellite component manufacturing traces its industrial lineage to Cold War-era defense procurement in the United States and Soviet-era space programs, with subsequent dispersion to Western Europe and East Asia as commercial launch markets liberalized.
United States
Space Force procurement programs and commercial mega-constellation operators drive demand for radiation-hardened subsystems and electric propulsion units. FCC orbital debris mitigation rules mandate 90% post-mission disposal reliability, elevating qualification requirements for new entrants. Manufacturing clusters concentrate in California, Colorado, and Virginia, where prime contractors maintain vertically integrated production lines for protected communications payloads.
China
State-owned satellite operators and emerging commercial launch ventures procure standardized subsystems for broadband and remote sensing constellations. GB standards and MIIT regulations govern component qualification for indigenous space programs. Production gravitates toward Beijing-Tianjin-Hebei and the Yangtze River Delta, where state-directed investment has built captive supply chains for solar cell substrates and propulsion thrusters.
France
ESA institutional programs and Direction Générale de l'Armement defense procurement anchor demand for dual-use earth observation and signals intelligence components. EU Space Surveillance and Tracking framework requirements mandate autonomous navigation capabilities for spacecraft above 600 kg. Toulouse and Paris-Saclay host prime contractor engineering centers and specialized subsystem suppliers serving European institutional markets.
Germany
REACH compliance burdens and ESA technical specifications drive reformulation of thermal control materials and connector platings for institutional satellite programs. Germanium wafer production for solar cell substrates clusters in Bavaria and Saxony, though raw material dependencies expose procurement to export control volatility. Munich and Bremen anchor propulsion system development for European orbital transfer vehicles.
India
ISRO's Gaganyaan crewed spaceflight program and NSIL commercialization initiatives create captive demand for indigenous component qualification. BIS standards and PLI scheme incentives support domestic manufacturing capacity for satellite subsystems. Bengaluru and Ahmedabad concentrate engineering talent and testing infrastructure for bus and payload integration serving national programs.
Satellite Parts and Components Market Competitive Landscape
Capital-heavy producers with captive foundry and environmental testing infrastructure compete with asset-light designers outsourcing fabrication to qualified suppliers. The market structure tilts toward consolidation at the prime contractor tier, with tier-two subsystem vendors facing volume pressure from mega-constellation procurement concentration. Strategic archetypes include vertically integrated European aerospace conglomerates, US defense-focused payload integrators, and Japanese diversified electronics manufacturers. Dominant competitive moves encompass strategic partnerships for electric propulsion technology access and geographic expansion into Indian and Middle Eastern procurement programs.
Within the European vertically integrated tier, Airbus SE and Thales Group represent archetypal positions combining civilian earth observation with institutional defense demand. Among US-based defense specialists, Northrop Grumman Corporation anchors protected communications payload integration for Space Force programs. These named entities exemplify how heritage qualification and established environmental testing capabilities create defensive moats against new entrants facing compressed commercial timelines.
| Leading Market Players |
|---|
| Airbus SE |
| RTX Corporation |
| Lockheed Martin Corporation |
| Mitsubishi Electric Corporation |
| Maxar Technologies Inc |
| Northrop Grumman Corporation |
| Thales Group |
| Raytheon |
| The Boeing Company |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in China and state-affiliated European aerospace conglomerates anchor supply-side discipline, translating captive foundry access into pricing power over radiation-hardened components while commercial mega-constellation operators compress margins through multi-year volume commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates qualification-intensive defense payloads from commercial constellation subsystems and commoditized ground support equipment. Price differentiation rests on radiation-hardening certification grade and mission-critical reliability tier, with Space Force programs tolerating cost-plus arrangements while broadband operators enforce fixed-price discipline. Cost compression in commercial tiers is intensifying because mega-constellation procurement concentrates buying power among fewer than ten anchor customers. Commercial satellite operators exhibit highest price sensitivity; defense agencies demonstrate lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for electric propulsion units and phased-array antennae, while specialized distributors serve fragmented government procurement programs. Manufacturing gravity centers on the United States, China, and Germany, with Germanium wafer production for solar cell substrates drawing from Bavarian and Saxon facilities. Supply chains rest on xenon propellant, gallium arsenide substrates, and radiation-hardened semiconductors. Single-source vulnerability in qualified semiconductor foundries exposes procurement to throughput constraints. Distribution runs through prime contractor integration facilities in California, Colorado, and Toulouse.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Satellite Parts and Components Market functions as a stable compounder, with FCC and EU orbital debris mandates generating durable demand for propulsion systems with verified passivation capabilities.
For Market Incumbents: Deploy heritage qualification leverage to capture electric propulsion upgrade cycles across existing satellite fleets. Incumbents should anchor backward integration into solar cell substrate production to offset Germanium supply concentration risk, while accelerating environmental testing throughput to match commercial constellation 12-18 month qualification demands. Capacity expansion in India addresses emerging ISRO and NSIL procurement requirements. For New Entrants and Emerging Players: Begin with indigenous component qualification for India's Gaganyaan program and commercial launch expansion, where BIS standards and PLI scheme incentives lower entry barriers. Synthetic aperture radar convergence offers the most penetrable white-space, combining civilian climate monitoring with defense signals intelligence demand. A targeted go-to-market angle positions modular subsystems for in-orbit servicing demonstration missions sponsored by NASA and ESA. For Investors and Strategic Acquirers: Prime contractors with captive environmental testing infrastructure are the most active acquirer in this space, consolidating tier-two subsystem vendors facing volume pressure from mega-constellation procurement concentration. Long-term viability favors targets with demonstrated radiation-hardening heritage and established ESA or Space Force program relationships. The signal to monitor is qualification timeline compression—vendors achieving 18-month environmental testing cycles for commercial customers command premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Technology Access Partnership | Hall-effect thruster licensing from established suppliers accelerates de-orbit capability compliance with FCC mandates. |
| Indigenous Component Qualification Program | ISRO procurement for Gaganyaan creates captive demand for radiation-hardened subsystems manufactured in Bengaluru. |
| Optical Inter-Satellite Link Deployment | Space Development Agency procurement drives volume for laser communication terminals reducing gateway infrastructure dependency. |
| REACH-Compliant Thermal Material Reformulation | ECHA restrictions on cadmium and hexavalent chromium force reformulation of satellite coating and connector plating chemistries. |
| Modular Subsystem Architecture Development | NASA and ESA in-orbit servicing missions validate robotic component replacement opening aftermarket revenue streams. |
Research Methodology
Coverage spans the United States, China, France, Germany, and India, with primary inputs from each market combining structured interviews with satellite bus engineers, procurement leads at commercial constellation operators, ESA program managers, Space Force contracting officers, and radiation effects specialists. Secondary validation draws from FCC orbital debris filings, ESA tender documentation, ISRO annual reports, SEC 10-K disclosures from prime contractors, and customs records for Germanium and gallium arsenide substrate trade flows. Bottom-up component demand modeling triangulates against top-down satellite launch forecasts.
Granularity extends to product-type level for propulsion systems, solar arrays, antennae, and actuators; technology level for communication, earth observation, remote sensing, and navigation; end-user level for defense, commercial, government, and aerospace; and application level for telecommunication, surveillance, weather monitoring, and scientific research. CAGRs derive from segment-level volume trajectories and value-per-unit assumptions across the projection horizon. Industry-specific inputs include electric propulsion adoption curves, mega-constellation deployment schedules, and regulatory compliance timeline requirements.
Several conditions sit outside the modeled scope, including classified defense payload specifications, proprietary radiation-hardening process parameters, and unannounced commercial constellation expansion plans. Forecasts assume stable regulatory enforcement of FCC and EU debris mitigation rules, continued xenon propellant availability, and intact Germanium supply chains. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Satellite Sensor Market
Satellite
Healthcare Satellite Connectivity Market
Satellite
France Satellite Connectivity Market
Satellite
Earth Observation Satellite Market
Satellite
Satellite Launch Vehicle (SLV) Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Reusable Satellite Launch Vehicle (RSLV) Market
Satellite
Italy Satellite Imagery Services Market
Satellite
Spain Satellite Imagery Services Market
Satellite
UK Satellite Connectivity Market
Satellite
Global Remote Sensing Services Market
Satellite
Global Broadband Satellite Services Market
Satellite
Satellite Photography Service Market
Satellite
Brazil Satellite-Based Earth Observation Market
Satellite
Low-Cost Satellite Market
Satellite
Optical Satellite Communication Market