
 Satellite Communication Subsystem Market | 2026-2036
Satellite Communication Subsystem Market Size, Share, and Industry Trends Forecast 2026-2036
Satellite Communication Subsystem Market Analytics
The premium military-grade segment is rebalancing away from commercial off-the-shelf hardware as hardened encryption and anti-jam specifications command widening price premiums over standard telecom configurations. L3Harris Technologies leverages decades of classified program experience to sustain its position in protected waveform architectures. Thales anchors European sovereign capability through national satellite programs in France and Italy. RTX competes across the full radio frequency chain with integrated aperture and processing solutions.
A satellite communication subsystem comprises the integrated electronic and RF assemblies—transceivers, modems, antennas, and power amplifiers—that encode, transmit, receive, and decode signals between orbital platforms and ground terminals, typically operating across Ku-band, Ka-band, X-band, or specialized military frequencies with pointing accuracies within fractions of a degree. These subsystems enable reliable data, voice, and video links for remote sensing networks, defense command networks, maritime safety systems, and broadband internet distribution where terrestrial infrastructure proves infeasible. Transmitter and antenna assemblies capture the dominant share of subsystem value given their material intensity in gallium nitride semiconductors and precision deployable structures, while Low Earth Orbit technology segments expand fastest as constellation operators demand phased-array solutions capable of rapid beam steering across hundreds of simultaneous links. The modem segment concentrates margin pools where software-defined waveform processing enables interoperability across legacy and next-generation protocols.
Defense procurement within NATO frameworks, FCC Part 25 licensing for NGSO operations, and ITU Radio Regulations governing orbital slot coordination collectively shape product roadmaps and market access timelines for subsystem vendors. EAR and ITAR export controls further segment addressable markets by restricting certain encryption and radiation-hardened technologies to approved national supply chains. Stakeholders must monitor spectrum reallocation proceedings and emerging quantum-resistant cryptographic standards to anticipate retrofit cycles and qualification requirements.
Market Dynamics
The Satellite Communication Subsystem Market is undergoing structural compression as phased-array antenna architectures displace mechanically steered parabolic dishes, collapsing unit economics for Low Earth Orbit constellation operators while elevating technical barriers for legacy suppliers.
Growth Catalysts
- LEO constellation deployment:Commercial operators are procuring thousands of flat-panel user terminals with electronic beam steering. FCC Part 25 licensing for non-geostationary orbit systems has compressed qualification timelines from years to months.
- NATO secure waveform mandates:Defense procurement frameworks now require protected communication links with anti-jam and low-probability-of-intercept capabilities. This specification shift is pulling hardened subsystem designs into mainstream military procurement.
- Gallium nitride semiconductor maturation:GaN power amplifiers deliver higher efficiency and thermal tolerance than gallium arsenide predecessors. Satellite manufacturers are redesigning transmitter chains around these devices to reduce spacecraft mass and extend operational life.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium for antenna positioning motors concentrate in Chinese processing facilities. Export licensing volatility creates input cost uncertainty for precision actuator suppliers.
- ITAR classification scope:US export controls on radiation-hardened electronics and cryptographic modules fragment addressable markets. European and Asian operators face procurement delays when sourcing qualified components.
- Orbital debris mitigation compliance:FCC and ITU mandates for post-mission disposal and collision avoidance systems add non-recurring engineering costs. Smaller subsystem vendors lack capital to certify deorbit mechanisms.
Strategic Opportunities
- Quantum-resistant cryptography retrofit:NIST post-quantum cryptographic standards will force upgrades to existing military satellite links. Subsystem vendors can capture replacement cycles by pre-integrating lattice-based encryption into modem architectures.
- Maritime broadband penetration:Cruise operators and commercial shipping fleets remain underserved by current LEO coverage. Terminal manufacturers can develop stabilized marine antennas with active wave compensation for high-latitude routes.
- Dual-use technology convergence:Commercial 5G waveform processing and military resilient networking standards are merging. Vendors with software-defined radio platforms can serve both segments without hardware redesign.
Industry Challenges
- Radiation-hardened ASIC design talent scarcity:Qualified integrated circuit designers with space-grade qualification experience concentrate at a handful of defense contractors. Workforce aging and limited university pipeline constrain expansion.
- Multi-constellation interoperability certification:Ground terminals must now authenticate across Starlink, OneWeb, and regional systems simultaneously. Modem firmware complexity and testing matrices extend development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Satellite Communication Subsystem Market |
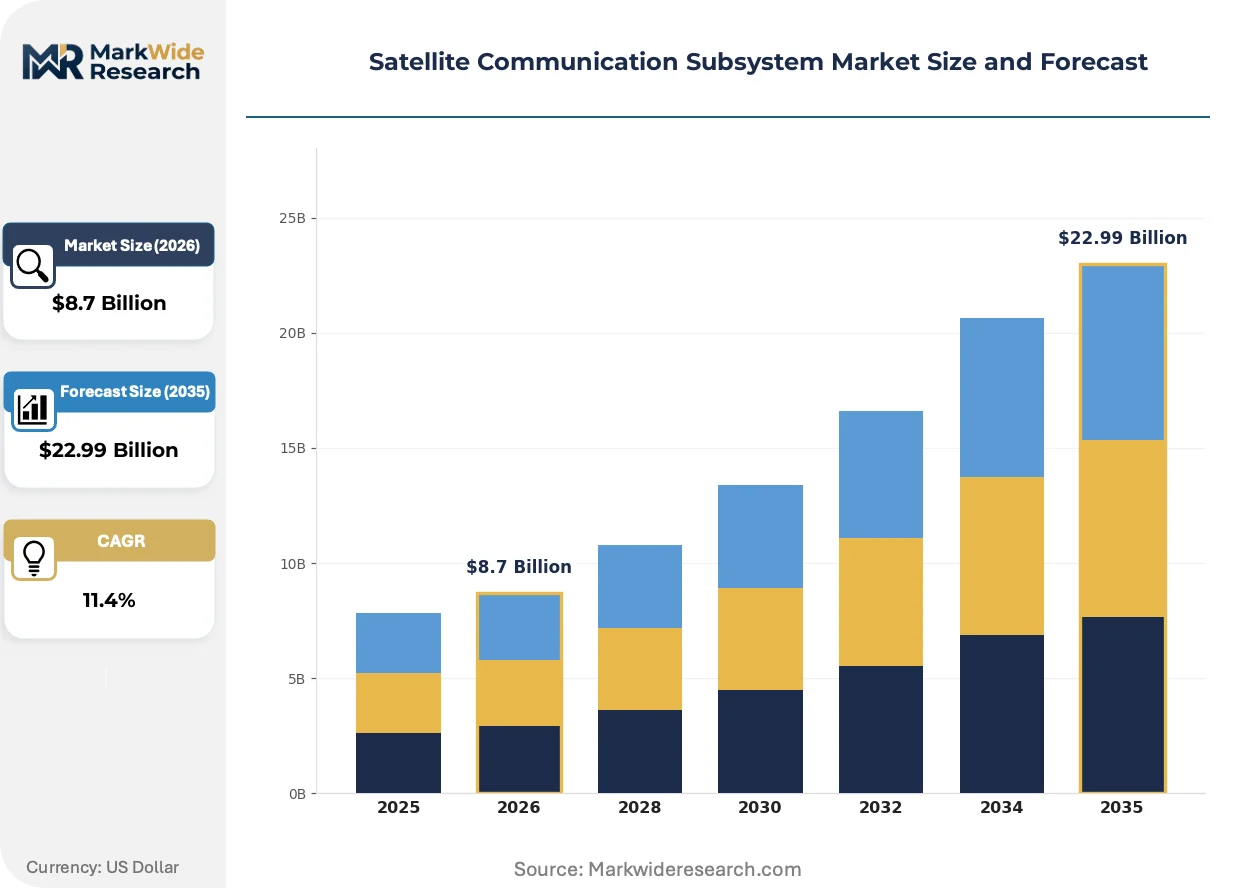
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmitter, Receiver, Modem, Antenna Technology: Geostationary, Low Earth Orbit, Medium Earth Orbit, Hybrid End User: Aerospace, Defense, Telecommunications, Maritime Service Type: Data Transmission, Voice Communication, Video Broadcasting, Internet Access |
| Companies Covered | Honeywell International, Ball Corporation, L3Harris Technologies, Thales, RTX, China Aerospace Science And Technology, IHI Aerospace, Bradford Space Holdings, Ananth Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Satellite Communication Subsystem Market Evolving Landscape
Phased-array technology is collapsing the traditional boundary between antenna and digital processing, enabling beam-forming algorithms to replace mechanical steering hardware. This shift is compressing subsystem footprints while multiplying link density requirements.
Software-defined aperture architectures are automating beam management tasks previously handled by discrete control electronics. Satellite operators in the LEO broadband segment are deploying these systems to maintain thousands of simultaneous links per spacecraft. The technology is automating handover sequences between ground cells, reducing latency variability for mobility applications.
The FCC's streamlined licensing framework for non-geostationary orbit constellations has eliminated sequential satellite-by-satellite approval processes. This regulatory simplification accelerates deployment timelines for commercial operators. Smaller subsystem vendors now face compressed qualification windows that favor pre-certified component platforms over custom designs.
Defense procurement patterns are fragmenting across national sovereign capability programs. European Space Agency member states are prioritizing domestic supply chains for military satellite programs. This demand rotation is displacing traditional transatlantic equipment flows and creating region-specific certification requirements that complicate vendor scale economics.
Satellite Communication Subsystem Market Segmentation
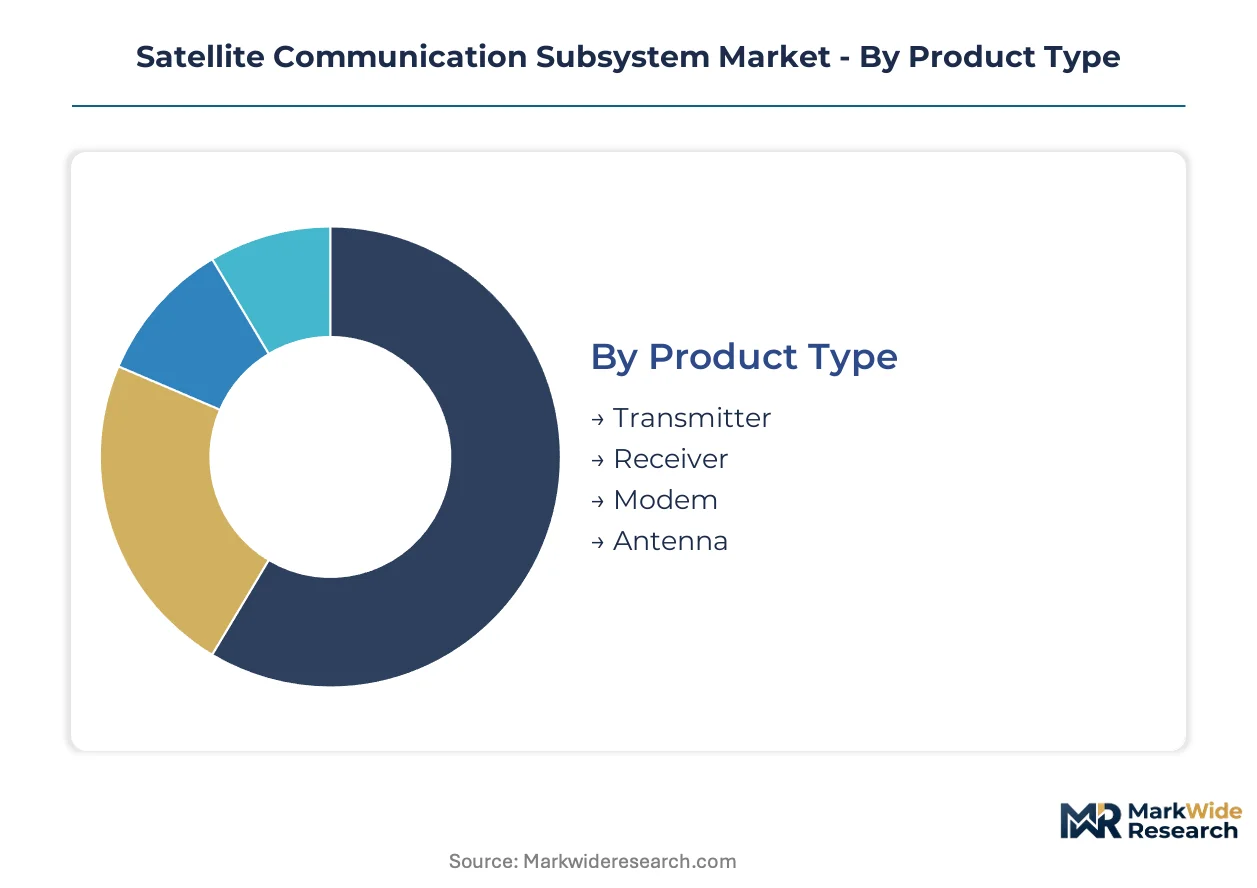
Subsystem vendors configure product portfolios around orbital altitude requirements, payload integration constraints, and end-user certification standards. Each segmentation dimension carries distinct margin profiles and qualification barriers that reshape competitive positioning across defense and commercial verticals.
Product Type:
Supply concentration in gallium nitride foundries and precision deployable structures tilts value capture toward transmitter and antenna assemblies.
- Transmitter:GaN power amplifiers dominate transmitter architectures, delivering higher efficiency and thermal tolerance than legacy gallium arsenide designs. Defense procurement across NATO member states concentrates demand for radiation-hardened transmitter chains with anti-jam waveform capabilities.
- Antenna:Phased-array flat panels displace mechanically steered parabolic dishes, collapsing unit economics for LEO constellation operators. FCC Part 25 licensing compression accelerates procurement timelines for electronically steered terminals.
- Receiver:Low-noise amplifiers and downconversion chains capture margin in precision filtering applications.
- Modem:Software-defined waveform processing enables interoperability across legacy and next-generation protocols.
Today's leader: Antenna. Tomorrow's challenger: Modem.
Technology:
Cost tier stratification separates capital-intensive geostationary platforms from mass-manufactured LEO terminals.
- Low Earth Orbit:Constellation operators procure thousands of compact terminals with rapid beam-steering requirements. Space Force modernization programs and commercial broadband infrastructure buildouts in the United States concentrate procurement velocity for LEO-compatible subsystems.
- Geostationary:Traditional parabolic ground stations and bent-pipe transponders sustain revenue in broadcast and enterprise backhaul. ITU Radio Regulations governing orbital slot coordination extend deployment timelines, preserving incumbent supplier relationships.
- Medium Earth Orbit:O3b and similar constellations occupy intermediate latency positions for maritime and aeronautical applications.
- Hybrid:Multi-orbit terminals aggregate capacity across geostationary and non-geostationary sources.
LEO subsystems are climbing the fastest; geostationary equipment retains the deepest installed base.
End User:
Application-specific certification requirements fragment vendor addressable markets across civilian and classified supply chains.
- Defense:Hardened encryption and anti-jam specifications command widening price premiums over commercial configurations. National sovereign capability programs in France and Italy anchor European procurement, displacing traditional transatlantic equipment flows.
- Aerospace:Commercial aviation connectivity demands stabilized terminals with rapid handover between satellite beams.
- Telecommunications:Rural broadband and cellular backhaul drive volume procurement of consumer-grade flat panels.
- Maritime:Cruise operators and commercial shipping fleets remain underserved by current LEO coverage patterns.
Defense commands the steepest pricing power; maritime represents the largest addressable gap.
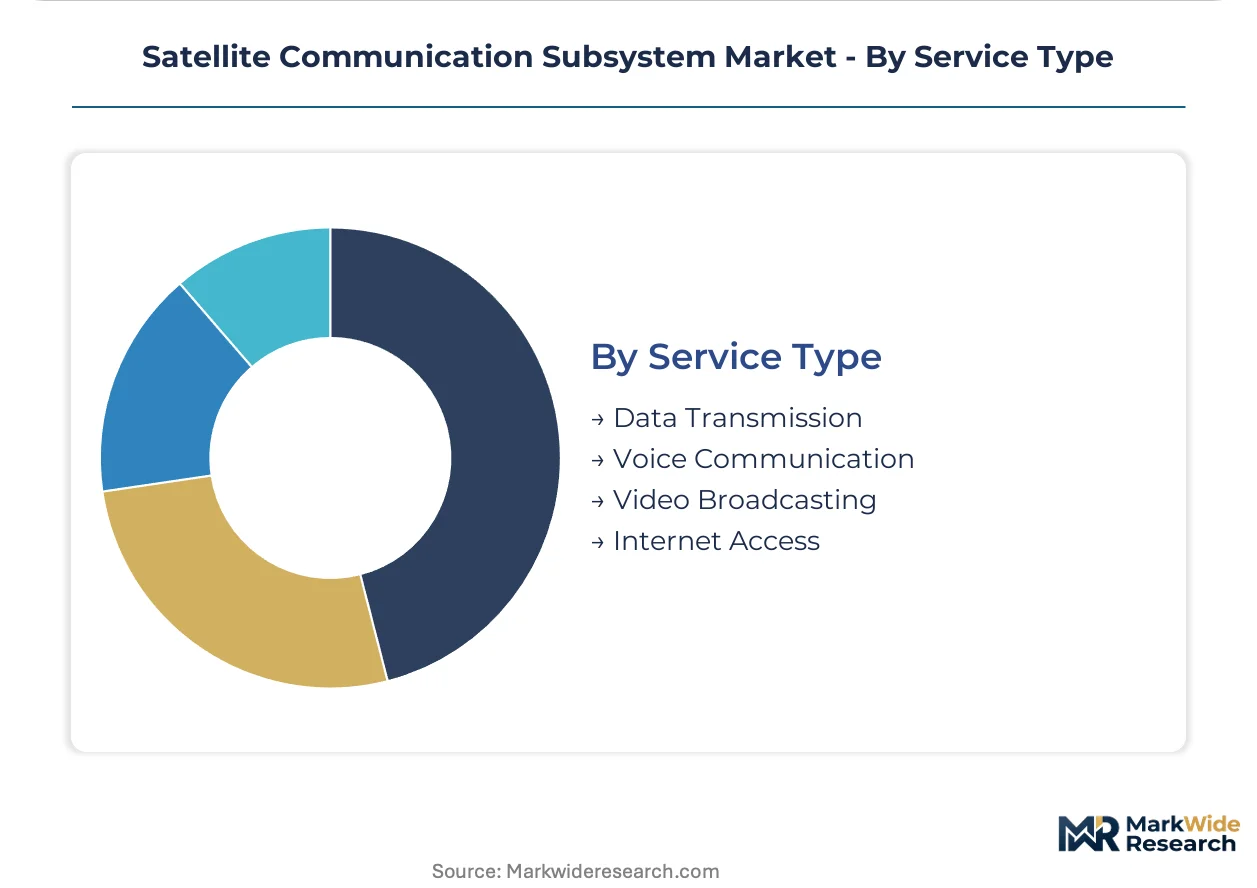
Service Type:
Customer type differentiation separates enterprise-grade service level agreements from consumer mass-market propositions.
- Internet Access:LEO broadband operators deploy phased-array user terminals capable of maintaining thousands of simultaneous links. United States infrastructure buildouts concentrate subscriber acquisition investment, compressing terminal cost curves through volume manufacturing.
- Data Transmission:Remote sensing networks and IoT backhaul demand low-duty-cycle, high-reliability links.
- Voice Communication:Narrowband satellite phones and push-to-talk services sustain niche subscriber bases.
- Video Broadcasting:Direct-to-home satellite television contracts as streaming displaces traditional distribution.
Internet access is gaining share fastest; video broadcasting faces structural decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified integrated circuit designers with space-grade qualification experience concentrate at defense contractors across the United States, France, and Japan. This talent distribution shapes subsystem manufacturing footprints and export control compliance capabilities.
United States
Space Force modernization programs and LEO broadband infrastructure buildouts concentrate procurement velocity for compatible subsystems. FCC Part 25 licensing for non-geostationary orbit systems has compressed qualification timelines from years to months. Colorado and California host dense clusters of satellite subsystem manufacturers serving both defense and commercial constellations.
France
National sovereign capability programs anchor European procurement for military satellite equipment, displacing traditional transatlantic equipment flows. ESA member state frameworks prioritize domestic supply chains for classified programs. Toulouse and Paris-Saclay clusters specialize in protected waveform architectures and radiation-hardened component integration.
Germany
ITAR export controls on cryptographic modules fragment addressable markets for European operators sourcing qualified components. The country's national space agency coordinates dual-use technology development with commercial foundries. Bavaria and Baden-Württemberg host precision actuator suppliers facing rare earth magnet input cost uncertainty.
Japan
Commercial aviation connectivity demands stabilized terminals with rapid handover between satellite beams. METI coordinates domestic satellite manufacturing standards with international ITU Radio Regulations. Nagoya and Tokyo metropolitan areas concentrate phased-array antenna development for maritime and aeronautical applications.
United Kingdom
Multi-constellation interoperability certification requirements extend development cycles for ground terminal modem firmware. The national space regulator aligns orbital debris mitigation mandates with FCC and ITU disposal standards. Harwell and Glasgow clusters specialize in small satellite subsystem integration for constellation operators.
Satellite Communication Subsystem Market Competitive Landscape
Top-tier vendors anchor classified program experience, while mid-tier specialists compete on software-defined radio platforms and rapid qualification timelines. The vendor base stratifies across defense primes with decades of protected waveform heritage, commercial constellation specialists with volume manufacturing scale, and regional champions serving national sovereign capability requirements. Two strategic archetypes dominate: radiation-hardened subsystem integrators and flat-panel terminal mass manufacturers. Competitive moves concentrate on M&A for GaN semiconductor supply security and strategic partnerships for multi-orbit interoperability certification.
Among US-based defense contractors, L3Harris Technologies and RTX exemplify the classified program integration archetype, while Thales anchors the European sovereign capability tier. Honeywell International occupies a position spanning both defense and commercial aviation connectivity segments. These three named entities represent distinct competitive vectors: waveform architecture depth, full RF chain integration, and dual-use platform versatility.
| Leading Market Players |
|---|
| Honeywell International |
| Ball Corporation |
| L3Harris Technologies |
| Thales |
| RTX |
| China Aerospace Science And Technology |
| IHI Aerospace |
| Bradford Space Holdings |
| Ananth Technologies |
| Others |
Value Network & Pricing Analysis
Gallium nitride wafer pricing indices cascade through transmitter assembly tiers, compressing margins for commercial off-the-shelf configurations while hardening radiation-qualified variants command widening premiums. FCC Part 25 licensing acceleration has compressed qualification timelines, forcing subsystem vendors to absorb upfront non-recurring engineering costs across shorter production runs.
Pricing Analysis
Bundled service contracts dominate defense procurement frameworks, while unbundled component sales characterize commercial LEO terminal procurement. Three-tier pricing structure across radiation-hardened, industrial-grade, and consumer configurations separates segments by ITAR certification burden and thermal tolerance specifications. Pricing pressure stems from volume manufacturing scale at flat-panel terminal producers, eroding mechanical steerable antenna margins. Commercial constellation operators exhibit highest price sensitivity, while NATO defense agencies prioritize waveform protection over unit cost.
Supply Chain Analysis
ITAR and EAR qualification gating fragments supplier bases, with radiation-hardened ASIC fabrication concentrating in the United States, precision antenna structures clustering in France and Japan, and GaN foundry capacity anchored in South Korea and Taiwan. Neodymium and dysprosium for antenna positioning motors draw from Chinese processing facilities, creating single-source vulnerability for precision actuator suppliers. Distribution runs through defense prime integrators for classified programs and direct OEM relationships for commercial constellation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in modem architectures where software-defined waveform processing enables premium-tier positioning, while GaN semiconductor maturation drives cost compression across transmitter chains.
For Market Incumbents: Deploy backward integration into GaN foundry capacity to secure power amplifier supply for radiation-hardened transmitter programs. Lock in multi-year qualification pipelines with Space Force modernization contractors before FCC licensing windows compress further. Counter emerging flat-panel terminal specialists by accelerating software-defined aperture firmware releases. For New Entrants and Emerging Players: Direct-to-constellation-operator sales channels offer lowest barrier-to-entry for modem firmware specialists with rapid FCC certification capabilities. Maritime broadband terminals for high-latitude shipping routes represent the most penetrable white-space segment, with active wave compensation requirements unmet by current LEO coverage. Lead with multi-constellation interoperability certification to bypass incumbent hardware lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with software-defined radio platform specialists bridging commercial 5G and military resilient networking standards. Long-term viability hinges on NIST post-quantum cryptographic retrofit cycles forcing hardware replacement across existing satellite links. Monitor FCC spectrum reallocation proceedings as inflection indicator for terminal refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Supply Security | Backward integration into foundry capacity secures power amplifier margins for radiation-hardened programs. |
| Multi-Orbit Interoperability Certification | Modem firmware enabling Starlink, OneWeb, and regional system authentication captures replacement cycles. |
| Quantum-Resistant Cryptography Pre-Integration | Lattice-based encryption in modem architectures positions vendors for NIST-mandated military retrofit demand. |
| Maritime Terminal Stabilization Development | Active wave compensation antennas address underserved cruise and commercial shipping broadband gaps. |
| Dual-Use Software-Defined Radio Platforms | Unified hardware serving commercial 5G and military resilient networks eliminates redundant R&D spend. |
Research Methodology
Coverage spans the United States, France, Germany, Japan, and the United Kingdom, with primary inputs from each region's defense procurement officers, satellite subsystem engineering directors, constellation operator supply chain managers, and GaN foundry operations leads. Secondary validation draws from FCC Part 25 licensing databases, ITU Radio Regulations filings, EAR and ITAR control list updates, and SEC disclosures from defense prime contractors. Bottom-up segment sizing triangulates against top-down procurement budget allocations from NATO member states and commercial operator capex announcements.
Rate-of-change decomposition separates volume growth from unit value shifts across the projection horizon. The analytical framework models product type, orbital technology tier, end-user certification grade, and service delivery model as core segmentation dimensions. CAGRs derive from satellite deployment manifests, ground terminal procurement schedules, and waveform architecture refresh cycles. Forecast inputs incorporate Space Force modernization program timelines, LEO constellation launch cadences, and ITU orbital slot coordination queues.
The model assumes a particular technology adoption path; alternative pathways for phased-array antenna maturation would alter the outlook for mechanical steerable terminal incumbents. Forecasts reflect assumptions regarding gallium nitride yield improvements, rare earth magnet export licensing stability, and radiation-hardened ASIC design talent pipeline expansion. A model refresh is warranted upon material change in FCC spectrum reallocation proceedings or NIST post-quantum cryptographic standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Satellite Launch Vehicle Market
Satellite
Satellite Compass Market
Satellite
US Satellite-Based Earth Observation Market
Satellite
North America Satellite Bus Market
Satellite
Satellite GPS Receivers Market
Satellite
Satellite Operation Service Market
Satellite
Nigeria Satellite-Based Earth Observation Market
Satellite
Israel Satellite Communications Market
Satellite
Satellite Signal Meter Market
Satellite
Israel Satellite Imagery Services Market
Satellite
Satellite Manufacturing Market
Satellite
Global Enterprise VSAT System Market
Satellite
Europe Military Satellite Market
Satellite
Low-Cost Satellite Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
UK Satellite Connectivity Market