
 GEO Satellite Market | 2026-2036
GEO Satellite Market Size, Share, and Industry Trends Forecast 2026-2036
GEO Satellite Market Insights
All-electric propulsion is restructuring satellite economics by eliminating hydrazine-based chemical systems and slashing launch mass by up to 40 percent. Boeing leverages its heritage in 702SP platform manufacturing to anchor high-throughput payload deliveries for commercial operators. Thales Alenia Space competes through Spacebus Neo electric-propulsion variants that sustain European sovereign capability. Airbus Defence and Space dominates military-grade GEO platforms with hardened payloads for government end users.
A geostationary Earth orbit satellite occupies a circular equatorial orbit at approximately 35,786 kilometers altitude, completing one revolution per sidereal day to maintain fixed apparent position above a ground point; this orbital slot stability enables continuous regional coverage with minimal ground infrastructure. Communications satellites command the largest value share within the satellite type dimension, driven by broadband trunking and direct-to-home video distribution. Earth observation payloads represent the fastest-expanding category as meteorological agencies and climate monitors demand persistent hemispheric imaging. Military end users concentrate margin pools through classified payload integration and hardened bus requirements.
FCC orbital slot licensing and ITU coordination procedures shape market access timelines, with U.S. operators facing multi-year queues for Ka-band and V-band spectrum rights. ESA procurement rules and EU Space Programme funding directives steer European manufacturer order books toward dual-use capability. Stakeholders must monitor spectrum reallocation proceedings and debris mitigation rulemaking at national regulators, as these decisions will determine which orbital architectures retain operational viability.
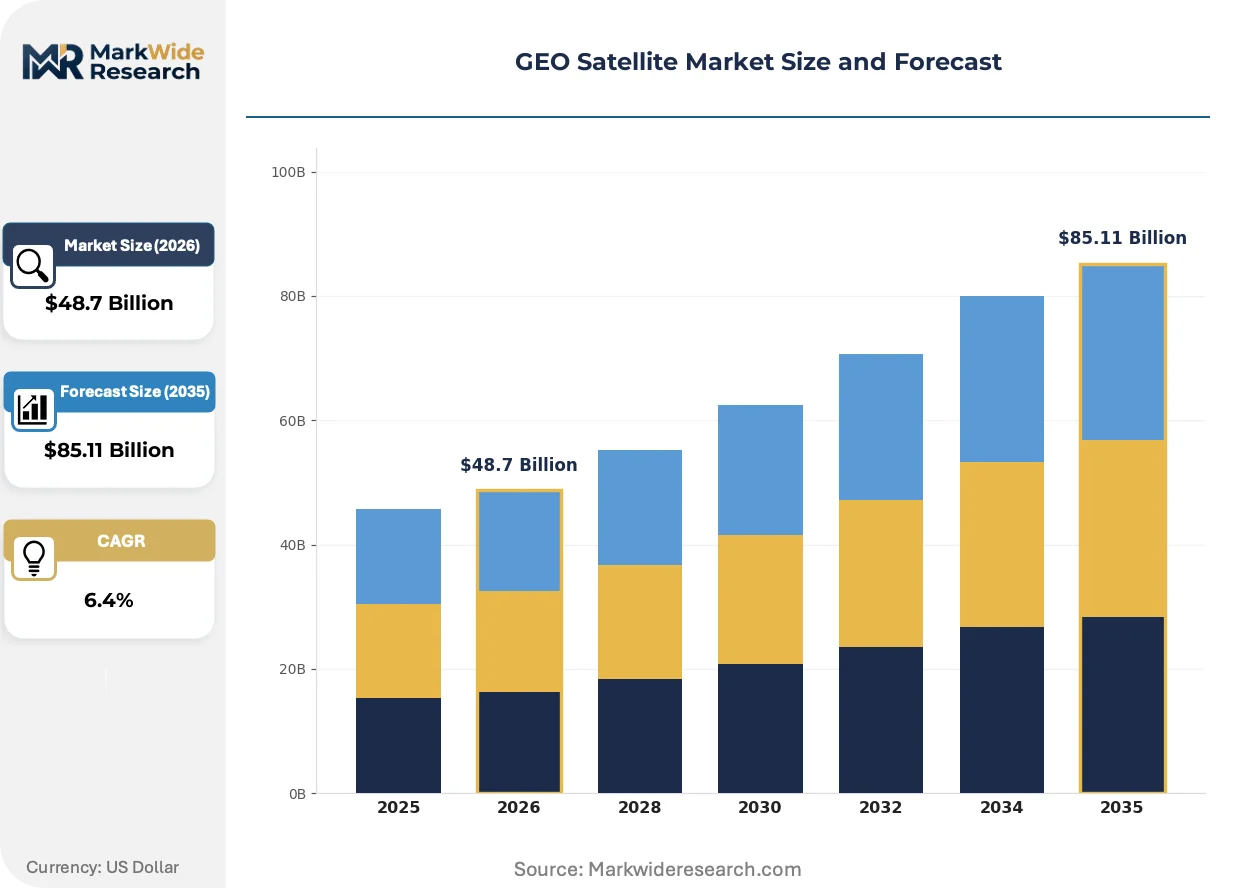
Market Dynamics
Electric propulsion architectures are compressing satellite wet mass and extending service life, fundamentally altering launch economics and orbital slot utilization strategies across the GEO ecosystem.
Growth Catalysts
- Defense Communications Procurement:The U.S. Space Force is accelerating hardened payload orders for secure military networks, channeling federal budgets into geostationary infrastructure with classified encryption requirements.
- ITU Spectrum Coordination:Ka-band and V-band licensing queues are lengthening, creating first-mover advantages for operators with secured orbital slots and predictable frequency rights.
- Meteorological Imaging Demand:Climate monitoring agencies require persistent hemispheric coverage, driving procurement of Earth observation payloads with thermal and multispectral sensing capabilities.
Market Restraints
- Launch Cost Concentration:Heavy-lift vehicle availability clusters with a limited supplier base, creating capacity bottlenecks for large all-electric satellite buses requiring dedicated rideshare or direct insertion.
- FCC Licensing Timelines:Multi-year orbital slot queues delay revenue realization for new market entrants, favoring incumbents with grandfathered spectrum allocations.
- LEO Constellation Substitution:Low Earth orbit broadband swarms from SpaceX and Amazon are fragmenting addressable demand for traditional GEO video distribution and consumer broadband.
Strategic Opportunities
- Dual-Use Platform Convergence:Military and commercial payload sharing on hardened buses enables cost recovery through civilian leasing during peacetime orbital operations.
- India's Space Programme Expansion:ISRO procurement of indigenous GEO platforms creates offset manufacturing opportunities for European subsystem suppliers under technology transfer agreements.
- ESA In-Orbit Servicing Mandates:Refueling and life-extension robotics are creating aftermarket revenue streams for satellite operators with compatible docking interfaces and standardized fluid transfer protocols.
Industry Challenges
- Electric Propulsion Talent Scarcity:Specialized workforce for Hall-effect thruster integration and power management electronics remains concentrated with legacy platform manufacturers, constraining new entrant scaling.
- Debris Mitigation Compliance:Post-mission disposal regulations require propellant reserves for graveyard orbit insertion, complicating mission planning and reducing operational flexibility for extended-service contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GEO Satellite Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Satellite Type: Communications, Earth Observation, Scientific, Navigation Payload Type: Imaging Sensors, Transponders, Weather Instruments, Scientific Instruments End User: Government, Commercial, Military, Research Institutions Launch Vehicle: Rocket, Spaceplane, Hybrid Vehicle, Small Launcher |
| Companies Covered | SES S.A., Intelsat S.A., Eutelsat Group, Viasat Inc., Lockheed Martin, Boeing, Northrop Grumman, Thales Alenia Space, Airbus Defence and Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GEO Satellite Market Trends and Innovations
Orbital slot economics and payload miniaturization are converging to reshape competitive positioning. Manufacturers are prioritizing modularity and software-defined architectures to extend platform relevance across shifting demand verticals.
All-electric propulsion is overtaking chemical bi-propellant systems for station-keeping and orbit-raising maneuvers. Commercial operators with high-throughput broadband mandates are adopting Boeing 702SP-derived platforms and Thales Spacebus Neo variants at accelerating rates. This transition is compressing launch mass requirements by eliminating heavy fuel tanks and enabling dual-satellite stacked deployments on single heavy-lift missions.
REACH chemical restrictions and EU Green Deal decarbonization targets are tightening material specifications for satellite manufacturing. European suppliers must now document full supply chain environmental footprints for ESA procurement eligibility, with fluorinated gas regulations affecting thermal control subsystem selection. French and Italian prime contractors are responding by qualifying alternative propellants and passive cooling architectures for export compliance.
Service contract unbundling is fragmenting traditional bundled procurement. Government end-users now separate bus manufacturing from payload integration and launch services, enabling competitive tendering at each stage. This pattern is most pronounced in U.S. Department of Defense acquisitions, where the Space Development Agency and U.S. Space Force are driving disaggregated satellite architecture mandates across multiple orbital regimes.
GEO Satellite Market Segmentation
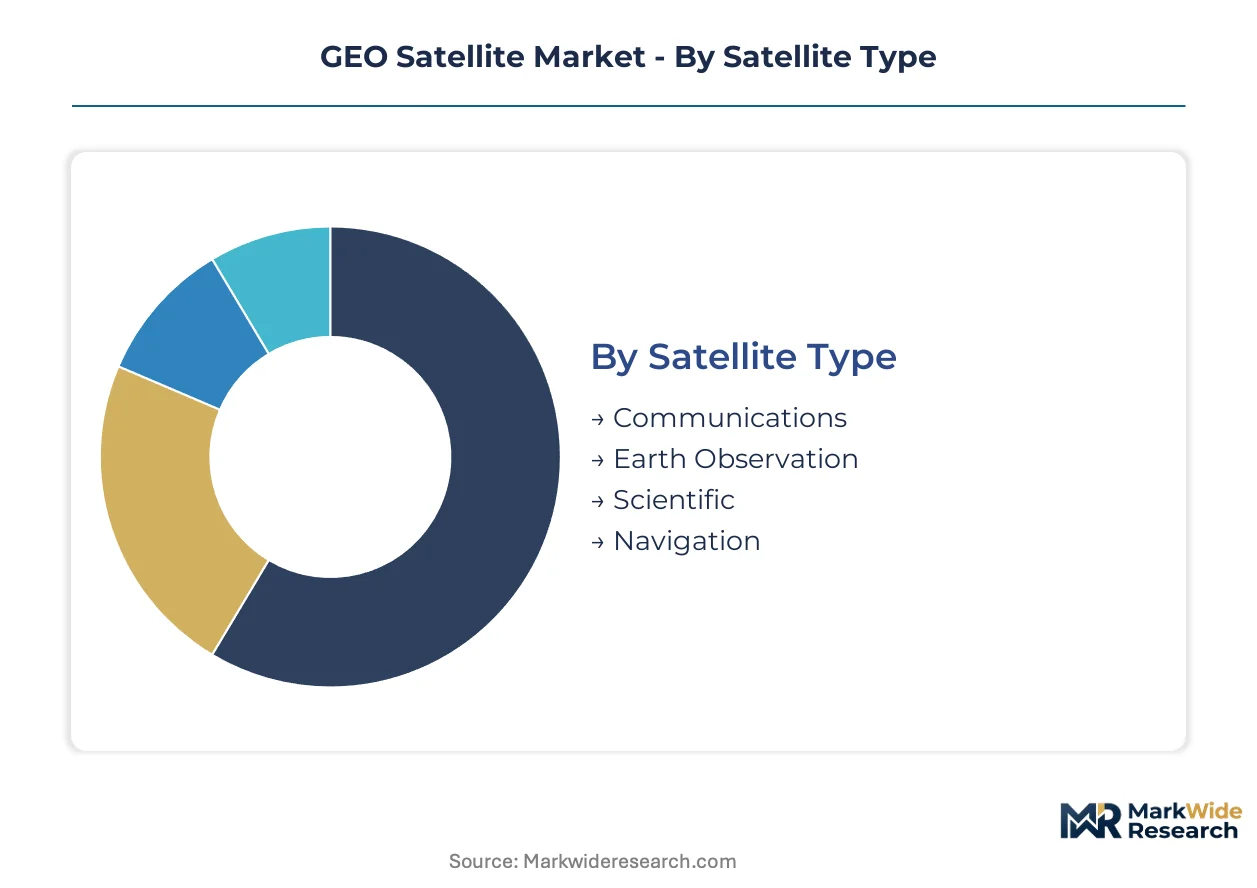
Segmentation in the GEO satellite market reveals distinct procurement patterns tied to orbital slot economics and payload lifecycle management. Upgrade cycles vary dramatically across satellite types, with communications platforms demanding replacement every 15 years while scientific missions extend operational windows through in-orbit servicing.
Satellite Type:
Replacement-cycle intensity drives manufacturer order book concentration, with operators balancing extended service life against spectral efficiency gains from newer platforms.
- Communications:High-throughput Ka-band and V-band payloads dominate procurement volumes. U.S. commercial operators and federal agencies anchor demand through direct-to-home video and broadband trunking mandates, with FCC licensing queues creating predictable replacement schedules.
- Earth Observation:Persistent hemispheric imaging requirements from meteorological agencies are accelerating procurement. European climate monitoring programs and U.S. NOAA contracts concentrate investment in thermal and multispectral sensing capabilities, with electric propulsion extending operational lifespans beyond traditional chemical systems.
- Scientific:Specialized orbital configurations for astrophysics and space weather monitoring serve NASA and ESA mission portfolios.
- Navigation:Timing and positioning augmentation payloads support GPS and Galileo constellation integrity.
Communications sits at the top of the volume ranking, with Earth Observation climbing the fastest.
Payload Type:
Cost tier differentiation separates heritage hardware from software-defined architectures that enable post-launch capability reconfiguration.
- Transponders:Bent-pipe and regenerative repeater systems process C-band, Ku-band, and emerging Ka-band traffic. Commercial satellite operators in the United States prioritize flexible channelization to capture shifting demand between video distribution and consumer broadband, with ITU coordination timelines dictating procurement urgency.
- Imaging Sensors:Multispectral and hyperspectral detectors capture thermal, visible, and infrared signatures. European meteorological agencies and U.S. climate science programs drive specification requirements, with REACH chemical restrictions influencing detector material selection.
- Weather Instruments:Radiometers and sounders profile atmospheric conditions for storm tracking and climate modeling.
- Scientific Instruments:Particle detectors and magnetometers support heliophysics and astrophysics research missions.
Transponders command the largest installed base, while Imaging Sensors gain share fastest among new procurements.
End User:
Customer-type fragmentation is unbundling traditional bundled procurement across defense, commercial, and civil government channels.
- Government:Civilian agencies including NOAA and meteorological services procure operational weather and climate monitoring platforms. Multi-year budget appropriations create predictable replacement cycles, with ESA member state contributions and U.S. congressional allocations determining procurement timing.
- Military:Classified payload integration and hardened bus requirements concentrate margin pools. The U.S. Space Force accelerates orders for secure communications with anti-jam capabilities, with disaggregated architecture mandates separating bus manufacturing from payload integration.
- Commercial:Telecommunications operators and broadcasters lease orbital slots for video distribution and broadband services.
- Research Institutions:Universities and national laboratories access shared-risk missions through hosted payload arrangements.
Military procurement delivers the highest unit margins, with Commercial volumes expanding most quickly through broadband constellation deployment.
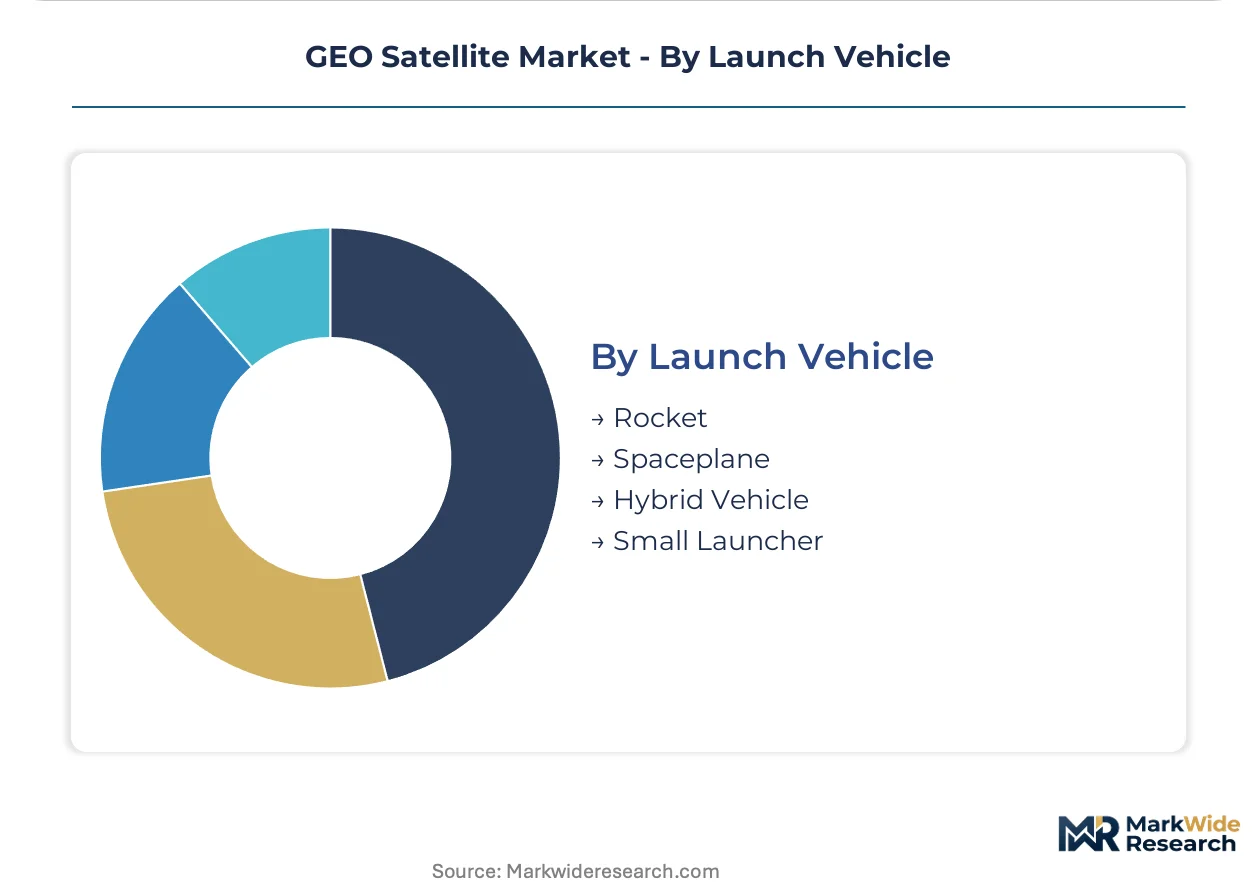
Launch Vehicle:
Supply concentration in heavy-lift capacity shapes platform design choices and deployment economics for large GEO satellites.
- Rocket:Expendable and partially reusable heavy-lift vehicles insert satellites directly into geostationary transfer orbit. Ariane, Falcon Heavy, and Vulcan Centaur availability determines scheduling certainty for large all-electric buses, with U.S. Space Force launch contracts prioritizing domestic vehicle certification.
- Small Launcher:Dedicated rideshare missions and rapid-response deployment serve technology demonstration and replacement payloads. Emerging providers in the United States and Europe compete for responsive space access contracts, with lower payload mass limits favoring miniaturized satellite designs.
- Spaceplane:Reusable winged vehicles offer potential for rapid turnaround and reduced per-mission costs.
- Hybrid Vehicle:Air-launch and other non-traditional architectures provide deployment flexibility for specialized orbital requirements.
Rocket platforms handle the majority of GEO mass to orbit, with Small Launcher utilization gaining fastest for auxiliary and replacement missions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors GEO satellite demand through federal space budgets and commercial broadband procurement, with orbital slot licensing queues at the FCC shaping manufacturer order timing.
United States
U.S. Space Force procurement of hardened communications payloads and NOAA meteorological satellite contracts drive sustained platform demand. FCC orbital slot licensing and ITU spectrum coordination procedures create multi-year queues for Ka-band and V-band rights. Los Angeles-area aerospace clusters concentrate prime contractor engineering for military-grade GEO buses.
France
European climate monitoring programs and dual-use military-civilian satellite mandates sustain manufacturing volumes. ESA procurement rules and EU Green Deal decarbonization targets steer supplier qualification toward REACH-compliant material specifications. Toulouse hosts Thales Alenia Space and Airbus Defence and Space engineering centers for electric propulsion integration.
Germany
German meteorological agencies and ESA scientific mission portfolios generate steady demand for Earth observation payloads. F-Gas Regulation restrictions on fluorinated thermal control materials compel subsystem redesigns for export eligibility. Munich and Bremen industrial clusters specialize in Hall-effect thruster manufacturing and power management electronics.
Japan
METI space program funding and JAXA climate monitoring contracts support indigenous platform development. National security guidelines increasingly restrict foreign payload integration on government satellites. Tokyo-Yokohama aerospace corridors concentrate Mitsubishi Electric and NEC satellite manufacturing capabilities.
India
ISRO procurement of indigenous GEO platforms for communications and weather monitoring accelerates domestic production capacity. Technology transfer agreements with European subsystem suppliers create offset manufacturing opportunities. Bengaluru and Ahmedabad host ISRO satellite integration facilities with expanding private sector participation.
GEO Satellite Market Competitive Landscape
Platform specialization dominates the current landscape, with manufacturers consolidating around electric propulsion architectures and hardened bus designs. The vendor base separates into three tiers: prime contractors with full vertical capability, subsystem specialists supplying propulsion and payload components, and emerging national champions serving protected domestic markets. Two strategic archetypes predominate: heritage platform manufacturers leveraging decades of flight-proven designs, and electric-propulsion innovators compressing launch mass to capture dual-satellite deployment economics. M&A activity concentrates on propulsion subsystem acquisition, while strategic partnerships address ITU spectrum coordination and shared orbital slot utilization.
Within the heritage prime contractor tier, Boeing and Lockheed Martin occupy positions anchored by decades of U.S. government and commercial satellite delivery. Thales Alenia Space exemplifies the European electric-propulsion specialist archetype, competing through Spacebus Neo variants that sustain sovereign manufacturing capability. These three entities represent distinct competitive vectors: American full-spectrum capability, European electric-propulsion innovation, and the broader pattern of geographic concentration where national space programs protect domestic supplier bases.
| Leading Market Players |
|---|
| SES S.A. |
| Intelsat S.A. |
| Eutelsat Group |
| Viasat Inc. |
| Lockheed Martin |
| Boeing |
| Northrop Grumman |
| Thales Alenia Space |
| Airbus Defence and Space |
| Others |
Pricing and Supply Chain Analysis
Specialized Hall-effect thruster engineers concentrated in Los Angeles and Toulouse aerospace clusters create labor-cost differentials that widen pricing-tier spreads between heritage prime contractors and emerging subsystem suppliers.
Pricing Analysis
Input-cost pass-through from rare-earth magnet and xenon propellant suppliers compresses margins on electric-propulsion platforms. Pricing stratifies across military-hardened buses, commercial high-throughput satellites, and standardized weather platforms based on ITAR certification levels and payload customization depth. Price erosion runs through commercial communications tiers as LEO constellation competition fragments video distribution demand. Government end-users show lowest price sensitivity due to classified payload integration requirements, while commercial telecom operators negotiate aggressively on volume procurement.
Supply Chain Analysis
Workforce availability for electric propulsion integration concentrates in the United States, France, and Germany, constraining platform manufacturing scalability outside these geographies. Supply chains draw from gallium arsenide solar cell foundries in Japan, precision antenna manufacturers in Italy, and carbon-fiber composite suppliers in the United States. Single-source vulnerability persists for radiation-hardened power management electronics. Distribution runs through prime contractor direct sales to government agencies and commercial operators, with ESA and U.S. Space Force procurement offices serving as gatekeepers for qualified vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in GEO satellite manufacturing hinges on electric propulsion adoption slashing launch mass premiums and enabling dual-satellite deployment economics.
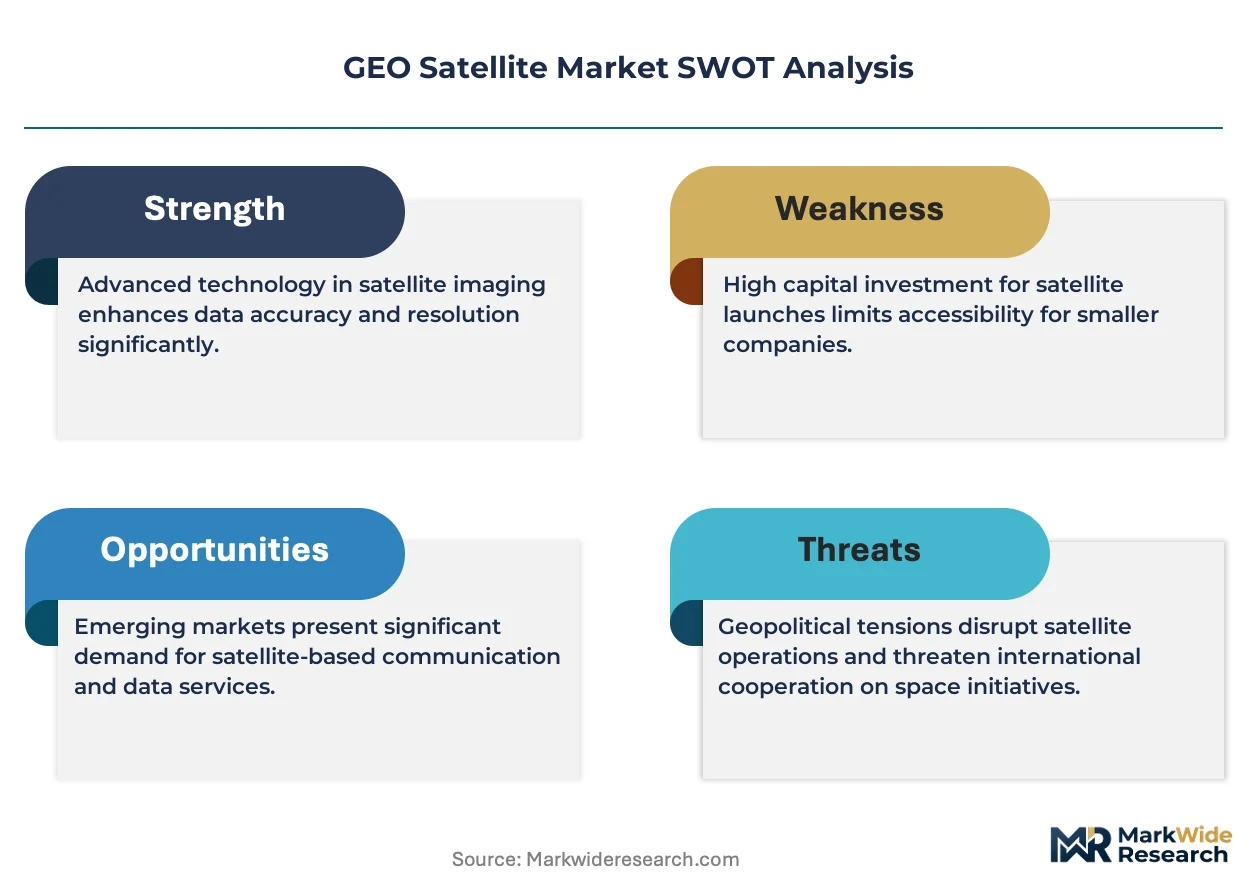
For Market Incumbents: Lock in Hall-effect thruster engineering talent through captive training pipelines in Los Angeles and Toulouse clusters. Secure grandfathered FCC orbital slot portfolios to delay competitive entry. Acquire specialized power electronics suppliers to defend against emerging platform competitors. For New Entrants and Emerging Players: Begin with ISRO offset manufacturing agreements for indigenous GEO platform subsystems. Target Indian and Japanese protected procurement markets where foreign prime contractor access faces national security restrictions. Pursue hosted payload arrangements on existing buses to bypass full platform development costs. For Investors and Strategic Acquirers: Valuations sit cheapest among European subsystem specialists with REACH-compliant material qualifications and ESA supplier status. Long-term viability centers on in-orbit servicing compatibility and refueling interface standardization. Watch Space Force disaggregated architecture mandates as signal for payload-integration carve-out opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Platform Qualification | Boeing 702SP and Thales Spacebus Neo heritage accelerates customer acceptance for all-electric buses. |
| ITU Spectrum Coordination Lock-in | Secured Ka-band and V-band rights at FCC create multi-year competitive moats for orbital slot holders. |
| Dual-Use Payload Integration | Military-civilian bus sharing enables cost recovery through commercial leasing during peacetime operations. |
| In-Orbit Servicing Interface Standardization | ESA refueling mandates generate aftermarket revenue for satellite operators with compatible docking protocols. |
| REACH-Compliant Supply Chain Certification | EU Green Deal material specifications determine ESA procurement eligibility for European manufacturers. |
Research Methodology
Multiple input streams — satellite operator procurement directors, Hall-effect thruster engineering leads, FCC licensing attorneys, and ESA programme managers — were reconciled against ITU spectrum coordination databases, U.S. Space Force budget justification documents, and ESA contract award notices. Secondary validation drew from NOAA satellite procurement records, ISRO annual reports, and customs data on xenon propellant trade flows. Bottom-up platform delivery forecasts and top-down orbital slot demand projections were cross-referenced for triangulation.
Historical launch manifests were cross-referenced against panel input from prime contractor business development executives and subsystem supplier sales directors. Segmentation modeling covered satellite type, payload architecture, end-user category, and launch vehicle class across the projection horizon. CAGRs were derived from replacement-cycle analysis and electric propulsion penetration curves. Industry-specific inputs included FCC licensing queue lengths and ESA in-orbit servicing mandate timelines.
Several conditions sit outside the modeled scope, including unannounced LEO constellation bankruptcy filings, ITU spectrum reallocation proceedings, and breakthrough nuclear propulsion demonstrations. Forecasts reflect assumptions about electric propulsion reliability maturation and heavy-lift vehicle availability. Material deviation in Space Force procurement acceleration or REACH chemical restriction tightening warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Asia-Pacific Satellite Bus Market
Satellite
US Satellite Connectivity Market
Satellite
Middle East Satellite Imagery Services Market
Satellite
South Korea Satellite Connectivity Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Asia-Pacific Satellite Attitude and Orbit Control System Market
Satellite
Global Satellite Propulsion System Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
Asia-Pacific Remote Sensing Satellites Market
Satellite
Israel Satellite Imagery Services Market
Satellite
Aviation Satellite Antenna Systems Market
Satellite
Global Commercial Satellite Imagery Market
Satellite
Satellite Sensor Market
Satellite
Satellite Amplifier Market
Satellite
Satellite Payload Market
Satellite
Middle East Satellite Communications Market