
 Global Rugged Power Supply Market | 2026-2036
Global Rugged Power Supply Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rugged Power Supply Market Intelligence
The capability gap between boutique, high-mix engineering for custom applications and high-volume, standardized manufacturing is unwinding competitive dynamics. Vicor Corporation specializes in high-density, modular power components for specialized systems. In contrast, Delta Electronics Inc. leverages its scale in commercial power solutions to offer cost-effective ruggedized variants. Ametek positions its offerings primarily for the high-specification aerospace and defense sectors, where performance and reliability justify premium costs.
A rugged power supply is an electronic device engineered to provide stable, reliable power conversion in environments with extreme shock, vibration, and temperature ranges. These units are often designed to meet specific standards, such as MIL-STD-810 for environmental endurance, ensuring operational integrity for critical systems. While AC-DC power supplies constitute the largest product type, DC-DC converters are gaining traction within aerospace systems for distributed power architectures. Military equipment applications represent the dominant end-use, though telecom infrastructure is showing significant expansion.
Compliance with stringent standards is non-negotiable for market participants. Regulations such as the US Department of Defense's MIL-STD-461 for electromagnetic interference and Europe's RoHS directive on hazardous substances define product design and material selection. These frameworks, alongside global IEC safety standards, create significant barriers to entry. Vendors must now decide whether to prioritize investment in next-generation compliance for defense contracts or focus on cost-optimized designs for industrial applications.
Market Dynamics
The proliferation of Gallium Nitride (GaN) semiconductor technology is the central structural force reshaping the rugged power supply market. This shift enables higher power densities and thermal efficiencies, creating a divergence between legacy silicon-based designs and next-generation modular power architectures.
Growth Catalysts
- 5G Infrastructure Expansion:The global build-out of 5G telecom networks requires ruggedized power supplies for outdoor base stations and remote cell sites, which must operate reliably across wide temperature and humidity ranges.
- Defense Modernization Programs:Initiatives in the United States and allied nations to upgrade military platforms, from ground vehicles to naval vessels, mandate compliance with standards like MIL-STD-810 for environmental endurance, driving demand for compliant power systems.
- Industrial Automation:The deployment of robotics and autonomous systems in harsh manufacturing, mining, and logistics environments necessitates rugged power solutions that can withstand constant vibration, electrical noise, and temperature extremes.
Market Restraints
- High Certification Costs:Achieving compliance with military standards such as MIL-STD-461 for electromagnetic interference involves extensive testing and specialized engineering, creating significant cost barriers for new entrants and smaller vendors.
- Thermal Management Complexity:Increasing power density in smaller form factors, a key benefit of GaN technology, presents significant challenges in dissipating heat, requiring advanced and often costly thermal engineering solutions.
- Long Product Lifecycles:Defense and aerospace programs require component availability for decades, creating a restraint where manufacturers must manage parts obsolescence and guarantee support for legacy systems, limiting design flexibility.
Strategic Opportunities
- Electric Aviation and eVTOLs:The emerging market for electric vertical take-off and landing aircraft and other urban air mobility platforms presents a new application space for lightweight, high-density, and extremely reliable DC-DC converters.
- Modular Power Architectures:Offering standardized, configurable power modules instead of fully custom monolithic units allows vendors to serve a wider range of applications, reduce engineering lead times, and enable easier field serviceability for end-users.
- Critical Infrastructure Hardening:Growing investments in grid modernization and securing critical infrastructure like water treatment facilities in countries such as India and Brazil create opportunities for industrial-grade rugged power supplies outside of the traditional defense sector.
Industry Challenges
- Component Traceability and Counterfeiting:Ensuring a secure supply chain for military-grade electronic components is a persistent challenge, with stringent traceability requirements necessary to prevent counterfeit parts from entering critical defense systems.
- Specialized Engineering Talent:A scarcity of power electronics engineers with specific expertise in high-frequency magnetics design, thermal management for sealed enclosures, and MIL-STD compliance testing hinders product development across the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rugged Power Supply Market |
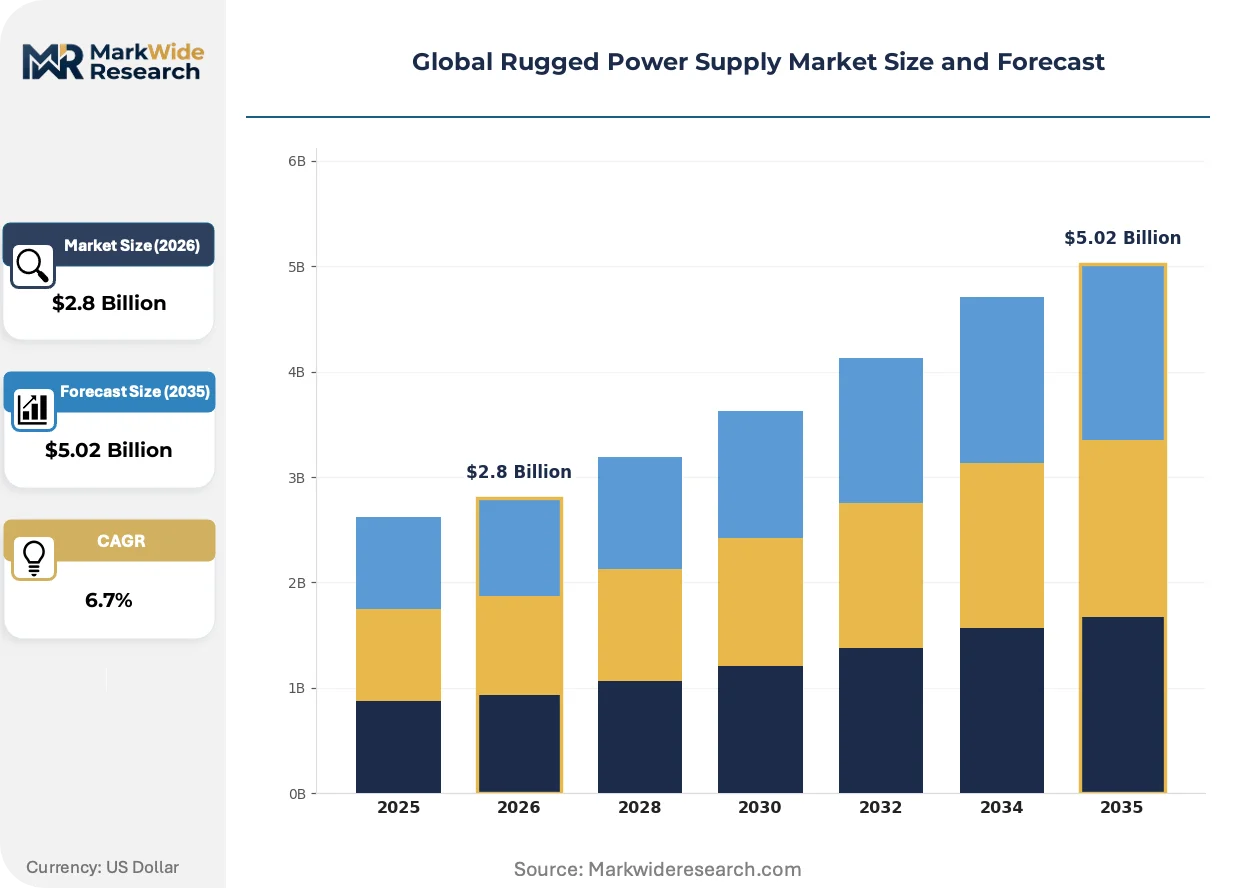
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC-DC Power Supply, DC-DC Converter, Uninterruptible Power Supply, Programmable Power Supply, Isolated Power Supply Technology: Switching, Linear, Modular, Encapsulated, Potting Application: Military Equipment, Aerospace Systems, Telecom Infrastructure, Transportation Electronics, Energy & Utilities End User: Defense Contractors, Avionics Manufacturers, Telecom Operators, Railway Companies, Power Grid Operators |
| Companies Covered | XP Power, TDK-Lambda Corporation, Vicor Corporation, Ametek, Astrodynse TDI, Advanced Conversion Technology, Mean Well Enterprises Co. Ltd., Delta Electronics Inc., Bel Power Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rugged Power Supply Market Strategic Shifts & Innovations
The fundamental architecture of rugged power systems is shifting from monolithic, application-specific units toward more flexible, component-based power delivery networks. This evolution is driven by advances in semiconductor materials and a changing procurement philosophy among major defense and industrial buyers.
Gallium Nitride (GaN) technology provides superior switching frequency and lower energy losses compared to traditional silicon. Aerospace and defense contractors are adopting GaN for next-generation radar, electronic warfare, and satellite communications systems. This technology is decomposing the concept of a single, large power supply box into a distributed network of smaller, high-density power modules placed closer to the point of load.
Regulatory frameworks like the European Union's RoHS directive restrict the use of hazardous substances, including lead in solder. This forces manufacturers to re-qualify products using lead-free alternatives, which can have different reliability characteristics under severe shock and vibration. The defense sector, which often relies on the long-term reliability of leaded solder, faces the most significant impact, often needing to secure specific exemptions or invest in extensive re-testing.
A shift in sourcing strategy is altering the value chain for complex systems. Prime contractors for military programs are increasingly specifying and directly procuring high-density power converter bricks from component specialists. This disintermediates traditional power supply system integrators, who previously would have designed and supplied the entire custom unit. This pattern is most visible within large-scale United States Department of Defense modernization programs.
Global Rugged Power Supply Market Segmentation
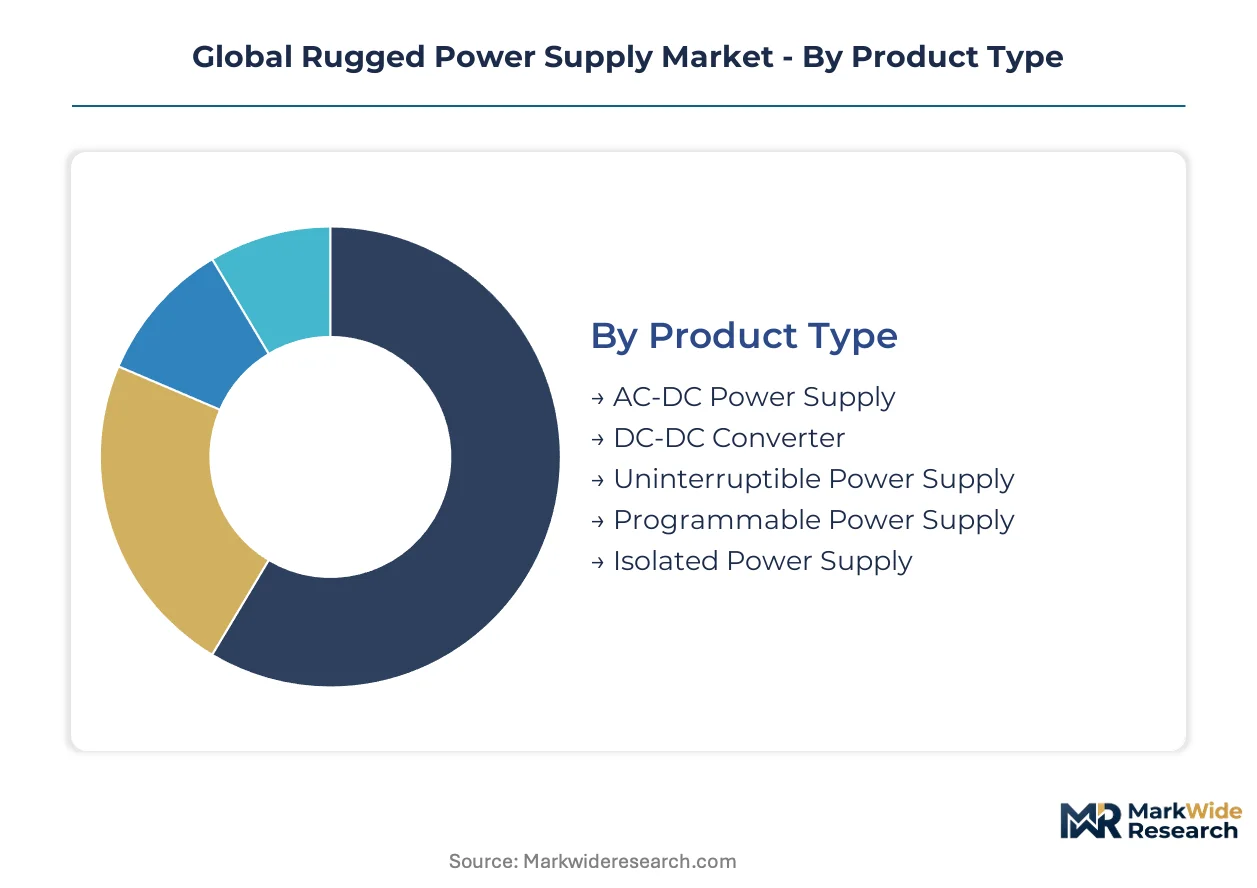
Segmentation within the rugged power supply market delineates distinct product characteristics, technological foundations, application requirements, and end-user profiles. This detailed breakdown helps identify specific demand pockets and competitive landscapes across critical infrastructure and defense sectors.
Product Type:
The rugged power supply market's product type segmentation highlights areas where functional alternatives exert pressure on traditional designs.
- AC-DC Power Supply:These units convert alternating current from a wall outlet or generator to direct current, providing stable power for various electronic systems. AC-DC supplies constitute the largest product type, serving a broad range of industrial and military applications globally.
- DC-DC Converter:DC-DC converters transform direct current from one voltage level to another, essential for distributed power architectures in complex systems. Demand for these converters is concentrating in aerospace systems, driven by requirements for lightweight, high-density power solutions.
- Uninterruptible Power Supply:These systems provide backup power during outages, ensuring continuous operation of critical equipment.
- Programmable Power Supply:Programmable units allow for dynamic adjustment of output voltage and current, used in testing and specialized industrial processes.
- Isolated Power Supply:Isolated power supplies prevent electrical noise and ground loops, crucial for sensitive instrumentation and safety-critical applications.
AC-DC Power Supply anchors the volume base while DC-DC Converters gain share at the steepest rate.
Technology:
Technology segmentation reflects the maturity curve of power conversion methodologies within rugged environments.
- Switching:Switching power supplies regulate output voltage by rapidly switching a power transistor on and off, offering high efficiency and compact size. This technology forms the backbone for most modern rugged power solutions due to its performance benefits.
- Modular:Modular power architectures utilize standardized, interchangeable power blocks that can be configured for various output requirements. This approach, often enabled by GaN technology, reduces engineering lead times and enhances field serviceability for complex systems.
- Linear:Linear power supplies provide very low noise output but are less efficient and larger than switching designs.
- Encapsulated:Encapsulated units are sealed within a protective compound, offering enhanced resistance to moisture, dust, and vibration.
- Potting:Potting involves filling a power supply enclosure with a resin, providing superior shock and vibration protection for extreme conditions.
Switching technology remains a foundational approach, while modular designs are rapidly expanding.
Application:
Application segments differentiate demand based on operational criticality and environmental severity.
- Military Equipment:This segment includes power systems for ground vehicles, naval vessels, and airborne platforms, requiring compliance with stringent MIL-STD environmental and EMI standards. Military equipment applications represent the dominant end-use, driven by extensive defense modernization initiatives in the United States.
- Telecom Infrastructure:Rugged power supplies support outdoor base stations, remote cell sites, and network equipment in 5G network build-outs. Telecom infrastructure is showing significant expansion due to the global deployment of next-generation communication networks.
- Aerospace Systems:Power solutions for aircraft, satellites, and urban air mobility platforms demand extreme reliability and lightweight designs.
- Transportation Electronics:This includes power for railway signaling, automotive, and marine electronics, operating under constant vibration and temperature fluctuations.
- Energy & Utilities:Applications in smart grids, oil & gas exploration, and renewable energy installations require robust power in harsh industrial settings.
Military equipment applications continue to drive substantial demand, with telecom infrastructure showing strong growth.
End User:
End user segmentation reflects distinct procurement patterns and compliance requirements across various industries.
- Defense Contractors:These entities procure rugged power supplies for integration into military platforms and systems, often requiring custom designs and long product lifecycles. Defense contractors in the United States are major buyers, driven by specific program requirements and MIL-STD compliance.
- Telecom Operators:Telecom operators deploy rugged power solutions for their network infrastructure, prioritizing cost-effectiveness, reliability, and wide temperature range operation. These operators are expanding their procurement for 5G network rollouts across various geographies.
- Avionics Manufacturers:Companies producing aircraft electronics require highly reliable, lightweight power supplies for flight-critical systems.
- Railway Companies:These users need rugged power solutions for signaling, control, and onboard systems that can withstand harsh rail environments.
- Power Grid Operators:Operators of electrical grids and critical infrastructure deploy industrial-grade rugged power supplies for control systems and remote monitoring.
Defense contractors significantly influence product design specifications, while telecom operators prioritize cost-effective, high-reliability solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global rugged power supply market exhibits a dynamic export-import balance, with specialized manufacturing hubs serving diverse international demands. Global demand for rugged power supplies drives both domestic production and international trade flows. Specific regions balance their internal needs with specialized manufacturing capabilities for these critical components.
United States
Extensive defense modernization initiatives and aerospace programs drive substantial demand for rugged power supplies in the United States. Compliance with MIL-STD-810 for environmental endurance and MIL-STD-461 for electromagnetic interference is non-negotiable for military applications. Major defense contractors in states like California and Virginia lead procurement for next-generation platforms.
Germany
Industrial automation, specialized machinery, and automotive electronics necessitate robust power solutions across Germany. The European Union's CE marking and RoHS directive influence product design and material selection for industrial applications. Bavaria and Baden-Württemberg host high-tech manufacturing clusters driving innovation in power electronics.
China
The rapid build-out of 5G infrastructure and expansion of industrial robotics create significant demand for rugged power supplies in China. Adherence to national GB standards for electronic products ensures operational reliability in harsh environments. The Yangtze River Delta region concentrates electronics manufacturing and telecom equipment production.
India
Telecom network expansion, including 5G rollouts, and ongoing defense procurement programs fuel the market for rugged power solutions in India. The Bureau of Indian Standards (BIS) mandates quality and safety for electronic components within the country. Bengaluru's electronics design and manufacturing ecosystem supports domestic and export demand.
Japan
High-speed rail systems, advanced industrial robotics, and satellite communications systems require highly reliable rugged power supplies in Japan. Japanese Industrial Standards (JIS) ensure product quality and performance across various industrial sectors. The Kanto region, including Tokyo, is a hub for precision manufacturing and industrial automation development.
Global Rugged Power Supply Market Key Industry Players
Concentration sits with specialized engineering firms and large-scale commercial power solution providers within the rugged power supply market. The market exhibits a tiered structure, differentiating between boutique, high-mix engineering for custom applications and high-volume, standardized manufacturing. Strategic archetypes include high-density modular specialists, cost-effective ruggedized variant providers, and high-specification aerospace and defense suppliers. Competitive moves involve technology licensing for GaN and strategic partnerships for defense contracts.
On the premium-tier vector, Vicor Corporation exemplifies expertise in high-density, modular power components for specialized systems. Delta Electronics Inc. leverages its scale in commercial power solutions to offer cost-effective ruggedized variants for industrial and telecom applications. Ametek positions its offerings primarily for the high-specification aerospace and defense sectors, where performance and reliability justify premium costs.
| Leading Market Players |
|---|
| XP Power |
| TDK-Lambda Corporation |
| Vicor Corporation |
| Ametek |
| Astrodynse TDI |
| Advanced Conversion Technology |
| Mean Well Enterprises Co. Ltd. |
| Delta Electronics Inc. |
| Bel Power Solutions |
| Others |
Cost & Logistics Intelligence
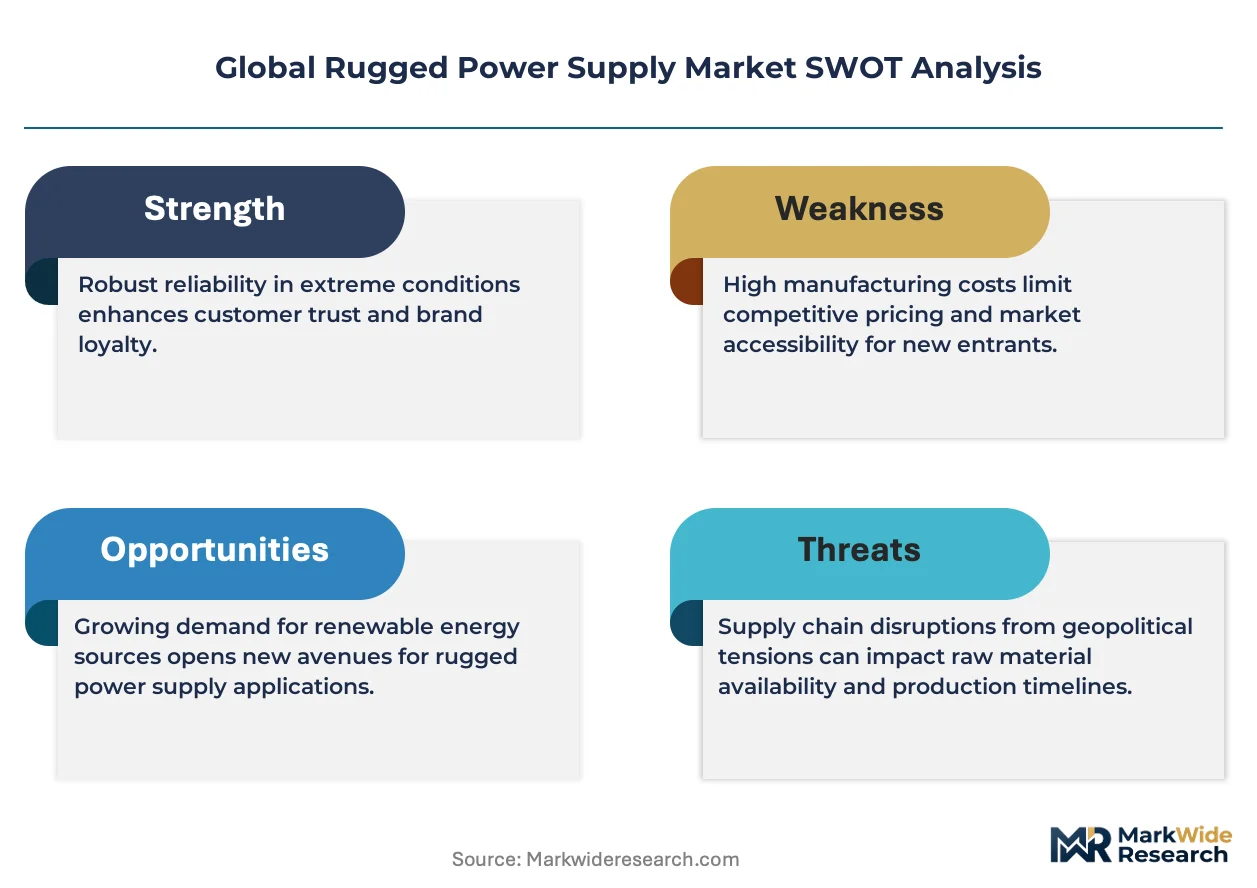
Extended lead times for specialized GaN components directly influence supply chain planning and exert upward pressure on pricing for advanced rugged power solutions. This dynamic shapes inventory strategies for both component manufacturers and system integrators.
Pricing Analysis
Configured-to-order pricing for high-specification defense applications commands a significant premium over standard, off-the-shelf industrial units. The dominant pricing model involves long-term contract-based offtake for military programs and per-unit transactional sales for commercial sectors. Price differentiation stems from stringent MIL-STD certification levels and extensive customization requirements. Pricing softness affects industrial and telecom applications due to competition from high-volume manufacturers. Defense contractors exhibit the lowest price sensitivity, prioritizing reliability and compliance.
Supply Chain Analysis
Rising inbound logistics costs, particularly for specialized semiconductor fabrication equipment, impact the overall cost structure for power supply manufacturers. Geographic supply centers for critical components include China for volume manufacturing, the United States for advanced GaN research, and Japan for high-precision components. The market relies on Gallium Nitride wafers and specialized magnetic materials. Component traceability and the risk of counterfeiting pose a significant structural vulnerability, especially for defense applications. Distribution runs through direct sales channels for defense prime contractors and specialized distributors for industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rugged power supply market functions as a defensive-moat story, primarily due to the regulatory entrenchment created by stringent military and industrial certification requirements. These high barriers to entry protect established players.
For Market Incumbents: Compound investment in GaN technology and advanced thermal management solutions to maintain performance leadership against emerging modular architectures. Secure long-term supply agreements for critical raw materials, such as specialized magnetic alloys, to mitigate supply chain disruption risks. Prioritize next-generation MIL-STD compliance initiatives to reinforce competitive advantages against smaller, less-certified entrants. Expand specialized engineering talent pools in high-frequency magnetics design to counter capability scarcity.
For New Entrants and Emerging Players: Lead with cost-optimized modular power architectures targeting industrial automation and critical infrastructure hardening segments, which present less stringent compliance hurdles than defense. Develop configurable DC-DC converters for the emerging electric aviation market, leveraging a lightweight, high-density value proposition. Focus on specific regional demand pockets, such as India's telecom network expansion, where established players may not optimize for local cost structures. Offer flexible service models to gain market share in maintenance-intensive industrial applications.
For Investors and Strategic Acquirers: Long-term, this sits as a critical infrastructure enabler play because reliable power is fundamental to defense, telecom, and industrial systems. Target acquisition archetypes include specialized GaN component manufacturers or niche providers of MIL-STD-certified power modules with strong intellectual property. A signal to watch is the increasing adoption rate of modular power architectures in defense modernization programs, indicating a shift from monolithic solutions. Assess companies with robust intellectual property portfolios in thermal management and high-frequency switching.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing for GaN | Securing access to advanced Gallium Nitride designs enhances power density and efficiency across product lines. |
| Capacity Expansion in Certified Facilities | Increasing production volume within MIL-STD compliant sites meets growing demand from defense programs. |
| Strategic Partnerships for Defense Contracts | Collaborating with prime contractors ensures integration into large-scale military modernization initiatives. |
| Modular Product Line Development | Offering configurable power modules reduces engineering lead times and expands application flexibility. |
| Talent Acquisition in Power Electronics | Recruiting specialized engineers addresses skill shortages in high-frequency magnetics and thermal management. |
Research Approach
Cross-validation between in-depth primary interviews and extensive secondary data analysis anchors the qualitative findings of this study. The research involved conversations with power electronics engineers, defense procurement officers, telecom network architects, and industrial automation integrators. Secondary sources included government defense spending reports, telecom infrastructure build-out plans, IEC safety standard documents, and company annual reports. This approach employed both bottom-up and top-down data triangulation.
Sensitivity analysis informed the projection of market dynamics over the analysis window, accounting for various growth scenarios. The analytical framework modeled segmentation dimensions including product type, technology, application, end user, and regional demand patterns. Compound annual growth rates were derived from historical trends and projected growth drivers, such as 5G rollout schedules and defense modernization budgets. This approach ensured a robust and adaptable forecast.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts or unforeseen material science breakthroughs would require recalibration. Forecasts reflect assumptions regarding regulatory stability and technological evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
North America Micro Inverter Market
Power Systems
Digital Inverter Market
Power Systems
Battery Racks Market
Power Systems
Automotive Power Electronics Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Power Inverter Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
PV Micro Inverters Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Telecom Power Systems Market
Power Systems
Asia Pacific Low Voltage Drives Market
Power Systems
EV Power Module Market
Power Systems
Power Semiconductor Market