
 Nimh Rechargeable Battery Market | 2026-2036
Nimh Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Nimh Rechargeable Battery Market Insights
Medical device demand is repositioning the end-use mix toward medium-capacity cylindrical formats. Panasonic leverages its vertical integration in Japan to sustain premium positioning for hospital-grade power systems. GP Batteries International Limited anchors European supply through its manufacturing base in Denmark, while Energizer competes aggressively in North American retail channels with standardized consumer packs.
Nickel-metal hydride rechargeable batteries store energy through hydrogen absorption in a metal alloy anode, typically offering nominal voltages of 1.2V and energy densities between 60-120 Wh/kg depending on formulation. The chemistry serves applications requiring safe, cost-effective cycling without the thermal runaway risks associated with lithium-ion alternatives. Cylindrical cells dominate industrial procurement due to established form-factor compatibility and automated assembly economics, while prismatic formats capture medical device contracts where space constraints override cost sensitivity. Fast charging infrastructure for power tools is expanding fastest among charging method segments, though standard charging retains the largest installed base in consumer electronics.
Japan's METI enforces JIS C 8712 standards for portable sealed cells, while China's SAMR administers GB/T 22084 compliance for domestic market access. The EU's REACH regulation restricts cadmium content in battery alloys, forcing reformulation across Asian supply chains. Stakeholders must monitor evolving chemistry patents and recycling mandates as jurisdictions tighten circular-economy requirements for nickel recovery.
Market Dynamics
Medical device procurement is redirecting cell-format demand toward medium-capacity cylindrical configurations, while industrial automation corridors in Germany and Japan's METI safety standards simultaneously reshape supply-side certification requirements.
Growth Catalysts
- Cold-weather reliability specifications:German tool OEMs mandate NiMH chemistry for outdoor industrial equipment operating below freezing, insulating the technology from lithium-ion displacement in Nordic climate zones.
- JIS C 8712 compliance expansion:Japan's METI standards for portable sealed cells are elevating quality thresholds that favor established chemistry platforms over unproven alternatives in hospital-grade applications.
- REACH cadmium restrictions:The EU's alloy reformulation mandates are accelerating R&D investment in rare-earth metal hydride compositions that improve energy density without toxic content.
Market Restraints
- Rare-earth metal price volatility:Lanthanum and cerium supply concentration in Chinese refining operations creates input cost instability for alloy anode production.
- Energy density ceiling:The 60-120 Wh/kg practical limit of metal hydride chemistry blocks penetration into electric mobility applications where lithium-ion dominates.
- GB/T 22084 certification friction:China's SAMR testing protocols extend market entry timelines for foreign cell manufacturers by six to nine months.
Strategic Opportunities
- Portable diagnostic equipment integration:Medium-capacity cylindrical formats are capturing design wins in point-of-care medical devices where thermal stability outweighs energy density priorities.
- Fast charging infrastructure deployment:Power tool OEMs are specifying rapid-charge protocols that leverage NiMH's superior charge acceptance at low temperatures versus lithium alternatives.
- Circular-economy nickel recovery mandates:The EU's battery recycling directives are creating closed-loop supply advantages for chemistry platforms with established hydrometallurgical recovery pathways.
Industry Challenges
- Electrochemical engineering talent scarcity:Universities are producing fewer specialists in aqueous electrolyte systems as academic research pivots toward solid-state lithium technologies.
- Legacy charger infrastructure incompatibility:Industrial tool fleets require simultaneous battery and charging station replacement, compressing customer switching economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nimh Rechargeable Battery Market |
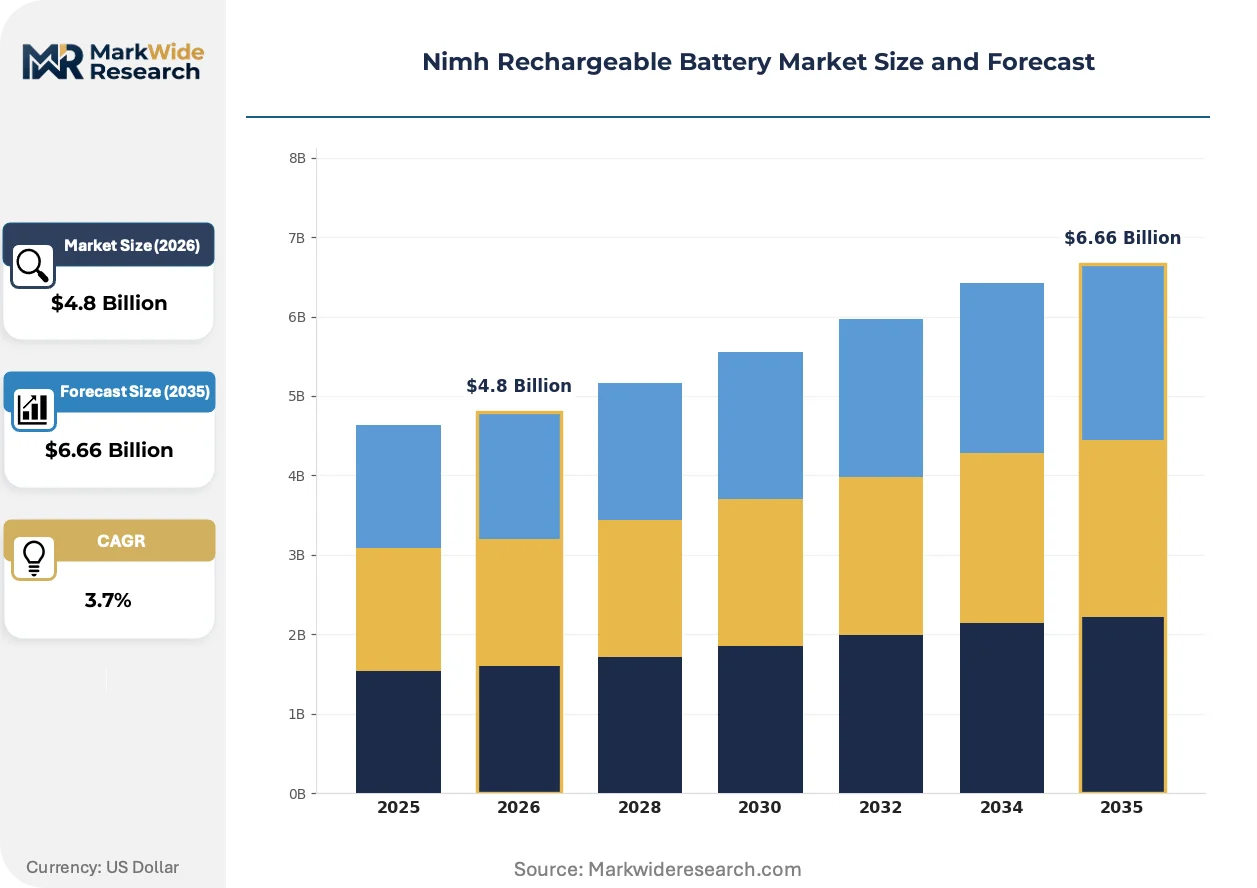
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Coin Cell, Button Cell End User: Consumer Electronics, Power Tools, Automotive, Medical Devices Charging Method: Standard Charging, Fast Charging, Solar Charging, USB Charging Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | Panasonic, FDK, Duracell, Energizer, Shenzhen Highpower Technology, GP Batteries International Limited, Hunan Corun New Energy, Nilar International AB, Guangzhou Great Power Energy & Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nimh Rechargeable Battery Market Trends and Innovations
Form-factor standardization and chemistry patent expirations are eroding historical barriers to entry, while regulatory pressure on recycling traceability accelerates process innovation across cell manufacturing.
Low-self-discharge (LSD) metal hydride formulations are consolidating market share in consumer electronics and residential backup power. The technology reduces monthly capacity loss from twenty percent to under three percent, enabling pre-charged retail packaging that eliminates consumer conditioning cycles. Japanese and Danish manufacturers are capturing premium positioning in this segment, compressing margins for conventional high-discharge product lines.
REACH cadmium restrictions and RoHS substance thresholds are forcing alloy reformulation across Asian supply chains. The EU's ECHA enforcement is rejecting traditional AB5 hydride compositions containing prohibited heavy metals, compelling migration toward AB2 and A2B7 rare-earth alternatives. Cell producers with captive rare-earth processing in Japan and China are absorbing compliance costs faster than trading-house dependent competitors.
Hospital procurement departments are consolidating vendor lists around dual-certified suppliers holding both JIS C 8712 and IEC 61951 compliance. This concentration is squeezing regional battery assemblers without in-house testing laboratories, while elevating contract values for integrated manufacturers with captive certification capabilities. German medical device OEMs are driving this pattern fastest, specifying cell-level traceability from raw material through finished pack.
Nimh Rechargeable Battery Market Segmentation
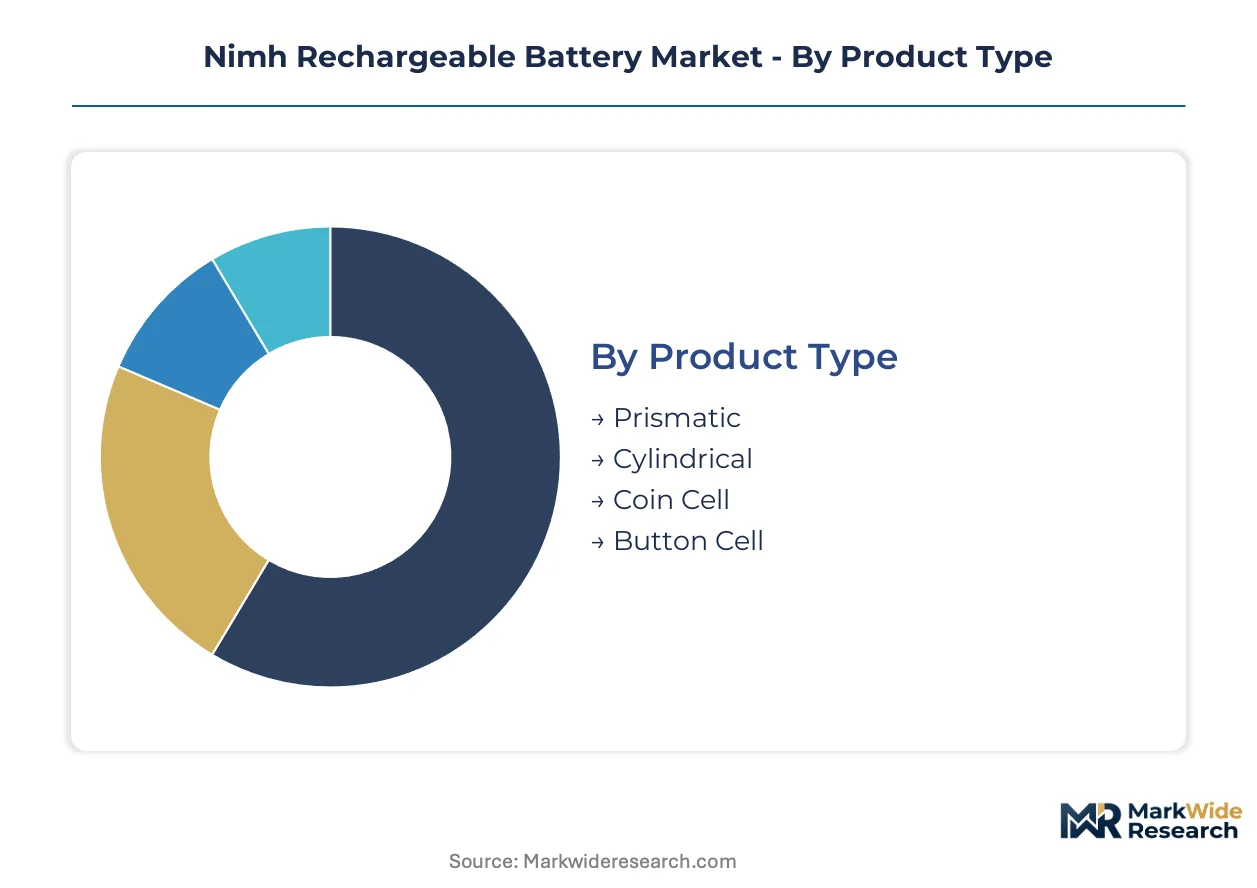
Segmentation in the NiMH rechargeable battery market reflects divergent technical requirements across replacement cycles. Tool OEMs and medical device manufacturers drive format-specific procurement, while charging infrastructure investments create distinct performance tiers.
Product Type:
Upgrade cycles vary dramatically by cell geometry, with cylindrical formats dominating industrial fleet replacements and prismatic cells capturing medical device redesigns.
- Cylindrical:Established 18650 and AA/AAA form factors enable automated pack assembly for power tools. German industrial automation corridors specify these cells for cold-weather reliability below freezing, insulating the format from lithium-ion displacement in Nordic climate zones.
- Prismatic:Flat rectangular cells maximize volumetric efficiency in portable diagnostic equipment. Medical device OEMs in Germany and Japan specify prismatic formats where space constraints override cost sensitivity, with JIS C 8712 compliance elevating quality thresholds.
- Coin Cell:Compact diameters serve hearing aids and wearable sensors.
- Button Cell:Low-profile designs fit legacy consumer electronics with minimal redesign.
Cylindrical sits at the top of the volume ranking, with prismatic climbing the fastest.
End User:
Customer procurement patterns separate into volume-driven replacement markets and specification-sensitive design-in segments.
- Power Tools:Professional tool fleets mandate NiMH chemistry for outdoor industrial equipment operating below freezing. Fast charging infrastructure deployment leverages the chemistry's superior charge acceptance at low temperatures versus lithium alternatives.
- Medical Devices:Hospital procurement departments consolidate vendor lists around dual-certified suppliers holding both JIS C 8712 and IEC 61951 compliance. Point-of-care diagnostic equipment specifies medium-capacity cylindrical formats where thermal stability outweighs energy density priorities.
- Consumer Electronics:Low-self-discharge formulations reduce monthly capacity loss from twenty percent to under three percent.
- Automotive:12V auxiliary systems and hybrid applications retain NiMH for safety-critical backup functions.
Power Tools commands the largest procurement volumes, while Medical Devices expands most quickly.
Charging Method:
Charging infrastructure investment intensity correlates with end-use downtime costs and fleet replacement schedules.
- Fast Charging:Rapid-charge protocols serve professional tool fleets where equipment utilization rates determine contract profitability. Power tool OEMs specify these systems for cold-weather job sites where lithium-ion charge rates degrade.
- Standard Charging:Overnight charging retains the largest installed base in consumer electronics and residential backup power. The method's lower infrastructure cost sustains margin in price-sensitive retail channels.
- USB Charging:Universal connector compatibility reduces charger proliferation in consumer segments.
- Solar Charging:Off-grid applications in remote industrial monitoring and emergency backup systems.
Standard Charging maintains the broadest installed base, with Fast Charging gaining share fastest.
Capacity:
Energy density positioning separates premium design-in opportunities from commodity replacement volumes.
- Medium Capacity:1500-2500 mAh cylindrical cells capture design wins in portable diagnostic equipment. Medical device manufacturers expanding procurement favor this tier for balancing cycle life against form factor constraints.
- High Capacity:2500-3000 mAh formulations approach the practical 60-120 Wh/kg ceiling of metal hydride chemistry. These cells serve power tool applications where runtime extension justifies alloy cost premiums.
- Low Capacity:Sub-1000 mAh cells serve backup memory and clock functions.
- Ultra High Capacity:Pushing alloy formulation limits for specialized industrial applications.
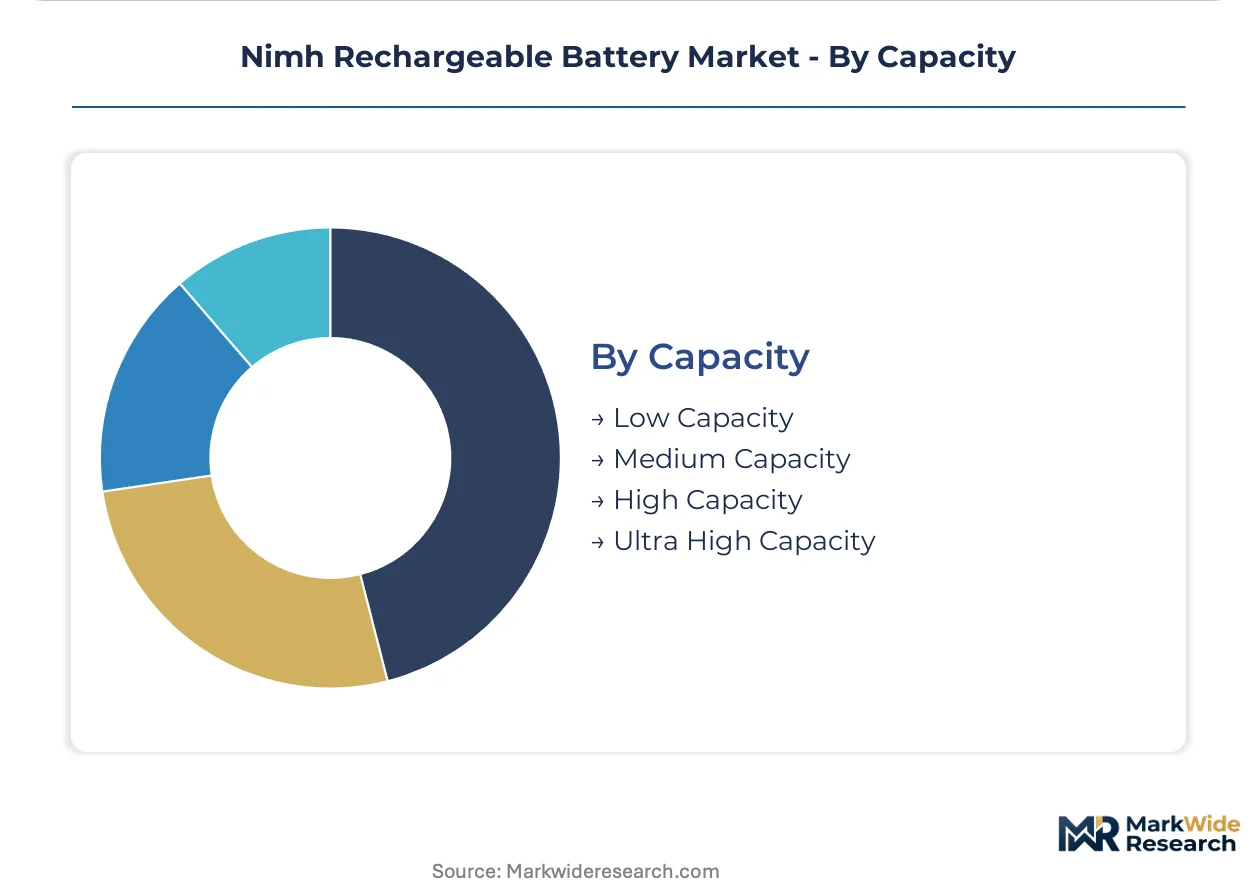
Medium Capacity leads procurement value, with High Capacity showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate to jurisdictions with streamlined certification pathways. Cost-of-compliance gaps between METI-certified Japanese facilities and GB/T-compliant Chinese operations are driving capacity reallocation decisions.
Japan
Hospital-grade power systems and portable diagnostic equipment anchor domestic demand for cylindrical cells. METI enforces JIS C 8712 standards that elevate quality thresholds for sealed portable cells. Tokyo-Osaka industrial corridor hosts integrated manufacturers with captive testing laboratories serving dual-certified medical device contracts.
China
Domestic procurement of medium-capacity cylindrical formats is accelerating for consumer electronics and industrial backup systems. SAMR administers GB/T 22084 compliance protocols that extend foreign market entry timelines. Shenzhen-Dongguan manufacturing cluster concentrates alloy anode production with captive rare-earth refining capabilities.
Germany
Tool OEMs specify NiMH chemistry for outdoor industrial equipment operating in sub-zero conditions. ECHA enforces REACH cadmium restrictions that compel AB5-to-AB2 alloy reformulation across supplier networks. Ruhr industrial automation corridor drives cold-weather reliability specifications for professional power tool fleets.
United States
Retail channel distribution of standardized consumer packs sustains volume demand for low-self-discharge formulations. EPA administers hazardous substance regulations affecting battery disposal and recycling infrastructure. Midwest industrial belt maintains legacy tool fleet replacement cycles with established charger infrastructure.
Denmark
European supply anchoring for medical device and industrial automation segments leverages regional logistics advantages. EU Battery Regulation mandates circular-economy nickel recovery pathways that favor established hydrometallurgical processes. Copenhagen-Malmo corridor concentrates pack assembly operations serving German OEM specifications.
Nimh Rechargeable Battery Market Competitive Landscape
Backward integration into rare-earth alloy production dominates the current landscape as manufacturers absorb REACH compliance costs. The vendor base stratifies between integrated chemistry platforms and trading-house-dependent assemblers. Three archetypes define positioning: captive-refining specialists, certification-heavy medical-grade suppliers, and retail-channel consumer pack distributors. M&A activity and capacity expansion in low-self-discharge formulations represent the dominant competitive vectors.
Among Japanese integrated manufacturers, Panasonic exemplifies the captive-certification archetype with METI-aligned quality systems. GP Batteries International Limited occupies a position bridging European medical device compliance and industrial automation supply. Energizer anchors the North American retail-channel tier with standardized consumer packaging strategies. These three represent distinct strategic postures rather than interchangeable competitors.
| Leading Market Players |
|---|
| Panasonic |
| FDK |
| Duracell |
| Energizer |
| Shenzhen Highpower Technology |
| GP Batteries International Limited |
| Hunan Corun New Energy |
| Nilar International AB |
| Guangzhou Great Power Energy & Technology |
| Others |
Pricing and Supply Chain Analysis
Electrochemical engineering talent concentration in East Asian manufacturing corridors connects labor-cost differentials to pricing-tier spreads across medical-grade and industrial battery segments. Alloy formulation expertise scarcity in Western markets widens the premium-to-economy price gap as certification-heavy producers capture margin from trading-house-dependent assemblers.
Pricing Analysis
Retailer markup layers in European medical device channels sustain premium positioning for dual-certified suppliers against direct-to-OEM discounting in Asian industrial procurement. Three-tier pricing structure across premium, standard, and economy levels separates JIS C 8712/IEC 61951 dual-certified cells from single-standard products and unbranded trading-house offerings. Price differentiation hinges on certification grade and captive rare-earth processing capability. Cost compression in economy-tier consumer packs is intensifying because of lanthanum and cerium price volatility. Professional tool fleets prove least price-sensitive due to cold-weather reliability specifications, while retail consumer electronics buyers drive the steepest volume discounts.
Supply Chain Analysis
Rare-earth metal hydride supply rests on Chinese refining operations for lanthanum and cerium, Japanese specialty alloy production for AB2 and A2B7 compositions, and Danish pack assembly for European medical device fulfillment. Raw material dependencies span rare-earth ore concentrates, nickel cathode materials, and potassium hydroxide electrolyte solutions. Single-source vulnerability in Chinese rare-earth refining creates structural risk for alloy anode cost stability. Distribution runs through integrated manufacturers with captive certification capabilities serving hospital procurement departments, alongside trading-house networks supplying price-sensitive industrial replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The NiMH rechargeable battery market functions as a stable compounder where medical device procurement and cold-weather industrial specifications generate replacement-driven revenue visibility. Regulatory compliance requirements for cadmium-free alloys and dual certification standards sustain incumbent advantages against lithium-ion substitution threats.
For Market Incumbents: Acquire captive rare-earth refining assets to absorb REACH compliance costs faster than trading-house-dependent competitors. Build AB2 and A2B7 alloy production capacity in Japan or China to secure supply chain control against lanthanum price volatility. Defensive positioning requires deepening hospital procurement relationships through JIS C 8712 and IEC 61951 dual certification maintenance, insulating premium tiers from emerging low-self-discharge specialists. For New Entrants and Emerging Players: Low-self-discharge formulation patents expiring create technology-first wedge opportunities in pre-charged retail consumer segments underserved by established Japanese and Danish manufacturers. Target white-space in portable diagnostic equipment medium-capacity cylindrical procurement where thermal stability specifications outweigh energy density priorities. Fast charging infrastructure deployment for Nordic power tool fleets offers the most penetrable industrial entry point, with go-to-market leverage through cold-weather reliability performance guarantees against lithium alternatives. For Investors and Strategic Acquirers: Valuations sit cheapest among trading-house-dependent assemblers without captive rare-earth processing or in-house testing laboratories. Long-term viability over a five-to-ten year window favors integrated chemistry platforms with backward integration into alloy production and established hydrometallurgical recycling pathways. Watch for inflection in EU Battery Regulation nickel recovery mandate enforcement timelines as the signal triggering consolidation premiums for closed-loop supply operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Refining | Captive lanthanum and cerium supply absorbs REACH-driven AB5-to-AB2 reformulation costs faster than competitors. |
| Dual Certification Investment | JIS C 8712 and IEC 61951 compliance opens hospital procurement vendor lists consolidating around traceable suppliers. |
| Low-Self-Discharge Capacity Expansion | Pre-charged retail packaging eliminates consumer conditioning cycles, capturing margin from conventional high-discharge lines. |
| Fast Charging Infrastructure Partnership | Cold-weather charge acceptance performance secures power tool OEM specifications against lithium-ion displacement. |
| Hydrometallurgical Recycling Buildout | Closed-loop nickel recovery pathways align with EU Battery Regulation circular-economy mandates for medical device contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cell manufacturing executives, medical device procurement managers, power tool OEM platform engineers, and rare-earth alloy specialists with secondary validation. Primary fieldwork drew from SEC 10-K filings, METI certification registries, EU ECHA substance restriction databases, and customs trade data for rare-earth concentrate flows. Bottom-up cell shipment modeling triangulated against top-down end-use equipment production estimates across portable diagnostic, industrial automation, and consumer electronics segments.
Historical reference periods anchored the projection horizon to documented replacement cycles in professional tool fleets and hospital equipment refresh schedules. Segmentation dimensions modeled include cell geometry, capacity tier, end-use application, charging method, and regional regulatory cluster. CAGRs were derived from equipment installed base aging analysis and procurement pattern elasticity to alloy cost movements. Forecast inputs incorporated REACH cadmium restriction compliance timelines and GB/T 22084 certification friction effects on foreign manufacturer market entry.
The model holds under stable rare-earth supply concentration and continued METI/GB/T certification divergence; deviation in lithium-ion cold-weather performance breakthroughs or EU recycling mandate acceleration would shift replacement rate assumptions. A small set of named triggers warrants ongoing watch: lanthanum export restriction policies, solid-state aqueous electrolyte research funding pivots, and medical device OEM vendor list consolidation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Space DC-DC Converters Market
Power Systems
Medium Voltage Drives Market
Power Systems
Global Power Semiconductor Switches Market
Power Systems
BCD Power IC Market
Power Systems
Global Next Generation Power Semiconductors Market
Power Systems
Pulse Generator Market
Power Systems
North America Electric Vehicle Power Inverter Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Liquid Cooling Systems Market
Power Systems
Synchronous Condenser Market
Power Systems
Laptop Battery Market
Power Systems
Southeast Asia Uninterruptible Power Supply (UPS) Market
Power Systems
South America DC Distribution Network Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Global Chip Power Inductor Market