
 Telecom Power Systems Market | 2026-2036
Telecom Power Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Power Systems Market Analysis
Chinese rectifier manufacturing is decoupling from European component sourcing as domestic semiconductor capacity expands. Huawei Technologies leverages in-house chip design to sustain vertical control over power conversion modules. Delta Electronics anchors its competitive position through manufacturing scale across Taiwan and Thailand production bases. Schneider Electric differentiates via embedded software-defined power management platforms for edge telecom sites.
Telecom power systems encompass rectifiers, inverters, power distribution units, and battery banks engineered to deliver conditioned DC or AC power with uptime exceeding 99.999% in base station environments. These systems integrate remote monitoring capabilities to enable predictive maintenance across geographically dispersed infrastructure. DC power systems dominate installed capacity in legacy mobile networks, while hybrid systems combining grid, diesel, and solar inputs represent the fastest-expanding technology segment as operators pursue Scope 2 emissions reduction targets. Rack-mounted installations command premium positioning in data center and central office applications where floor space constraints intensify.
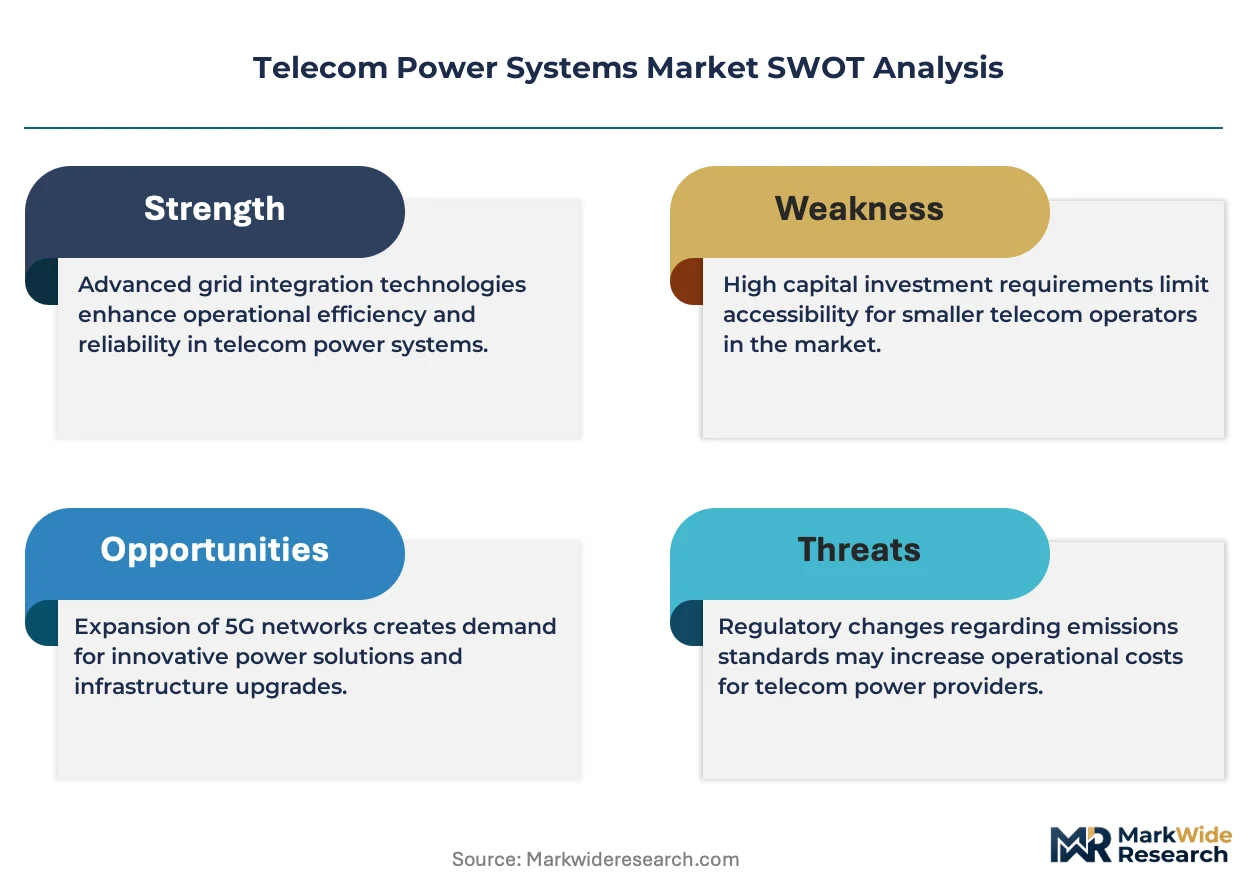
FCC equipment authorization requirements shape product compliance pathways for US-bound telecom power equipment, while the EU F-Gas Regulation and REACH constrain coolant and battery material selections across European deployments. India's BIS certification mandates and CEA grid interconnection standards govern product eligibility for domestic 5G infrastructure tenders. Stakeholders must monitor evolving carbon border adjustment mechanisms and local content thresholds that will determine competitive access across priority national markets.
Market Dynamics
5G network densification is forcing mobile operators to triple backup power deployments at macro and small cell sites, compressing procurement cycles and reshaping supplier qualification criteria toward lithium-ion compatibility and remote monitoring integration.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon coolants in thermal management systems is accelerating battery chemistry transitions toward solid-state and lithium-ion alternatives in European base station deployments.
- India PLI scheme:Production-linked incentives for domestic telecom equipment manufacturing are channeling rectifier and hybrid system procurement toward local certified vendors serving BharatNet rural broadband expansion.
- Edge computing infrastructure:Distributed micro data centers at cell tower bases are creating incremental demand for rack-mounted DC power systems with sub-50ms transfer switching capabilities.
Market Restraints
- Lithium supply concentration:Cathode active material processing capacity clusters in China, exposing non-Chinese system integrators to input cost volatility and forced supply chain reconfiguration under carbon border adjustment mechanisms.
- Lead-acid stranded assets:Existing battery bank installations at legacy 2G/3G sites create technical debt, as premature replacement cycles clash with ten-year depreciation schedules and tower company lease structures.
- REACH substance restrictions:The European Chemicals Agency's evolving candidate list for Substances of Very High Concern is complicating coolant and flame retardant selections, extending product recertification timelines by 12-18 months.
Strategic Opportunities
- Sub-Saharan Africa off-grid:Solar-diesel hybrid systems with lithium buffer storage are penetrating markets where grid reliability falls below 40%, bypassing traditional lead-acid incumbent positions.
- Software-defined power management:Convergence of telecom power controllers with AI-driven predictive analytics is opening recurring revenue streams through remote diagnostics subscriptions.
- US IRA clean energy credits:Investment tax credits for standalone energy storage are improving project economics for battery-backed telecom infrastructure serving tribal lands and rural coverage gaps.
Industry Challenges
- Multimode radio integration:Power systems must simultaneously support 2G voice, 4G LTE, and 5G NR active antenna arrays, complicating load profiling and thermal design at existing tower sites with constrained physical footprints.
- CEA grid interconnection certification:Indian central electricity authority standards for power quality and harmonic distortion are creating 6-9 month approval bottlenecks for imported rectifier systems, delaying 5G site commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Power Systems Market |
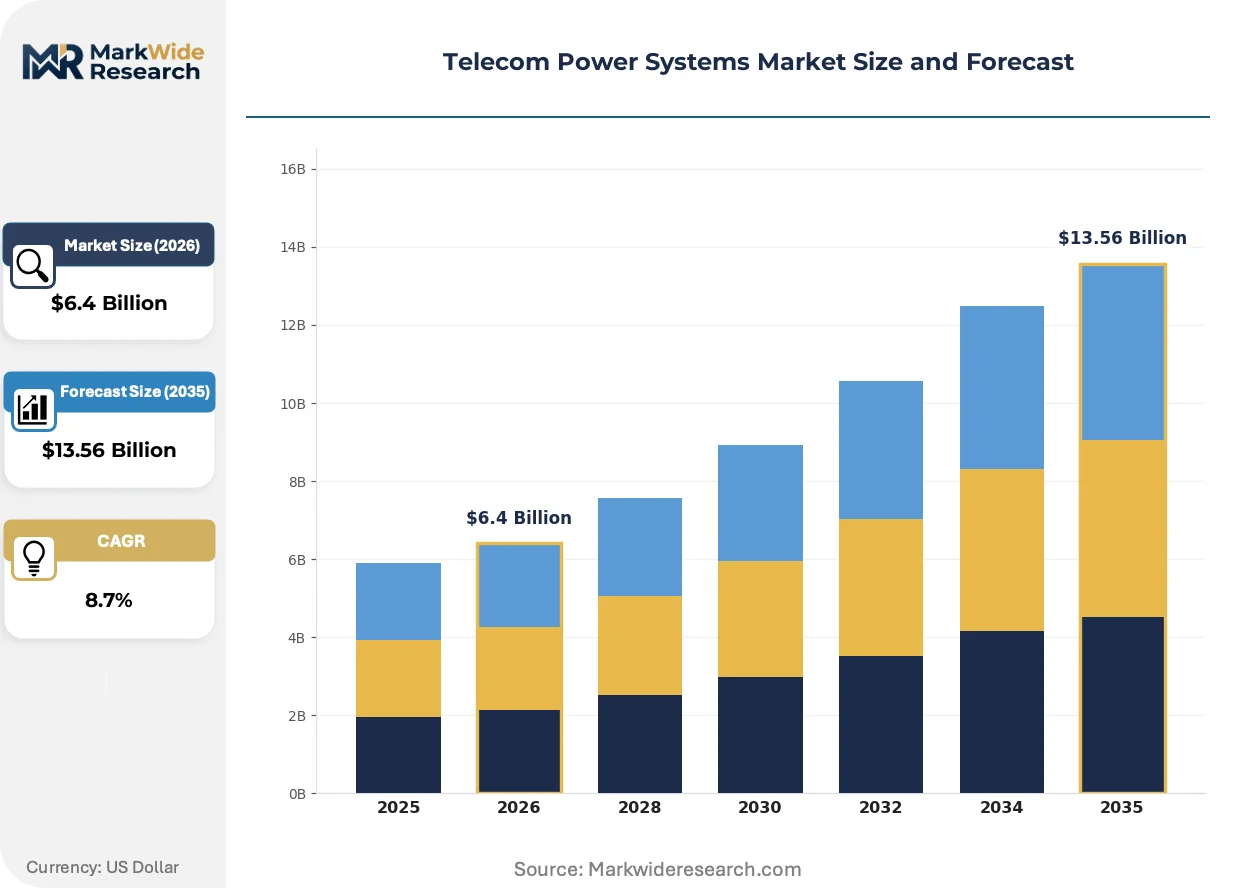
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectifiers, Inverters, Power Distribution Units, Batteries End User: Mobile Network Operators, Wireless Internet Service Providers, Data Centers, Telecommunications Equipment Manufacturers Technology: AC Power Systems, DC Power Systems, Hybrid Systems, Renewable Energy Integration Installation: Indoor, Outdoor, Pole-Mounted, Rack-Mounted |
| Companies Covered | Huawei Technologies, Delta Electronics, Eaton Corporation, Cummins, Schneider Electric, ZTE Corporation, General Electric, Vertiv Holdings, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Power Systems Market Emerging Trajectories
Telecom power architecture is fragmenting across three simultaneous vectors: chemistry transitions, software integration, and procurement model reinvention. Each vector carries distinct competitive implications for hardware incumbents and energy service entrants.
Wide-bandgap semiconductors using silicon carbide substrates are electrifying rectifier efficiency curves, cutting switching losses by half compared to legacy silicon IGBT designs. Tier-1 operators in Germany and Japan are specifying SiC-based power conversion modules for new 5G macro sites, enabling smaller heat sinks and higher power density in constrained equipment shelters. This technology compression is electrifying incumbent supplier margins while opening qualification pathways for semiconductor specialists without legacy telecom power heritage.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing coolant reformulation across European thermal management suppliers. The industrial consequence extends beyond material substitution to full system redesign, as dielectric fluid properties directly impact heat exchanger sizing and pump power budgets. Outdoor cabinet manufacturers serving Nordic and Alpine deployments are most affected, accelerating partnerships with fluorinated fluid alternatives certified under OECD screening protocols.
Power-as-a-service contracting is displacing capital purchase models among tower companies managing multi-tenant sites. Under this structure, system integrators retain battery asset ownership and charge availability-based fees, transferring performance risk from MNOs to equipment vendors. This financing innovation is most visible in Southeast Asian markets where currency volatility and interest rate spreads make traditional project finance prohibitively expensive for greenfield 5G rollout.
Telecom Power Systems Market Segmentation
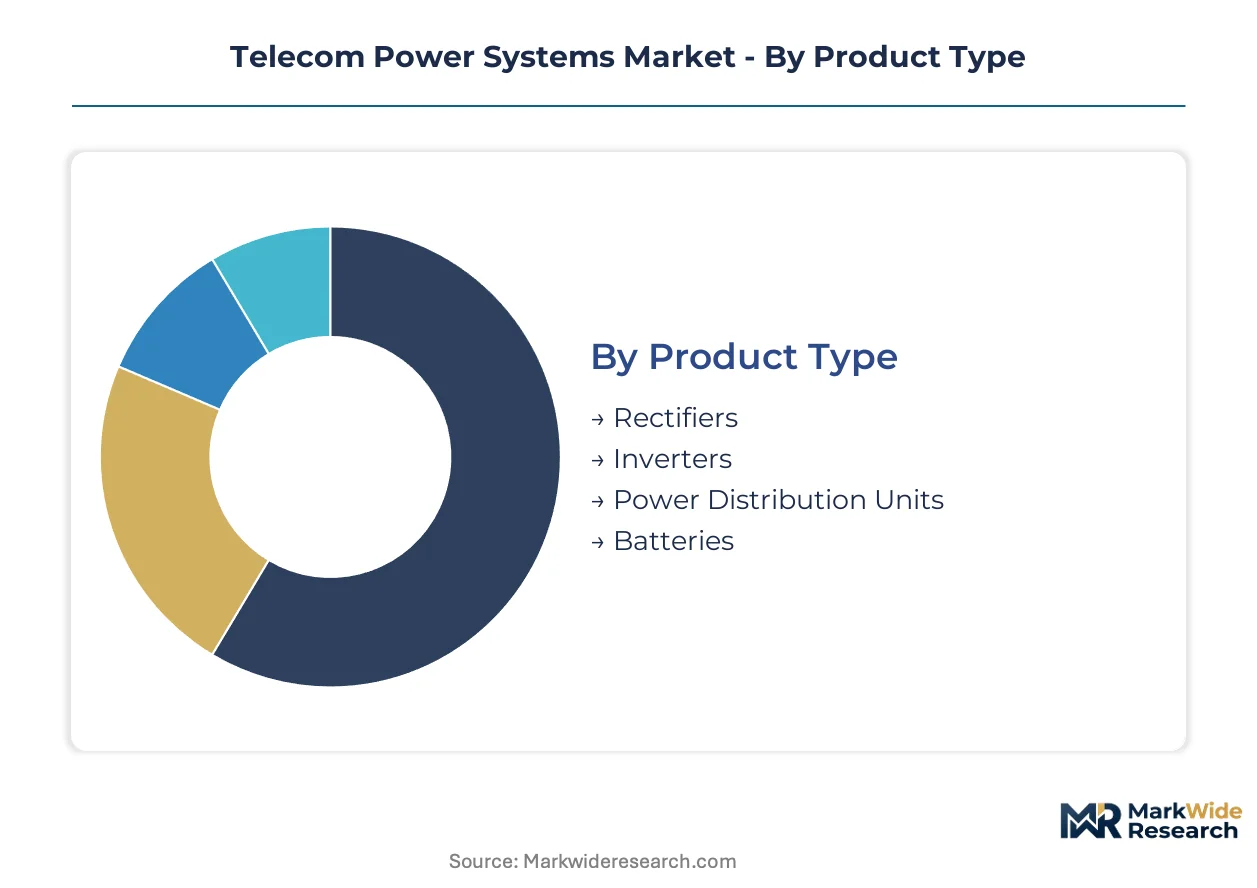
Telecom power systems fragment across four distinct axes that determine procurement patterns, technical specifications, and margin structures. Each segmentation layer reveals divergent capital requirements, installation constraints, and regulatory exposure that shape supplier positioning.
Product Type:
Rectifiers and batteries absorb the majority of upfront capital expenditure across greenfield deployments, with lithium-ion chemistry transitions amplifying unit costs.
- Rectifiers:AC-to-DC conversion modules employing silicon carbide substrates achieve efficiency gains above 96% in 5G macro site configurations. Indian tower companies under BharatNet rural broadband mandates are procuring high-capacity rectifiers with CEA grid interconnection certification, compressing supplier qualification timelines.
- Batteries:Lithium-ion alternatives displace lead-acid incumbent positions across European base stations subject to EU F-Gas Regulation phasedown requirements. German mobile network operators specify solid-state buffer storage for edge computing nodes, transferring thermal management burdens from coolant systems to battery chemistry.
- Inverters:DC-to-AC conversion equipment serving hybrid solar-diesel installations in sub-Saharan African markets with sub-40% grid reliability.
- Power Distribution Units:Rack-mounted PDUs with remote monitoring integration for data center and central office floor space constraints.
Most installed capacity flows through rectifiers. Expansion is steepest in batteries.
End User:
Customer type determines contract scale, technical sophistication requirements, and financing model preferences across the value chain.
- Mobile Network Operators:Tier-1 carriers in Germany and Japan specify SiC-based power conversion with embedded predictive analytics for 5G densification programs. MNO procurement cycles have compressed to 18-24 months amid backup power triplication mandates at macro and small cell sites.
- Data Centers:Hyperscale facilities and edge micro data centers demand rack-mounted DC systems with sub-50ms transfer switching capabilities. Thermal design priorities differ from outdoor base station applications, favoring liquid cooling integration.
- Wireless Internet Service Providers:Fixed wireless access providers in rural coverage gaps leverage IRA clean energy credits for standalone battery-backed infrastructure.
- Telecommunications Equipment Manufacturers:Original equipment manufacturers integrate power modules into radio access network hardware, requiring component-level certification rather than system-level validation.
Mobile network operators command the largest contract values. Data centers are climbing the fastest.
Technology:
Architecture selection governs emissions profiles, fuel diversity, and operational flexibility under divergent grid reliability conditions.
- DC Power Systems:Legacy 48V direct current infrastructure dominates installed base across 2G/3G/4G networks with ten-year depreciation schedules. Stranded asset risk intensifies as lithium-ion replacements accelerate.
- Hybrid Systems:Grid-diesel-solar combinations with lithium buffer storage are penetrating sub-Saharan African markets, bypassing traditional lead-acid positions through power-as-a-service contracting structures.
- AC Power Systems:Alternating current architectures for central office and data center applications with existing AC distribution infrastructure.
- Renewable Energy Integration:Solar PV and wind coupling with battery storage for Scope 2 emissions reduction targets in European and Japanese deployments.
DC systems retain the deepest installed base. Hybrid configurations show the steepest expansion trajectory.
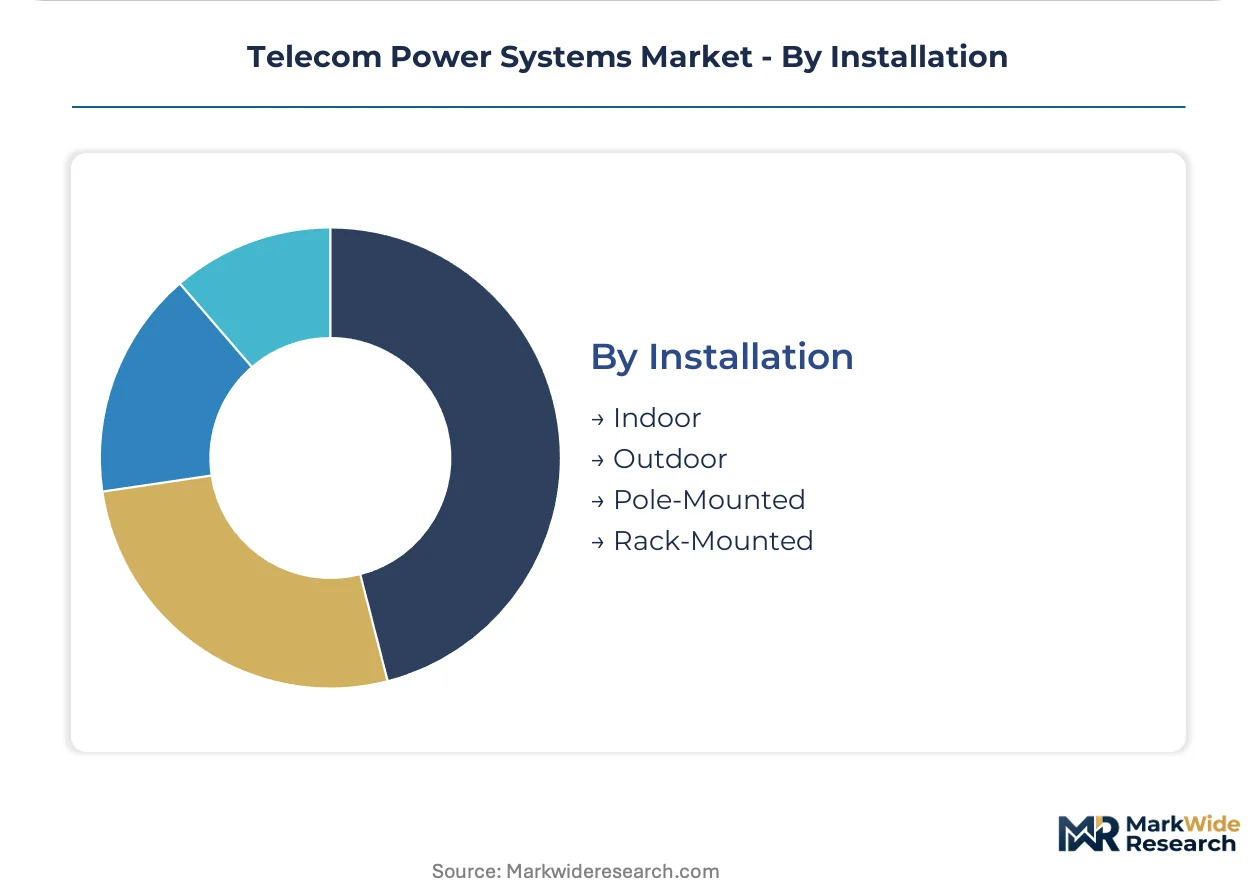
Installation:
Physical mounting constraints dictate thermal management approaches, environmental protection ratings, and maintenance access protocols.
- Outdoor:Weather-hardened cabinets with active cooling face REACH substance restrictions on fluorinated coolants, forcing Nordic and Alpine suppliers into dielectric fluid reformulation partnerships. Heat exchanger sizing and pump power budgets shift with each coolant generation.
- Rack-Mounted:Space-optimized installations command premium positioning in data centers and central offices where floor space constraints intensify. Sub-50ms transfer switching capabilities differentiate high-availability configurations.
- Indoor:Climate-controlled shelter installations for legacy macro sites with established HVAC infrastructure.
- Pole-Mounted:Compact configurations for 5G small cell densification with constrained physical footprints and multimode radio integration requirements.
Outdoor installations absorb the majority of new deployment volume. Rack-mounted systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing manufacturing footprints as compliance-cost gaps between jurisdictions widen. Chinese rectifier producers exploit domestic semiconductor capacity expansion to bypass European component dependencies, while Indian PLI incentives pull assembly operations away from traditional ASEAN bases.
India
BharatNet rural broadband mandates and aggressive 5G densification targets are compressing procurement cycles for rectifiers and hybrid power systems. The CEA grid interconnection standards create 6-9 month certification bottlenecks for imported equipment, channeling demand toward BIS-certified domestic vendors. Manufacturing clusters in Gujarat and Tamil Nadu are scaling lithium-ion battery assembly for tower company power-as-a-service contracts.
United States
IRA clean energy credits for standalone energy storage are improving project economics for battery-backed infrastructure serving tribal lands and rural coverage gaps. FCC equipment authorization requirements shape compliance pathways for power conversion hardware. Tower companies in Texas and the Mountain West are tripling backup power deployments at macro and small cell sites.
Germany
Tier-1 mobile operators specify silicon carbide-based power conversion modules for 5G macro sites, enabling smaller heat sinks in constrained equipment shelters. The EU F-Gas Regulation phasedown accelerates battery chemistry transitions away from coolant-dependent thermal management. Industrial concentration in Bavaria and Baden-Württemberg anchors rectifier system integration for European export markets.
China
Domestic semiconductor foundry expansion supports vertical control over power conversion module supply chains. MIIT dual carbon goals and GB standards for base station energy efficiency are tightening operational requirements. Manufacturing bases in Shenzhen and Suzhou are shipping SiC-based rectifiers to Belt and Road telecom infrastructure projects.
Japan
METI efficiency standards and earthquake resilience codes drive demand for sub-50ms transfer switching capabilities in rack-mounted DC systems. Solid-state battery buffer storage specifications for edge computing nodes are transferring thermal management burdens from coolant systems to chemistry. Nagoya and Osaka industrial corridors concentrate precision power electronics manufacturing for domestic and Southeast Asian markets.
Telecom Power Systems Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined power management and power-as-a-service contracting structures. The supplier base stratifies across three maturity levels: legacy electrical equipment conglomerates with broad industrial portfolios, specialized telecom power pure-plays, and semiconductor specialists leveraging wide-bandgap substrate advantages. Consolidation pressure intensifies as lithium-ion chemistry transitions and REACH coolant reformulation requirements raise R&D minimums. Dominant competitive moves include strategic partnerships with fluorinated fluid alternatives suppliers and geographic expansion through CEA-certified manufacturing in India.
Within the integrated systems tier, Huawei Technologies exemplifies vertical control through in-house chip design, while Delta Electronics anchors scale-driven positioning across Taiwan and Thailand production bases. Schneider Electric occupies the software-differentiation vector with embedded power management platforms for edge telecom sites. These three entities represent distinct strategic archetypes: captive semiconductor integration, multi-site manufacturing scale, and embedded software value-add.
| Leading Market Players |
|---|
| Huawei Technologies |
| Delta Electronics |
| Eaton Corporation |
| Cummins |
| Schneider Electric |
| ZTE Corporation |
| General Electric |
| Vertiv Holdings |
| ABB |
| Others |
Supply Flow & Price Mechanics
Tower company power-as-a-service contracts in Southeast Asia concentrate equipment ownership among specialized system integrators, compressing distributor margins while anchoring long-term pricing discipline through availability-based fee structures rather than transactional hardware sales.
Pricing Analysis
Distributor margins on rectifier systems compress as Chinese producers with captive semiconductor capacity bypass traditional component layers and sell direct to BharatNet-certified integrators in India. Three-tier pricing structure across premium SiC-based modules, standard silicon IGBT configurations, and economy-grade lead-acid compatible systems differentiates on certification grade and remote monitoring bundling. Pricing pressure stems from lithium cathode active material processing concentration in China exposing non-Chinese integrators to input cost volatility. Rural broadband tower companies exhibit highest price sensitivity, while German Tier-1 mobile network operators prioritize efficiency specifications over unit cost.
Supply Chain Analysis
Freight costs from Thailand and Taiwan production bases to Indian CEA certification facilities have risen as manufacturing clusters consolidate around Gujarat and Tamil Nadu lithium-ion assembly hubs. Silicon carbide substrate supply concentrates in China, Japan, and the United States, while rectifier manufacturing draws from Taiwan, Thailand, and domestic Chinese capacity. Supply chain risk centers on single-source vulnerability for wide-bandgap semiconductor substrates under carbon border adjustment mechanisms. Distribution runs through tower company procurement consortia and mobile network operator direct contracts, bypassing traditional electrical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The telecom power systems market functions as a stable compounder, with 5G densification mandates forcing sustained backup power deployment cycles across mobile network operator capital programs.
For Market Incumbents: Cement market position through backward integration into lithium-ion battery assembly in CEA-certified Indian manufacturing clusters, defending against pure-play energy service entrants capturing power-as-a-service revenue pools. Prioritize REACH-compliant coolant reformulation partnerships with Nordic fluorinated fluid alternatives suppliers to preempt regulatory recertification delays. For New Entrants and Emerging Players: Begin with software-defined power management platforms targeting edge computing micro data center deployments at cell tower bases, where sub-50ms transfer switching capabilities command premium positioning. Sub-Saharan African solar-diesel hybrid installations offer the most penetrable white space, bypassing entrenched lead-acid incumbents through availability-based contracting structures. For Investors and Strategic Acquirers: Valuations sit cheapest among semiconductor specialists with wide-bandgap substrate expertise but lacking legacy telecom power heritage, as SiC efficiency gains electrify qualification pathways. Acquisition targets with CEA certification and Indian manufacturing presence offer the strongest long-term viability through BharatNet procurement concentration. Watch for carbon border adjustment mechanism implementation as the critical inflection signal for supply chain reconfiguration urgency.| Strategic Initiative | Industry Significance |
|---|---|
| CEA Certification Investment | Unlocks eligibility for BharatNet rural broadband tenders in India. |
| Silicon Carbide Module Development | Captures efficiency premiums from German and Japanese Tier-1 operator specifications. |
| Power-as-a-Service Contracting | Transfers performance risk from mobile operators to equipment vendors in Southeast Asia. |
| REACH-Compliant Coolant Partnership | Prevents 12-18 month product recertification delays in European deployments. |
| Indian Lithium-Ion Assembly Scale-Up | Secures PLI scheme incentives and bypasses import certification bottlenecks. |
Methodological Framework
Direct dialogue with mobile network operator procurement directors, tower company engineering executives, rectifier system integration specialists, and CEA certification consultants anchored qualitative grounding, cross-referenced against TRAI deployment statistics, BIS certification databases, SEC filings from listed equipment vendors, and EU F-Gas Regulation implementation trackers. Bottom-up unit deployment estimates across India, Germany, the United States, China, and Japan converged with top-down market sizing derived from mobile operator capital expenditure disclosures.
Segmented outputs across product type, end user, technology, and installation configuration populated the analytical framework across the projection horizon, with CAGRs derived from regression analysis of historical procurement cycles against 5G site densification trajectories. Forecast inputs incorporated silicon carbide substrate supply expansion timelines, lithium-ion chemistry transition adoption curves, and power-as-a-service contract penetration rates by region.
Several conditions sit outside the modeled scope, including unforeseen REACH substance list expansions, abrupt carbon border adjustment mechanism enforcement dates, and geopolitical disruptions to semiconductor substrate trade flows. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Gan-Powered Chargers Market
Power Systems
Battery Charge Controller Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Harmonic Generators Market
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Flyback Transformer Market
Power Systems
Grid Forming Inverters Market
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Integrated UPS Market
Power Systems
Synchronous Condenser Market
Power Systems
US Variable Frequency Drive Market
Power Systems
Burner Management System (BMS) Market