
 Voltage Tester Market | 2026-2036
Voltage Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Voltage Tester Market Outlook
Industrial distribution channels is tilting toward specialized electrical supply houses and direct manufacturer portals. Fluke Corporation leverages its calibration laboratory network to sustain premium positioning among utility clients. Klein Tools anchors its volume position through dominant shelf space at North American hardware retail chains. Megger Group Limited specializes in high-voltage insulation testers for power generation applications where safety certification requirements are most stringent.
A voltage tester is a portable electrical safety instrument designed to detect the presence or absence of voltage in conductors, circuits, or equipment, typically operating across ranges from 12V to 1000V AC/DC with CAT III or CAT IV overvoltage protection ratings. Its primary commercial purpose is to prevent electrical shock and arc-flash incidents by enabling qualified personnel to verify de-energization before maintenance or troubleshooting procedures. Digital testers with true RMS capability capture the fastest-growing margin pools as variable-frequency drives and switching power supplies proliferate in industrial environments. Non-contact technology segments are displacing traditional contact methods in residential and light commercial inspections where speed and convenience outweigh laboratory-grade precision requirements.
IEC 61010 safety standards govern instrument design and overvoltage category ratings across European and Asia-Pacific markets, while NFPA 70E mandates live-work verification protocols that directly specify tester deployment in US industrial facilities. OSHA electrical safety regulations and the EU's CE marking directives create compliance-driven replacement cycles that insulate demand from pure construction cyclicality. Stakeholders must monitor evolving smart voltage detection protocols and wireless data-logging integration as these features redefine product differentiation and service revenue attachment in contractor tool portfolios.
Market Dynamics
Smart grid deployment and IEC 61010 certification upgrades are forcing simultaneous hardware replacement cycles across utility, industrial, and residential inspection workflows. This dual pressure—technological obsolescence plus safety mandate compliance—compresses purchasing decisions and elevates specification authority toward centralized procurement functions.
Growth Catalysts
- NFPA 70E arc-flash mandates:US industrial facilities must verify de-energization with rated testers before live work, creating mandatory replacement demand independent of construction cycles.
- Variable-frequency drive proliferation:Industrial motor control systems generate non-sinusoidal waveforms that require true RMS measurement capability, invalidating legacy average-responding instruments.
- India:Rural electrification programs and distribution network expansion under the national power ministry are generating first-time tester demand among state electricity board maintenance crews.
Market Restraints
- Semiconductor input volatility:Precision analog-to-digital converters and isolated power management ICs face allocation constraints that extend lead times for CAT IV-rated instruments.
- China:Domestic GB standard certification requirements create technical barriers for imported instruments, fragmenting supply availability across Asia-Pacific markets.
- Non-contact infrared thermography:Thermal imaging cameras with voltage detection modes substitute for traditional testers in preventive maintenance routines, compressing unit demand in some industrial accounts.
Strategic Opportunities
- Brazil:ANVISA-equivalent electrical safety enforcement in healthcare facilities creates certified tester demand for biomedical equipment maintenance protocols.
- Wireless data-logging integration:Bluetooth-enabled testers feeding mobile CMMS platforms enable predictive maintenance subscription revenue models.
- EU Green Deal building renovation wave:Mandatory energy audits of commercial structures require electrical safety verification, expanding tester deployment among HVAC and lighting retrofit contractors.
Industry Challenges
- CAT IV certification timelines:Third-party laboratory testing for 1000V overvoltage category validation extends product development cycles by 8-14 months.
- Legacy analog tester replacement:Skilled electrician preference for tactile rotary-selector interfaces slows digital touchscreen adoption in mature workforce segments.
- Calibration infrastructure gaps:Field service organizations struggle to maintain traceable voltage reference standards across distributed technician fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voltage Tester Market |
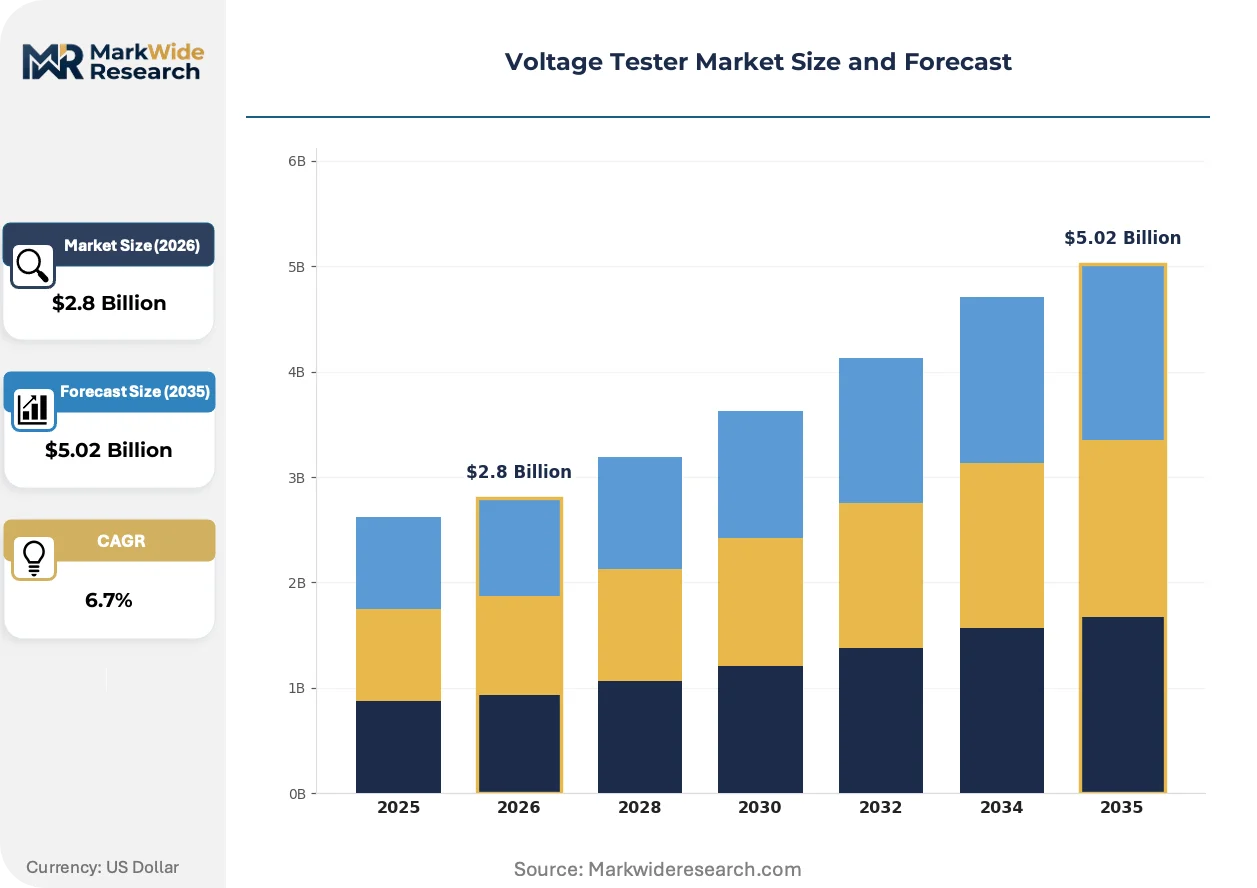
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Tester, Analog Tester, Clamp Meter, Multifunction Tester Technology: Non-Contact, Contact, True RMS, Smart Voltage Detection Application: Electrical Maintenance, Troubleshooting, Circuit Testing, Home Inspections End User: Electrical Contractors, DIY Enthusiasts, Industrial Technicians, Power Utility Providers |
| Companies Covered | Fluke Corporation, Klein Tools, Amprobe, IDEAL Industries, Megger Group Limited, Extech Instruments, Southwire Company, Hioki E.E. Corporation, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voltage Tester Market Strategic Shifts
Tester functionality is converging with adjacent diagnostic categories as contractors demand consolidated tool kits. Manufacturers respond by embedding multi-parameter sensing within familiar form factors, blurring historical product boundaries.
Non-contact voltage detection is hybridizing with thermal imaging sensors to produce combined electrical safety and temperature diagnostic instruments. Industrial maintenance teams in US manufacturing plants adopt these hybrid units to reduce tool belt weight and inspection cycle time. The convergence compresses standalone thermal camera demand while elevating price realization for integrated instruments.
OSHA electrical safety regulations now explicitly reference verification testing procedures, embedding instrument specifications within enforceable workplace standards. Industrial facility safety managers must document compliance through calibrated, rated equipment. US petrochemical and data center operators respond by centralizing tester procurement through corporate safety departments rather than decentralized maintenance budgets.
Certification-driven preference shifts are elevating specification authority toward third-party calibration providers. Large electrical contractors in Germany and France now require documented traceability chains before accepting tester deployment on commercial sites. This behavior concentrates demand toward manufacturers with captive metrology laboratory networks, compressing shelf-space availability for uncertified economy-tier alternatives.
Voltage Tester Market Segmentation
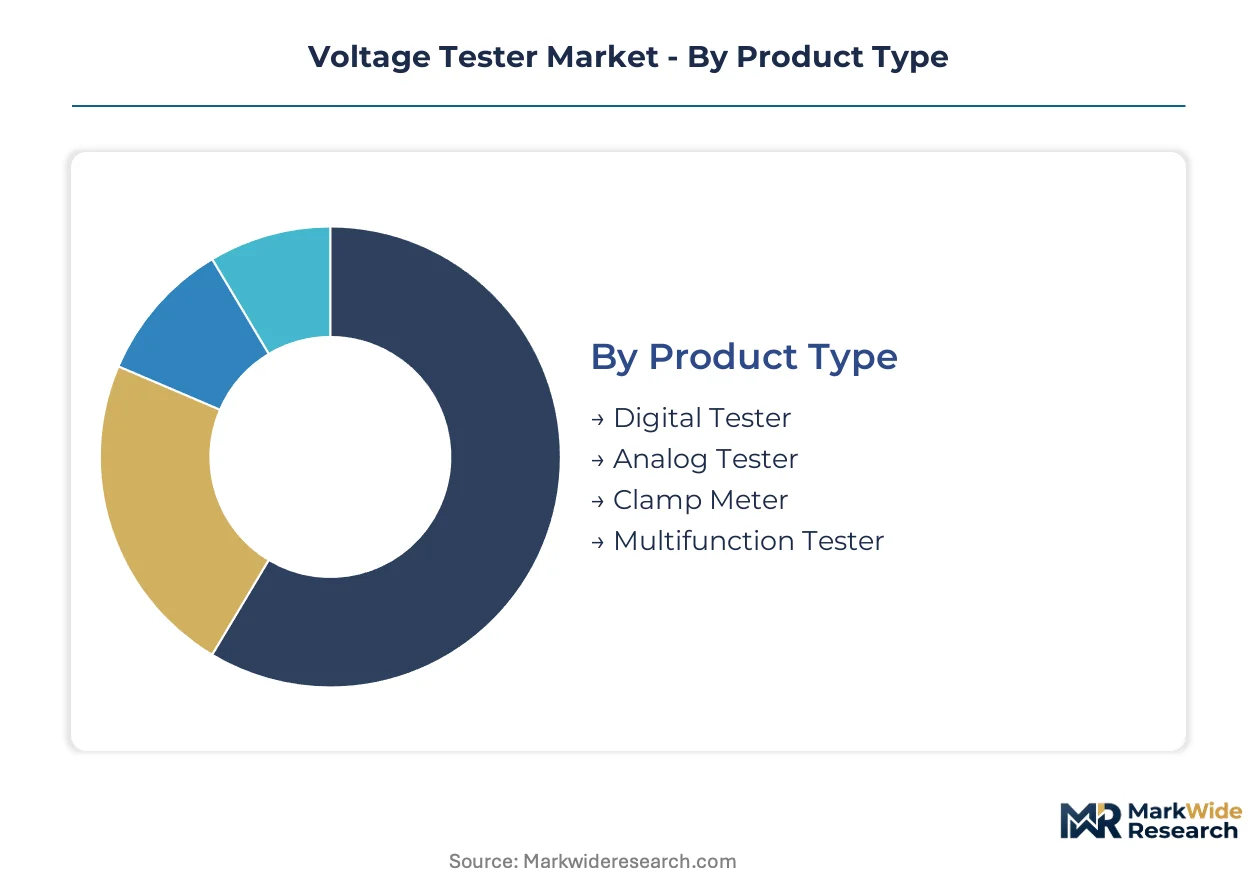
Voltage tester segmentation reveals distinct service lifecycle patterns across product architectures. Calibration frequency, warranty attachment rates, and field repair complexity vary sharply between digital platforms and legacy analog units, reshaping manufacturer aftermarket strategies.
Product Type:
After-sales service intensity diverges most acutely across this dimension, with digital architectures demanding firmware updates and annual calibration protocols that analog units never required.
- Digital Tester:Microprocessor-based instruments with LCD displays and data-logging capability require traceable calibration certificates per IEC 61010. Industrial facilities in Germany and France now mandate documented metrology chains before site deployment, elevating specification authority toward manufacturers with captive laboratory networks.
- Analog Tester:Electromechanical needle-movement devices with tactile rotary selectors persist among veteran electricians who distrust touchscreen interfaces. Skilled workforce preference slows replacement cycles in mature North American contractor segments despite inferior measurement precision.
- Clamp Meter:Current-measuring jaws with voltage detection modes serve HVAC technicians performing dual-parameter diagnostics without circuit interruption.
- Multifunction Tester:Combined insulation, continuity, and loop-impedance instruments target European electrical contractors conducting mandatory periodic inspection certifications.
Digital testers hold the largest share; momentum sits with multifunction platforms as regulatory inspection scopes expand.
Technology:
Cost tier stratification separates premium sensing architectures from commodity proximity detection, with price multiples exceeding 4x between entry-level and laboratory-grade specifications.
- Non-Contact:Proximity-based electric field detection operates through insulation barriers without metallic contact. Residential inspectors and light commercial electricians in the United States favor these units for speed during preliminary safety checks where absolute precision is secondary.
- Contact:Direct metallic probe connection delivers measurement certainty required for lockout-tagout verification under OSHA electrical safety regulations. Petrochemical and data center operators centralize procurement through corporate safety departments to ensure rated equipment compliance.
- True RMS:Root-mean-square conversion algorithms capture accurate readings from variable-frequency drives and switching power supplies with non-sinusoidal waveforms.
- Smart Voltage Detection:Bluetooth-enabled units with wireless CMMS integration enable predictive maintenance subscription revenue models among industrial facility managers.
Contact technology anchors volume; smart voltage detection gains share fastest as connectivity becomes standard in utility modernization programs.
Application:
Customer type concentration varies by task complexity, with industrial accounts dominating high-value troubleshooting while residential construction drives home inspection volumes.
- Electrical Maintenance:Scheduled preventive procedures in manufacturing plants and utility substations require CAT III or CAT IV rated instruments with documented calibration histories. US industrial facilities respond to NFPA 70E mandates by verifying de-energization before live work, creating mandatory replacement demand independent of capital expenditure cycles.
- Troubleshooting:Diagnostic fault-finding in energized circuits demands true RMS capability as motor control systems proliferate with non-sinusoidal outputs.
- Circuit Testing:Verification of proper installation and conductor integrity occurs across new construction and renovation projects.
- Home Inspections:Pre-purchase electrical safety assessments in residential real estate transactions favor lightweight non-contact units for rapid outlet and panel screening.
Electrical maintenance commands premium pricing; home inspections represent the steepest expansion trajectory as housing transaction volumes recover.
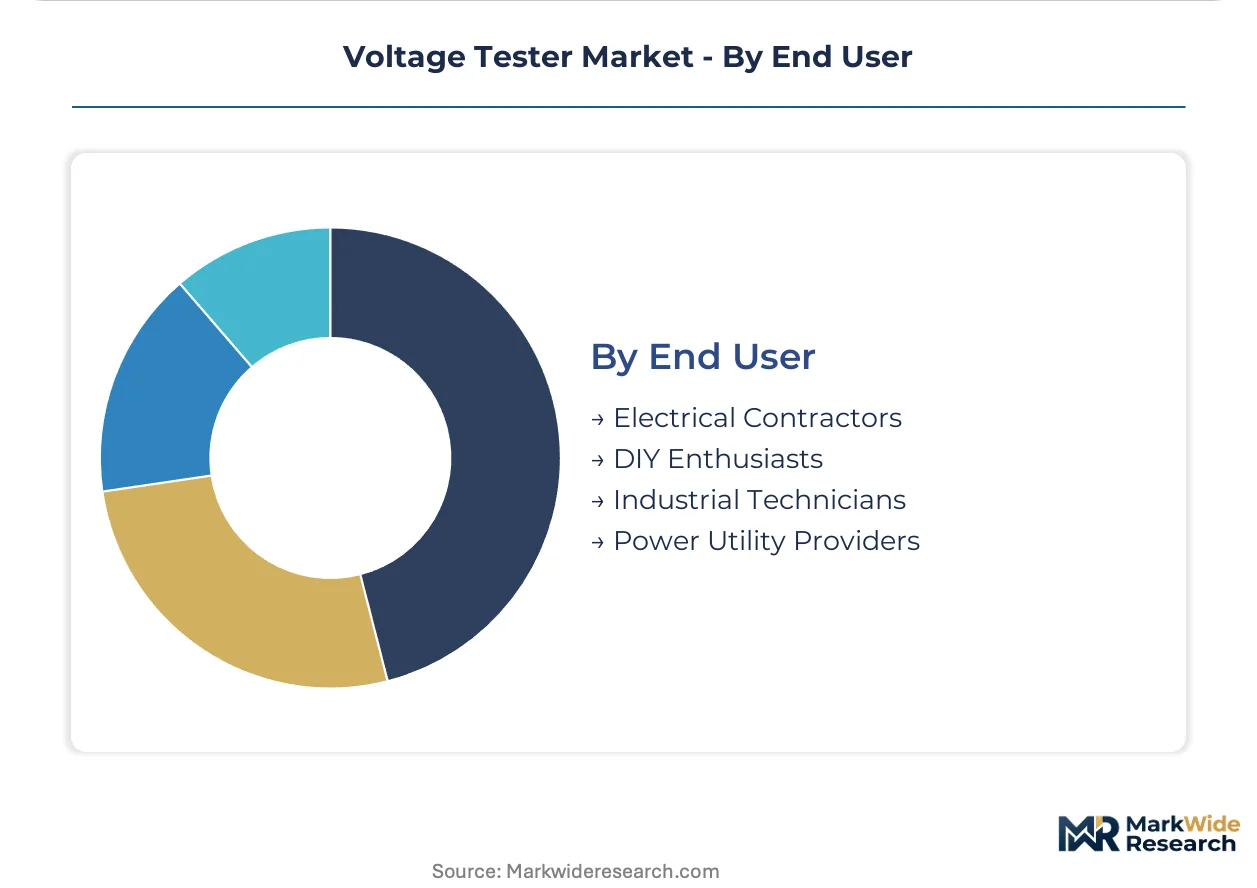
End User:
Volume concentration tilts toward electrical contractors, though margin capture favors industrial technicians with specification authority over centralized procurement budgets.
- Electrical Contractors:Commercial and industrial construction specialists maintain diverse tester inventories across voltage ranges and safety categories. Hardware retail chains in North America compete aggressively for their volume purchases through dominant shelf-space arrangements.
- Industrial Technicians:In-house maintenance personnel at manufacturing and processing facilities operate under strict safety management systems with corporate-mandated equipment standards. Procurement centralization elevates specification authority toward manufacturers with calibration laboratory networks.
- DIY Enthusiasts:Residential consumers performing minor electrical repairs drive economy-tier non-contact unit sales through home improvement retailers.
- Power Utility Providers:Transmission and distribution network operators require high-voltage insulation testers with stringent safety certification for live-line maintenance protocols.
Electrical contractors generate the highest unit volumes; industrial technicians deliver superior margin realization through specification-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility modernization incentives and electrical safety enforcement are steering procurement patterns across concentrated industrial clusters. National regulatory frameworks now embed instrument specifications within workplace compliance mandates. Regional demand concentrates where transmission infrastructure age and construction activity intersect.
United States
NFPA 70E arc-flash mandates compel industrial facilities to verify de-energization with rated testers before live work. OSHA electrical safety regulations explicitly reference verification testing procedures. Petrochemical operators in Texas and data center clusters in Northern Virginia centralize procurement through corporate safety departments.
Germany
Industrial automation density and mandatory periodic inspection protocols sustain premium instrument demand. CE marking directives and IEC 61010 safety standards govern overvoltage category ratings. Large electrical contractors in the Ruhr industrial corridor now require documented metrology traceability before site deployment.
China
Distribution network expansion and rural electrification programs generate volume demand among state grid maintenance crews. Domestic GB standard certification requirements create technical barriers for imported instruments. Manufacturing concentration in the Yangtze River Delta supports localized production of CAT III-rated units.
India
Rural electrification programs under the national power ministry are generating first-time tester demand among state electricity board crews. Central Electricity Authority safety protocols mandate instrument certification for distribution maintenance. Western Maharashtra and Gujarat industrial corridors exhibit concentrated procurement from textile and chemical processing plants.
Brazil
Healthcare facility electrical safety enforcement creates certified tester demand for biomedical equipment maintenance. ANVISA-equivalent protocols mandate verification instruments for hospital infrastructure. São Paulo state anchors demand through its concentration of medical device manufacturing and private hospital networks.
Voltage Tester Market Competitive Environment
On the supply side, the industry is tiered across calibration-capable premium specialists, volume-positioned hardware suppliers, and regional certification-focused fabricators. Three strategic archetypes dominate: metrology-integrated laboratories serving utility procurement, retail-channel-anchored brands capturing contractor volumes, and high-voltage insulation specialists targeting power generation safety requirements. Competitive moves concentrate on captive calibration network expansion and direct-to-safety-department corporate bypass of traditional distribution.
Among established instrumentation specialists, Fluke Corporation, Klein Tools, and Megger Group Limited occupy distinct positioning vectors. Fluke Corporation exemplifies the metrology-integrated archetype through its laboratory network anchoring utility client relationships. Klein Tools represents the retail-channel dominance model with hardware chain shelf-space concentration. Megger Group Limited sits within the high-voltage insulation specialist tier where safety certification requirements reach maximum stringency.
| Leading Market Players |
|---|
| Fluke Corporation |
| Klein Tools |
| Amprobe |
| IDEAL Industries |
| Megger Group Limited |
| Extech Instruments |
| Southwire Company |
| Hioki E.E. Corporation |
| Yokogawa Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta freight corridor channels precision analog-to-digital converters and isolated power management ICs from semiconductor foundries to CAT IV-rated instrument assemblers, concentrating cost leverage among calibration-capable manufacturers while fragmenting price realization across uncertified economy tiers.
Pricing Analysis
Certification level (IEC 61010 CAT III/CAT IV) creates the primary spread between premium and economy offerings. Three-tier pricing structure across premium, standard, and economy levels dominates, with CAT IV-rated units commanding multiples over non-certified alternatives due to third-party laboratory validation costs. Cost compression in the economy tier is intensifying because of non-contact infrared thermography substitution in preventive maintenance routines. DIY enthusiasts and residential inspectors exhibit highest price sensitivity, while industrial technicians under corporate safety mandates show lowest sensitivity to unit cost.
Supply Chain Analysis
Precision analog-to-digital converters and isolated power management ICs draw from Taiwan, South Korea, and Japan, feeding assembly operations in China, Mexico, and Germany. Semiconductor input volatility and allocation constraints for CAT IV-rated components constitute the dominant structural risk. Distribution runs through specialized electrical supply houses and direct manufacturer portals, bypassing traditional hardware retail for utility and industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through corporate safety department procurement centralization at US petrochemical operators and data center clusters, fragmenting specification authority away from decentralized maintenance budgets.
For Market Incumbents: Build captive calibration laboratory networks as the defensive moat against metrology-traceability mandates from German and French electrical contractors. Expand certification investment in IEC 61010 CAT IV validation to extend product development cycle advantages over emerging entrants. Channel control through direct-to-safety-department corporate bypass protects margin pools from hardware retail price erosion. For New Entrants and Emerging Players: Pursue wireless data-logging integration as the white-space target, feeding Bluetooth-enabled testers into mobile CMMS platforms for predictive maintenance subscription revenue. Brazil's ANVISA-equivalent healthcare facility enforcement offers the most penetrable geography for certified biomedical equipment maintenance protocols. Go-to-market positioning should anchor on ANVISA-equivalent compliance documentation for hospital infrastructure segments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial instrumentation parents seeking to divest non-core electrical safety divisions. Long-term viability rests on calibration infrastructure ownership and IEC 61010 certification capabilities rather than volume manufacturing scale. The signal to watch is NFPA 70E enforcement intensity at US industrial facilities as mandatory replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | Fluke Corporation's laboratory footprint anchors utility client relationships against uncertified competitors. |
| Wireless CMMS Platform Integration | Bluetooth-enabled testers feeding mobile platforms enable predictive maintenance subscription models among facility managers. |
| Direct Corporate Safety Department Channel | Bypassing hardware retail captures specification authority at US petrochemical and data center operators. |
| ANVISA-Equivalent Certification Investment | Brazil healthcare facility enforcement creates certified tester demand for biomedical equipment protocols. |
| True RMS Capability Development | Variable-frequency drive proliferation invalidates average-responding instruments in industrial motor control systems. |
Study Parameters
The analysis maps digital tester, analog tester, clamp meter, and multifunction tester sub-sectors, each validated through electrical contractor procurement managers, industrial facility safety directors, calibration laboratory technicians, and hardware retail category buyers. Primary interviews with these stakeholders combined with secondary validation from IEC 61010 certification databases, OSHA electrical safety enforcement records, NFPA 70E compliance documentation, and utility modernization program disclosures. Bottom-up unit demand modeling and top-down market sizing triangulate volume and value estimates.
Assumptions held fixed include continued NFPA 70E enforcement intensity and IEC 61010 certification validity periods, while smart grid deployment pace and semiconductor allocation constraints were varied across sensitivity scenarios. Segmentation dimensions modeled span product architecture, sensing technology, application task complexity, and end-user procurement centralization. CAGRs were derived from installation base replacement cycles and regulatory mandate compliance deadlines, with variable-frequency drive penetration and non-contact technology substitution as industry-specific forecast inputs.
Sensitivities concentrate around semiconductor input allocation constraints extending CAT IV-rated instrument lead times and NFPA 70E enforcement variance across US industrial facilities. Cross-checking against utility capital expenditure disclosures and electrical contractor equipment inventory surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
UPS Battery and Supercapacitor Health Diagnostics Test Equipment Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
Sound Level Measurement Meter Market
Test and Measurement
Wireless Network Test Equipment Market
Test and Measurement
India Electrical Testing Services Market
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
Optical Critical Dimension (OCD) Measurements System Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
Microhardness Testing System Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Lithium Metal Anode Dendrite Growth Visualization Test Platforms Market
Test and Measurement
Fiber Optic Tester Market