
 PV Micro Inverters Market | 2026-2036
PV Micro Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
PV Micro Inverters Market Analytics
Residential installations is shifting toward module-level power electronics as homeowners prioritize shading tolerance and per-panel monitoring. Enphase Energy dominates the North American channel through captive supply of integrated storage-ready systems. Hoymiles anchors the Asia-Pacific landscape with cost-optimized multi-link architectures for rooftop arrays. SMA Solar Technology navigates European certification complexity with extended warranty programs that differentiate its premium positioning.
PV micro inverters are compact DC-to-AC conversion devices installed per solar module, typically rated between 250W and 500W, enabling independent maximum power point tracking to mitigate output losses from partial shading or soiling. Their primary commercial purpose is to boost energy harvest and safety in distributed generation systems by eliminating high-voltage DC string wiring. Single-phase micro inverters lead the residential segment where standard split-phase service dominates, while three-phase variants are capturing commercial installations across European industrial rooftops. Smart micro inverters with embedded Wi-Fi and cellular connectivity represent the fastest-growing connectivity intersection, as remote diagnostics reduce truck-roll costs for installers.
FCC certification governs wireless-enabled units in the United States, while CE marking and EU Green Deal alignment shape product access across European member states. Australia's Clean Energy Council listing requirement filters non-compliant hardware from subsidy-eligible installations, tightening market access for new entrants. Stakeholders must weigh module-level electronics against string inverter plus power optimizer hybrids as capital cost sensitivity intensifies and installer training ecosystems mature.
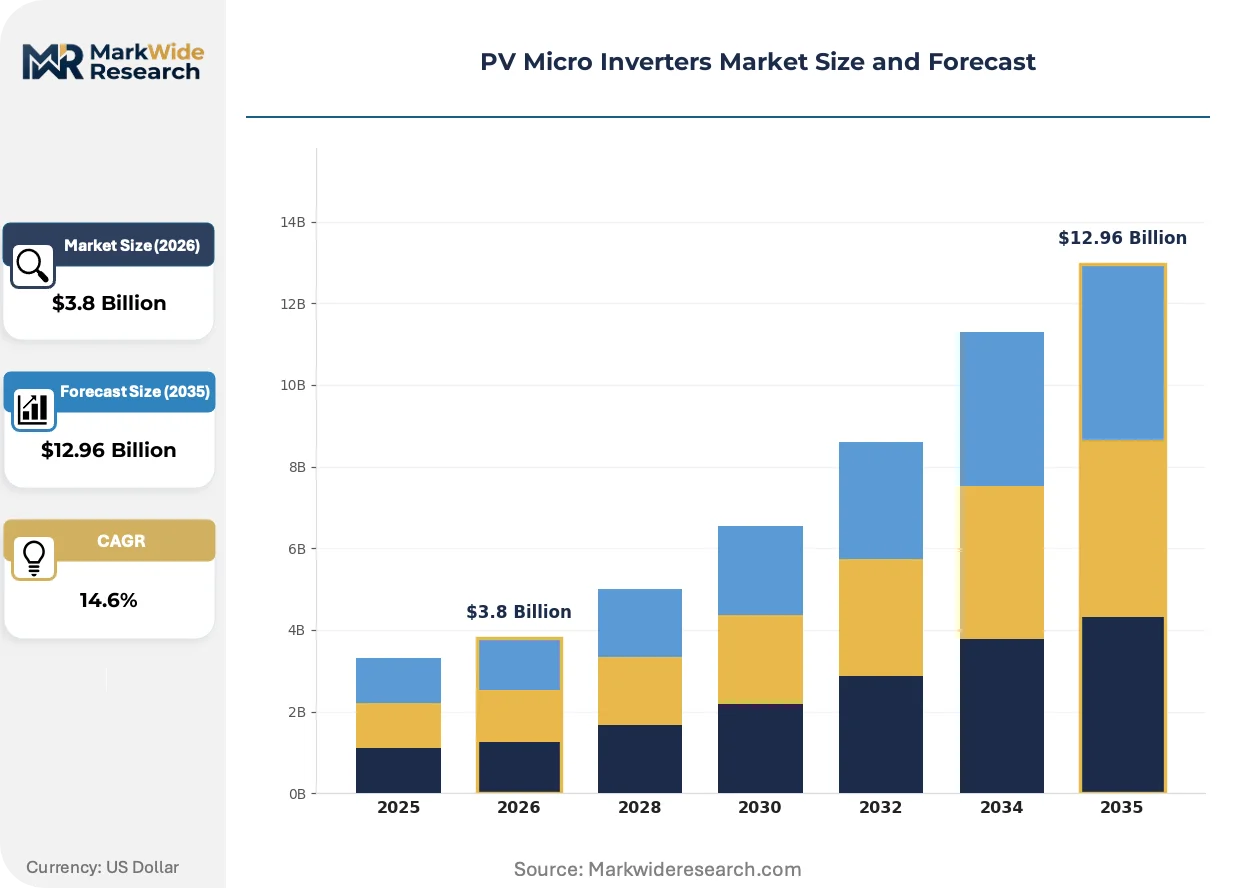
Market Dynamics
Module-level power electronics is displacing centralized string architectures as residential solar installers prioritize shading resilience and per-panel visibility. This technology pivot compresses margins for legacy inverter suppliers while rewarding semiconductor integration capabilities.
Growth Catalysts
- Shading Tolerance Requirements:Dense urban rooftop installations in Germany and Australia favor distributed MPPT architectures that isolate underperforming modules. Building-integrated photovoltaics mandates in several EU member states accelerate this specification.
- FCC Part 15 Certification:Wireless-enabled micro inverters gain streamlined market access in the United States through harmonized electromagnetic compliance testing. This reduces time-to-revenue for connectivity-embedded hardware.
- Grid-Forming Inverter Standards:IEEE 1547-2018 revisions in California and Hawaii require advanced reactive power capabilities that micro inverter platforms satisfy natively. Utility interconnection queues favor compliant hardware.
Market Restraints
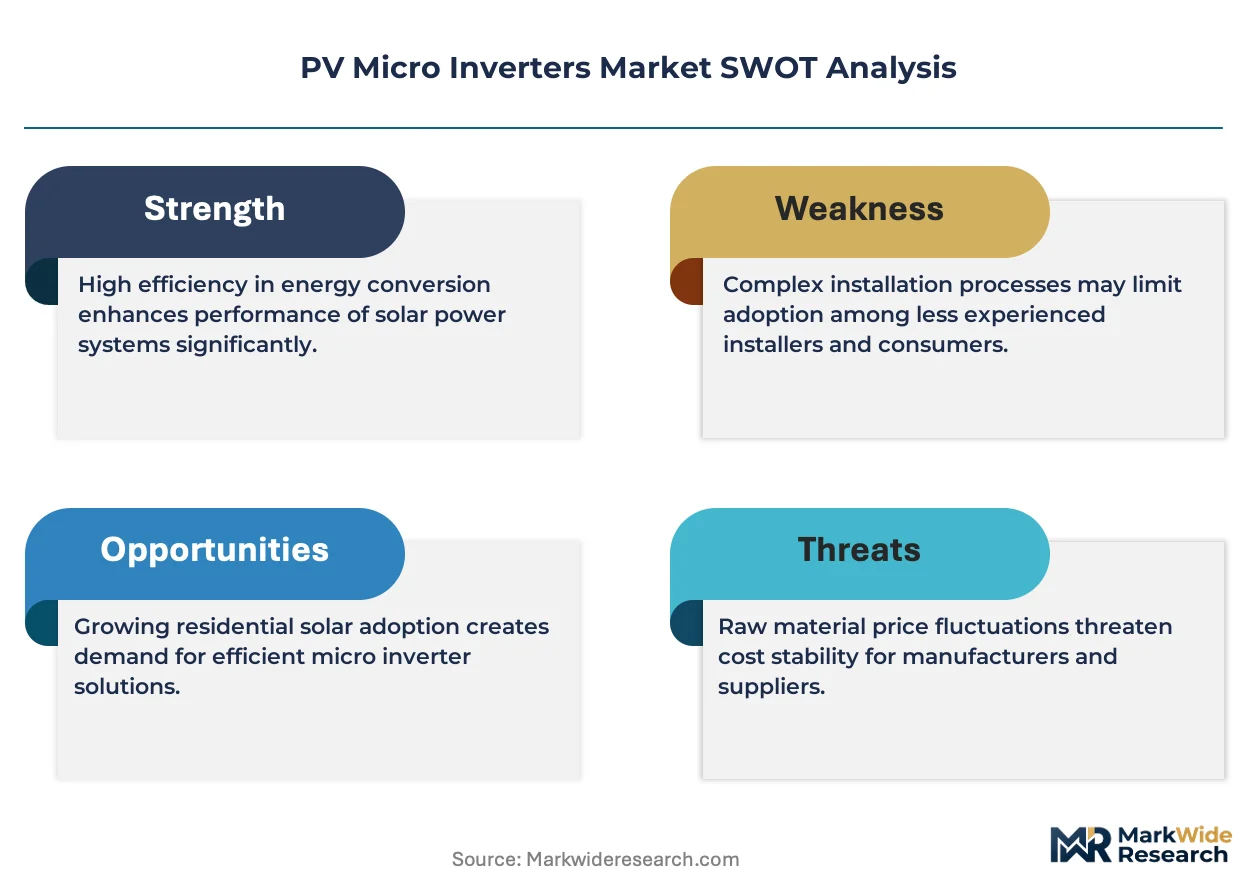
- Silicon Carbide Wafer Supply:Power semiconductor substrate concentration in Chinese and Japanese foundries creates input cost volatility for high-efficiency designs. Geopolitical trade measures amplify price uncertainty.
- String Inverter Plus Optimizer Hybrids:Solaredge and SMA power optimizer combinations capture cost-sensitive commercial segments with comparable shading mitigation at lower per-watt installed cost.
- CE Marking Complexity:EU harmonized standards for grid-connected inverters require notified body involvement that extends certification timelines versus FCC self-certification pathways.
Strategic Opportunities
- Agricultural Solar-Plus-Storage:Japanese farmland solarization policies under METI guidelines create demand for AC-coupled battery-ready micro inverters with islanding capability.
- Virtual Power Plant Aggregation:Australian distributed energy resource orchestration platforms monetize fleet-wide frequency response, rewarding granular module-level telemetry.
- Three-Phase Commercial Rooftops:European industrial building codes in Italy and Spain mandate three-phase service for installations above 10kW, opening a higher-margin product tier.
Industry Challenges
- Installer Training Ecosystem Maturity:Module-level electronics require electrical contractor recertification that lags product availability in emerging solar markets. Workforce development programs in Brazil and South Africa struggle to scale.
- Legacy String Inverter Retrofit Integration:Existing residential installations with functional central inverters present switching friction that extends replacement cycles beyond equipment depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PV Micro Inverters Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-phase Micro Inverters, Three-phase Micro Inverters, Smart Micro Inverters, Multi-link Micro Inverters End User: Residential Installations, Commercial Installations, Utility-scale Projects, Agriculture Applications Connectivity: Wi-Fi, Ethernet, Powerline Communication, Cellular Installation: Rooftop Mount, Ground Mount, BIPV Systems, Off-grid Solutions |
| Companies Covered | Enphase Energy, Hoymiles, SolarEdge Technologies, APsystems, Deye Inverter, Altenergy Power Systems, Chilicon Power, SMA Solar Technology, Darfon Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PV Micro Inverters Market Evolving Landscape
Silicon carbide power semiconductors and embedded connectivity stacks are compressing cost curves while enabling new grid services. These hardware advances coincide with regulatory pressure for distributed energy resource visibility and procurement model evolution toward integrated storage.
GaN and SiC transistor architectures are converging with conventional silicon IGBT designs in next-generation micro inverters. Residential installers in California and Texas specify these platforms for their heat dissipation advantages in attic mounting configurations. The technology shift is compressing thermal management component counts while extending warranty terms.
The EU Green Deal's renewable energy directive revision tightens embodied carbon disclosure requirements for imported solar hardware. Manufacturers targeting Netherlands and Denmark must document supply chain emissions through third-party verification. This regulatory pressure favors European assembly operations with shorter logistics footprints.
Installer procurement patterns are fragmenting across direct OEM relationships, distributor consignment programs, and utility-administered bulk purchasing cooperatives. The channel shift compresses working capital requirements for smaller electrical contractors in Australia and fragments volume concentration previously held by national distributors. After-sales service obligations are unbundling from hardware margins as third-party O&M platforms capture recurring revenue streams.
PV Micro Inverters Market Segmentation
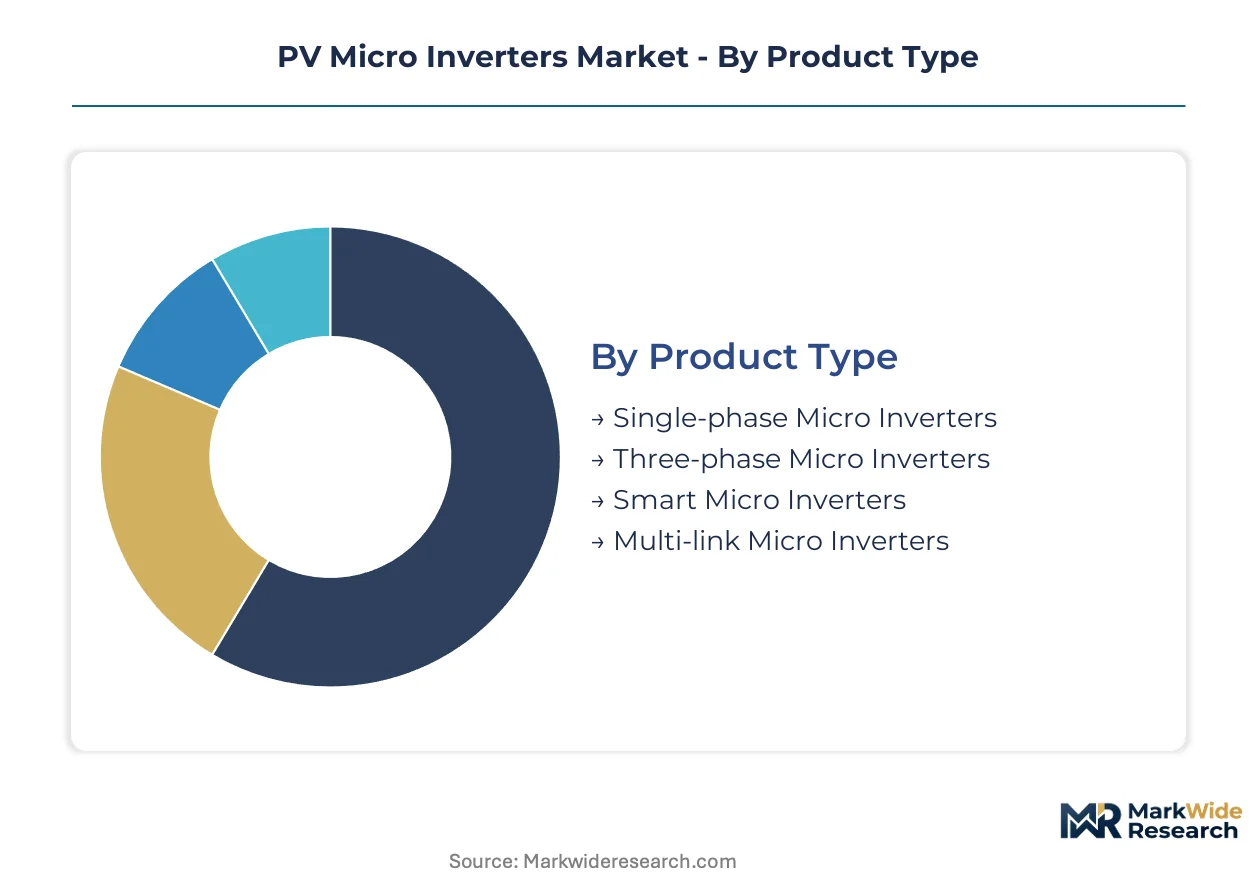
PV micro inverter segmentation reflects divergent technical requirements across residential, commercial, and specialized applications. Each dimension—product architecture, end-user profile, connectivity protocol, and mounting configuration—carries distinct margin structures and certification burdens that shape supplier positioning.
Product Type:
Standardization dominates entry-level offerings while premium tiers embed semiconductor differentiation and grid-forming capabilities.
- Single-phase Micro Inverters:Split-phase architectures rated 250-400W serve North American residential rooftops with 120/240V service. California and Texas installers specify these for attic mounting where thermal management constraints favor GaN transistor designs over conventional silicon.
- Smart Micro Inverters:Embedded telemetry stacks with Wi-Fi or cellular modems enable per-module monitoring and remote diagnostics. Australian virtual power plant operators aggregate these fleets for frequency response services, rewarding granular visibility with premium procurement terms.
- Three-phase Micro Inverters:400V commercial variants address European industrial rooftops above 10kW.
- Multi-link Micro Inverters:Cost-optimized architectures connect multiple modules to one inverter unit.
Leading the category by volume: Single-phase Micro Inverters. Growing fastest: Smart Micro Inverters.
End User:
Margin concentration follows installation scale, with residential commanding premium pricing per watt and utility-scale prioritizing capital efficiency.
- Residential Installations:Homeowners in Germany and Australia drive module-level electronics adoption for shading resilience and per-panel production visibility. High electricity tariffs in South Australia accelerate payback calculations that favor micro inverters over string alternatives despite higher upfront hardware costs.
- Commercial Installations:Industrial rooftops in Italy and Spain require three-phase service compliance above 10kW thresholds. Extended warranty programs and reactive power capabilities under IEEE 1547-2018 revisions differentiate compliant hardware in California utility interconnection queues.
- Utility-scale Projects:Large ground-mount arrays rarely specify micro inverters due to cost-per-watt sensitivity.
- Agriculture Applications:Japanese farmland solarization under METI guidelines creates demand for AC-coupled battery-ready units with islanding capability.
Residential Installations generate the highest per-watt margins. Agriculture Applications show the steepest expansion trajectory as agrivoltaic policies proliferate.
Connectivity:
Protocol selection trades installation labor against recurring data service revenue and cybersecurity exposure.
- Wi-Fi:Dominant residential protocol in suburban markets with reliable broadband infrastructure. FCC Part 15 certification streamlines U.S. market access for embedded wireless hardware, reducing time-to-revenue versus cellular alternatives requiring carrier partnerships.
- Cellular:Critical for rural and off-grid installations lacking fixed-line internet. Australian distributed energy resource platforms rely on cellular-backhauled telemetry for fleet-wide orchestration, though monthly data costs compress installer margins.
- Ethernet:Preferred in commercial settings with structured cabling.
- Powerline Communication:Leverages existing AC wiring for data transmission in retrofit scenarios.
Wi-Fi holds the largest installed base. Cellular is climbing the fastest as rural solarization accelerates.
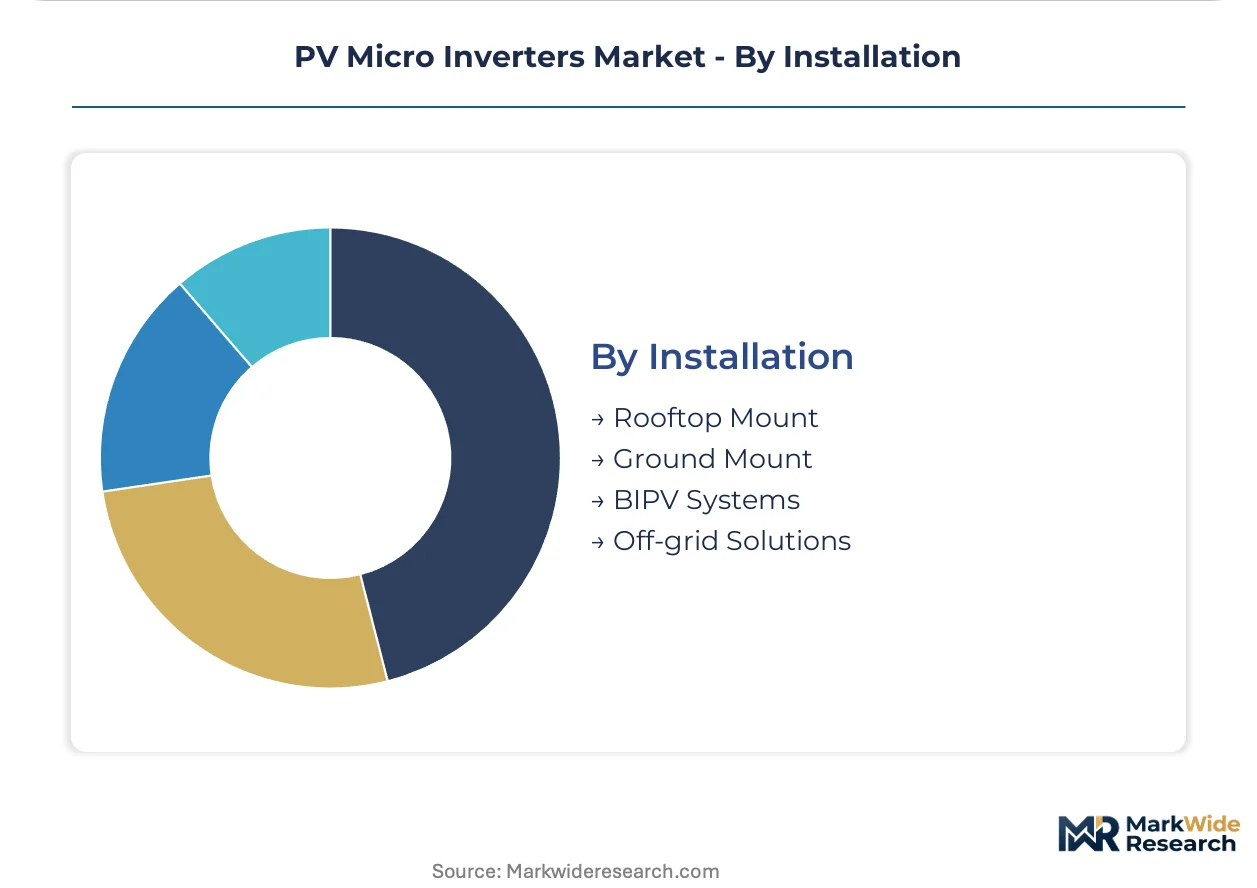
Installation:
Mounting configuration dictates thermal environment, accessibility for maintenance, and integration with building systems.
- Rooftop Mount:Standard residential deployment in dense urban environments across Germany and Australia. Shading from adjacent structures and HVAC equipment makes module-level MPPT essential, driving specification of distributed architectures over centralized alternatives.
- BIPV Systems:Building-integrated photovoltaics mandates in several EU member states accelerate demand for aesthetically compact micro inverters. Netherlands and Denmark projects must document embodied carbon through third-party verification under EU Green Deal alignment requirements.
- Ground Mount:Utility-scale and agricultural applications favor cost-optimized string solutions.
- Off-grid Solutions:Islanding capability and battery coupling define specification in remote installations.
Rooftop Mount dominates unit shipments. BIPV Systems are gaining share fastest as building codes tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's Priority Investment Program zones and distributed generation incentives concentrate micro inverter procurement in New South Wales and Victoria, where high electricity tariffs accelerate residential solar payback calculations.
United States
California and Texas installers specify GaN transistor designs for attic mounting configurations where thermal management constraints favor advanced semiconductors. FCC Part 15 certification streamlines market access for wireless-enabled hardware, reducing electromagnetic compliance testing timelines. Installers in the Southwest cluster around Phoenix and Las Vegas prioritize shading resilience in dense suburban rooftop deployments.
Germany
Dense urban rooftop installations in Berlin and Munich favor distributed MPPT architectures that isolate underperforming modules from partial shading. Building-integrated photovoltaics mandates in several EU member states accelerate specification of aesthetically compact units. The Ruhr industrial corridor drives three-phase commercial adoption above 10kW thresholds for industrial building compliance.
Australia
Homeowners in South Australia and Queensland drive module-level electronics adoption for per-panel production visibility under high electricity tariff environments. Clean Energy Council listing requirements filter non-compliant hardware from subsidy-eligible installations, tightening market access. Virtual power plant operators in Victoria aggregate cellular-backhauled fleets for frequency response services.
Japan
Farmland solarization policies under METI guidelines create demand for AC-coupled battery-ready units with islanding capability in rural prefectures. Agricultural cooperatives in Hokkaido and Kyushu specify micro inverters for distributed generation on rice paddies and greenhouse operations. The Kanto region around Tokyo concentrates residential retrofit activity with shading-tolerant architectures.
Italy
Industrial building codes mandate three-phase service for installations above 10kW across Lombardy and Veneto, opening higher-margin commercial product tiers. Extended warranty programs differentiate premium positioning in European certification complexity. Installers in the Po Valley prioritize reactive power capabilities under evolving grid interconnection standards.
PV Micro Inverters Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated storage-ready systems commanding premium positioning in North American residential channels while cost-optimized multi-link architectures capture Asia-Pacific volume. The vendor base organizes around three strategic archetypes: semiconductor-integrated specialists with captive power electronics design, regional assemblers leveraging Chinese foundry partnerships, and legacy inverter suppliers pivoting from string architectures. Competitive moves concentrate on backward integration into power semiconductor supply and certification pre-positioning for emerging grid-forming standards.
Within the integrated-systems tier, Enphase Energy and Hoymiles occupy distinct geographic anchor positions, with the former exemplifying North American channel dominance through storage-ready architectures and the latter representing Asia-Pacific cost optimization through multi-link designs. SMA Solar Technology sits within the European premium tier, navigating CE marking complexity through extended warranty differentiation. These three anchors illustrate how competitive positioning fragments across certification ecosystems and installer training infrastructures rather than consolidating around pure manufacturing scale.
| Leading Market Players |
|---|
| Enphase Energy |
| Hoymiles |
| SolarEdge Technologies |
| APsystems |
| Deye Inverter |
| Altenergy Power Systems |
| Chilicon Power |
| SMA Solar Technology |
| Darfon Electronics Corporation |
| Others |
Value Network & Pricing Analysis
Utility-administered bulk purchasing cooperatives in Australia and national distributor consignment programs in Germany anchor the dominant contract-based pricing model, compressing working capital requirements for smaller electrical contractors while fragmenting volume concentration.
Pricing Analysis
Short lead-time premiums distinguish certified inventory held in regional Australian and German distribution centers from spot-market units sourced through Asian trading houses. Three-tier pricing structure across premium, standard, and economy levels separates grid-forming smart units with IEEE 1547-2018 compliance from entry-level single-phase hardware. Price differentiation hinges on CE marking complexity versus FCC self-certification pathways. Cost compression in the standard tier is intensifying because Solaredge and SMA power optimizer combinations capture shading-mitigation demand at lower per-watt installed cost. Commercial installers in Italy and Spain show least price sensitivity due to three-phase mandate compliance requirements, while residential contractors in emerging solar markets exhibit highest sensitivity.
Supply Chain Analysis
Regional distribution centers in Shanghai, Shenzhen, and Ningbo feed hub-and-spoke patterns into Australian and German installer networks. Silicon carbide wafer supply concentrates in Chinese and Japanese foundries, with power semiconductor substrate concentration creating input cost volatility. Raw material dependencies include SiC wafers, GaN epitaxial layers, and aluminum heat dissipation housings. Single-source vulnerability in Japanese SiC substrate production amplifies price uncertainty under geopolitical trade measures. Distribution runs through captive OEM-direct channels for Enphase and Hoymiles, distributor consignment for SMA, and utility-administered cooperatives in Australian Priority Investment Program zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PV micro inverter market functions as a vertical-integration race where captive power electronics design and semiconductor foundry partnerships determine margin sustainability. Players pursue backward integration into silicon carbide wafer supply to escape substrate volatility.
For Market Incumbents: Anticipate Solaredge and SMA power optimizer hybrid encroachment by accelerating IEEE 1547-2018 certification pre-positioning for California and Hawaii utility interconnection queues. Deepen backward integration into SiC wafer supply through Japanese and Chinese foundry partnerships to defend against substrate cost volatility. Lock installer training ecosystem control in Brazil and South Africa before workforce development programs mature.
For New Entrants and Emerging Players: Agricultural cooperatives in Hokkaido and Kyushu represent the most penetrable buyer archetype, with METI farmland solarization guidelines creating unmet demand for AC-coupled battery-ready units with islanding capability. Target Japanese agrivoltaic specifications before incumbent warranty programs extend into rural prefectures. Pursue Clean Energy Council pre-listing in Australia to access subsidy-eligible procurement channels.
For Investors and Strategic Acquirers: The window for entry favors semiconductor-integrated specialists with captive GaN transistor design and existing FCC Part 15 certification infrastructure. Long-term viability centers on grid-forming inverter standard compliance as IEEE 1547 revisions propagate across U.S. jurisdictions. Watch California utility interconnection queue backlogs as the inflection signal for hardware compliance premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Wafer Supply | Japanese and Chinese foundry partnerships reduce substrate cost volatility exposure. |
| IEEE 1547-2018 Certification Pre-Positioning | California and Hawaii utility interconnection queues favor compliant hardware procurement. |
| Virtual Power Plant Platform Integration | Australian distributed energy resource orchestration monetizes fleet-wide frequency response. |
| Clean Energy Council Listing Investment | Australia's subsidy eligibility requirements filter non-compliant hardware from procurement. |
| Installer Training Ecosystem Development | Brazil and South Africa workforce recertification programs lag product availability. |
Research Methodology
Independent corroboration across EPC contractor interviews, utility planning officer consultations, and semiconductor procurement lead surveys underwrites the qualitative findings. Primary fieldwork captured residential installer specification patterns in California, Texas, and South Australia alongside commercial procurement decisions in Lombardy and Veneto. Secondary validation drew from FERC interconnection filings, EIA distributed generation databases, IEA renewable energy deployment statistics, and Clean Energy Council accredited product listings. Bottom-up module shipment aggregation and top-down addressable market sizing triangulate volume estimates.
Comparable-period anchoring to historical installation data across the projection horizon grounds growth trajectory assumptions. The analytical framework models segmentation across product architecture, end-user profile, connectivity protocol, and mounting configuration, with semiconductor technology tier as an industry-specific dimension. CAGRs derive from regression analysis of module-level electronics penetration rates against string inverter displacement curves. Forecast inputs include shading tolerance specification intensity and grid-forming inverter standard adoption velocity.
Revisions become necessary when silicon carbide wafer supply disruptions, IEEE 1547 revision implementation delays, or Australian distributed generation incentive policy shifts materialize. Forecast outputs reflect documented assumptions about installer training ecosystem maturation and power optimizer hybrid competitive response. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Surface Mounted Medium Voltage Distribution Panel Market
Power Systems
Smart Power Strips Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
AC DC Power Adapter Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Hybrid Inverters Market
Power Systems
Battery Balancer Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Germany Rechargeable Battery Market
Power Systems
Global Power Semiconductor Switches Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
Telecom Power Systems Market
Power Systems
Power Semiconductor Market
Power Systems
DC-DC Converter Market