
 EV Power Module Market | 2026-2036
EV Power Module Market Size, Share, and Industry Trends Forecast 2026-2036
EV Power Module Market Foresight
Silicon carbide is restructuring EV power module economics as the material displaces silicon IGBTs in high-voltage traction inverters. Infineon Technologies leverages its Dresden fab capacity to anchor European supply security for automotive-grade SiC dies. Mitsubishi Electric sustains vertical integration from wafer growth through module packaging, controlling cost trajectories in Japanese OEM programs. Wolfspeed dominates SiC substrate supply, extending its Durham, North Carolina materials complex to serve North American EV ramp schedules.
An EV power module integrates power semiconductor dies, ceramic substrates, baseplates, and gate drivers into a thermally managed assembly that converts DC battery current to variable-frequency AC for traction motors, typically operating at 400–800 V with switching frequencies above 10 kHz. Silicon carbide technology leads in premium passenger vehicle platforms where efficiency gains offset die costs, while IGBT modules retain share in commercial vehicle applications where voltage and thermal requirements remain moderate. Gallium nitride competes in onboard charger segments where higher switching frequencies enable passive component miniaturization.
The U.S. Inflation Reduction Act domestic content rules, Europe's Ecodesign requirements for energy-related products, and China's GB standards for new energy vehicle safety collectively reshape module qualification pathways and sourcing geography. EPA tailpipe standards and NHTSA CAFE rules in the United States tighten the efficiency envelope that power modules must deliver. Stakeholders must monitor regulatory divergence between jurisdictions to avoid duplicative certification investments as module architectures consolidate around 800 V platforms.
Market Dynamics
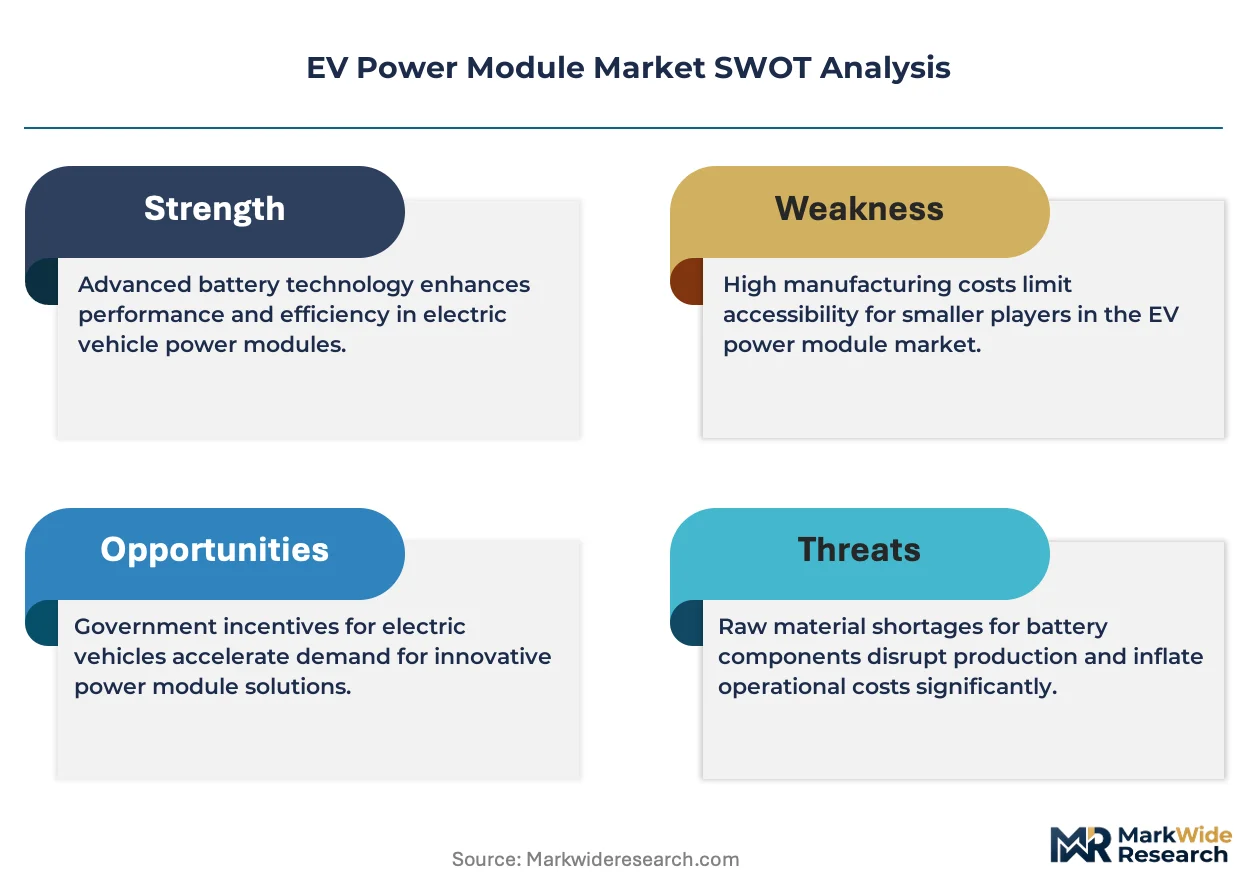
Silicon carbide die penetration is compressing incumbent silicon IGBT economics and forcing module suppliers to recalibrate thermal management architectures around higher switching frequencies and elevated operating temperatures.
Growth Catalysts
- China NEV safety mandates:GB standards for new energy vehicle thermal runaway protection accelerate module qualification cycles for domestic OEMs and tier-one integrators.
- 800 V platform proliferation:Premium passenger vehicle architectures demand SiC-compatible power stages, pulling die attach and substrate materials into higher thermal conductivity tiers.
- U.S. Inflation Reduction Act domestic content rules:North American assembly requirements redirect module sourcing geography toward regional substrate and packaging capacity.
Market Restraints
- Substrate supply concentration:SiC wafer output clusters in limited geographies, exposing module makers to allocation risk during automotive ramp cycles.
- Silver sintering material costs:Die attach materials face precious metal price volatility that compresses gross margins at volume scale.
- IGBT residual competitiveness:Silicon devices retain cost advantage in 400 V commercial vehicle platforms where efficiency requirements remain moderate.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for advanced automotive electronics attract module packaging investment toward emerging domestic EV supply chains.
- GaN-on-Si convergence with OBC architectures:Onboard charger segments integrate gallium nitride switches for frequency multiplication and magnetics miniaturization.
- Europe Ecodesign efficiency tiers:Energy-related product mandates create premium positioning for modules exceeding minimum loss thresholds.
Industry Challenges
- Power electronics talent scarcity:Module design requires rare combinations of thermal engineering, semiconductor physics, and automotive qualification expertise.
- Automotive SPICE and functional safety certification:ASIL-D compliance timelines extend development cycles and strain validation resources.
- Multi-jurisdictional homologation:Divergent China GB, Europe ECE, and U.S. FMVSS test protocols force redundant testing investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Power Module Market |
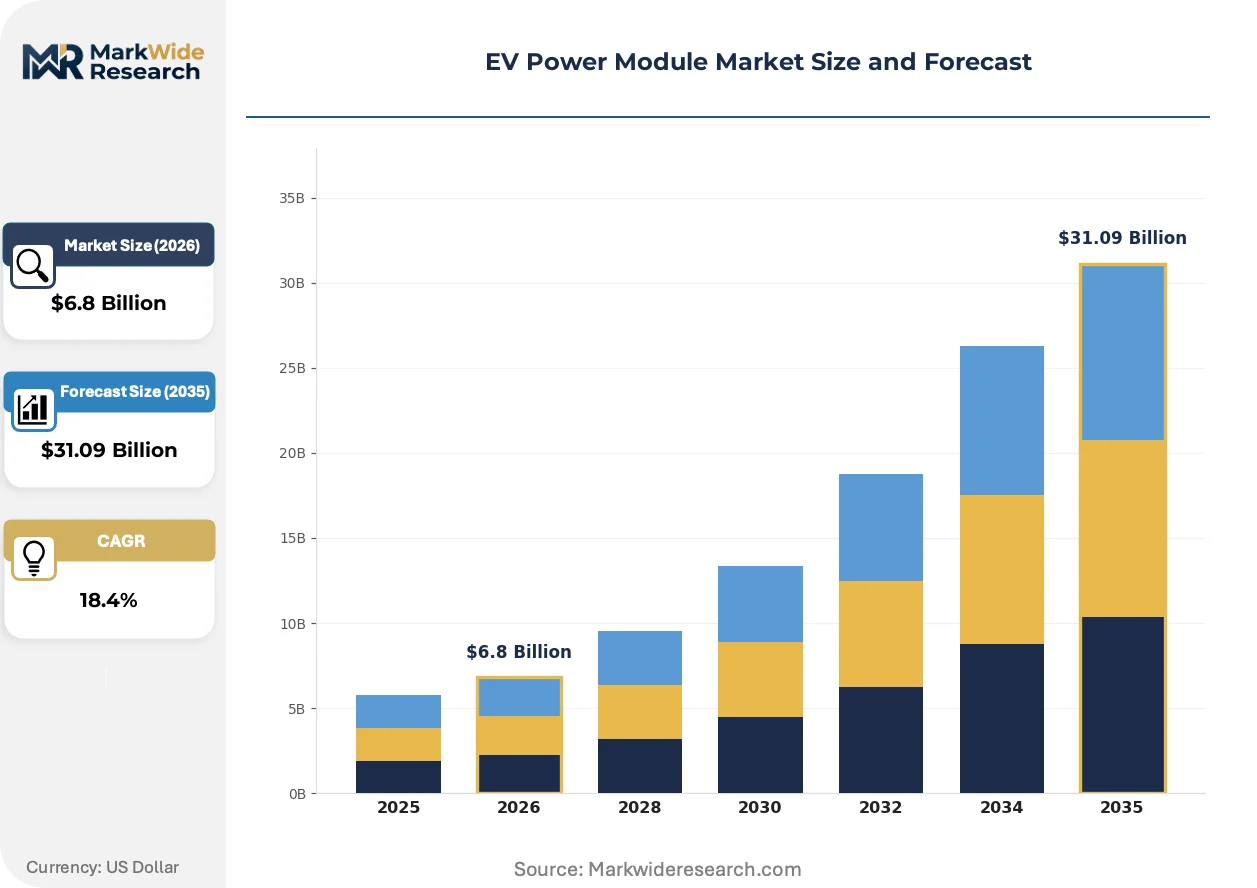
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverters, Chargers, Battery Management Systems, Thermal Management Systems Technology: Silicon Carbide, Gallium Nitride, IGBT, MOSFET End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Public Transport |
| Companies Covered | Infineon Technologies, Mitsubishi Electric, ON Semiconductor, STMicroelectronics, Continental AG, Robert Bosch GmbH, Denso Corporation, Hitachi Automotive Systems, Wolfspeed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Power Module Market Shifts & Advancements
Module architectures are converging around standardized 800 V platforms while materials science advances unlock thermal performance gains that redefine efficiency benchmarks across passenger and commercial vehicle segments.
Silicon carbide MOSFET technology is consolidating its position in traction inverters through superior switching characteristics that reduce thermal management mass. Premium OEMs in Germany and South Korea have accelerated platform migration toward full-SiC designs. This transition is consolidating supplier relationships around die attach and substrate vendors capable of 175°C continuous operation.
Europe's Ecodesign for Energy-Related Products framework tightens standby loss limits and efficiency grading thresholds for automotive power conversion equipment. Module suppliers must redesign gate drive circuits and magnetic components to meet tiered performance bands. Korean and Japanese tier-one integrators are pre-qualifying designs against anticipated 2027 efficiency tiers.
Fleet operators and OEM procurement teams are compressing supplier qualification timelines from 36 months toward 24 months to match accelerated EV platform launch schedules. Direct sourcing relationships between automotive OEMs and substrate material vendors are displacing traditional tier-two distribution channels. This pattern is most pronounced in China where vertical battery-module integration creates captive power electronics demand.
EV Power Module Market Segmentation
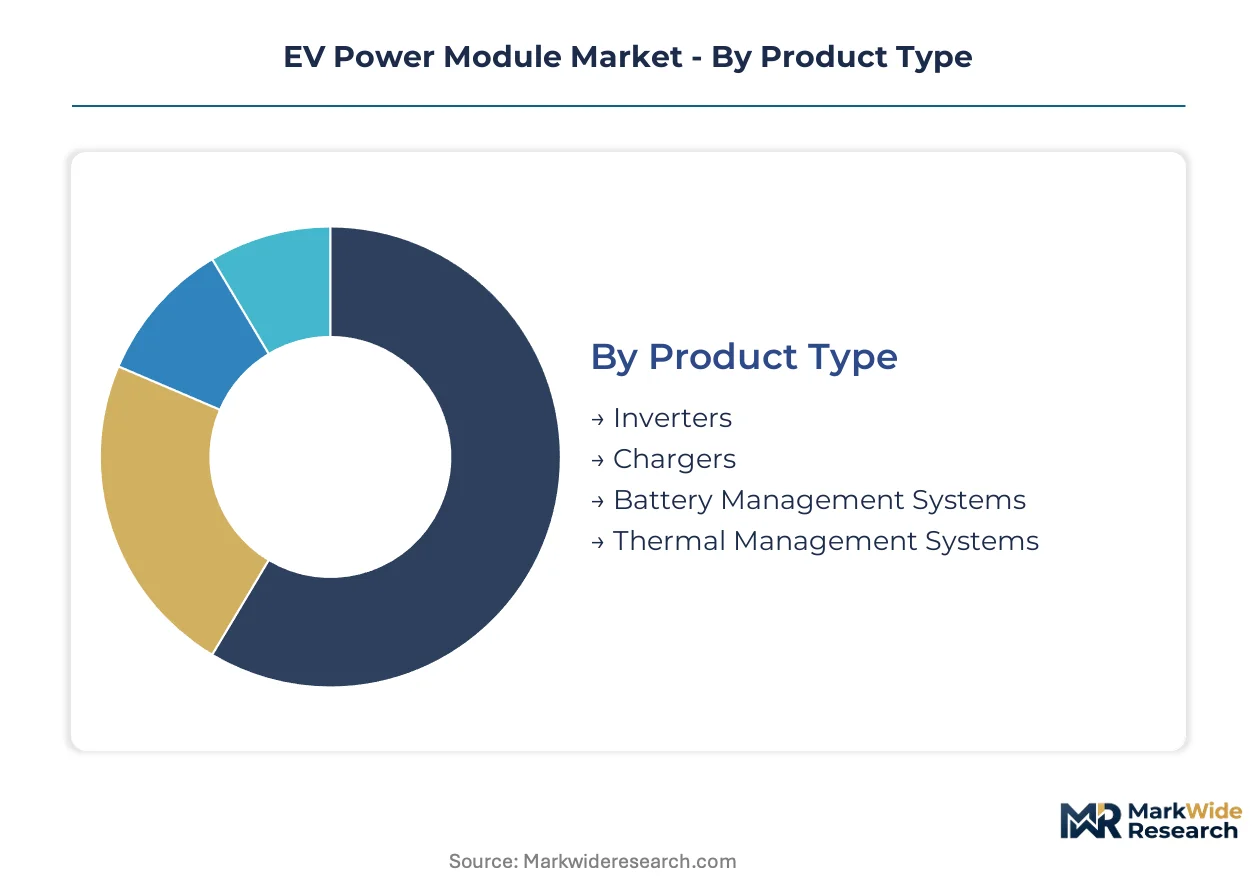
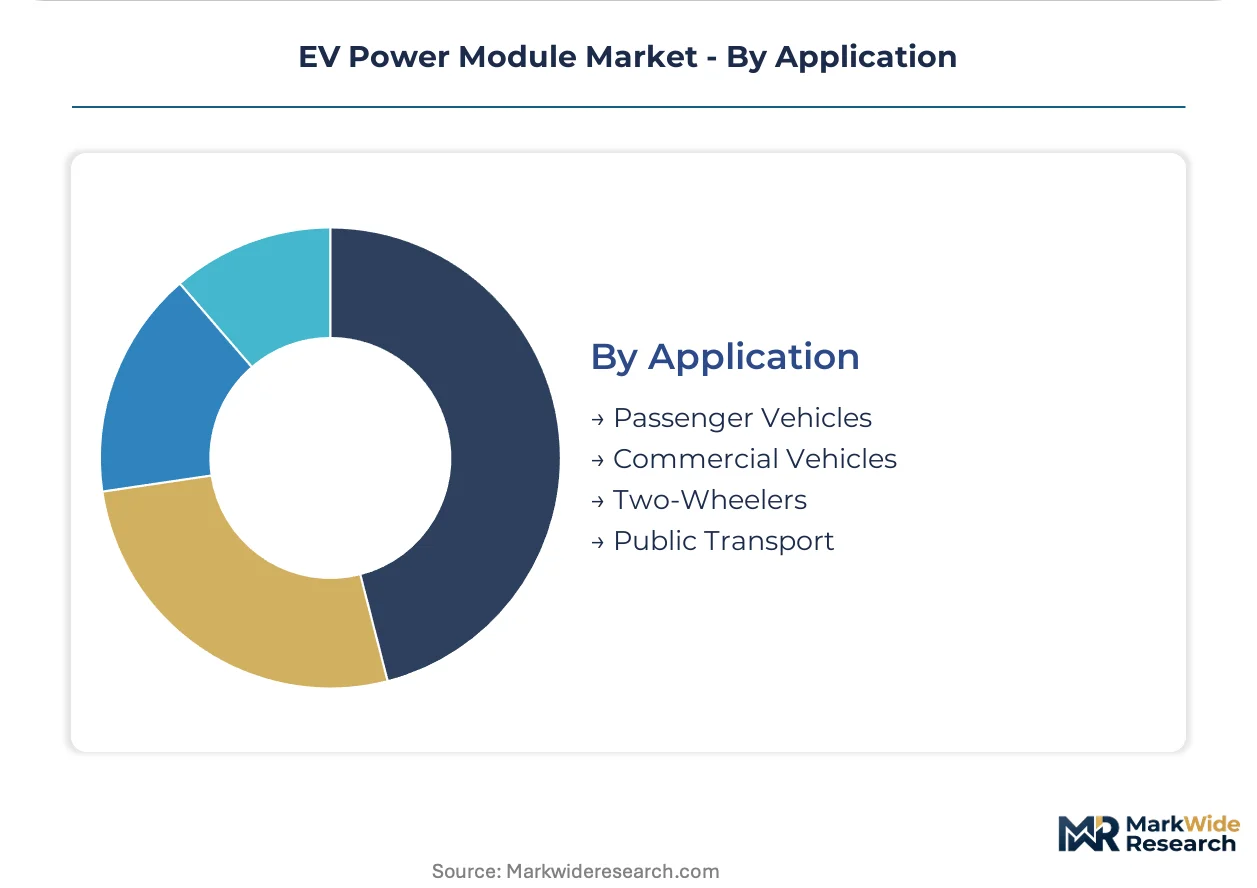
Segmentation in the EV power module market reveals how technology choices, end-use requirements, and application architectures create distinct competitive arenas with diverging qualification standards and margin profiles.
Product Type:
Voltage and power density specifications differentiate module categories across the drivetrain hierarchy.
- Inverters:Traction inverters handle the highest power throughput, converting DC battery voltage to three-phase AC for propulsion motors. Demand concentrates in 800 V passenger vehicle platforms where SiC MOSFETs reduce switching losses and thermal mass. China's premium NEV segment anchors volume uptake.
- Chargers:Onboard chargers manage AC-to-DC conversion with isolation requirements and power factor correction. Fleet operators in Europe are specifying bidirectional V2G-capable designs that stress semiconductor reliability under cyclic loading.
- Battery Management Systems:Cell monitoring and balancing circuits require precision voltage sensing with ASIL-D functional safety compliance.
- Thermal Management Systems:Cooling loop controllers and heater drives operate at lower voltages but demand automotive-grade temperature cycling resilience.
Mature deployment sits with inverters. Newer deployment is concentrated in bidirectional charging architectures.
Technology:
Material bandgap and switching characteristics determine efficiency ceilings and thermal design complexity.
- Silicon Carbide:Wide-bandgap MOSFETs enable 175°C junction temperatures and switching frequencies above 50 kHz, shrinking magnetics and cooling hardware. German and South Korean OEMs have accelerated full-SiC traction inverter adoption.
- IGBT:Insulated-gate bipolar transistors retain cost advantage in 400 V commercial vehicle platforms where efficiency requirements remain moderate and thermal budgets permit larger heat sinks.
- Gallium Nitride:GaN HEMTs excel in onboard charger and DC-DC converter segments where frequencies above 100 kHz enable passive component miniaturization.
- MOSFET:Silicon super-junction devices persist in auxiliary power stages and low-voltage distribution where switching speeds are less critical.
IGBTs dominate installed base. Gallium nitride is climbing the fastest in OBC frequency multiplication applications.
End User:
Procurement authority and technical specification control vary sharply across customer archetypes.
- OEMs:Automotive manufacturers specify module architectures, qualify suppliers against proprietary test protocols, and negotiate direct die sourcing agreements. Vertical integration into captive power electronics production is most pronounced at Chinese battery-module integrators.
- Fleet Operators:Commercial vehicle and bus fleet managers are compressing supplier qualification timelines from 36 months toward 24 months to match accelerated platform launch schedules.
- Aftermarket Providers:Replacement module sourcing faces compatibility constraints with proprietary OEM software and thermal interfaces.
- Research Institutions:University and national laboratory programs stress emerging topologies and packaging concepts without production volume requirements.
Volume concentration rests with OEMs. Procurement autonomy is expanding fastest among fleet operators with direct supplier relationships.
Application:
Duty cycles, voltage classes, and thermal environments create distinct module specification clusters.
- Passenger Vehicles:Premium platforms at 800 V with SiC traction inverters define efficiency benchmarks. Continuous power density targets above 30 kW/liter stress substrate thermal conductivity and die attach reliability.
- Commercial Vehicles:Heavy-duty trucks and vans operate at 400-600 V with sustained high-torque loading that favors IGBT robustness over switching speed optimization.
- Two-Wheelers:Low-voltage scooters and motorcycles use compact modules with integrated controllers where cost minimization dominates specification priorities.
- Public Transport:Electric buses require megawatt-scale inverters with redundancy provisions and 15-year service life guarantees that strain semiconductor packaging technologies.
Technology leadership sits with passenger vehicles. Specification intensity is expanding most quickly in public transport electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in China's coastal provinces concentrate SiC substrate processing capacity. Dresden's semiconductor cluster anchors European automotive-grade die production. North Carolina's research triangle attracts materials science investment for wide-bandgap supply chains.
China
Premium NEV platforms from BYD and NIO pull SiC module demand at 800 V. GB standards for thermal runaway protection accelerate qualification cycles for domestic suppliers. The Yangtze River Delta cluster around Shanghai hosts concentrated packaging capacity for traction inverters.
Germany
BMW and Volkswagen procurement teams specify full-SiC traction inverters for premium EV architectures. The EU Ecodesign framework tightens standby loss limits for automotive power conversion equipment. Bavaria's automotive corridor around Munich anchors Infineon's Dresden-sourced die integration into module assemblies.
United States
Detroit Three OEMs compress supplier qualification timelines to match accelerated EV platform launches. The Inflation Reduction Act domestic content rules redirect module sourcing toward North American substrate capacity. Wolfspeed's Durham materials complex serves ramp schedules for 800 V passenger vehicle programs.
Japan
Toyota and Honda sustain IGBT module demand in 400 V hybrid platforms where efficiency requirements remain moderate. METI subsidies for next-generation semiconductor manufacturing support SiC wafer development. The Nagoya-Tokyo industrial corridor concentrates Mitsubishi Electric's vertically integrated production from crystal growth through module packaging.
South Korea
Hyundai Motor Group and Kia accelerate full-SiC adoption in E-GMP platform derivatives. MFDS automotive safety standards align with global functional safety benchmarks for power electronics. The Seoul metropolitan area clusters module packaging investment from tier-one integrators serving domestic OEM ramp schedules.
EV Power Module Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with IDM suppliers controlling SiC die supply and tier-one integrators managing thermal packaging. The vendor base concentrates around three strategic archetypes: vertically integrated semiconductor manufacturers, automotive tier-one system integrators, and substrate-focused materials specialists. Capacity expansion and strategic partnerships dominate competitive moves as firms secure wafer allocation and qualification slots.
Among European IDM suppliers, Infineon Technologies and STMicroelectronics exemplify the vertically integrated archetype controlling die fabrication and module assembly. Mitsubishi Electric represents Japanese vertical integration from crystal growth through automotive qualification. Wolfspeed anchors North American substrate supply concentration.
| Leading Market Players |
|---|
| Infineon Technologies |
| Mitsubishi Electric |
| ON Semiconductor |
| STMicroelectronics |
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Hitachi Automotive Systems |
| Wolfspeed |
| Others |
Supply & Pricing Matrix
Europe's Ecodesign for Energy-Related Products framework gates qualified supply access and premium-tier pricing eligibility for automotive power module vendors. Module suppliers must demonstrate compliance with standby loss limits and efficiency grading thresholds to secure OEM procurement slots at favorable price points.
Pricing Analysis
Lead-time-driven pricing stratification rewards short-lead-time fulfillment with premium positioning while spot inventory clears at discounted rates. Contract-based long-term offtake dominates the pricing structure, with differentiation hinging on ASIL-D certification tier and volume scale commitments. Cost compression in standard-grade IGBT modules is intensifying because Chinese packaging capacity expansion outpaces demand growth. Fleet operators exhibit highest price sensitivity, while German premium OEMs prioritize thermal performance over unit economics.
Supply Chain Analysis
The U.S. Inflation Reduction Act domestic content rules and China's GB standards are reshaping sourcing geography toward regional substrate and packaging capacity. SiC wafer supply draws from the United States, Japan, and Germany, with ceramic substrate processing anchored in China's Yangtze River Delta. Raw material dependencies include high-purity silicon carbide boules, silver sintering pastes, and direct-bonded copper substrates. Single-source vulnerability in SiC substrate supply exposes module makers to allocation risk during automotive ramp cycles. Distribution runs through direct OEM procurement relationships that displace traditional tier-two channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with SiC substrate wafer capacity bottlenecks propping pricing power for qualified vendors across the forecast window.
For Market Incumbents: Hedge silicon IGBT exposure by accelerating SiC die attach and substrate material qualification for 175°C continuous operation. Secure long-term wafer offtake agreements with Wolfspeed and Infineon to defend against allocation risk during OEM ramp cycles. Prioritize backward integration into ceramic substrate processing to capture margin pool compression from precious metal volatility.
For New Entrants and Emerging Players: Direct-to-OEM digital procurement platforms offer route-to-market access for specialized thermal interface material suppliers and gate driver IC vendors. Target India's PLI-supported automotive electronics ecosystem, where domestic EV supply chain buildout creates white-space for module packaging investment. Pursue qualification partnerships with Korean tier-one integrators pre-certifying against anticipated Ecodesign efficiency tiers.
For Investors and Strategic Acquirers: Wolfspeed's Durham capacity expansion timeline is the leading indicator that North American substrate supply will loosen from current allocation constraints. Over a multi-year horizon, vertically integrated module assemblers with captive die sourcing command superior margin durability. Monitor Chinese NEV platform launch schedules as demand inflection signal for SiC penetration rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Wolfspeed's Durham materials complex extension secures North American automotive-grade SiC substrate supply. |
| Backward Integration | Mitsubishi Electric's crystal-to-module verticality controls cost trajectories in Japanese OEM programs. |
| Platform Standardization | 800 V traction inverter convergence reduces qualification burden and enables scale economies. |
| Long-term Supply Agreement | Direct die sourcing contracts between OEMs and substrate vendors displace traditional distribution. |
| Joint Venture | European packaging partnerships with Dresden-sourced die secure regional supply security. |
Research Methodology
Multi-period observation of SiC substrate allocation patterns, OEM platform migration schedules, and module qualification cycle durations anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and semiconductor packaging specialists. Secondary validation drew from SEC filings, vehicle production databases, IHS Markit registration data, and customs records. Bottom-up module shipment tallies triangulated against top-down EV production forecasts.
Input-output matrices modeled volume and value trajectories across the projection horizon by vehicle class, propulsion architecture, semiconductor technology type, and regional production cluster. CAGRs were derived from segment-level growth rate reconciliation with aggregate market expansion. Forecast inputs included OEM 800 V platform rollout schedules, SiC wafer capacity expansion announcements, and regulatory efficiency tier implementation timelines.
The model holds under sustained NEV penetration assumptions and stable substrate supply expansion; deviation in raw material cost spikes or trade restriction escalations would shift module pricing trajectories. Forecasts reflect documented assumptions regarding technology substitution rates and qualification timeline compression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Power Amplifier Modules Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Telecom Battery Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
Buck-Boost Controller Market
Power Systems
Laptop Battery Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Global Excitation Systems Market
Power Systems
Shunt Capacitor Market
Power Systems
Converter Modules Market
Power Systems
USB Power Adapters Market
Power Systems
Asia-Pacific IGBT and Super Junction MOSFET Market
Power Systems
Thyristor Surge Protectors Market