
 Middle East and Africa IT Device Market | 2026-2036
Middle East and Africa IT Device Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa IT Device Market Foresight
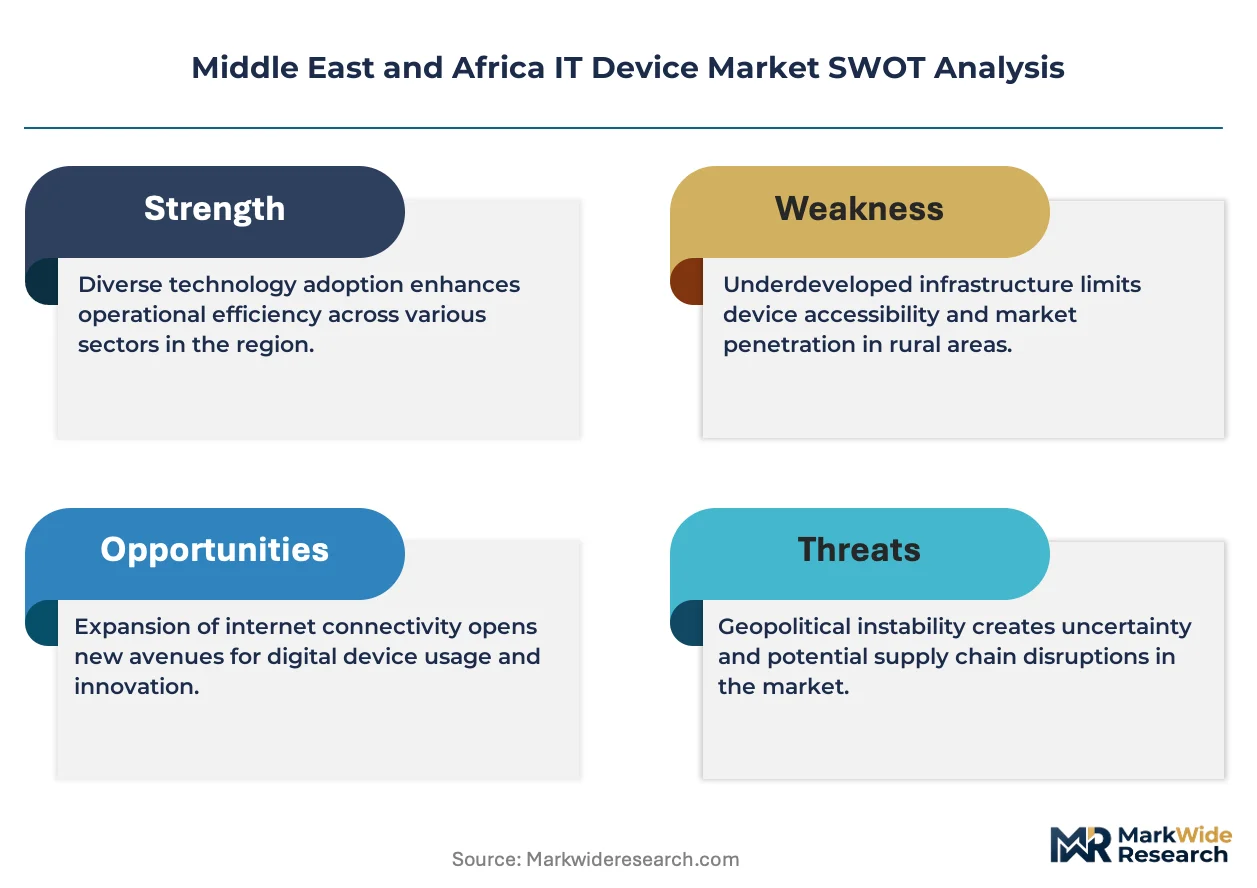
The divergence between premium enterprise-grade devices and commodity consumer hardware is realigning procurement patterns across Middle East and Africa IT channels. HP Inc anchors its position through deep channel control in Gulf corporate accounts, while Lenovo Group Limited competes aggressively on manufacturing scale to capture public-sector tenders in South Africa. Dell Technologies differentiates through service-led enterprise contracts that bundle hardware with multi-year support frameworks.
The Middle East and Africa IT Device encompasses computing and communications hardware—spanning processors with sub-7nm architectures, solid-state storage arrays, and radio modules supporting sub-6 GHz 5G bands—deployed to enable data processing, network connectivity, and digital service delivery across commercial and institutional environments. Laptops command the dominant margin pool as hybrid work policies persist in Gulf financial centers and North African outsourcing hubs. Smartphones represent the fastest-expanding volume category, driven by mobile-first banking penetration in Nigeria and Ethiopia. Cloud Computing as a technology dimension is pulling demand toward thin-client configurations that reduce per-unit component costs while shifting compute loads to regional data centers.
South Africa's POPIA framework, Nigeria's NITDA data governance guidelines, and the UAE's NESA cybersecurity standards collectively raise the compliance threshold for devices entering institutional procurement cycles. These regulations mandate hardware-level encryption, localized data residency capabilities, and traceable supply chain documentation that favors vendors with certified manufacturing partners. Stakeholders must monitor how divergent national certification timelines fragment product qualification requirements and inflate go-to-market costs for cross-border device portfolios.
Market Dynamics
Enterprise cloud migration across Gulf banking networks is compressing device refresh cycles while forcing vendors to reconfigure hardware specifications around thin-client architectures and localized data residency mandates.
Growth Catalysts
- Cloud-enabled workstation deployment:Gulf financial institutions are replacing traditional desktops with managed endpoint configurations that stream compute from regional data centers, reducing per-unit hardware costs while tightening vendor relationships.
- POPIA compliance procurement:South Africa's data-protection framework mandates hardware-level encryption for devices handling personal information, creating qualified demand for certified enterprise-grade portfolios.
- Mobile-money infrastructure expansion:Kenya's M-Pesa ecosystem and Nigeria's fintech corridor are driving volume procurement of sub-6 GHz 5G smartphones and associated merchant acceptance devices.
Market Restraints
- Component supply concentration:Sub-7nm processor fabrication depends on a concentrated East Asian supplier base, exposing procurement timelines to geopolitical friction and export control variability.
- Currency volatility impact:Nigerian naira and South African rand depreciation against dollar-denominated component contracts is inflating landed costs for institutional buyers with fixed local-currency budgets.
- Fragmented certification timelines:Divergent national approval processes across UAE NESA, Saudi CITC, and Egyptian NTRA standards delay product launches and inflate qualification overhead for cross-border portfolios.
Strategic Opportunities
- Ethiopia's underpenetrated banking digitization:The country's state-led financial modernization is creating first-mover opportunities for device vendors willing to establish local assembly partnerships and comply with emerging data-localization rules.
- Edge computing convergence with 5G:Mining operations in Zambia and Botswana are piloting on-site processing nodes that combine ruggedized industrial PCs with private network infrastructure, opening industrial IoT hardware demand.
- Green procurement mandates:UAE and Saudi government tenders are increasingly weighting energy-efficiency certifications and circular-economy documentation, favoring vendors with certified recycling partnerships and low-carbon manufacturing disclosures.
Industry Challenges
- Certification backlog congestion:Nigeria's NITDA type-approval queue for data-processing hardware has extended beyond eight months, freezing product launches and compressing effective selling seasons.
- Legacy system integration friction:North African public-sector buyers in Morocco and Tunisia operate mixed fleets of decade-old Windows 7 endpoints and modern cloud-ready devices, complicating unified endpoint management deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa IT Device Market |
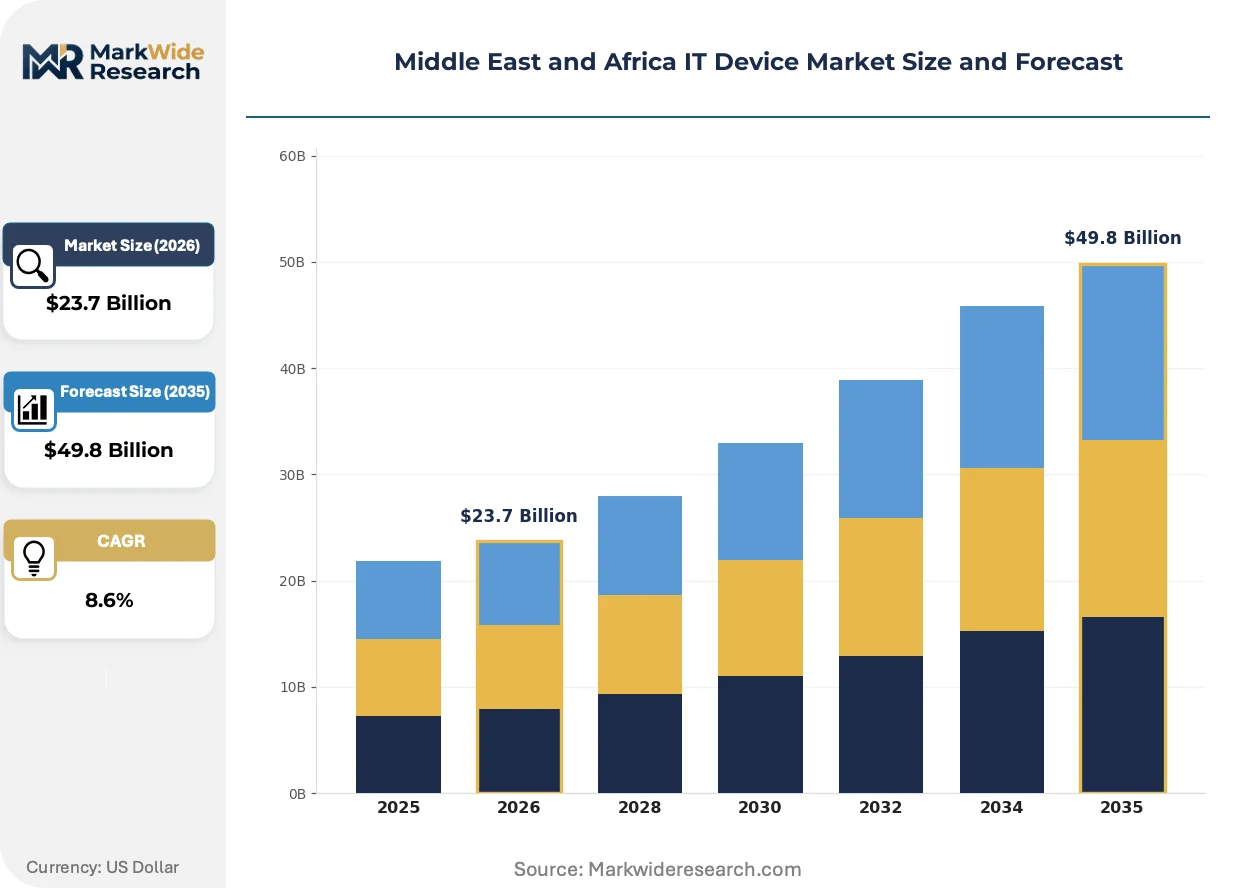
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Laptops, Desktops End User: Households, Enterprises, Educational Institutions, Government Agencies Technology: 5G, Wi-Fi 6, Augmented Reality, Cloud Computing Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | HP Inc, Lenovo Group Limited, Dell Technologies, Samsung Electronics Co Ltd, Apple Inc, Huawei Technologies Co Ltd, Xiaomi Corporation, Acer Group, ASUSTek Computer Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa IT Device Market Shifts & Advancements
Hardware architecture is converging around software-defined endpoints that shift computational loads off-device, while regulatory fragmentation forces vendors to maintain parallel certification tracks for otherwise identical products.
Unified endpoint management platforms are unifying previously siloed device control, security policy enforcement, and application delivery into single-pane administration. Large South African mining houses and Gulf logistics operators are adopting these stacks aggressively to reduce IT headcount. This convergence is unifying procurement decisions around ecosystem breadth rather than standalone hardware specifications, compressing margins for pure-play device manufacturers.
South Africa's POPIA enforcement is tightening hardware encryption requirements for any device processing resident personal data, with the national information regulator issuing specific technical standards for key management and audit logging. Banking and healthcare procurement committees are now disqualifying uncertified portfolios at the RFP stage. Vendors are responding by pre-integrating hardware security modules and localized key storage into standard enterprise SKUs rather than treating these as premium options.
Enterprise buyers across the Gulf are compressing device replacement cycles from four years to twenty-four months for cloud-dependent roles, while extending legacy hardware lifespans for offline functions through third-party maintenance contracts. This bifurcation is fragmenting vendor relationships: cloud-ready endpoint suppliers capture premium recurring revenue, while independent service organizations absorb the aftermarket for aging installed bases. The pattern is most pronounced in Dubai's financial free zones and Riyadh's government digitization programs.
Middle East and Africa IT Device Market Segmentation
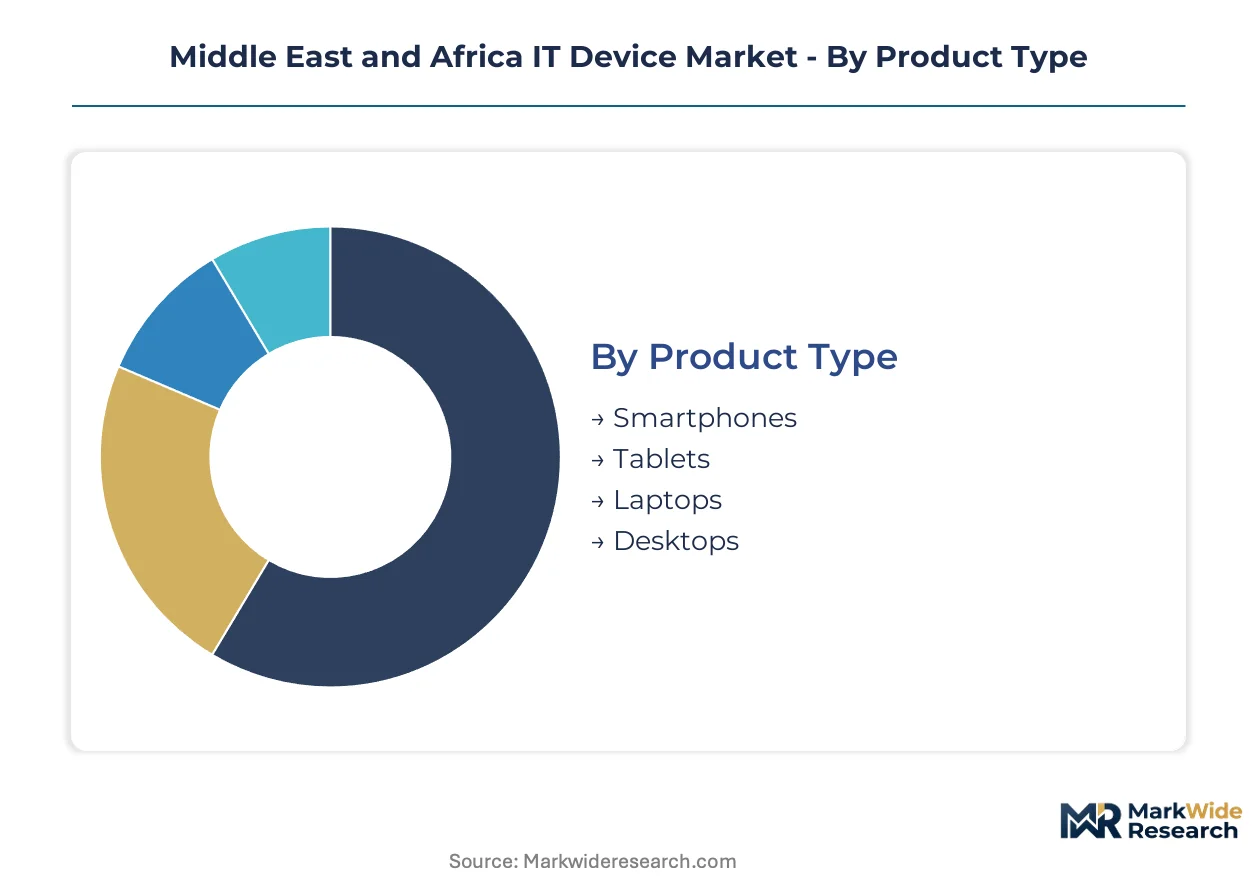
Segmentation across the Middle East and Africa IT Device Market reveals divergent capital requirements and margin structures. Hardware categories demand heavy semiconductor inventory exposure, while channel strategies vary dramatically in working capital intensity.
Product Type:
Capital intensity peaks with laptops and their sub-7nm processor supply chains, while smartphones operate on thinner margins but faster inventory turns.
- Laptops:Sub-7nm processor architectures and solid-state storage arrays dominate bill-of-materials costs. Gulf banking networks and North African outsourcing hubs in Casablanca and Cairo concentrate procurement for hybrid workforces, with POPIA-compliant encryption modules now mandatory for South African financial buyers.
- Smartphones:Sub-6 GHz 5G radio modules and high-refresh-rate OLED panels define technical specifications. Nigeria's fintech corridor and Kenya's M-Pesa merchant ecosystem drive volume demand, though naira depreciation against dollar-denominated component contracts compresses distributor margins.
- Tablets:Education ministries in UAE and Saudi Arabia issue bulk tenders for stylus-enabled classroom devices.
- Desktops:Thin-client configurations are displacing traditional tower deployments in Gulf enterprise accounts as cloud migration accelerates.
Laptops absorb the bulk of installed capacity; smartphones are expanding most quickly.
End User:
Enterprise procurement cycles stretch 18-24 months with complex certification requirements, while household purchases respond immediately to currency fluctuations and financing availability.
- Enterprises:Gulf banking networks and South African mining houses mandate hardware security modules and localized key storage. NESA cybersecurity standards in UAE and POPIA encryption rules in South Africa disqualify uncertified portfolios at the RFP stage, extending qualification timelines.
- Government Agencies:Saudi government digitization programs and Dubai's financial free zones compress replacement cycles to twenty-four months for cloud-dependent roles. Green procurement mandates increasingly weight energy-efficiency certifications and circular-economy documentation.
- Households:Mobile-first banking penetration in Nigeria and Ethiopia drives entry-level 5G smartphone adoption despite currency headwinds.
- Educational Institutions:State-led modernization in Ethiopia and Tunisia creates first-mover opportunities for vendors establishing local assembly partnerships.
Enterprises command the premium pricing tier; government agencies are climbing the fastest on volume.
Technology:
5G infrastructure deployment demands the heaviest upfront spectrum investment, while cloud computing shifts capital expenditure from endpoints to data center buildouts.
- 5G:Sub-6 GHz radio modules support mobile-money infrastructure across Kenya and Nigeria. Private network pilots in Zambian and Botswanan mining operations combine ruggedized industrial hardware with on-site processing nodes.
- Cloud Computing:Thin-client architectures reduce per-unit component costs while shifting compute loads to regional data centers in UAE and South Africa. Gulf financial institutions favor managed endpoint configurations that stream processing from localized facilities.
- Wi-Fi 6:Enterprise campus upgrades in Riyadh and Johannesburg prioritize low-latency connectivity for unified endpoint management platforms.
- Augmented Reality:Industrial maintenance applications in Gulf logistics operators remain nascent, with pilot deployments concentrated in Dubai's port automation projects.
Cloud Computing is capturing the steepest expansion trajectory as enterprise migration accelerates; 5G maintains the largest installed base.
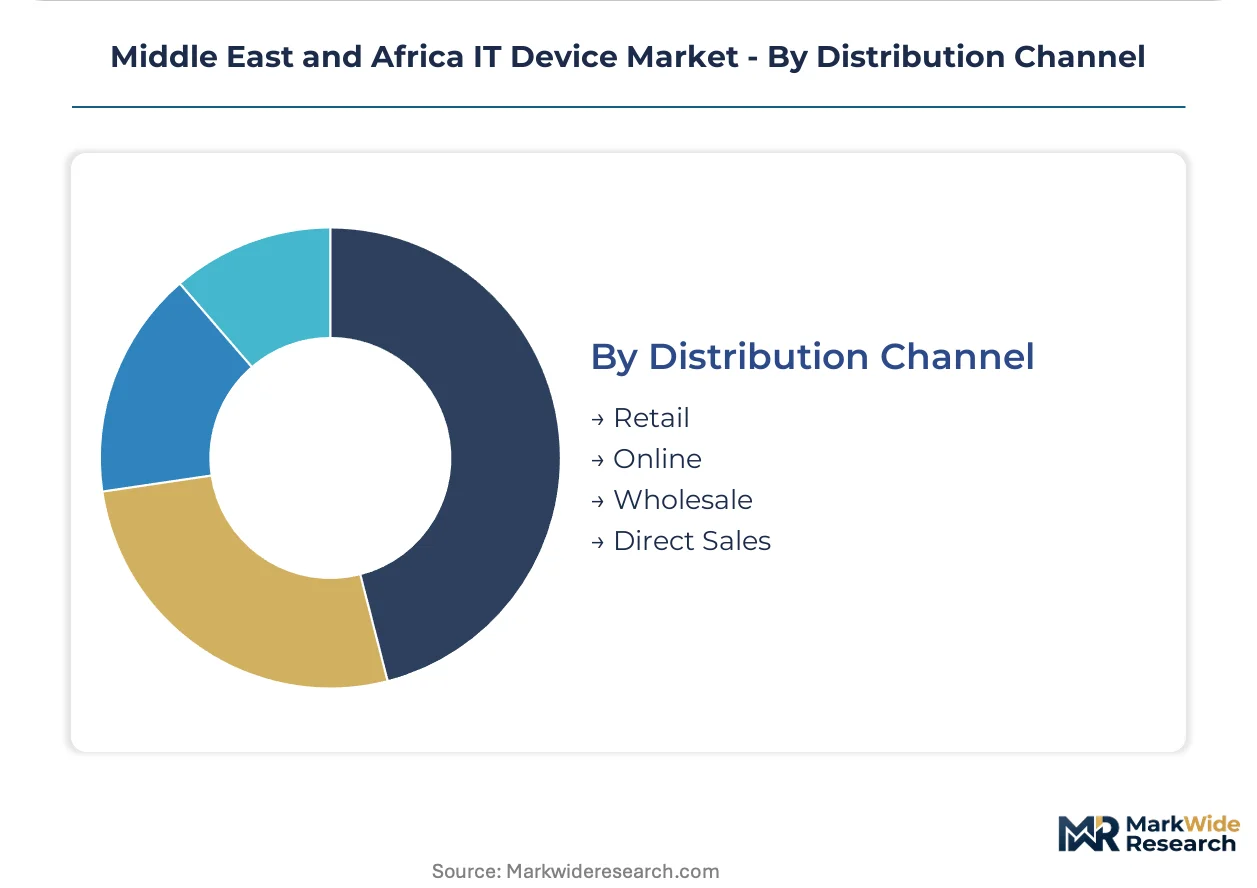
Distribution Channel:
Direct sales require dedicated enterprise salesforces and certification expertise, while online channels demand logistics infrastructure and payment gateway integration.
- Direct Sales:Multi-year service contracts bundle hardware with support frameworks for South African mining houses and Gulf logistics operators. Dell Technologies and HP Inc anchor positions through deep channel control in corporate accounts.
- Wholesale:Regional distributors in Lagos and Nairobi manage currency hedging for naira and rand volatility, extending credit to sub-distributors serving secondary cities.
- Retail:Mall-based electronics chains in Dubai and Johannesburg face compression from online price transparency.
- Online:Jumia and Noon.com aggregate demand across fragmented geographies, though last-mile delivery remains challenging outside major metros.
Direct Sales locks in the highest-value contracts; Online is gaining share fastest among household segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's financial free zones anchor enterprise device procurement across the Gulf Cooperation Council, where banking digitization and government modernization programs concentrate demand for cloud-ready endpoints.
United Arab Emirates
Dubai International Financial Centre and Abu Dhabi Global Market drive enterprise laptop refresh cycles for hybrid workforces. NESA cybersecurity standards mandate hardware-level encryption and localized data residency capabilities for institutional procurement. Dubai's logistics operators pilot ruggedized industrial hardware for port automation projects.
Saudi Arabia
Riyadh's government digitization programs and Vision 2030 initiatives compress device replacement timelines to twenty-four months for cloud-dependent roles. CITC certification requirements extend product qualification timelines for cross-border vendors. NEOM's technology zone attracts vendors establishing regional assembly partnerships.
South Africa
Johannesburg's mining houses and Cape Town's financial services sector mandate POPIA-compliant encryption modules for devices handling personal information. The national information regulator issues specific technical standards for key management and audit logging. Gauteng province concentrates procurement for unified endpoint management platforms.
Nigeria
Lagos anchors the fintech corridor where mobile-first banking penetration drives volume demand for sub-6 GHz 5G smartphones. NITDA data governance guidelines and type-approval queues extending beyond eight months freeze product launches. Naira depreciation against dollar-denominated component contracts inflates landed costs for institutional buyers.
Kenya
Nairobi's M-Pesa merchant ecosystem drives procurement of smartphones and associated point-of-sale acceptance devices. The central bank's mobile-money regulations shape hardware specifications for financial inclusion programs. Konza Technology City's data center buildouts shift compute loads from endpoints to regional cloud infrastructure.
Middle East and Africa IT Device Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Middle East and Africa IT Device Market, with fabrication scale separating tier-one suppliers from assembly-dependent challengers. The vendor base clusters around three strategic archetypes: integrated multinationals controlling semiconductor supply chains, regional assemblers leveraging local content rules, and ecosystem specialists bundling hardware with managed services. Dominant competitive moves include backward integration into component manufacturing and strategic partnerships with regional data center operators.
Within the integrated multinational tier, HP Inc, Lenovo Group Limited, and Dell Technologies occupy positions defined by channel depth and service attach rates. HP Inc anchors Gulf corporate accounts through direct enterprise relationships. Lenovo Group Limited exemplifies scale-driven competition for public-sector tenders. Dell Technologies represents the service-led archetype bundling hardware with multi-year support frameworks.
| Leading Market Players |
|---|
| HP Inc |
| Lenovo Group Limited |
| Dell Technologies |
| Samsung Electronics Co Ltd |
| Apple Inc |
| Huawei Technologies Co Ltd |
| Xiaomi Corporation |
| Acer Group |
| ASUSTek Computer Inc |
| Others |
Supply & Pricing Matrix
Thin-client workstation deployment across Gulf financial networks is compressing per-unit hardware costs while shifting margin capture toward recurring managed-service contracts and regional data-center partnerships. This architectural transition simultaneously reduces component intensity in endpoints and concentrates procurement leverage among buyers with multi-year cloud migration commitments.
Pricing Analysis
Outcome-based pricing tied to device uptime and security compliance now anchors enterprise negotiations in South African banking and Gulf government tenders. Three-tier pricing structure across premium enterprise, certified standard, and unmanaged economy levels reflects encryption certification status and localized support bundling. Cost compression in the economy tier is intensifying because naira and rand depreciation against dollar-denominated component contracts squeezes distributor margins. Household segments in Nigeria and Ethiopia exhibit highest price sensitivity, while South African mining houses and UAE financial institutions prioritize compliance-grade specifications over unit cost.
Supply Chain Analysis
Freight cost volatility on Asia-Middle East routes and Red Sea disruption contingencies are forcing inventory pre-positioning in Dubai Jebel Ali and Lagos free zones. Sub-7nm processor fabrication draws from Taiwan and South Korea, with memory modules and OLED panels sourcing predominantly from China and Vietnam. Single-source vulnerability in advanced node semiconductor supply exposes procurement timelines to export control variability. Distribution runs through regional distributors in Lagos and Nairobi who manage currency hedging for naira and rand exposure, extending credit to sub-distributors serving secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa IT Device Market sits in a technology-transition phase where cloud-enabled endpoints are displacing traditional fat-client architectures, compressing hardware refresh cycles while elevating service-attach revenue.
For Market Incumbents: Deepen backward integration into hardware security module supply to defend margin position against certified-component shortages that now disqualify portfolios at South African POPIA and UAE NESA RFP stages. Fortify channel control in Gulf corporate accounts through multi-year managed endpoint contracts that bundle thin-client hardware with localized data-center connectivity, raising switching costs for banking and logistics buyers. For New Entrants and Emerging Players: Enter via Ethiopia's state-led banking digitization programs where first-mover status in local assembly partnerships unlocks preferential procurement positioning before data-localization rules harden. Target Kenya's M-Pesa merchant ecosystem with ruggedized point-of-sale acceptance devices engineered for intermittent power and dust exposure, leveraging mobile-money infrastructure expansion as the go-to-market anchor. For Investors and Strategic Acquirers: Re-rating potential sits with regional assemblers possessing certified manufacturing partnerships and in-country technical support infrastructure given green procurement mandates in UAE and Saudi government tenders. Long-term viability over the next decade hinges on compliance-grade certification breadth rather than manufacturing scale alone. Monitor NITDA type-approval queue lengths in Nigeria as the inflection indicator for cross-border product launch velocity and effective selling season capture.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | Ethiopia's emerging data-localization rules favor vendors with domestic manufacturing presence and certified technical support. |
| Hardware Security Module Integration | POPIA and NESA encryption mandates now require pre-integrated key management at the RFP qualification stage. |
| Managed Endpoint Service Contract | Gulf banking networks prioritize thin-client configurations streaming compute from regional UAE data centers. |
| Green Procurement Certification | Saudi and UAE government tenders increasingly weight energy-efficiency documentation and circular-economy partnerships. |
| Currency Hedging Infrastructure | Nigerian distributors with naira-dollar hedging capabilities capture margin that unhedged competitors lose to depreciation. |
Research Methodology
Independent corroboration across primary interviews with IT procurement officers at Gulf financial institutions, channel distribution heads in Lagos and Nairobi, and regulatory compliance leads at South African mining houses underwrites the qualitative findings. Secondary validation draws from NITDA type-approval databases, NESA cybersecurity certification registries, POPIA technical standard disclosures, and customs import records for semiconductor components. Bottom-up demand modeling across enterprise, government, and household segments triangulates against top-down market sizing from regional distributor revenue disclosures and OEM regional business unit filings.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology adoption stage, and distribution channel intensity, with additional granularity on encryption certification tier and localized data-residency capability. CAGRs derive from installed base evolution, replacement cycle compression patterns, and technology substitution curves. Cloud migration velocity in Gulf banking and mobile-money penetration rates in Nigeria and Kenya serve as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained currency depreciation in Nigeria and South Africa or extended semiconductor export control restrictions. Forecasts reflect assumptions on regulatory certification timeline normalization and regional data-center buildout completion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IT Hardware
India IT Hardware Market
IT Hardware
Global 4K Set Top Box (STB) Market
IT Hardware
Asia Pacific IT Device Market
IT Hardware
Europe IT Device Market
IT Hardware
Three-Proof Laptop Market
IT Hardware
Single Board Computer Market
IT Hardware
USB 3.0 Market
IT Hardware
Tablet PC Market
IT Hardware
Server Chassis Market
IT Hardware
Global IT Hardware Market
IT Hardware
Industrial Motherboards Market
IT Hardware
Cloud IT Infrastructure Hardware Market
IT Hardware
PC Case Market