
 Vacuum Pressure Impregnated (VPI) Transformer Market | 2026-2036
Vacuum Pressure Impregnated (VPI) Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Pressure Impregnated (VPI) Transformer Market Analysis
Class H insulation and epoxy-encapsulated winding specifications is rotating through utility procurement channels as operators prioritize thermal endurance and reduced fire risk in dense urban installations. Siemens Energy leverages its European manufacturing footprint to supply resin-cast VPI units for metro rail electrification. Hitachi Energy anchors the Asia-Pacific project pipeline through localized production of three-phase distribution transformers. CG Power specializes in tropical-climate-rated designs with enhanced moisture resistance for Indian substation operators.
Vacuum Pressure Impregnated (VPI) Transformers are electrical devices where winding assemblies undergo vacuum evacuation followed by pressure-driven resin impregnation, typically achieving dielectric strength above 20 kV/mm and thermal class ratings up to 180 degrees Celsius. The process eliminates voids that cause partial discharge, making these units suitable for indoor commercial installations and offshore renewable platforms where mineral-oil alternatives pose fire hazards. Three-phase configurations occupy the dominant share of utility procurement volumes due to grid-scale distribution requirements, while epoxy resin insulation commands premium positioning over paper-based alternatives because of superior moisture ingress protection and compatibility with IEC 60076-11 dry-type standards. Renewable integration applications are expanding fastest as wind and solar farms require non-flammable transformer technologies for nacelle and substation deployment.
FDA oversight of electrical equipment in healthcare facility infrastructure, combined with EPA restrictions on polychlorinated biphenyls in legacy transformer fleets, is redirecting replacement demand toward resin-impregnated dry-type designs in the United States. The EU F-Gas Regulation and REACH chemical compliance frameworks are compressing availability of conventional insulating fluids, elevating VPI transformers as the default specification for indoor industrial and commercial installations across Europe. Stakeholders must monitor evolving national building codes and carbon-border adjustment mechanisms to anticipate specification-tier migrations and localize supply chains ahead of procurement cycle shifts.
Market Dynamics
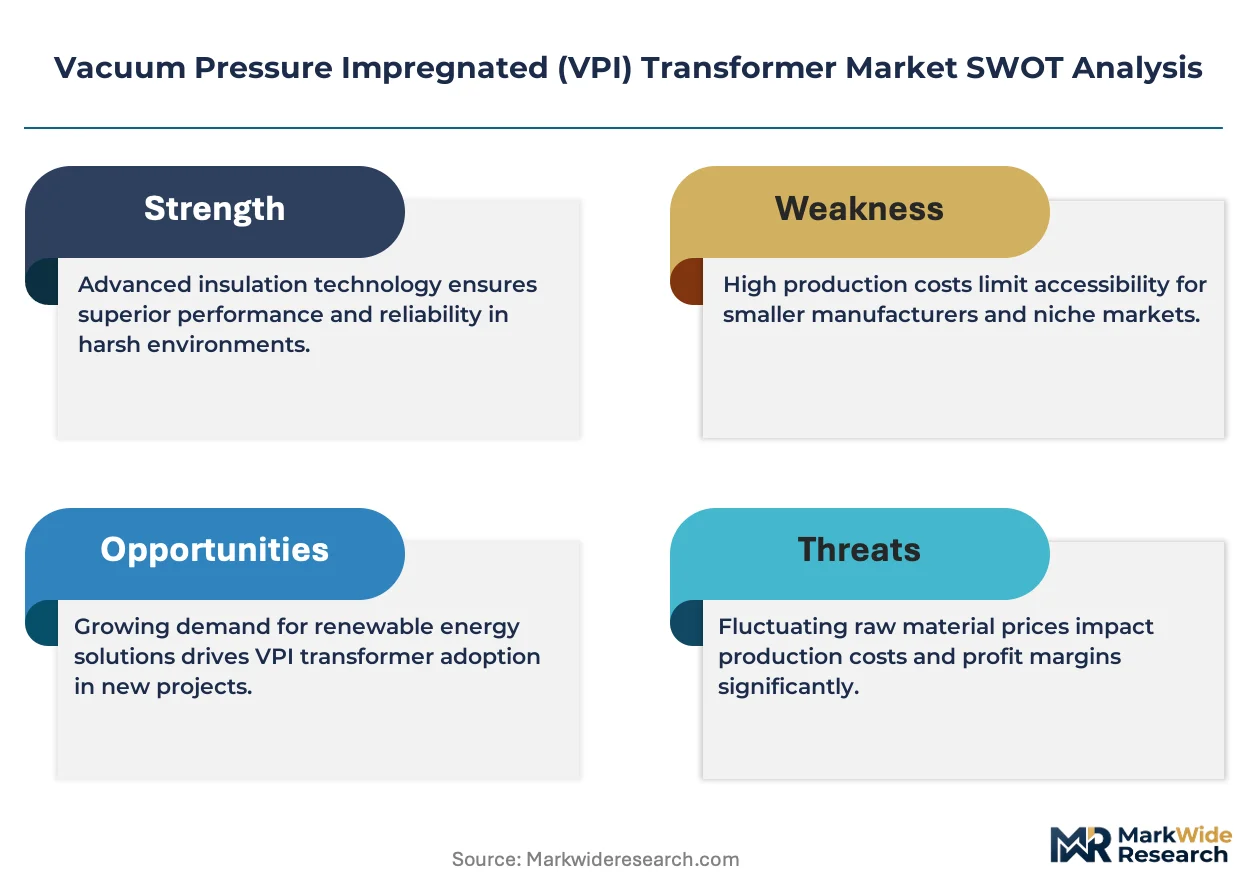
Urban substation densification is compressing procurement cycles for resin-sealed distribution assets as utilities prioritize fire-safety compliance over first-cost economics in indoor installations.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases in conventional insulating fluids is redirecting industrial transformer procurement toward epoxy-impregnated dry-type designs across German and French manufacturing corridors.
- Metro rail electrification:Underground transit authorities in India and China are specifying Class H insulation systems for traction substations where mineral-oil fire risk is prohibitive.
- Wind farm nacelle deployment:Offshore renewable developers are mandating non-flammable transformer technologies for turbine-integrated step-up applications in North Sea installations.
Market Restraints
- Copper price volatility:Winding conductor costs constitute 35-45% of unit manufacturing expense, exposing margin structures to London Metal Exchange commodity swings.
- Epoxy resin supply concentration:Specialized bisphenol-A and anhydride curing agent production clusters in Northeast Asian chemical corridors create input bottleneck risks.
- Dimensional constraints:Resin-encapsulated designs require 15-20% larger physical footprints than equivalent oil-filled units, complicating retrofit applications in legacy substation buildings.
Strategic Opportunities
- Healthcare infrastructure modernization:FDA electrical safety mandates for hospital substations are opening replacement demand for low-smoke zero-halogen VPI configurations in US medical campus expansions.
- Digital substation integration:Convergence of IEC 61850 communication protocols with embedded thermal monitoring sensors is creating premium-tier product differentiation.
- Commercial building electrification:India's Energy Conservation Building Code enforcement is accelerating specification of dry-type transformers in Tier-1 metropolitan high-rise developments.
Industry Challenges
- Vacuum impregnation technician scarcity:Specialized resin handling and void-elimination process expertise resides with aging workforces in European and Japanese manufacturing bases.
- IEC 60076-11 certification timelines:Third-party thermal class verification and short-circuit withstand testing extends product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Pressure Impregnated (VPI) Transformer Market |
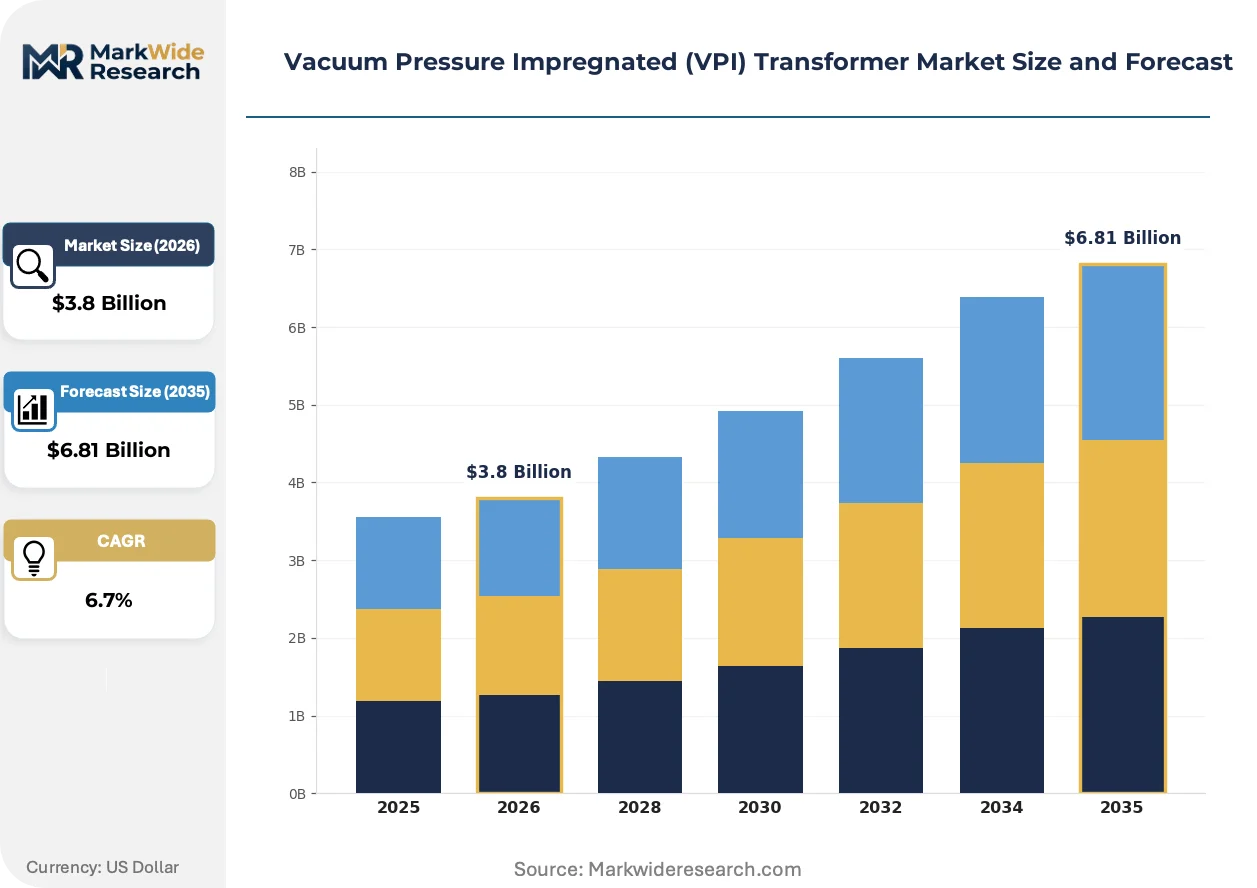
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Pole-Mounted, Pad-Mounted Insulation Material: Epoxy Resin, Paper-Based, Silicone, Polyurethane End User: Utilities, Industrial Plants, Commercial Buildings, Renewable Energy Application: Power Distribution, Motor Drives, Renewable Integration, Voltage Regulation |
| Companies Covered | Siemens Energy, Bharat Heavy Electricals, ABB, General Electric, Schneider Electric, CG Power, Hitachi Energy, Toshiba Energy Systems, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Pressure Impregnated (VPI) Transformer Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are restructuring competitive differentiation around thermal endurance and environmental compliance rather than traditional cost-per-kVA metrics.
Epoxy-anhydride resin systems with nano-filler additives are decomposing the traditional trade-off between dielectric strength and thermal conductivity in medium-voltage windings. Wind turbine OEMs are adopting these formulations for 66 kV class nacelle transformers operating at 155°C continuous hot-spot temperatures. The technology is decomposing established supplier hierarchies by enabling Asian component specialists to meet previously European-dominated offshore specifications.
REACH chemical authorization requirements are constraining halogenated flame retardant use in winding insulation across European industrial installations. Manufacturers are reformulating with phosphorus-based and metal-hydroxide alternatives that maintain UL 94 V-0 ratings without SVHC substance inclusion. German and Italian electrical distributors are prioritizing inventory positions with suppliers holding full SCIP database disclosure compliance.
Utility procurement offices are compressing vendor qualification cycles through pre-certified product platform agreements rather than project-specific technical specifications. Engineering-procurement-construction firms are consolidating transformer purchasing under multi-year framework contracts with thermal class upgrade options. This pattern is most pronounced in Indian state transmission utilities executing centralized procurement for urban distribution network reinforcement.
Vacuum Pressure Impregnated (VPI) Transformer Market Segmentation
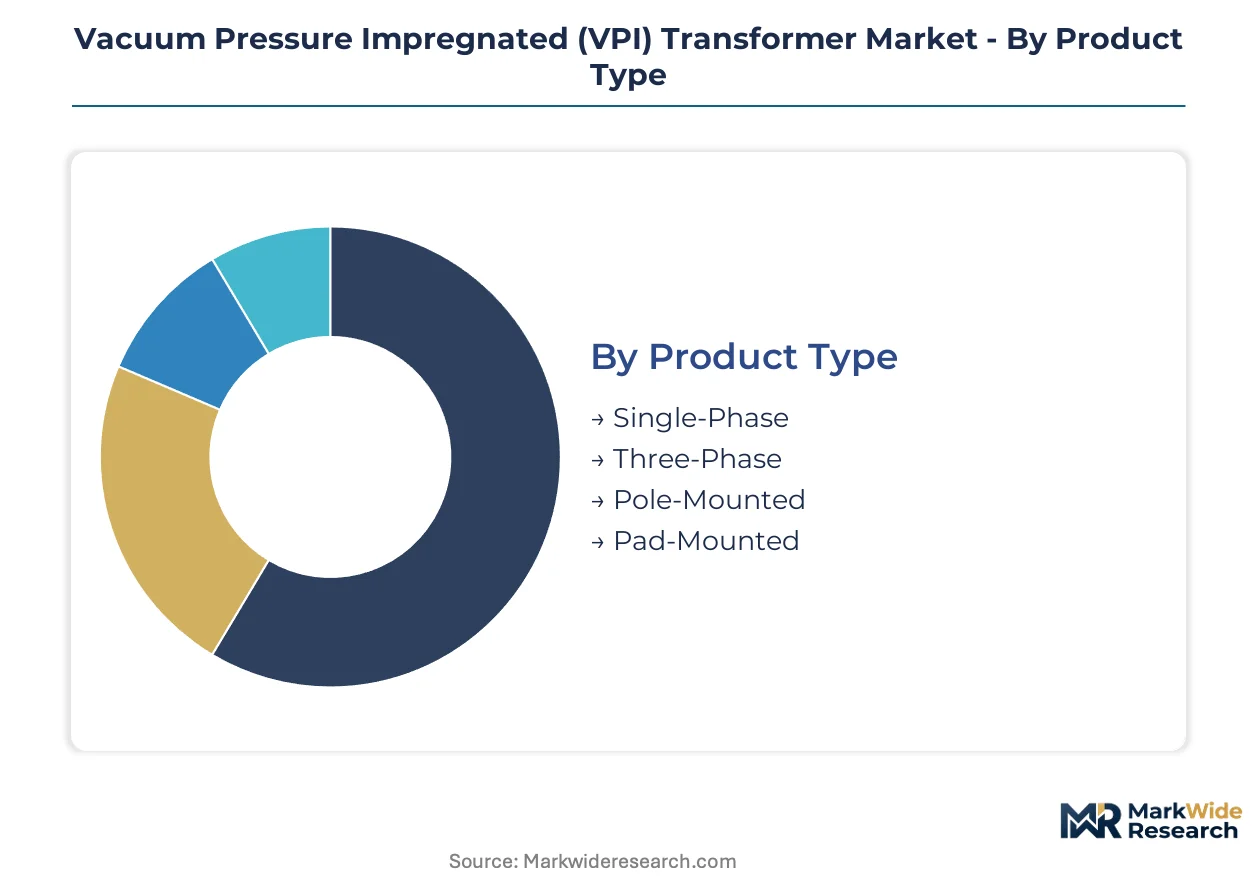
VPI transformer procurement patterns diverge sharply across product architectures and end-use environments. Specification requirements for thermal class, fire resistance, and dimensional constraints reshape demand concentration within each segment cluster.
Product Type:
Domestic procurement dominates pad-mounted and pole-mounted categories, while three-phase units flow through export channels to infrastructure projects across multiple continents.
- Three-Phase:Grid-scale distribution infrastructure specifies these units for 11 kV to 33 kV substation networks. Indian state transmission utilities and German industrial corridor operators concentrate procurement here, driven by IEC 60076-11 dry-type compliance mandates in dense urban installations.
- Single-Phase:Rural electrification programs and residential distribution feeders specify compact single-phase designs. Isolated demand pockets in North American residential subdivisions and Japanese mountain village grids sustain this segment against three-phase dominance.
- Pole-Mounted:Overhead distribution networks in tropical climates specify these for space-constrained urban alleys.
- Pad-Mounted:Underground commercial developments in US metropolitan cores favor pad-mounted resin-sealed units for sidewalk-level transformer vaults.
Three-Phase holds the largest share; momentum sits with Pad-Mounted configurations as urban densification accelerates.
Insulation Material:
Epoxy resin commands premium positioning through thermal performance advantages, while paper-based alternatives serve cost-sensitive retrofit applications.
- Epoxy Resin:Vacuum-pressure-impregnated bisphenol-A and anhydride formulations achieve dielectric strength above 20 kV/mm with 180°C thermal class ratings. Offshore wind developers in the North Sea and metro rail authorities in India specify these for fire-safety-critical nacelle and traction substation installations.
- Paper-Based:Cellulose insulation with oil-impregnated variants persists in legacy transformer refurbishment. Eastern European industrial plants with dated substation infrastructure represent the residual demand concentration as operators phase out mineral-oil units under EU F-Gas Regulation timelines.
- Silicone:Flexible high-temperature formulations suit compact winding geometries in specialty motor drive applications.
- Polyurethane:Lower-cost encapsulation serves temporary construction power and portable distribution skids.
Epoxy Resin dominates procurement value; Silicone is climbing the fastest as motor drive OEMs seek compact thermal solutions.
End User:
Utility procurement operates through centralized tender frameworks, while commercial building developers specify through engineering-procurement-construction contractor channels.
- Utilities:State-owned transmission companies execute multi-year framework agreements for distribution network reinforcement. India's Power Grid Corporation and German municipal utilities concentrate procurement of Class H insulation systems for urban substation densification programs.
- Renewable Energy:Wind turbine OEMs and solar farm developers mandate non-flammable transformer technologies. Offshore wind installation contractors in Danish and UK waters specify resin-cast units for turbine-integrated step-up transformers exposed to salt spray and fire risk.
- Industrial Plants:Manufacturing corridors in automotive and chemical processing specify VPI units for indoor substation fire compliance.
- Commercial Buildings:High-rise developers in Mumbai, Bangalore, and Delhi NCR specify dry-type transformers under Energy Conservation Building Code enforcement.
Utilities command the dominant procurement volume; Renewable Energy shows the steepest expansion trajectory as offshore wind capacity builds out.
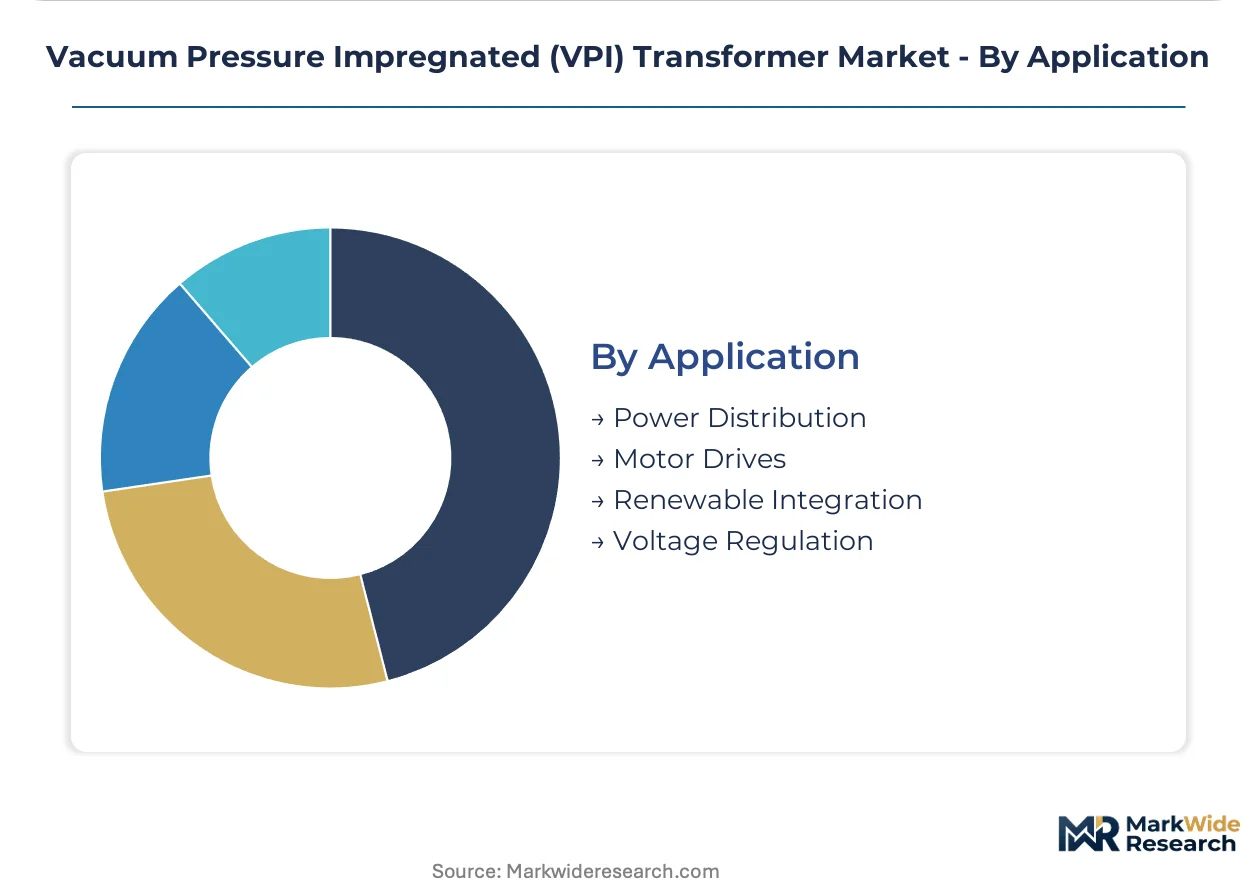
Application:
Power distribution absorbs baseline manufacturing capacity, while renewable integration applications pull specialized thermal class and compact form factor development.
- Power Distribution:Primary and secondary distribution networks specify resin-impregnated units for 11 kV to 36 kV voltage classes. Urban utilities in France, Italy, and India rotate procurement toward dry-type designs as indoor substation fire codes tighten.
- Renewable Integration:Wind farm collection systems and solar inverter step-up applications require non-flammable transformer technologies. Turbine OEMs specify 66 kV class nacelle transformers with 155°C continuous hot-spot capability for North Sea and Baltic Sea installations.
- Motor Drives:Variable frequency drive isolation transformers protect sensitive control electronics in industrial automation.
- Voltage Regulation:On-load tap changer integration with VPI winding assemblies serves grid stability applications.
Power Distribution retains the largest installed base; Renewable Integration is gaining share fastest as offshore wind procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European and Japanese manufacturers retain concentrated expertise in vacuum impregnation process engineering, while Asian utilities drive procurement volume through urban electrification programs. This geographic split shapes competitive positioning across technology tiers.
Germany
Industrial corridor operators specify Class H insulation systems for manufacturing plant substations under EU F-Gas Regulation phase-down timelines. ECHA chemical compliance frameworks constrain conventional insulating fluid availability. Bavarian electrical distributors prioritize SCIP database disclosure compliance from resin-cast transformer suppliers.
India
State transmission utilities execute centralized procurement for urban distribution network reinforcement through multi-year framework agreements. CEA technical standards mandate dry-type transformer specifications for indoor commercial installations. Maharashtra and Gujarat industrial clusters concentrate manufacturing capacity for tropical-climate-rated designs.
United States
FDA electrical safety mandates redirect hospital substation replacement demand toward low-smoke zero-halogen VPI configurations. EPA PCB restrictions accelerate legacy transformer fleet modernization. Medical campus expansions in Texas and California drive specification of resin-sealed units for healthcare infrastructure.
China
Metro rail authorities specify Class H insulation for underground traction substations where mineral-oil fire risk is prohibitive. MIIT industrial standards align with IEC 60076-11 dry-type compliance frameworks. Yangtze River Delta manufacturing bases supply resin-cast units for domestic and export project pipelines.
United Kingdom
Offshore wind developers mandate non-flammable transformer technologies for North Sea turbine-integrated step-up applications. EU F-Gas Regulation alignment constrains conventional insulating fluid procurement. Scottish and English coastal installation contractors concentrate demand for 66 kV class nacelle transformers.
Vacuum Pressure Impregnated (VPI) Transformer Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. European and Japanese incumbents dominate premium thermal class specifications through accumulated process expertise, while Asian fabricators compete on scale and localization. The market separates into three strategic archetypes: integrated electrical conglomerates with full power equipment portfolios, specialized transformer manufacturers with regional density, and component-focused suppliers serving niche thermal requirements. Competitive moves concentrate on geographic expansion through localized production partnerships and portfolio diversification into digital monitoring integration.
Among integrated electrical conglomerates, Siemens Energy and Hitachi Energy occupy positions spanning premium-tier product development and utility-scale project execution. CG Power exemplifies regional specialist archetype concentration, anchoring tropical-climate-rated design capabilities for Indian substation operators. These three companies represent distinct competitive positioning vectors: European manufacturing footprint leverage, Asia-Pacific localized production scale, and emerging market environmental adaptation specialization.
| Leading Market Players |
|---|
| Siemens Energy |
| Bharat Heavy Electricals |
| ABB |
| General Electric |
| Schneider Electric |
| CG Power |
| Hitachi Energy |
| Toshiba Energy Systems |
| Eaton |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Northeast Asian epoxy resin facilities shapes both supply concentration and price floors for VPI transformer manufacturers. German and Indian utilities absorb premium-tier output while cost-sensitive retrofit buyers in Eastern Europe anchor economy-tier demand.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates IEC 60076-11 certified Class H units from uncertified alternatives. Cost compression in economy tiers is intensifying because of copper price volatility on the London Metal Exchange. Industrial plant operators in automotive corridors show highest price sensitivity, while offshore wind developers demonstrate lowest sensitivity due to fire-safety compliance mandates.
Supply Chain Analysis
Strategic stockpile preferences dominate raw material procurement as manufacturers buffer against epoxy resin supply disruptions. Production clusters in Germany, China, and India feed winding conductor and resin formulation requirements. Specialized bisphenol-A and anhydride curing agent production draws from concentrated Northeast Asian chemical corridors. Single-source vulnerability in nano-filler additives for high-thermal-class windings threatens premium-tier output. Distribution runs through engineering-procurement-construction contractor networks for utility-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VPI transformer manufacturing constitutes a defensive-moat market anchored by regulatory entrenchment. IEC 60076-11 certification requirements and REACH chemical compliance create switching costs that protect qualified incumbent positions.
For Market Incumbents: Shield market position through backward integration into epoxy resin formulation capabilities and captive supply of Class H insulation systems. Siemens Energy and Hitachi Energy should accelerate tropical-climate-rated design capacity in Indian manufacturing corridors before CEA technical standards tighten further. Vacuum impregnation technician scarcity in European and Japanese bases threatens output scalability.
For New Entrants and Emerging Players: IEC 61850 digital integration certification offers a fast-track into premium-tier procurement channels. White-space concentration sits with healthcare infrastructure modernization in US medical campuses and motor drive isolation transformers for industrial automation. Target US hospital substation replacement demand through low-smoke zero-halogen configuration specialization.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated electrical conglomerates with multi-year utility framework agreements. Long-term viability favors manufacturers with captive resin supply and digital monitoring integration capabilities. Acquisition targets should demonstrate full SCIP database disclosure compliance and IEC 60076-11 pre-certification. Watch for copper price stabilization as inflection indicator for margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin | Captive supply of bisphenol-A formulations insulates margin structures from Northeast Asian chemical corridor bottlenecks. |
| Digital Substation Integration | IEC 61850 protocol convergence with embedded thermal sensors creates premium-tier differentiation against commodity suppliers. |
| Tropical-Climate Manufacturing Footprint | Localized production in Maharashtra and Gujarat industrial clusters addresses CEA dry-type mandates for Indian utilities. |
| Healthcare Infrastructure Certification | FDA electrical safety compliance for low-smoke zero-halogen configurations opens US medical campus replacement demand. |
| Offshore Wind Nacelle Specialization | 66 kV class thermal endurance ratings capture North Sea and Baltic Sea turbine-integrated step-up procurement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of IEC standards documentation, ECHA chemical authorization databases, and utility procurement tender records. Primary interviews engaged vacuum impregnation process engineers, utility substation planning officers, EPC contractor procurement leads, and resin formulation technical directors. Secondary validation drew from CEA technical standards filings, EU F-Gas Regulation implementation reports, and copper commodity exchange data. Bottom-up unit demand modeling triangulated against top-down infrastructure investment forecasts.
Segmentation dimensions modeled include product architecture, insulation material chemistry, end-user procurement channel, and application voltage class across the analysis window. CAGRs derive from installed base rotation rates and new-build infrastructure pipelines. Forecast inputs incorporate urban substation densification timelines, renewable integration capacity additions, and regulatory chemistry restriction phase-down schedules.
Decision-makers should treat outputs as directional under stable copper pricing and REACH authorization continuity assumptions; material deviation would warrant model refresh. Revision becomes warranted when epoxy resin supply concentration crosses critical disruption thresholds or when IEC 60076-11 certification timelines extend beyond baseline qualification cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
South Korea Battery Management Systems Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Buck-Boost Controller Market
Power Systems
Global Excitation Systems Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Global Automatic Voltage Stabilizer Market
Power Systems
Europe Micro Inverter Market
Power Systems
Solid State Power Controller Market
Power Systems
Digital Inverter Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
USB Power Adapters Market
Power Systems
Asia Pacific Transformer Monitoring System Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Harmonic Generators Market