
 High Voltage Ceramic Zinc Oxide Surge Arrester Market | 2026-2036
High Voltage Ceramic Zinc Oxide Surge Arrester Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Ceramic Zinc Oxide Surge Arrester Market Insights
China's manufacturing base for ceramic metal-oxide varistors is narrowing the cost gap with European producers. ABB leverages vertically integrated ceramic pressing and sintering operations to sustain margin structures across station-class product lines. Siemens Energy anchors its competitive position through IEC-certified testing laboratories in Germany and Switzerland. Hitachi Energy specializes in polymer-housed designs for coastal substations, differentiating on salt-fog contamination resistance.
A high voltage ceramic zinc oxide surge arrester is a protective device comprising sintered zinc oxide discs stacked within a porcelain or polymer housing, exhibiting highly non-linear voltage-current characteristics that clamp transient overvoltages to safe levels. The primary purpose is to protect transformers, circuit breakers, and buswork in electrical substations from lightning strikes and switching surges. Station-class arresters command the deepest margin pools due to factory acceptance testing rigor and utility qualification timelines. Transmission-class products represent the fastest-growing application segment as grid operators harden ultra-high voltage corridors. Gapless zinc oxide technology has displaced silicon carbide designs across all voltage tiers above 72.5 kV.
Grid operators in the United States face NERC CIP reliability standards that mandate surge protection redundancy for critical substations. EMA and CE marking requirements under the EU's Low Voltage Directive shape product access for European suppliers. China's GB 11032 standard and MEE environmental compliance protocols govern domestic procurement and export eligibility. Stakeholders must monitor how IEC revision cycles and emerging national content requirements redistribute competitive advantage across manufacturing geographies.
Market Dynamics
IEC 60099-4 revision cycles are compressing product certification timelines while China's GB 11032 standard tightens environmental compliance thresholds, forcing manufacturers to requalify existing product lines across multiple jurisdictions simultaneously.
Growth Catalysts
- Ultra-high voltage transmission build-outs:China's western-to-eastern power corridor expansion is accelerating procurement of transmission-class arresters rated above 550 kV.
- NERC CIP reliability mandates:US grid operators must install redundant surge protection at critical substations, creating mandatory replacement cycles.
- Lightning hardening programs:Southeast Asian electric utilities are prioritizing station-class arrester deployment to reduce outage frequency from tropical storm activity.
Market Restraints
- Zinc oxide disc supply concentration:Sintered varistor manufacturing clusters heavily in China's Hunan and Jiangxi provinces, creating geographic single-point vulnerability.
- Extended factory acceptance testing:IEC-certified laboratory capacity constraints in Europe and Japan stretch utility qualification timelines to 18-24 months.
- Silicon carbide legacy substitution:Remaining installed base above 72.5 kV delays full gapless zinc oxide conversion in select emerging markets.
Strategic Opportunities
- Polymer-housed coastal designs:Salt-fog contamination resistance specifications for substations within 50 kilometers of shorelines open premium product tiers.
- EU Green Deal alignment:Arrester recyclability and reduced porcelain mass qualify for sustainability-linked procurement preferences under CSRD disclosure requirements.
- Digital monitoring integration:Embedded leakage current sensors and IoT connectivity enable condition-based maintenance contracts with transmission operators.
Industry Challenges
- Ceramic sintering specialist scarcity:Mastery of temperature-controlled zinc oxide disc firing requires 10-15 year apprenticeship pipelines that regional training programs have failed to replenish.
- Multi-jurisdiction certification stacking:Simultaneous pursuit of IEC, GB, and NEMA approvals fragments engineering resources and extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Ceramic Zinc Oxide Surge Arrester Market |
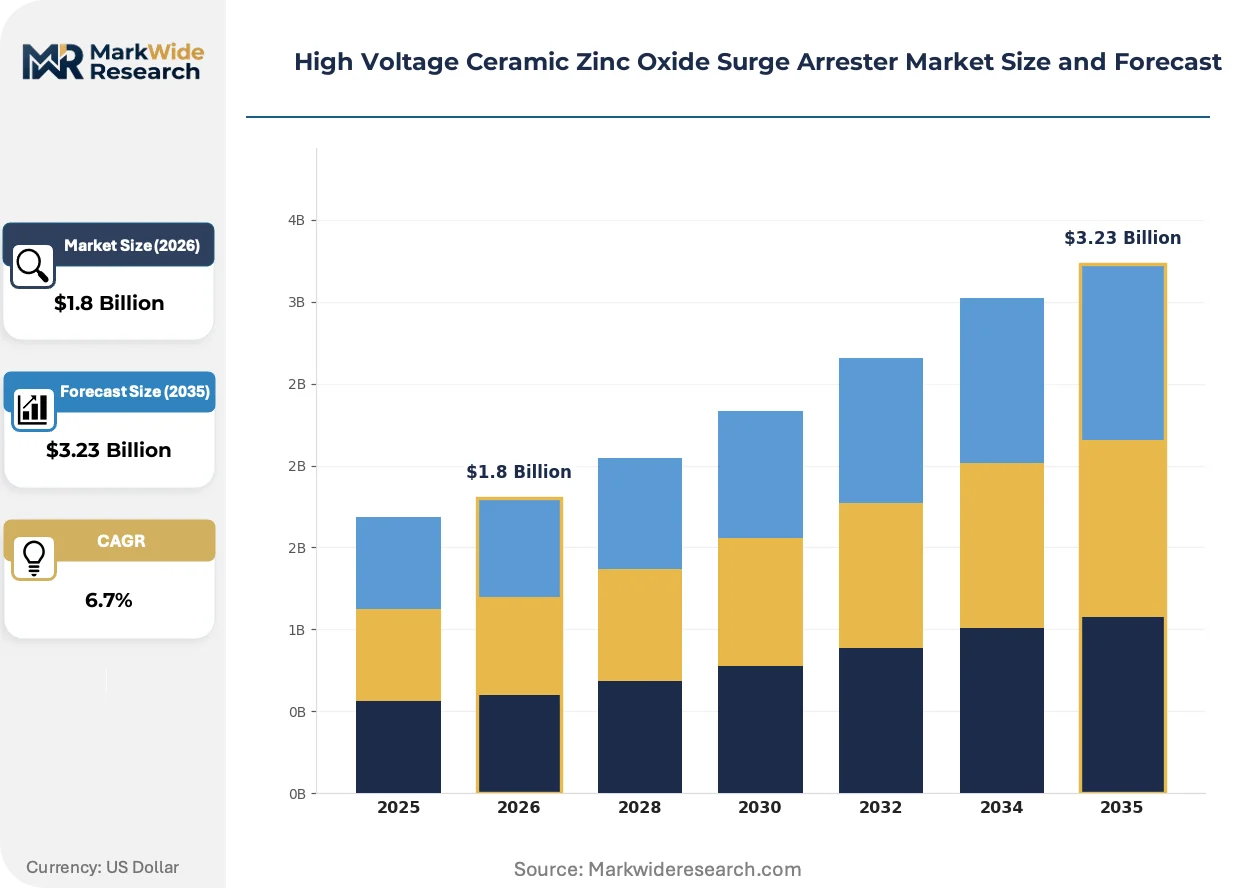
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Station Class, Distribution Class, Transmission Class, Polymer Housing Technology: Zinc Oxide, Silicon Carbide, Gapless Design, Multi-Layer Varistor Application: Power Generation, Substation Protection, High Voltage Transmission, Renewable Integration End User: Electric Utilities, Grid Operators, Industrial Plants, Independent Power Producers |
| Companies Covered | ABB, Siemens Energy, Hitachi Energy, GE Vernova, Eaton, Schneider Electric, Mitsubishi Electric, Toshiba Energy Systems & Solutions, Meidensha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Ceramic Zinc Oxide Surge Arrester Market Trends and Innovations
Gapless metal-oxide technology is collapsing residual voltage protection thresholds while digital condition monitoring and tightened environmental compliance protocols reshape how arresters are specified, tested, and procured across voltage classes.
Polymer housing materials are collapsing the historical performance gap with porcelain enclosures in contaminated environments. Coastal substation operators in Vietnam and the Philippines now specify silicone rubber housings for 220 kV installations previously reserved for ceramic. The shift is compressing maintenance intervals from 6-year porcelain washing cycles to 12-year polymer replacement schedules.
EU F-Gas Regulation amendments are accelerating scrutiny of SF6-insulated switchgear companion protection, indirectly elevating arrester specification rigor for gas-insulated substations. German TSOs now require third-party witnessed partial discharge testing for all station-class products above 420 kV. The mandate is filtering into Polish and Romanian procurement standards through EU harmonization pressure.
Utility engineering departments are consolidating arrester specifications into framework agreements with pre-qualified manufacturers, displacing project-by-project tendering. State Grid Corporation of China's centralized procurement platform now aggregates 80 percent of domestic transmission-class demand. The concentration is forcing smaller European and Japanese suppliers to establish local joint ventures or forfeit volume access.
High Voltage Ceramic Zinc Oxide Surge Arrester Market Segmentation
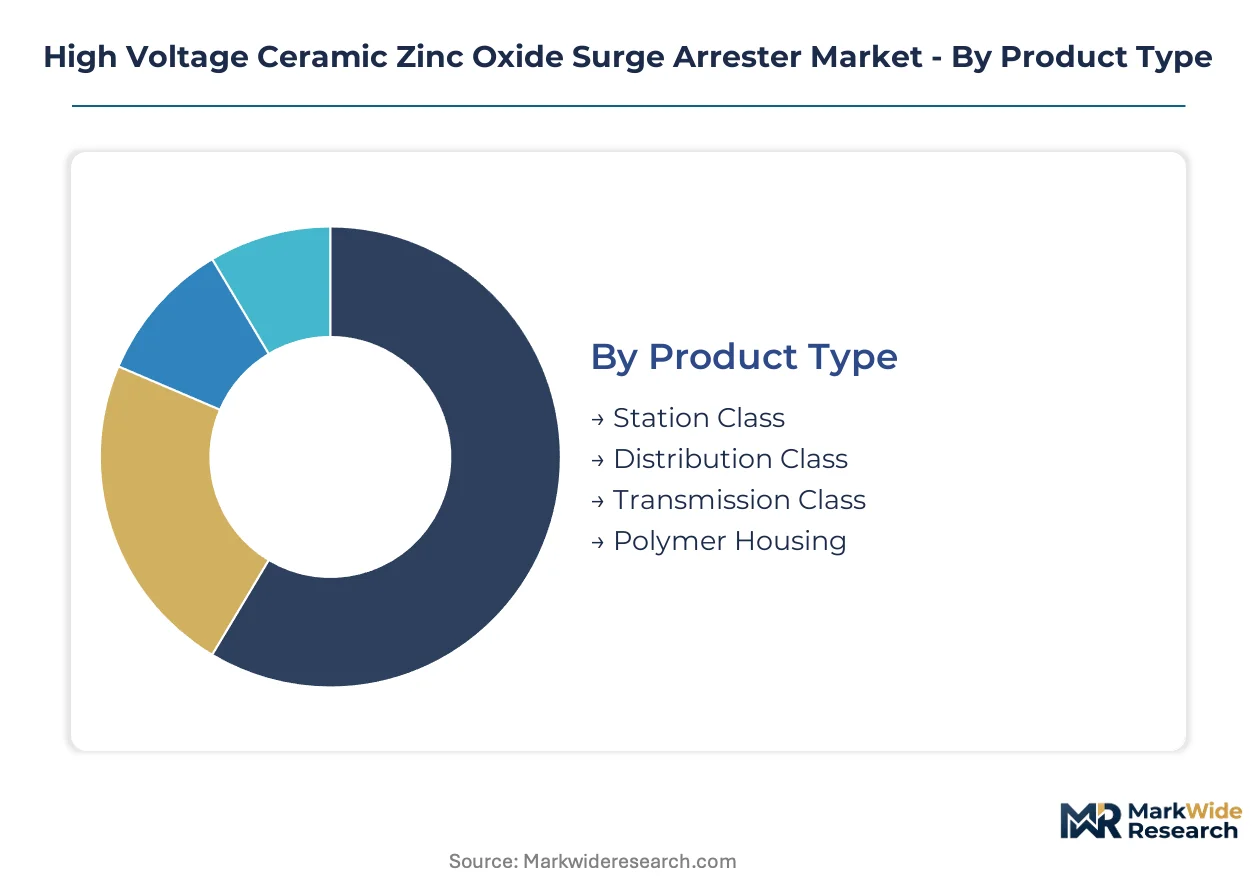
Segmentation in the high voltage ceramic zinc oxide surge arrester market determines procurement pathways, certification requirements, and service contract structures. Utility buyers segment demand by voltage class and housing material, while OEM specifications hinge on varistor technology and gap configuration.
Product Type:
After-sales service intensity varies sharply across housing materials and voltage classes, with porcelain-enclosed station-class products demanding the most intensive field inspection protocols.
- Station Class:These arresters protect equipment in substations above 72.5 kV with porcelain or polymer housings enclosing multiple zinc oxide disc columns. Electric utilities in Germany and Japan specify station-class units for 420 kV and 550 kV transformer protection, driven by IEC 60099-4 factory acceptance testing mandates that stretch qualification timelines to 18-24 months.
- Transmission Class:Rated above 550 kV, these arresters clamp lightning-induced overvoltages on ultra-high voltage corridors spanning hundreds of kilometers. China's State Grid Corporation concentrates procurement through centralized platforms for western-to-eastern power corridor build-outs, with gapless designs displacing all silicon carbide legacy units in new installations.
- Distribution Class:Lower voltage ratings suit 15-72.5 kV feeder protection with simplified maintenance schedules.
- Polymer Housing:Silicone rubber enclosures resist salt-fog contamination in coastal Vietnamese and Philippine substations, collapsing washing cycles from 6 years to replacement at 12 years.
By volume, Distribution Class leads. By growth pace, Transmission Class is ahead.
Technology:
Cost tier stratification separates mature varistor formulations from advanced multi-layer architectures that command premium pricing in ultra-high voltage applications.
- Zinc Oxide:Sintered varistor discs exhibit highly non-linear voltage-current characteristics that clamp transients within nanoseconds. Gapless zinc oxide technology has displaced silicon carbide designs across all voltage tiers above 72.5 kV, with manufacturing clusters concentrated in China's Hunan and Jiangxi provinces creating supply vulnerability.
- Gapless Design:Eliminating series gaps reduces residual voltage protection thresholds and maintenance requirements. German TSOs now mandate third-party witnessed partial discharge testing for all gapless station-class products above 420 kV, filtering into Polish and Romanian procurement through EU harmonization pressure.
- Silicon Carbide:Legacy technology persists in select emerging market retrofit applications where full zinc oxide conversion faces capital constraints.
- Multi-Layer Varistor:Stacked disc configurations optimize energy absorption for severe lightning exposure zones.
By installed base, Zinc Oxide dominates. By specification momentum, Gapless Design is expanding most quickly.
Application:
Customer type concentration shapes volume allocation, with grid operators consolidating procurement through framework agreements that displace project-by-project tendering.
- Substation Protection:Arresters shield transformers, circuit breakers, and buswork from lightning strikes and switching surges. NERC CIP reliability standards mandate redundant surge protection at critical US substations, creating mandatory replacement cycles that independent system operators must execute.
- High Voltage Transmission:Corridor hardening programs accelerate deployment along exposed routes. Southeast Asian utilities prioritize transmission-class arrester procurement to reduce outage frequency from tropical storm activity, with salt-fog specifications tightening for installations within 50 kilometers of shorelines.
- Power Generation:Generator step-up transformer protection requires coordinated insulation coordination studies.
- Renewable Integration:Wind and solar connection points need switching surge protection for inverter-fed generation.
By current procurement value, Substation Protection leads. By expansion trajectory, High Voltage Transmission shows the steepest climb.
End User:
Margin tier differentiation separates utility framework agreements with pre-qualified manufacturers from industrial spot purchasing with shorter qualification horizons.
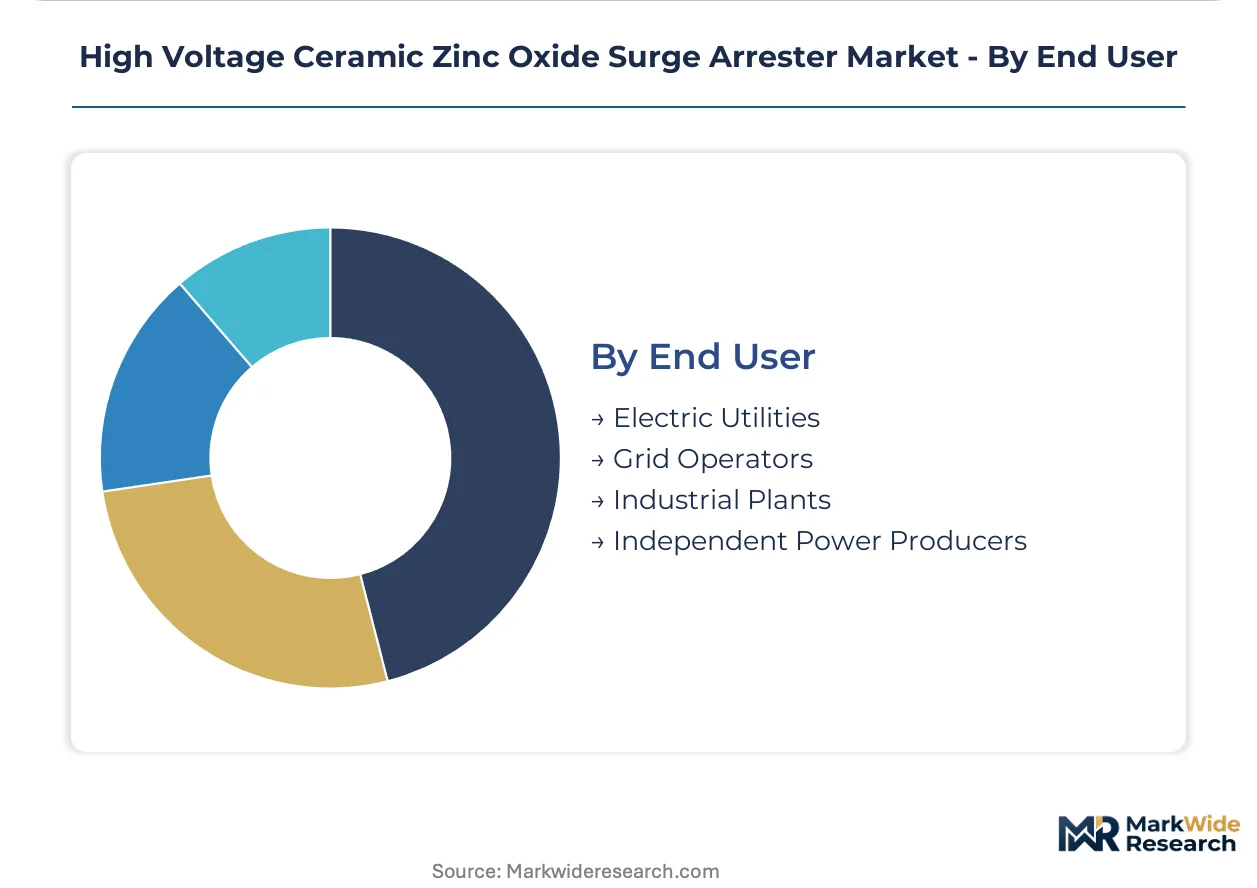
- Electric Utilities:Vertically integrated operators specify arresters through centralized procurement platforms. State Grid Corporation of China's platform aggregates 80 percent of domestic transmission-class demand, forcing smaller European and Japanese suppliers to establish local joint ventures or forfeit volume access.
- Grid Operators:Independent system operators and transmission system operators manage reliability standards compliance. US regional transmission organizations face NERC CIP enforcement actions that elevate arrester redundancy from preference to mandate at critical nodes.
- Industrial Plants:Captive substations for steel, chemical, and mining operations specify arresters through EPC contractors.
- Independent Power Producers:Merchant generators prioritize lead time over qualification depth for non-critical installations.
By contract value concentration, Electric Utilities lead. By procurement flexibility expansion, Grid Operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Chinese utilities prioritize transmission-class procurement for ultra-high voltage corridors, while European and US operators emphasize station-class redundancy mandates and extended factory acceptance testing protocols.
China
State Grid Corporation's centralized procurement platform aggregates four-fifths of domestic transmission-class demand, funneling orders toward western-to-eastern power corridor build-outs. GB 11032 standard revisions and MEE environmental compliance protocols tighten product requalification thresholds. Manufacturing clusters in Hunan and Jiangxi provinces dominate sintered varistor production, creating geographic supply concentration.
Germany
German transmission system operators drive station-class specification rigor through third-party witnessed partial discharge testing mandates above 420 kV. EU F-Gas Regulation amendments elevate arrester companion protection requirements for gas-insulated substations. IEC-certified testing laboratories in Bavaria and North Rhine-Westphalia anchor European qualification capacity.
United States
Regional transmission organizations face NERC CIP enforcement actions that transform surge protection redundancy from preference to mandate at critical substation nodes. Independent system operators execute mandatory replacement cycles across the Eastern and Western interconnections. Texas and California grid operators concentrate procurement for lightning hardening programs.
Japan
Japanese electric utilities maintain stringent factory acceptance testing timelines stretching 18-24 months for station-class products. METI energy security frameworks prioritize domestic supply chain resilience for critical grid infrastructure. Industrial clusters in the Chubu region around Nagoya specialize in precision ceramic sintering operations.
Vietnam
Vietnam Electricity prioritizes polymer-housed arresters for coastal substations within 50 kilometers of shorelines, collapsing maintenance intervals from six-year washing cycles to twelve-year replacement schedules. Tropical storm exposure drives transmission-class deployment along the north-south power corridor. Da Nang and Ho Chi Minh City substation upgrade programs concentrate demand.
High Voltage Ceramic Zinc Oxide Surge Arrester Market Competitive Landscape
Capability concentration sits with European and Japanese specialists mastering IEC-certified testing and extended qualification protocols; scale advantage sits with Chinese manufacturers leveraging vertically integrated ceramic pressing and sintering operations. The market structures around three archetypes: vertically integrated industrial conglomerates with captive varistor production, specialized arrester manufacturers with polymer housing expertise, and regional fabricators serving domestic procurement platforms. Dominant competitive moves include backward integration into zinc oxide disc manufacturing and strategic joint ventures to access China's centralized procurement systems.
Among European-based industrial conglomerates, ABB and Siemens Energy exemplify the capability-intensive tier, anchoring competitive positioning through in-house testing infrastructure and multi-jurisdiction certification depth. Hitachi Energy occupies a specialist position within the polymer-housing segment, representing the coastal contamination resistance vector that commands premium pricing in Southeast Asian markets.
| Leading Market Players |
|---|
| ABB |
| Siemens Energy |
| Hitachi Energy |
| GE Vernova |
| Eaton |
| Schneider Electric |
| Mitsubishi Electric |
| Toshiba Energy Systems & Solutions |
| Meidensha |
| Others |
Pricing and Supply Chain Analysis
Sintered zinc oxide disc production clusters in China's Hunan and Jiangxi provinces concentrate upstream supply control, directing margin capture toward manufacturers with captive varistor operations and compressing pricing power for assembly-only competitors.
Pricing Analysis
Long-term framework agreements dominate procurement for transmission-class arresters, with State Grid Corporation's centralized platform aggregating volume commitments that lock in pricing for 24-36 month cycles. Three-tier pricing structure across IEC-certified premium, GB-compliant standard, and regional-economy levels separates manufacturers by testing laboratory access and qualification depth. Cost compression in station-class tiers is intensifying because European TSOs are consolidating supplier panels. Industrial spot buyers at captive substations exhibit highest price sensitivity; utility framework participants accept premium positioning for certification pedigree.
Supply Chain Analysis
High-purity zinc oxide feedstock draws from specialized chemical processors in China, Germany, and Japan, with ceramic pressing equipment sourcing concentrated among Italian and Japanese machinery specialists. Sintered varistor discs, silicone rubber housing compounds, and precision metal end-fittings constitute critical component dependencies. Single-source vulnerability runs through China's dominance of varistor firing kilns above 400 kV rating class. Distribution runs through EPC contractor channels for industrial end-users and direct utility procurement platforms for grid operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with polymer-housed coastal designs and digital monitoring integration, as demand-side procurement consolidation creates niche openings for specialists outside volume-platform access.
For Market Incumbents: Harden qualification depth through third-party witnessed partial discharge testing investment above 420 kV, matching German TSO mandates now filtering eastward. Deepen backward integration into zinc oxide disc manufacturing to defend margin structures against Chinese vertically integrated competitors. IEC 60099-4 revision cycles compressing certification timelines represent the critical regulatory threat requiring pre-positioned laboratory capacity. For New Entrants and Emerging Players: Coastal substation upgrades in Vietnam and the Philippines represent the most penetrable entry point, where salt-fog specifications favor polymer expertise over porcelain legacy. Digital condition monitoring modules for existing arrester fleets offer attachment revenue without full qualification burden. Partner with regional EPC contractors for channel access rather than pursuing direct utility framework inclusion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across transmission-class manufacturing as ultra-high voltage corridor build-outs demand dedicated firing kiln investments. Acquisition targets should profile mid-scale polymer housing specialists with IEC testing relationships and Southeast Asian installation track records. Watch for inflection in Chinese GB 11032 environmental compliance enforcement as signal for requalification spending waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Varistor Production | Captive zinc oxide disc supply insulates margin structures from Hunan-Jiangxi concentration risk. |
| Polymer Housing Technology Licensing | Silicone rubber expertise unlocks premium coastal substation tiers in Vietnam and Philippines. |
| Digital Monitoring Module Development | Embedded leakage current sensors enable condition-based maintenance contracts with transmission operators. |
| Joint Venture for China Market Access | Local partnerships bypass State Grid centralized procurement exclusion for non-domestic suppliers. |
| IEC-Certified Testing Laboratory Expansion | In-house partial discharge capacity accelerates qualification timelines compressed by revision cycles. |
Research Methodology
Operator-level perspectives from utility procurement officers, EPC contractor project managers, ceramic sintering specialists, and transmission planning engineers anchored the qualitative base. Secondary validation drew from IEC standard revision documentation, GB 11032 compliance filings, NERC CIP enforcement records, and customs trade data for zinc oxide varistor imports. Bottom-up installation unit estimates triangulated against top-down grid infrastructure spending forecasts.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning voltage class, housing material, gap configuration, and end-user procurement channel. CAGRs derived from utility capital expenditure trajectories, lightning hardening program announcements, and substation upgrade cycle timing. Forecast inputs incorporated transmission corridor build-out schedules and environmental compliance protocol enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in grid infrastructure investment cycles, commodity zinc pricing, or trade policy for electrical equipment would shift the trajectory. Forecasts reflect documented assumptions regarding standard revision implementation timing and certification capacity expansion. Cross-checking against utility disclosed procurement volumes and EPC contractor order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Battery Thermal Management System Market
Power Systems
Solid State Transformer Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Battery Electronic Control Unit Market
Power Systems
Shunt Capacitor Market
Power Systems
South America DC Distribution Network Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
North America Electric Vehicle Power Inverter Market
Power Systems
HVDC Converters Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Switching Regulators Power Management IC Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
Europe Variable Frequency Drive Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
DC Power Supplies Market