
 North America Micro Inverter Market | 2026-2036
North America Micro Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
North America Micro Inverter Market Insights
Silicon carbide is consolidating its position as the preferred semiconductor substrate in next-generation micro inverters, displacing traditional silicon IGBTs in high-efficiency designs above 97% peak conversion. Enphase Energy leverages its integrated battery-storage ecosystem to anchor premium residential deployments across the continent. APsystems competes aggressively on cost-per-watt metrics in the commercial rooftop segment. SolarEdge Technologies differentiates through power optimizer compatibility, though it navigates intensifying pressure from dedicated micro inverter architectures.
A micro inverter converts direct current from individual photovoltaic modules into grid-compliant alternating current at the panel level, enabling per-module maximum power point tracking and eliminating single-point failure risks inherent to string architectures. The device typically achieves 250-500W nominal output with 97-99% peak efficiency, using gallium nitride or silicon carbide switching elements to minimize conversion losses and thermal footprint. Single-phase units dominate residential deployments, while three-phase configurations capture commercial and light-industrial rooftops where higher capacity and grid stability requirements apply. Smart micro inverters with embedded monitoring and rapid shutdown capabilities represent the fastest-expanding product tier, as NEC compliance mandates reshape hardware specifications across jurisdictions. Battery-ready hybrid variants remain nascent but occupy the highest margin pool as solar-plus-storage penetration deepens.
US NEC Article 690.12 rapid shutdown requirements and IEEE 1547-2018 interconnection standards collectively dictate product certification pathways and installation protocols across American jurisdictions. Health Canada's CSA C22.2 No. 107.1-16 and provincial utility interconnection rules govern market access in Canadian provinces, creating a dual-compliance burden for manufacturers serving the full regional footprint. Mexico's CRE grid codes and NOM energy efficiency standards add a third regulatory layer as distributed generation expands south of the border. Stakeholders must monitor evolving net metering reforms and inverter efficiency minimums as these policy levers increasingly determine product-market fit and geographic prioritization.
Market Dynamics
Silicon carbide substrate migration is compressing thermal management costs while NEC rapid shutdown mandates force hardware redesign cycles across every installation jurisdiction. Module-level power electronics now face simultaneous pressure from efficiency ceilings and compliance complexity.
Growth Catalysts
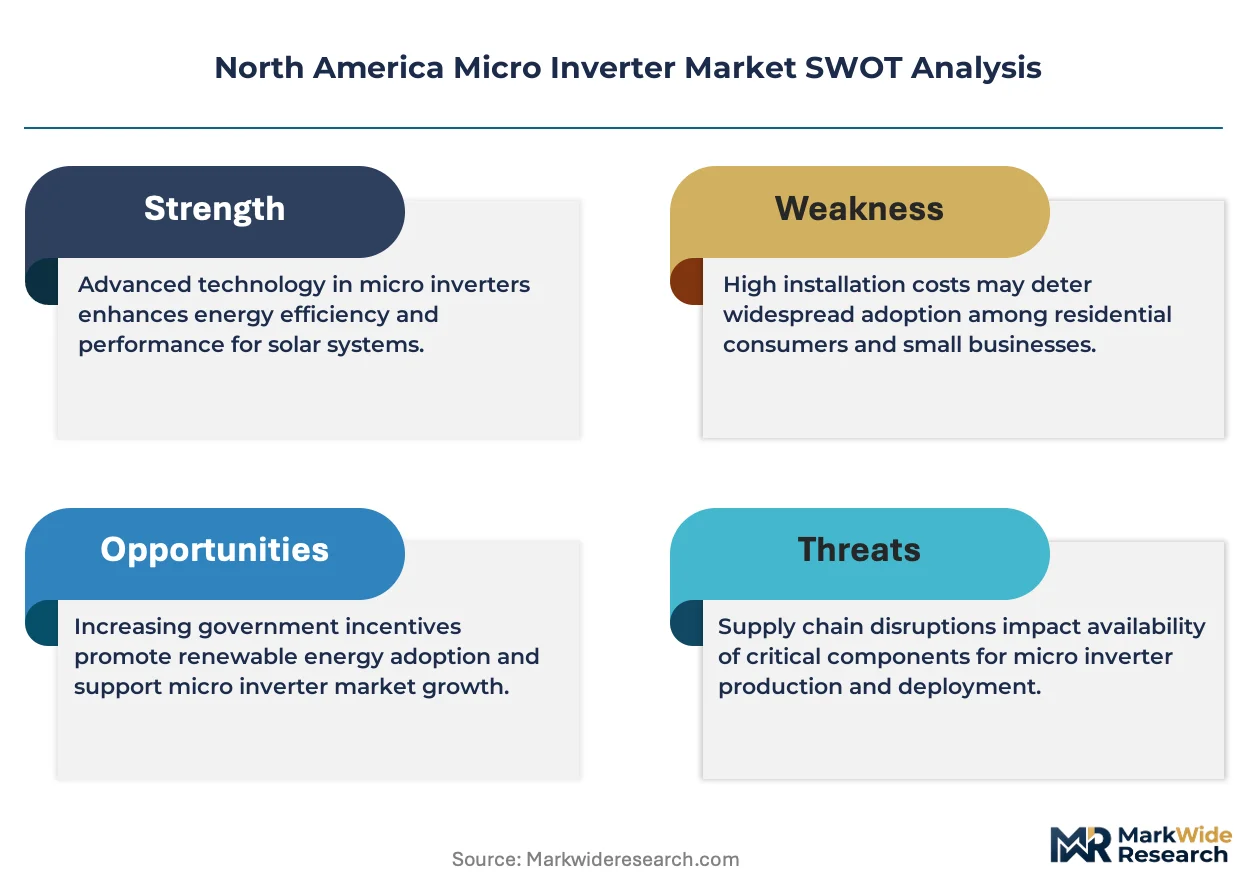
- IRA Investment Tax Credit:The 30% residential credit extension through 2032 directly improves payback periods for rooftop solar-plus-storage bundles in high-rate utility territories.
- Module-level rapid shutdown:NEC Article 690.12 mandates are eliminating string inverter compatibility in new California and Florida residential permits, forcing hardware upgrades.
- Silicon carbide switching:Wide-bandgap semiconductors are cutting conversion losses below 2% at partial load, enabling smaller heat sinks and higher wattage density per unit.
Market Restraints
- Wafer supply concentration:Silicon carbide substrate fabrication concentrates among three global suppliers, creating input bottlenecks for North American micro inverter assembly.
- String inverter substitution:Power optimizer architectures from SolarEdge Technologies capture cost-sensitive commercial rooftops with lower per-watt hardware expenditure.
- Net metering compression:California NEM 3.0 export rate cuts are elongating residential payback calculations and dampening immediate replacement demand.
Strategic Opportunities
- Mexico distributed generation:CRE grid code liberalization is opening C&I rooftop segments where three-phase micro inverters address voltage stability requirements.
- Battery-ready hybrid architectures:DC-coupled storage integration creates margin expansion as solar-plus-storage penetration accelerates in Texas ERCOT territories.
- Direct-to-installer digital channels:Bypassing traditional distribution through Enphase and APsystems contractor portals is compressing customer acquisition costs in saturated California markets.
Industry Challenges
- Power electronics engineering scarcity:Gallium nitride and silicon carbide design expertise concentrates among semiconductor veterans, constraining product development velocity for mid-tier entrants.
- Dual certification burden:Simultaneous UL 1741 SA and IEEE 1547-2018 compliance testing extends product launch timelines by 8-14 months for multi-jurisdiction deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Micro Inverter Market |
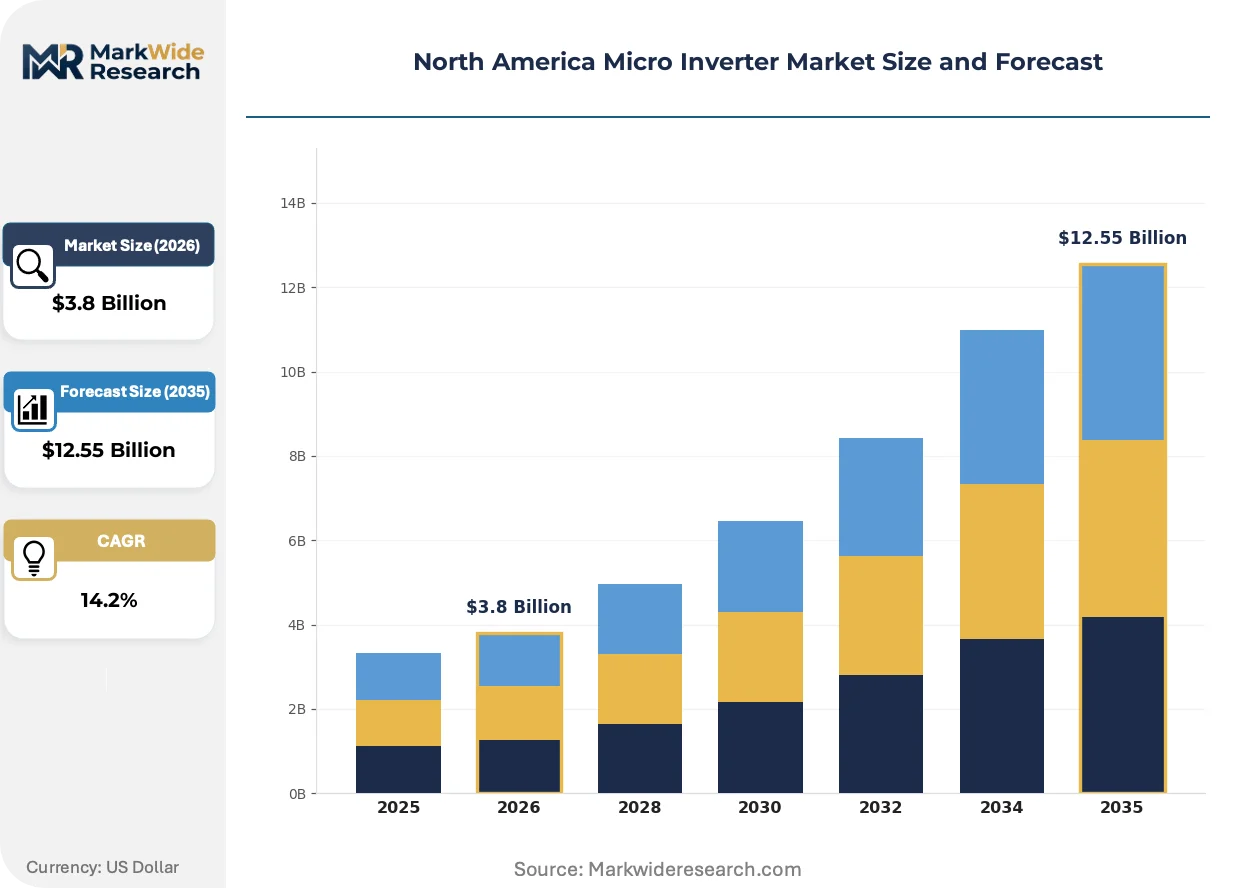
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Smart Micro Inverters, Hybrid Inverters Technology: Grid-Tied, Off-Grid, Battery Storage, Centralized End User: Residential, Commercial, Industrial, Utility Distribution Channel: Online Retail, Direct Sales, Distributors, Installers |
| Companies Covered | Enphase Energy, APsystems, Hoymiles, Sungrow, Altenergy Power Systems, Chilicon Power, SolarEdge Technologies, Tigo Energy, SMA Solar Technology, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Micro Inverter Market Trends and Innovations
Power conversion architecture is fragmenting across semiconductor substrates while regulatory mandates accelerate hardware obsolescence cycles. Installer procurement patterns and utility interconnection protocols are simultaneously rewiring competitive positioning.
Gallium nitride high-electron-mobility transistors are displacing silicon MOSFETs in sub-500W residential units, cutting switching losses by 40% at 100 kHz frequencies. Texas and Arizona installers are specifying GaN-based units for attic-mount deployments where thermal derating historically constrained output. This substrate migration is decentralizing inverter manufacturing away from legacy silicon foundry dependencies toward compound semiconductor specialists.
The US Inflation Reduction Act's domestic content bonus credit is reshaping supply chain geography, requiring 40% North American manufacturing value for full incentive stacking. Assembly operations are migrating from Southeast Asia to Mexico and Texas border zones to capture tariff advantages. Residential contractors in California and Florida now prioritize SKUs qualifying for the 10% domestic content adder.
Installer procurement is consolidating through master distribution agreements with Sunrun and Freedom Forever, compressing regional distributor margins. Direct fulfillment from manufacturer portals is displacing traditional two-step electrical distribution for projects above 50 kW. This channel compression is most visible in Texas, where integrated residential developers now specify hardware at corporate level rather than branch-level purchasing.
North America Micro Inverter Market Segmentation
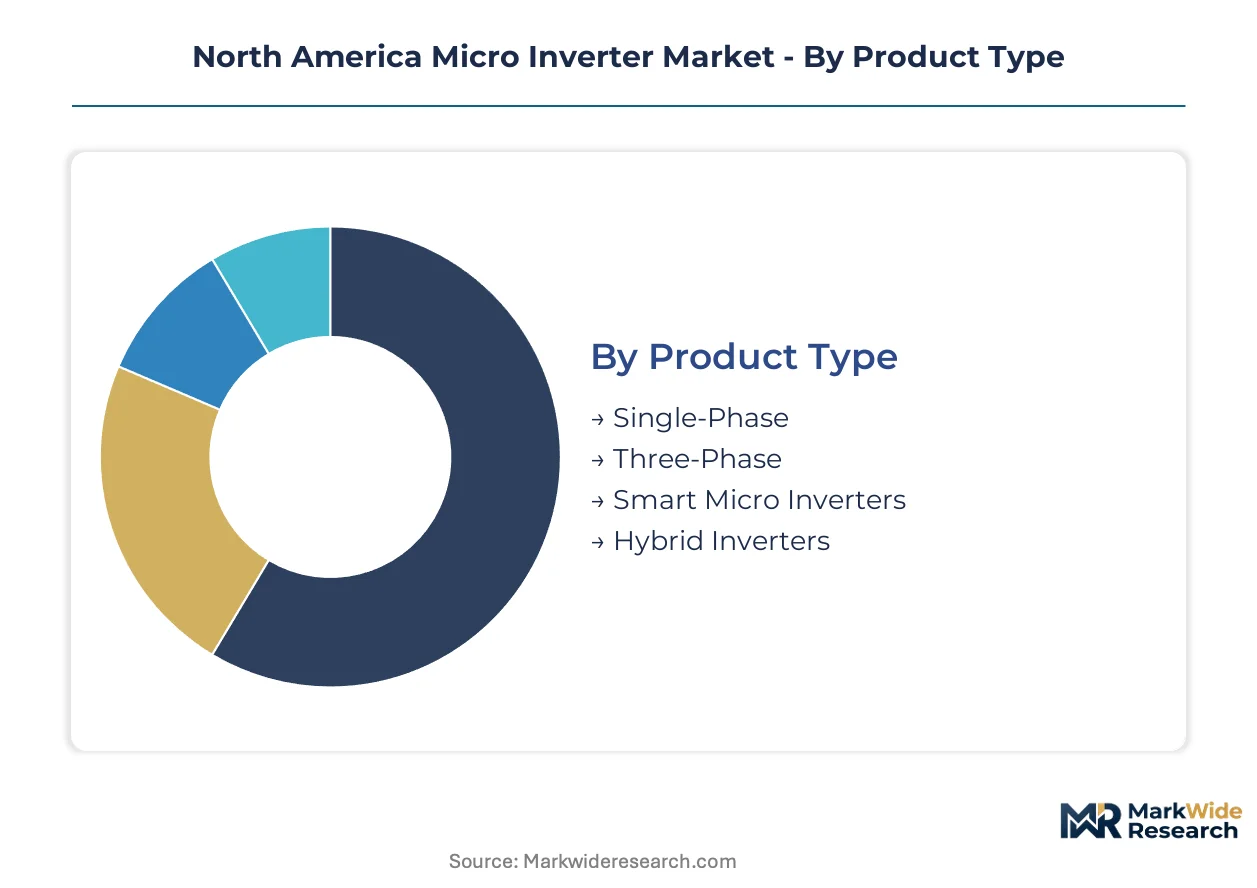
Micro inverter procurement patterns diverge sharply across installation scales and interconnection requirements. Product specifications, semiconductor substrates, and channel economics must align precisely with each segment's technical constraints and regulatory exposure.
Product Type:
Standardization dominates single-phase residential units while three-phase and hybrid variants demand extensive customization for voltage stability and storage integration.
- Single-Phase:Nominal 250-400W output with 97-99% peak efficiency using silicon carbide switching elements. Demand concentrates in California and Florida residential rooftops where NEC rapid shutdown mandates force module-level architectures.
- Three-Phase:480W-2kW capacity with balanced phase management for commercial rooftops. Texas and Arizona C&I installations specify these units for voltage sag correction and grid stability compliance.
- Smart Micro Inverters:Embedded monitoring and rapid shutdown capabilities per NEC Article 690.12. California installers now specify these as baseline for new permits.
- Hybrid Inverters:DC-coupled battery-ready architectures with bidirectional conversion. Texas ERCOT territories show steepest adoption for solar-plus-storage resilience.
Most installed capacity flows through Single-Phase units. Expansion is steepest in Hybrid Inverters.
Technology:
Interconnection topology determines certification burden and margin structure across this dimension.
- Grid-Tied:IEEE 1547-2018 compliant synchronization with anti-islanding protection. Dominates California and Florida deployments where net metering economics remain favorable.
- Off-Grid:Standalone frequency regulation without utility interconnection. Remote Texas ranch properties and Arizona desert installations drive niche demand.
- Battery Storage:DC-coupled integration with lithium-ion or LFP chemistries. Texas and California residential contractors specify these for time-of-use arbitrage.
- Centralized:Clustered AC aggregation for simplified utility interconnection. Emerging in Mexican C&I segments under CRE grid code liberalization.
Grid-Tied architectures carry the heaviest certification load. Battery Storage configurations are climbing the fastest.
End User:
Scale economics and procurement authority fragment sharply across customer categories.
- Residential:Single-family and multi-family rooftop installations under 20kW. California, Texas, and Florida account for concentrated permit volumes.
- Commercial:Light-industrial rooftops and retail facilities from 20kW to 500kW. Texas and Arizona distribution centers specify three-phase units for demand charge management.
- Industrial:Manufacturing facilities with 500kW+ aggregated capacity. Limited penetration due to central inverter cost advantages at this scale.
- Utility:Ground-mount community solar and distributed generation portfolios. Emerging in Mexico under CRE distributed generation reforms.
Residential channels move the highest unit volumes. Commercial applications are gaining share fastest.
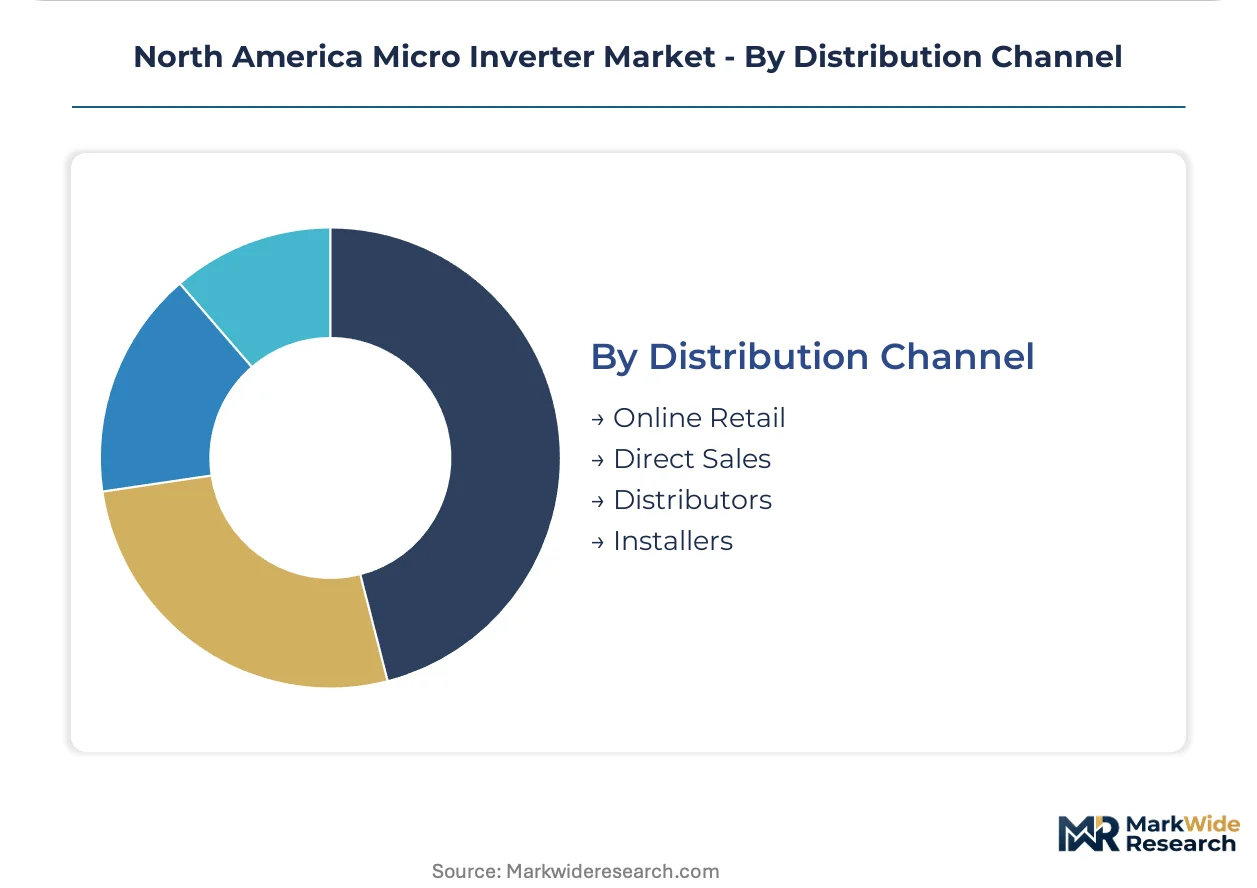
Distribution Channel:
Channel power is consolidating toward direct manufacturer relationships and bypassing traditional electrical distribution.
- Online Retail:E-commerce platforms serving DIY installers and small contractors. Limited penetration due to electrical licensing requirements.
- Direct Sales:Manufacturer portals and master service agreements with national installers. Sunrun and Freedom Forever procurement now flows primarily through this channel.
- Distributors:Traditional two-step electrical supply houses. Margins compressing as direct channels capture California and Texas volume.
- Installers:Local and regional contractor networks with specification authority. Texas integrated developers now centralize hardware selection at corporate level.
Installer relationships determine most specification outcomes. Direct Sales channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's solar manufacturing corridor anchors North American micro inverter demand, with module-level power electronics clustering around Los Angeles and San Jose industrial zones. The region's regulatory density and utility rate structures create concentrated pull for rapid-shutdown-compliant hardware.
United States
The IRA's domestic content bonus credit is reshaping procurement patterns across Texas and Florida residential markets. NEC Article 690.12 rapid shutdown mandates eliminate string inverter compatibility in new California and Florida permits. Installer procurement concentrates through Sunrun and Freedom Forever master agreements in the California Central Valley.
Canada
High electricity rates in Ontario and British Columbia sustain residential solar economics despite winter irradiance constraints. Health Canada's CSA C22.2 No. 107.1-16 certification requirements create dual-compliance burdens alongside US UL standards. Toronto and Vancouver metropolitan areas show concentrated permit activity for single-phase residential units.
Mexico
CRE grid code liberalization is opening commercial and industrial rooftop segments for three-phase micro inverter deployment. NOM energy efficiency standards and distributed generation reforms are reshaping hardware specifications for voltage stability compliance. Mexico City and Nuevo León industrial corridors show emerging demand from manufacturing facilities seeking demand charge management.
Texas
ERCOT grid volatility is accelerating solar-plus-storage bundling across Dallas-Fort Worth and Houston metro areas. Time-of-use arbitrage economics favor battery-ready hybrid micro inverter architectures. Installer procurement is consolidating through integrated residential developers centralizing hardware selection at corporate level rather than branch purchasing.
Florida
Hurricane resilience requirements and favorable net metering policies sustain residential deployment momentum across Tampa and Miami-Dade counties. Building code enforcement of rapid shutdown capabilities is eliminating legacy string inverter retrofits in new construction. High humidity and salt exposure specifications favor sealed enclosure designs with enhanced thermal management.
North America Micro Inverter Market Competitive Landscape
Global majors compete with regional champions across semiconductor substrate and channel access dimensions. The vendor base organizes around three tiers: integrated storage ecosystem providers, cost-optimized commercial specialists, and power optimizer hybrid architects. Strategic moves concentrate on domestic content qualification for IRA incentive stacking and direct-to-installer channel compression.
Within the integrated ecosystem tier, Enphase Energy occupies a position exemplifying premium residential bundling with battery storage compatibility. APsystems represents the cost-optimized commercial vector competing on per-watt metrics. SolarEdge Technologies anchors the power optimizer hybrid approach navigating pressure from dedicated micro inverter architectures.
| Leading Market Players |
|---|
| Enphase Energy |
| APsystems |
| Hoymiles |
| Sungrow |
| Altenergy Power Systems |
| Chilicon Power |
| SolarEdge Technologies |
| Tigo Energy |
| SMA Solar Technology |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide substrate costs cascade through three distinct pricing tiers, with 6-inch wafer premiums from Wolfspeed and Coherent feeding into module-level power electronics that California installers specify for NEC 690.12 compliance. Residential contractors in Texas and Florida absorb these input markups differently based on IRA domestic content bonus qualification status.
Pricing Analysis
Input-cost pass-through from wide-bandgap semiconductor substrates dominates pricing structures, with silicon carbide wafer premiums compressing margins for mid-tier assemblers while Enphase and APsystems defend position through volume scale. Three-tier pricing separates battery-ready hybrid architectures from standard single-phase units and economy-grade commercial SKUs, with certification grade (UL 1741 SA versus baseline UL 1741) and after-sales monitoring bundling as primary differentiation drivers. Pricing pressure stems from gallium nitride substitution in sub-500W residential segments, where Hoymiles and Chilicon Power compete on cost-per-watt metrics. Commercial installers show highest price sensitivity due to power optimizer alternatives from SolarEdge Technologies, while residential integrators prioritize domestic content qualification over absolute unit cost.
Supply Chain Analysis
Freight cost volatility from Southeast Asia to Mexico and Texas border zones is accelerating assembly migration, with Juarez and Matamoros industrial parks capturing tariff-advantaged production for IRA bonus credit eligibility. Silicon carbide substrate fabrication concentrates in the United States, Germany, and Japan, while gallium nitride epitaxy draws from Taiwan and South Korea foundries. Raw material dependencies span copper busbar, aluminum heat sink extrusions, and rare-earth magnetic components for inductor assemblies. Single-source vulnerability concentrates in 6-inch SiC wafer supply from Wolfspeed's Mohawk Valley facility. Distribution runs through direct manufacturer portals and master service agreements with Sunrun and Freedom Forever, displacing traditional two-step electrical distribution in California and Texas volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with California NEM 3.0 export rate compression and NEC rapid shutdown mandates shifting contractor specification authority toward premium-tier hardware with embedded monitoring and battery-ready architectures.
For Market Incumbents: Anticipate power optimizer substitution pressure in commercial rooftops by deepening backward integration into silicon carbide substrate supply through long-term offtake agreements with Wolfspeed or Coherent. Defend channel control in California and Texas through exclusive master service agreements with integrated residential developers, while accelerating certification investment for IEEE 1547-2018 and UL 1741 SA compliance to extend product launch timelines as a competitive moat. For New Entrants and Emerging Players: Begin with Mexico C&I rooftop segments under CRE grid code liberalization, where three-phase micro inverter demand for voltage stability outruns incumbent coverage. Target Nuevo León and Mexico City industrial corridors with manufacturing facilities seeking demand charge management. Pursue a go-to-market angle through direct-to-installer digital channels that bypass traditional distribution, mirroring APsystems contractor portal architecture. For Investors and Strategic Acquirers: Roll-up economics work for compound semiconductor design specialists because gallium nitride and silicon carbide engineering expertise concentrates among semiconductor veterans and constrains product development velocity for mid-tier entrants. Long-term viability favors platform consolidation around integrated storage ecosystems over pure-play hardware. Watch for inflection in Texas ERCOT solar-plus-storage penetration rates as the signal for battery-ready hybrid architecture margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Qualification | IRA 40% North American manufacturing value requirement reshapes assembly geography toward Mexico and Texas border zones. |
| Silicon Carbide Supply Agreement | Long-term wafer offtake from Wolfspeed or Coherent secures substrate access and compresses thermal management costs. |
| Direct-to-Installer Channel Buildout | Manufacturer portals bypassing traditional electrical distribution capture California and Texas residential volume from Sunrun procurement. |
| Battery-Ready Hybrid Certification | DC-coupled storage integration addresses Texas ERCOT resilience demand and occupies highest margin product tier. |
| Mexico C&I Market Entry | CRE grid code liberalization opens commercial rooftop segments for three-phase voltage stability applications. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining interviews with micro inverter product managers, utility interconnection officers at ERCOT and CAISO, residential solar EPC contractors, and semiconductor procurement leads at wide-bandgap substrate suppliers. Secondary validation draws from FERC interconnection filings, EIA solar deployment data, SEC 10-K disclosures from listed solar hardware manufacturers, and CSA C22.2 certification registries. Bottom-up unit shipment estimates triangulate against top-down addressable market calculations across single-phase, three-phase, and hybrid product categories.
Rate-of-change decomposition separates volume growth from average selling price trajectories across the projection horizon, with segmentation modeling across product type, technology topology, end-user scale, and distribution channel. The analytical framework incorporates semiconductor substrate cost curves, IRA incentive phase-out schedules, and evolving net metering export rate structures as industry-specific forecast inputs. CAGRs derive from logistic adoption curve fitting adjusted for regulatory mandate acceleration effects.
Several conditions sit outside the modeled scope, including potential tariff regime changes affecting Mexico assembly operations, breakthroughs in string inverter rapid shutdown compliance that would erode module-level power electronics share, and severe ERCOT grid instability events that could accelerate or disrupt solar-plus-storage economics. Forecasts reflect assumptions about continued silicon carbide substrate supply expansion and stable IRA domestic content bonus thresholds. A model refresh is warranted upon material change in California net metering policy or IEEE 1547 interconnection standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Series Reactor Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
AC Voltage Transducer Market
Power Systems
Pulse Generator Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
Global Data Center Transformer Market
Power Systems
PV Micro Inverters Market
Power Systems
Voltage Regulators Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Thermoelectric Assemblies Market
Power Systems
Asia Pacific Solid State Transformers Market