
 Automotive Power Electronics Market | 2026-2036
Automotive Power Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Power Electronics Market Analysis
Project finance for dedicated SiC wafer fabs is rewriting capital requirements for new entrants in automotive power electronics. Infineon Technologies AG leverages captive silicon carbide substrate capacity to anchor long-term supply agreements with European OEMs. STMicroelectronics sustains vertical integration from epitaxy to module assembly, competing on yield consistency rather than price alone. Texas Instruments Incorporated specializes in integrated gate drivers and protection logic, occupying a niche between discrete and full-module suppliers.
Automotive power electronics encompasses semiconductor devices and circuits that control, convert, and distribute electrical energy in vehicle powertrains, typically operating at switching frequencies from 20 kHz to 100 kHz and junction temperatures exceeding 175°C in SiC implementations. These systems enable torque vectoring, regenerative braking, and thermal stability across electric and hybrid architectures. Power modules lead unit shipments due to their integration of IGBTs or MOSFETs with ceramic substrates and baseplates, though SiC technology captures expanding share as OEMs prioritize efficiency gains over silicon cost advantages. Motor drives represent a mature segment with stable margins, while DC-DC converters face accelerating redesign cycles as 48-volt mild-hybrid systems proliferate alongside full battery-electric platforms.
The EU Green Deal and F-Gas Regulation tighten embodied carbon thresholds for imported power electronics, compelling suppliers to document manufacturing energy intensity across their supply chains. China's MIIT enforces GB standards for electromagnetic compatibility and functional safety that foreign module makers must satisfy for domestic vehicle platform qualification. The EPA and NHTSA in the United States coordinate tailpipe and upstream emissions rules that extend compliance burdens to semiconductor content in electrified powertrains. Stakeholders must monitor how regional carbon-border adjustments and safety-critical software standards reshape qualification timelines and localization requirements for new manufacturing investments.
Market Dynamics
The automotive power electronics sector faces a structural compression between silicon carbide substrate shortages and 800-volt platform proliferation, forcing OEMs to lock in multi-year supply contracts before capacity ramps materialize.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:The regulation compels module suppliers to document manufacturing energy intensity, creating qualification advantages for European producers with renewable-heavy grids.
- 800-volt battery architectures:Premium EV platforms demand SiC inverters capable of higher switching frequencies and thermal tolerance, expanding addressable module value per vehicle.
- China's dual carbon goals:MIIT enforcement of GB standards for electromagnetic compatibility accelerates domestic platform qualification timelines for compliant foreign suppliers.
Market Restraints
- Silicon carbide substrate concentration:Six-inch wafer supply concentrates among three merchant producers, creating allocation bottlenecks during demand surges.
- Platinum-group metal volatility in ceramic substrates:DBC and AMB baseplates rely on silver and copper metallization layers exposed to commodity price swings.
- Functional safety certification friction:ISO 26262 ASIL-D qualification for gate driver ICs extends development cycles by 18-24 months for new entrants.
Strategic Opportunities
- 48-volt mild-hybrid DC-DC redesign cycles:Legacy combustion platforms in Germany and the United States require new converter architectures, opening volume slots for second-tier suppliers.
- Integrated intelligent power modules:Convergence of trench-gate MOSFETs with on-chip temperature and current sensing enables tier-1 suppliers to offer subsystem-level solutions.
- US Inflation Reduction Act domestic content credits:Semiconductor packaging and test localization near vehicle assembly plants in Michigan and Tennessee qualifies for production incentives.
Industry Challenges
- Power packaging engineering scarcity:Thermal-mechanical simulation expertise for wide-bandgap devices remains concentrated among specialists with GaN and SiC field experience.
- Multi-physics co-design complexity:Electromagnetic interference, thermal cycling, and mechanical stress must be solved simultaneously for 175°C junction operation.
- Supply chain reconfiguration friction:Relocating ceramic substrate sourcing from East Asia to Eastern Europe disrupts established qualification relationships with German OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Power Electronics Market |
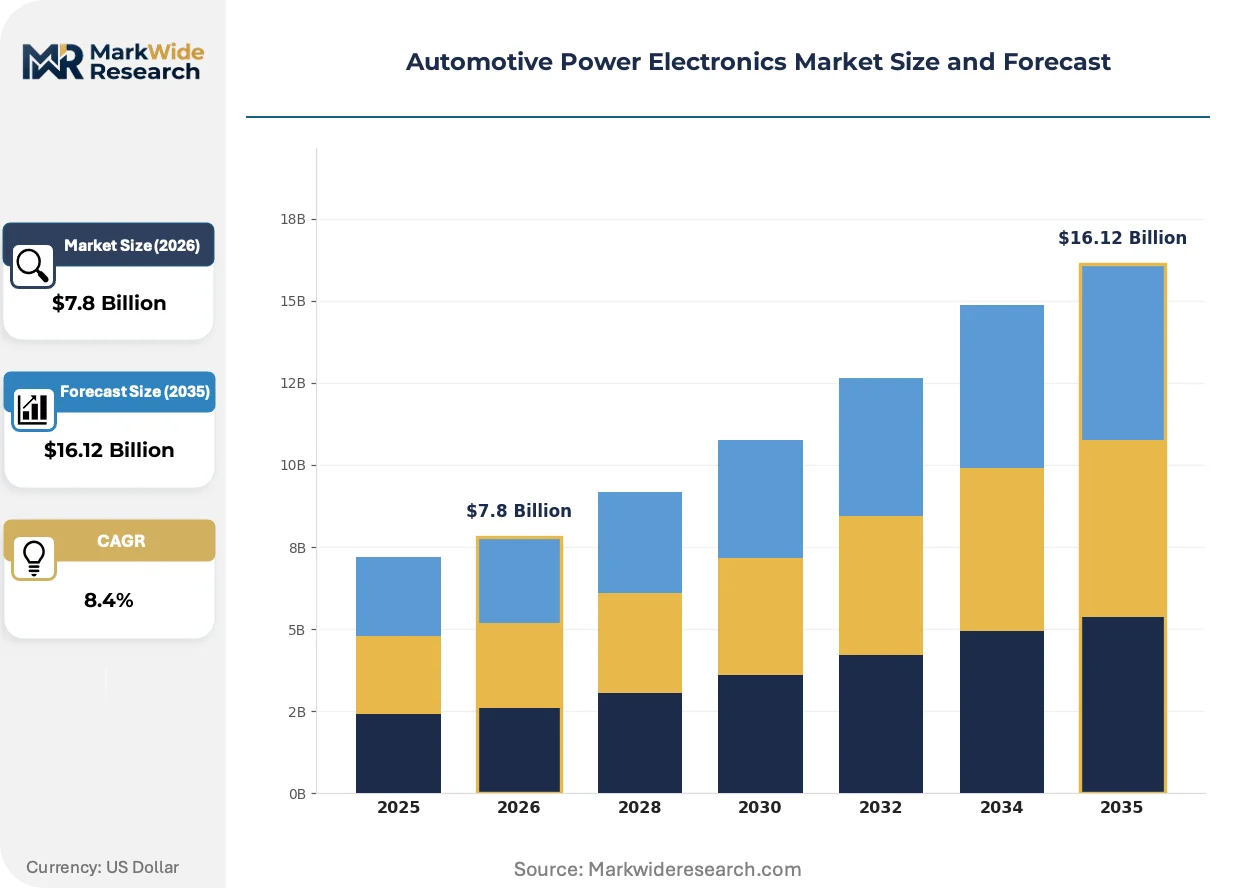
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Modules, Motor Drives, Power Management ICs, DC-DC Converters Technology: Silicon, SiC, GaN, Analog End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Electric Vehicles, Hybrid Vehicles, Power Steering, Thermal Management |
| Companies Covered | STMicroelectronics, NXP Semiconductors N.V., Infineon Technologies AG, Continental AG, ON Semiconductor, Texas Instruments Incorporated, Renesas Electronics Corporation, Mitsubishi Electric Corporation, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Power Electronics Market Emerging Trajectories
Silicon carbide technology is compressing the cost-performance frontier for traction inverters, while regulatory pressure on embodied carbon reshapes supplier qualification criteria and procurement patterns favor vertically integrated module makers.
Silicon carbide MOSFETs enable higher switching frequencies with lower switching losses than silicon IGBTs in 800-volt traction inverters. European and Chinese OEMs are adopting these devices fastest in premium EV platforms. The technology is migrating from discrete die sales toward complete power module subsystems as suppliers capture more value per vehicle.
The EU F-Gas Regulation tightens embodied carbon thresholds for imported power electronics, compelling suppliers to document manufacturing energy intensity across supply chains. Module makers must now trace substrate epitaxy, wafer dicing, and packaging energy consumption. German OEMs are responding by co-locating assembly plants with suppliers possessing renewable-heavy production footprints.
Fleet procurement departments are consolidating inverter supplier rosters from five-plus vendors to two or three strategic partners per platform generation. Tier-1 module makers are displacing discrete component distributors in direct OEM relationships. This concentration is most visible in China, where BYD and NIO have established captive engineering teams within supplier facilities to compress development cycles.
Automotive Power Electronics Market Segmentation
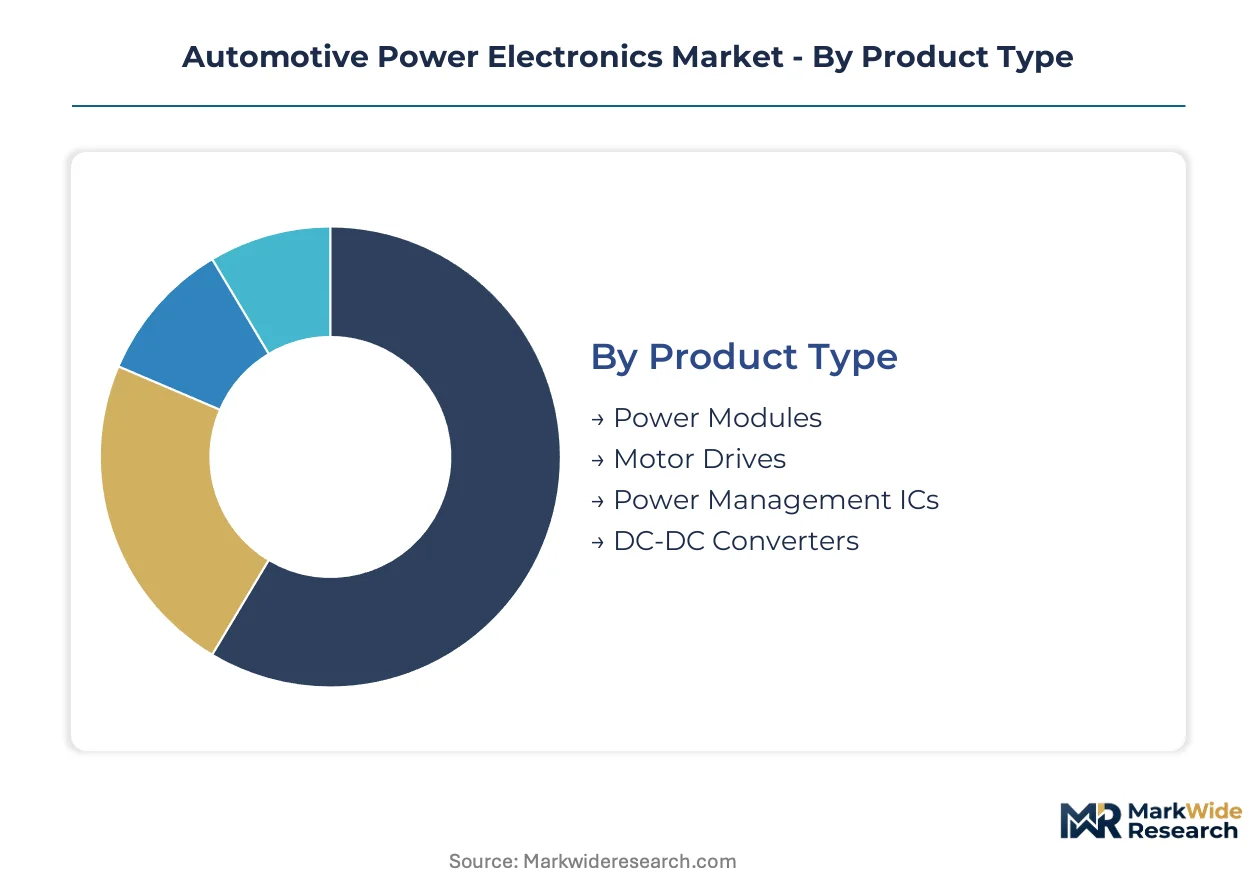
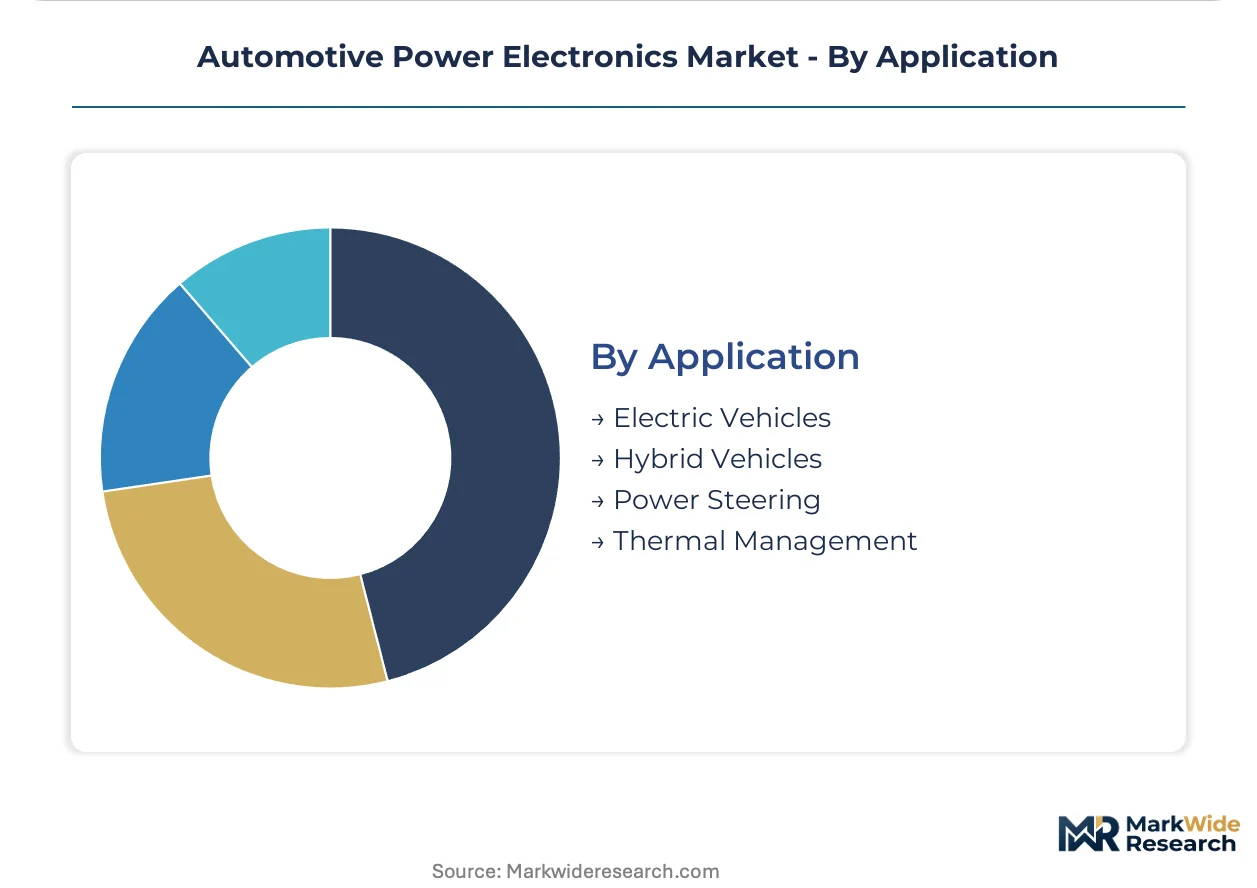
Automotive power electronics segmentation reflects competing pressures between silicon legacy infrastructure and wide-bandgap technology transitions. Module architecture choices directly determine qualification pathways with European and Chinese OEMs.
Product Type:
Mature silicon-based categories dominate current procurement volumes while SiC-integrated modules command premium positioning in 800-volt platform tenders.
- Power Modules:These integrate IGBTs or MOSFETs with ceramic substrates and copper baseplates into sealed packages rated for 175°C junction temperatures. German OEMs concentrate procurement with suppliers co-located near vehicle assembly plants in Bavaria and Baden-Württemberg to satisfy EU Green Deal embodied carbon documentation requirements.
- Motor Drives:Inverter subsystems convert DC battery output to variable-frequency AC for traction motors, typically operating at 20-100 kHz switching frequencies. China's MIIT enforces GB standards for electromagnetic compatibility that foreign module makers must satisfy for domestic platform qualification, accelerating redesign cycles for entry.
- Power Management ICs:Gate drivers and protection logic from suppliers like Texas Instruments manage switching sequences and fault isolation.
- DC-DC Converters:These step voltage between 48-volt mild-hybrid subsystems and 12-volt accessory networks.
Power Modules retain volume leadership; DC-DC Converters hold the steepest expansion curve.
Technology:
Cost tier stratification separates commodity silicon from qualification-constrained wide-bandgap alternatives.
- Silicon:Mature IGBT technology serves 400-volt platforms and cost-sensitive hybrid architectures with established supply chains.
- SiC:Silicon carbide MOSFETs enable higher switching frequencies with lower thermal losses than silicon equivalents. Substrate supply concentrates among three merchant producers of six-inch wafers, creating allocation bottlenecks during demand surges.
- GaN:Gallium nitride devices target on-board charger and DC-DC applications below 650V.
- Analog:Discrete control circuits persist in legacy power steering and thermal management subsystems.
Silicon retains installed base dominance; SiC claims the steepest expansion curve.
End User:
Customer type determines contract structure, with direct OEM relationships displacing distributor channels for strategic platform components.
- OEMs:Volkswagen Group and BYD consolidate inverter supplier rosters to two or three strategic partners per platform generation, compressing qualification timelines through captive engineering teams embedded at supplier facilities.
- Tier-1 Suppliers:Bosch and Continental module divisions integrate trench-gate MOSFETs with on-chip sensing to offer subsystem-level solutions directly to vehicle assemblers.
- Aftermarket Providers:Independent distributors serve repair networks for legacy hybrid fleets.
- Vehicle Assemblers:Contract manufacturers in Michigan and Tennessee qualify for US Inflation Reduction Act domestic content credits when packaging and test operations localize near final assembly.
Tier-1 Suppliers retain volume leadership; OEM direct procurement holds the steepest expansion curve.
Application:
Application segmentation tracks powertrain electrification intensity across vehicle architectures.
- Electric Vehicles:Battery-electric platforms demand full traction inverters, on-board chargers, and high-voltage DC-DC conversion. NIO and XPeng specify SiC inverters for premium 800-volt architectures to maximize range efficiency.
- Hybrid Vehicles:48-volt mild-hybrid systems require redesigned DC-DC converters alongside conventional 12-volt networks, opening volume slots for second-tier suppliers in Germany and the United States.
- Power Steering:Electric power steering modules represent a mature segment with stable margins and silicon IGBT dominance.
- Thermal Management:HVAC compressor drives and battery thermal regulation circuits operate at lower power thresholds.
Hybrid Vehicles retain volume leadership; Electric Vehicles hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in automotive power electronics tilt toward net-importing European and North American markets, while China and South Korea build surplus capacity in SiC substrate processing and module assembly.
China
Domestic EV manufacturers BYD and NIO drive procurement of 800-volt SiC inverters at scale. MIIT enforces GB standards for electromagnetic compatibility that foreign module makers must satisfy for platform qualification. Yangtze River Delta clusters around Shanghai and Suzhou concentrate captive SiC epitaxy and packaging operations.
Germany
Volkswagen Group and BMW anchor demand for high-voltage traction inverters with integrated thermal management. EU Green Deal embodied carbon thresholds compel suppliers to document manufacturing energy intensity across supply chains. Bavaria and Baden-Württemberg host co-located module production near vehicle assembly plants to satisfy renewable-heavy grid documentation.
United States
General Motors and Ford expand 800-volt platform procurement, compressing supplier qualification timelines. EPA and NHTSA coordinate tailpipe and upstream emissions rules extending compliance burdens to semiconductor content. Michigan and Tennessee vehicle assembly corridors attract packaging and test localization qualifying for Inflation Reduction Act domestic content credits.
Japan
Toyota and Honda hybrid platforms sustain demand for silicon IGBT motor drives with stable procurement volumes. METI promotes domestic SiC substrate development through technology roadmaps and public-private partnerships. Kansai and Nagoya industrial corridors maintain legacy power module assembly for hybrid powertrain exports.
South Korea
Hyundai-Kia electrification targets accelerate SiC inverter adoption across premium EV architectures. National semiconductor strategies under K-Semiconductor Belt programs incentivize wafer fab capacity expansion. Seoul Capital Area and Busan-Ulsan corridors concentrate module packaging operations serving domestic OEMs and export markets.
Automotive Power Electronics Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in semiconductor substrate and discrete device supply. The vendor base stratifies across three tiers: captive silicon carbide producers with epitaxy-to-module pipelines, fabless gate driver specialists, and tier-1 subsystem integrators. Dominant competitive moves include capacity expansion in six-inch SiC wafer fabrication and strategic partnerships locking multi-year supply agreements before substrate ramps materialize.
Among European semiconductor fabricators, Infineon Technologies AG, STMicroelectronics, and Robert Bosch GmbH exemplify contrasting strategic postures. Infineon anchors the captive substrate tier with in-house six-inch SiC wafer production. STMicroelectronics occupies the vertical integration archetype spanning epitaxy through module assembly. Bosch represents the tier-1 subsystem integrator tier, embedding power electronics within broader powertrain portfolios.
| Leading Market Players |
|---|
| STMicroelectronics |
| NXP Semiconductors N.V. |
| Infineon Technologies AG |
| Continental AG |
| ON Semiconductor |
| Texas Instruments Incorporated |
| Renesas Electronics Corporation |
| Mitsubishi Electric Corporation |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Six-inch SiC wafer undercapacity across East Asian merchant producers tightens allocation discipline, forcing OEMs to accept long-term offtake premiums and locking module makers into fixed-price substrate contracts that compress margin flexibility.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for power modules, with three-tier pricing structure across premium SiC, standard silicon IGBT, and economy-grade legacy architectures. Price differentiation stems from ISO 26262 ASIL-D certification tier and volume scale commitments above ten-thousand units annually. Pricing pressure stems from platinum-group metal volatility in ceramic substrates, particularly silver metallization layers. Tier-1 suppliers with captive SiC capacity exhibit lowest price sensitivity; aftermarket distributors serving legacy hybrid fleets face acute cost compression.
Supply Chain Analysis
Export controls on wide-bandgap semiconductor manufacturing equipment restrict substrate fabrication equipment flows to Chinese fabs, concentrating six-inch SiC wafer supply among Taiwan, Japan, and the United States. Raw material dependencies include high-purity silicon carbide powder, copper-clad ceramic substrates, and silver sinter pastes for die attach. Single-source vulnerability concentrates in AMB ceramic substrate supply from Japanese producers. Distribution runs through direct OEM procurement channels displacing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive power electronics market is recovering from cyclical inventory destocking as 800-volt platform launches accelerate procurement cycles.
For Market Incumbents: Entrench through backward integration into SiC epitaxy capacity and captive six-inch wafer fabrication to offset substrate allocation risk from merchant suppliers. Lock multi-year supply agreements with European OEMs before competitor capacity ramps materialize. Prioritize ISO 26262 ASIL-D certification investment to defend against emerging fabless gate driver specialists. For New Entrants and Emerging Players: Build out 48-volt mild-hybrid DC-DC converter architectures for legacy combustion platforms in Germany and the United States, the most penetrable white-space segment. Target tier-2 supplier relationships with vehicle assemblers qualifying for US Inflation Reduction Act domestic content credits. Pursue subsystem-level integration with on-chip temperature sensing as the go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-1 module makers with captive OEM platform engineering teams. Long-term viability over the next decade favors vertically integrated suppliers spanning epitaxy through module assembly. Acquisition target archetype: mid-cap specialists with existing SiC field experience and thermal-mechanical simulation expertise. The signal to watch is MIIT enforcement pace for GB electromagnetic compatibility standards accelerating domestic qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Substrate Capacity Expansion | Captive six-inch wafer fabrication secures allocation priority with Volkswagen Group and BYD. |
| Long-term Supply Agreement | Multi-year offtake contracts with OEMs de-risk capital deployment for greenfield fab investments. |
| Platform Standardization | Unified 800-volt inverter architectures reduce qualification burden across NIO and XPeng vehicle lines. |
| Geographic Manufacturing Footprint | Michigan and Tennessee packaging localization qualifies for IRA domestic content credits. |
| Software-Defined Vehicle Investment | Integrated gate drivers with on-chip protection logic enable over-the-air calibration updates. |
Methodological Framework
Desk research of SEC filings, vehicle production databases, and customs trade records preceded structured interviews with OEM platform engineers, tier-1 supplier procurement leads, SiC substrate specialists, and aftermarket distribution heads. Primary fieldwork combined telephone consultations and facility observations with bottom-up bill-of-materials analysis and top-down market sizing triangulation.
Assumptions held fixed include current EU Green Deal embodied carbon thresholds and MIIT GB standard enforcement timelines; variables tested across the analysis window included SiC substrate ramp schedules and 800-volt platform adoption curves. Segmentation dimensions modeled encompass propulsion architecture, semiconductor technology tier, content per vehicle, and regional production cluster. CAGRs derived from unit shipment trajectories weighted by average selling price evolution, with inputs including IHS Markit vehicle registration data and OEM powertrain disclosure filings.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed substrate producers would shift outcomes. Material shifts in US EPA tailpipe rule stringency or EU F-Gas Regulation carbon-border adjustment implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Semiconductor Rectifier Market
Power Systems
Generator Circuit Breaker Market
Power Systems
North America Variable Frequency Drive Market
Power Systems
Harmonic Generators Market
Power Systems
Synchronous Condenser Market
Power Systems
DC-DC Converter Market
Power Systems
Solid State Transformer Market
Power Systems
Traction Inverter Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Global Excitation Systems Market
Power Systems
Automotive Inverters Market
Power Systems
Power Integrated Modules Market
Power Systems
Battery Charge Controller Market
Power Systems
Flyback Transformer Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Synchrophasors Market