
 Power Transistor Market | 2026-2036
Power Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Power Transistor Market Analysis
EPA tailpipe emissions standards are repositioning the cost-of-entry calculus for automotive-qualified power transistors. Infineon Technologies AG leverages its vertical integration into silicon carbide substrates to sustain pricing power in EV traction inverters. Texas Instruments Incorporated anchors its industrial portfolio with integrated gate drivers that reduce design cycle times for switch mode power supplies.
A power transistor is a semiconductor device engineered to regulate substantial current and voltage levels, typically fabricated from silicon, silicon carbide, or gallium nitride, with switching frequencies spanning kilohertz to megahertz depending on material bandgap. Its primary purpose is to control power flow in switching and amplification circuits across automotive, industrial, and energy applications. MOSFETs occupy the largest volume share due to their dominance in consumer electronics and low-voltage motor drives, while silicon carbide IGBTs represent the fastest-expanding margin pool as EV platforms migrate to 800-volt architectures. Gallium nitride field effect transistors are displacing legacy silicon in high-frequency switch mode power supplies below 650 volts.
FCC equipment authorization rules constrain electromagnetic interference thresholds for consumer electronics deployments, while EPA corporate average fuel economy standards and NHTSA safety mandates accelerate automotive electrification that consumes higher transistor counts per vehicle. The EU Green Deal and associated F-Gas Regulation phase-downs are tightening energy efficiency benchmarks for industrial motor drives across European manufacturing bases. Stakeholders must monitor how rapidly evolving material qualification protocols for wide-bandgap semiconductors reshape supplier certification requirements and foundry allocation priorities.
Market Dynamics
Power transistor procurement is concentrating around 800-volt EV platforms, forcing foundries to reallocate capacity toward silicon carbide wafers and away from legacy silicon IGBT lines.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Stringent fleet efficiency mandates in the United States are compelling automakers to electrify powertrains, multiplying transistor counts per vehicle by three to five times over internal combustion equivalents.
- Silicon carbide substrate transitions:Wide-bandgap material adoption is unlocking higher switching frequencies and reduced thermal losses, enabling smaller inverter footprints and extended driving range in premium EV segments.
- EU F-Gas Regulation phase-downs:Industrial motor drive manufacturers across Germany, France, and Italy face mandatory efficiency upgrades, creating replacement demand for high-performance MOSFET modules in HVAC and pumping systems.
Market Restraints
- Silicon carbide wafer supply concentration:Over 80 percent of substrate production remains captive to vertically integrated device manufacturers, constraining independent foundry access and inflating raw material premiums.
- Copper and rare earth price volatility:Package metallization and magnetic component costs fluctuate with commodity cycles, compressing gross margins for standard-grade discrete transistor suppliers.
- Technical yield limitations at 200mm:Defect density in larger-diameter silicon carbide boules remains elevated versus silicon, throttling output expansion and elongating qualification timelines for automotive-grade devices.
Strategic Opportunities
- India PLI scheme for semiconductors:Production-linked incentives for domestic fabs and packaging facilities are attracting joint venture proposals for power discrete manufacturing serving South Asian automotive and renewable energy markets.
- GaN-on-silicon integration with consumer adapters:Gallium nitride transistors are penetrating sub-100-watt fast-charger applications, opening volume markets previously reserved for silicon superjunction MOSFETs.
- Grid-scale energy storage inverters:Utility-scale battery installations require megawatt-class power conversion, creating demand for paralleled IGBT and SiC modules with 25-year operational lifespans.
Industry Challenges
- Automotive AEC-Q101 qualification timelines:Extended stress testing and temperature cycling requirements delay product introductions by 18 to 24 months, straining R&D budgets and obsolescence risk management.
- Packaging thermal-mechanical expertise scarcity:Finite pools of engineers skilled in silver sintering and transient liquid phase bonding constrain module reliability advancement for 175°C junction temperature targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Transistor Market |
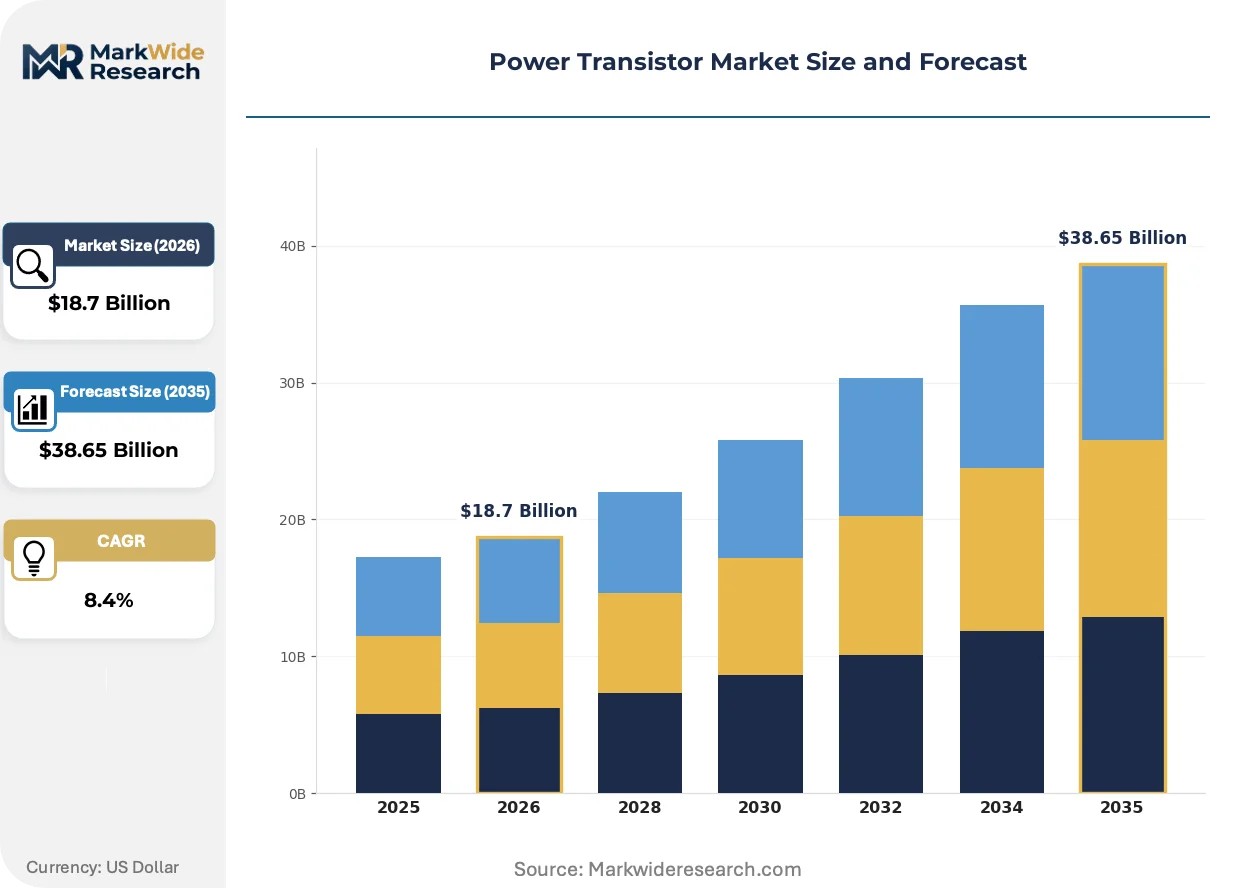
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction Transistor, Field Effect Transistor, IGBT, MOSFET Application: Amplifiers, Switch Mode Power Supplies, Motor Drives, Renewable Energy Systems Technology: Silicon, Gallium Nitride, Silicon Carbide, Organic End User: Consumer Electronics, Industrial Automation, Automotive, Aerospace |
| Companies Covered | Texas Instruments Incorporated, Renesas Electronics Corporation, Infineon Technologies AG, Mitsubishi Electric Corporation, Toshiba Corporation, STMicroelectronics N.V., NXP Semiconductors N.V., Wolfspeed Inc., onsemi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Transistor Market Emerging Trajectories
Material science breakthroughs and regulatory efficiency mandates are converging to redefine power transistor architectures, with thermal performance and electromagnetic compliance emerging as primary design constraints.
Silicon carbide MOSFET technology is automating thermal management complexity in EV traction inverters by enabling higher junction temperatures and reduced cooling system mass. Automakers in Germany and the United States are accelerating platform migrations to 800-volt architectures, compressing development cycles for integrated power modules. The structural consequence is a consolidation of inverter supply chains around device suppliers with captive SiC substrate access and advanced packaging capabilities.
The EU F-Gas Regulation and associated Ecodesign requirements are mandating efficiency thresholds for industrial motor systems above 375 kilowatts. European manufacturers must retrofit existing variable frequency drives with next-generation transistors or face operational restrictions in energy-intensive sectors. German machine builders and Italian pump OEMs are responding by pre-qualifying SiC-based drive platforms ahead of 2027 enforcement deadlines.
Direct procurement relationships between EV OEMs and power semiconductor foundries are displacing traditional tiered distribution channels for high-voltage devices. Volume commitments for 2027-2030 model year platforms are being negotiated 36 months ahead of production, locking in capacity at the expense of spot market flexibility. This pattern is most visible in China, where domestic EV brands are securing multi-year supply agreements with local SiC wafer growers to insulate against export control volatility.
Power Transistor Market Segmentation
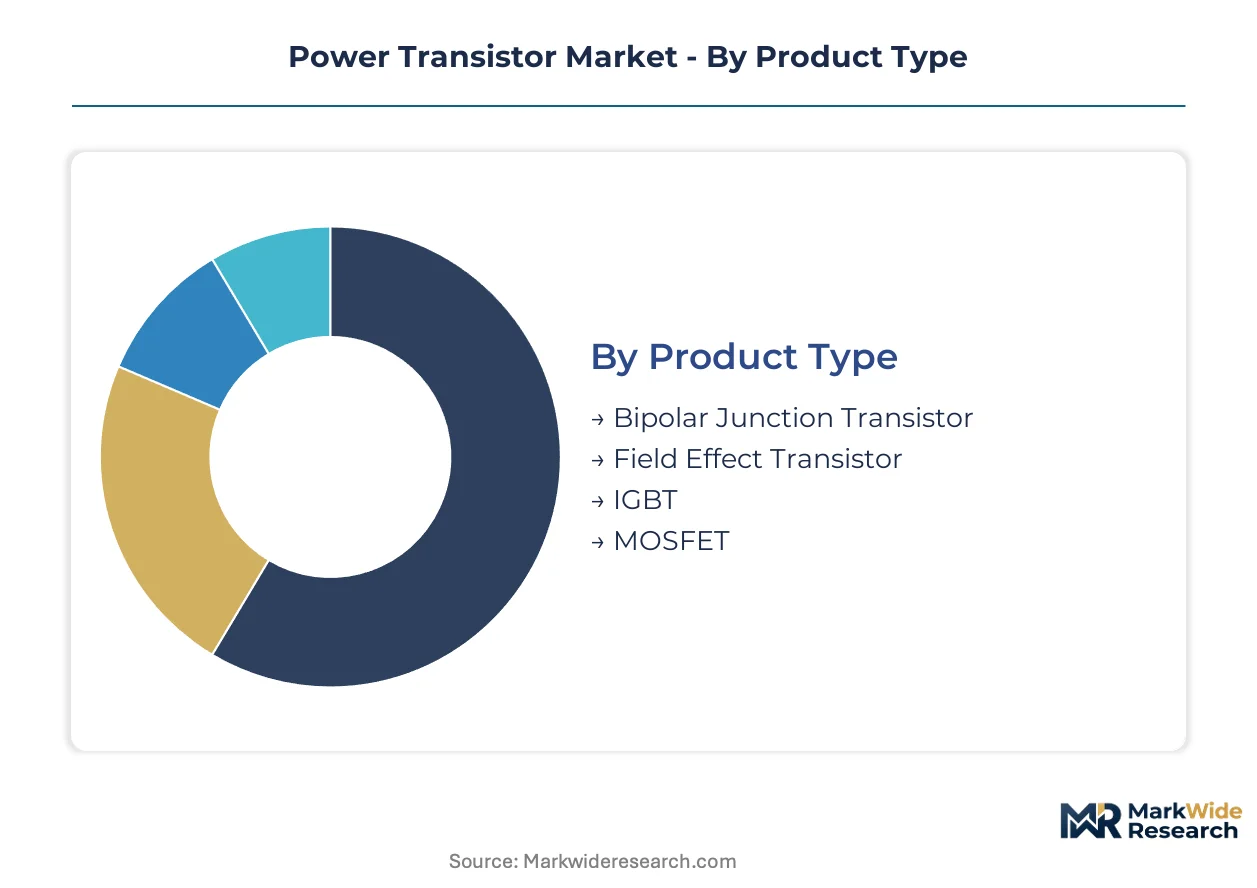
Power transistor procurement decisions hinge on voltage thresholds, switching frequencies, and thermal envelopes that vary sharply across end-use environments. Segmentation reveals how material transitions and application-specific qualification requirements reshape supplier strategies and foundry allocation priorities.
Product Type:
Engineering teams select device architectures based on switching speed requirements and voltage-handling thresholds, with cost-per-ampere and thermal efficiency serving as primary trade-off variables.
- MOSFET:Metal-oxide-semiconductor field-effect transistors dominate low-voltage motor drives and consumer electronics through superior switching speeds and reduced gate drive losses. Demand concentrates in German industrial automation clusters and Chinese EV auxiliary systems where efficiency mandates tighten.
- IGBT:Insulated-gate bipolar transistors merge MOSFET gate control with bipolar conduction, optimizing 600-volt to 6.5-kilovolt traction inverters and grid-scale converters. Adoption accelerates in 800-volt EV platforms across the United States and China as automakers pursue extended range targets.
- Field Effect Transistor:Generic FET architectures serve specialized RF amplification and precision analog switching where linearity requirements exceed power density priorities.
- Bipolar Junction Transistor:Legacy silicon BJTs persist in cost-sensitive linear amplification and low-frequency power regulation where switching speed is secondary to unit economics.
MOSFET leads on scale; IGBT leads on momentum.
Application:
End-use voltage levels and duty cycle intensity determine whether silicon, silicon carbide, or gallium nitride devices deliver optimal lifetime cost of ownership.
- Switch Mode Power Supplies:High-frequency DC-DC and AC-DC conversion in data centers, telecom infrastructure, and consumer adapters. GaN transistors below 650 volts displace silicon superjunction MOSFETs in premium fast-charger segments across Chinese and US consumer markets.
- Motor Drives:Variable frequency drives for HVAC, pumping, and industrial motion control. EU F-Gas Regulation phase-downs force German and Italian manufacturers toward SiC-based platforms ahead of 2027 efficiency enforcement deadlines.
- Renewable Energy Systems:Solar inverters and wind turbine converters requiring 25-year operational lifespans. Utility-scale battery storage in China and the United States drives paralleled module configurations.
- Amplifiers:Audio and RF amplification where linearity and harmonic distortion specifications outweigh switching efficiency metrics.
Switch Mode Power Supplies command the broadest volume base; Motor Drives face the steepest technology substitution pressure.
Technology:
Bandgap engineering directly determines switching frequency ceilings, thermal conductivity, and the cooling system mass required for reliable operation.
- Silicon Carbide:Wide-bandgap compound enabling 175°C junction temperatures and 50% reduction in inverter cooling hardware. Captive substrate supply at Infineon and Wolfspeed constrains independent foundry access while automotive qualification timelines extend 18 to 24 months.
- Silicon:Mature trench-gate and superjunction architectures serving cost-optimized applications below 600 volts where switching frequencies remain below 100 kilohertz.
- Gallium Nitride:Heteroepitaxial GaN-on-silicon integration unlocks megahertz switching in sub-100-watt adapters and telecom rectifiers, with volume manufacturing scaling through consumer electronics supply chains.
- Organic:Emerging flexible and printable transistor architectures for disposable electronics and biomedical sensing where mechanical conformity exceeds power handling requirements.
Silicon retains volume dominance; Silicon Carbide exhibits the steepest expansion trajectory.
End User:
Qualification protocols and procurement scale separate automotive-grade reliability requirements from consumer electronics cost optimization.
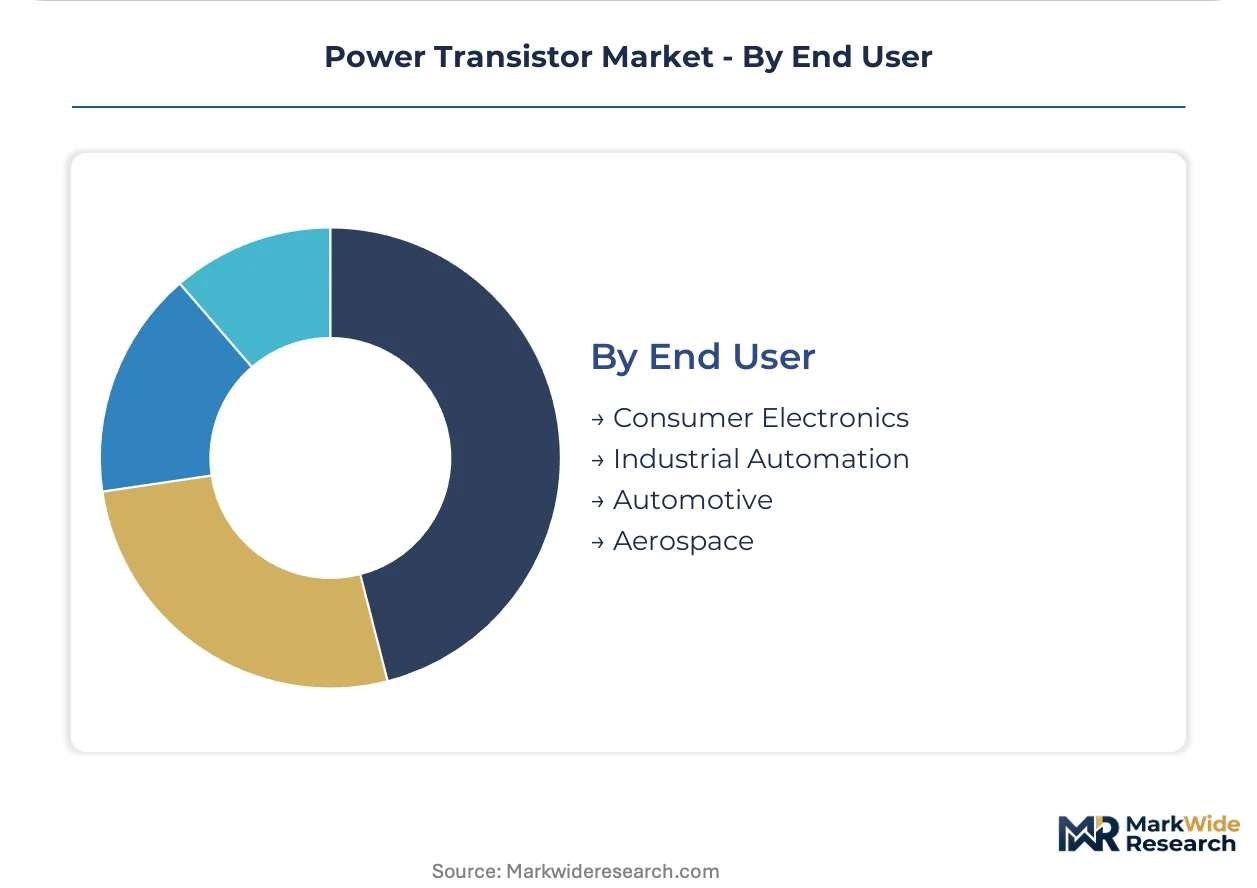
- Automotive:Traction inverters, onboard chargers, and DC-DC converters subject to AEC-Q101 stress testing and ISO 26262 functional safety. Direct OEM-foundry contracting in China and Germany locks capacity 36 months ahead of production.
- Industrial Automation:Variable frequency drives and servo systems requiring 100,000-hour mean time between failures. German machine builders pre-qualify SiC platforms to meet EU Ecodesign thresholds.
- Consumer Electronics:Smartphone adapters, laptop power bricks, and white goods where GaN penetration accelerates in 65-watt to 100-watt fast-charger segments.
- Aerospace:Radiation-hardened and high-reliability devices for satellite power conditioning and aircraft actuation systems subject to DO-160 environmental testing.
Automotive commands the highest qualification barriers; Consumer Electronics enables the fastest technology refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power transistor engineering talent clusters in Munich, Austin, and Shenzhen anchor the industry's geographic footprint. Foundry investments and automotive electrification programs concentrate procurement decisions in three dominant markets.
United States
EV traction inverter demand from Detroit automakers and Austin-based Tesla operations drives silicon carbide procurement. EPA Corporate Average Fuel Economy standards mandate fleet efficiency improvements that multiply transistor counts per vehicle. Texas Instruments anchors industrial gate driver supply from its Dallas-Fort Worth fabrication complex.
Germany
Industrial motor drive retrofits and 800-volt EV platform development consume premium IGBT and SiC modules. EU F-Gas Regulation phase-downs force efficiency upgrades in HVAC and pumping systems by 2027. Bavarian machine builders in Munich-Augsburg corridor pre-qualify SiC-based variable frequency drives ahead of enforcement deadlines.
China
Domestic EV brands secure multi-year supply agreements with local SiC wafer growers to insulate against export control volatility. MIIT dual carbon goals accelerate powertrain electrification timelines across state-owned automakers. Yangtze River Delta clusters in Shanghai-Suzhou dominate both device fabrication and end-use vehicle assembly.
Japan
Precision industrial automation and hybrid vehicle platforms sustain demand for high-reliability discrete transistors. METI energy efficiency benchmarks tighten motor drive specifications in manufacturing sectors. Nagoya-Toyota corridor suppliers integrate advanced packaging for 175°C junction temperature targets in automotive modules.
South Korea
Consumer electronics fast-charger manufacturing and data center power supply expansion drive GaN transistor volume. Domestic semiconductor majors expand 200mm SiC wafer pilot lines under national technology initiatives. Seoul-Incheon metroplex concentrates adapter OEM procurement for 65-watt to 100-watt premium charger segments.
Power Transistor Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Vertically integrated device manufacturers with captive substrate supply command premium pricing in automotive-qualified segments. Independent foundries and fabless designers occupy mid-tier industrial and consumer positions. Standard discrete suppliers face margin compression from commodity silicon oversupply. Capacity expansion and strategic partnerships dominate competitive moves as foundries race to qualify 200mm SiC lines.
Among diversified European semiconductor majors, Infineon Technologies AG and STMicroelectronics N.V. exemplify the vertically integrated archetype with in-house SiC substrate production. Texas Instruments Incorporated anchors the industrial portfolio tier with integrated solutions that compress customer design cycles. Wolfspeed Inc. represents the pure-play wide-bandgap specialist model focused exclusively on compound semiconductor materials.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Renesas Electronics Corporation |
| Infineon Technologies AG |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| Wolfspeed Inc. |
| onsemi |
| Others |
Supply Flow & Price Mechanics
Automotive OEM direct procurement teams now dominate high-voltage power transistor purchasing, compressing traditional distribution margins and forcing suppliers toward long-term contract structures indexed to silicon carbide wafer availability.
Pricing Analysis
Unbundled component sales prevail in industrial and consumer segments, while automotive traction inverter procurement bundles device, gate driver, and thermal substrate into single-source agreements. Price differentiation rests on AEC-Q101 certification grade and captive silicon carbide substrate access. Cost compression in standard silicon MOSFETs is intensifying because Chinese foundry capacity expansion outpaces demand growth. Consumer electronics buyers exhibit highest price sensitivity, while automotive OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for 800-volt EV platforms, displacing tiered distribution for automotive-qualified devices. Substrate production concentrates in the United States, Germany, and China, with over eighty percent captive to vertically integrated manufacturers. Device fabrication draws from silicon carbide boules, copper metallization, and rare earth magnetic components. Single-source vulnerability in 200mm SiC wafer supply constrains foundry allocation flexibility. Distribution runs through authorized distributors for industrial mid-volume segments and direct contracts for automotive Tier 1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Corporate Average Fuel Economy standards function as a regulatory compounder, mandating fleet efficiency improvements that multiply power transistor content per vehicle and lock in demand visibility across multi-year platform cycles.
For Market Incumbents: To counter independent foundry access constraints, deepen backward integration into silicon carbide substrate growth while expanding 200mm qualification capacity in Germany or the United States. Secure direct OEM contracting relationships 36 months ahead of production to defend channel position against emerging Chinese suppliers.
For New Entrants and Emerging Players: EU F-Gas Regulation phase-downs in Germany and Italy open a window for SiC-based motor drive retrofits in HVAC and pumping systems ahead of 2027 enforcement. Target Italian pump OEMs and German machine builders with pre-qualified efficiency-upgrade platforms. Pursue joint venture structures under India's PLI scheme to access South Asian automotive and renewable energy demand.
For Investors and Strategic Acquirers: Automotive Tier 1 suppliers are the most active acquirer in this space, seeking captive device supply to secure inverter platform bids. Five-to-ten year viability hinges on substrate access and packaging thermal-mechanical expertise. Monitor 200mm SiC yield improvement announcements as the inflection signal for capacity expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive SiC Substrate Expansion | Infineon and Wolfspeed in-house boule growth secures automotive pricing power against independent foundries. |
| Direct OEM-Foundry Contracting | Tesla and BYD volume commitments lock capacity 36 months ahead, eliminating spot market flexibility. |
| GaN-on-Silicon Consumer Adapter Integration | Navitas and GaN Systems displace silicon superjunction MOSFETs in 65-watt to 100-watt fast-charger segments. |
| 200mm SiC Wafer Qualification | Wolfspeed Mohawk Valley and STMicroelectronics Catania pilot lines target defect density reduction for automotive-grade output. |
| Silver Sintering Packaging Investment | Bosch and Denso advanced module assembly targets 175°C junction temperature for extended EV driving range. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with power semiconductor procurement directors, automotive platform engineers, foundry operations managers, and industrial drive OEM technical directors with secondary validation against SEC 10-K filings, EPA regulatory dockets, EU Ecodesign implementing measures, and customs trade data. Bottom-up device shipment modeling and top-down end-use consumption estimates were triangulated to anchor volume projections.
Comparable historical periods spanning silicon-to-silicon-carbide technology transitions informed the projection framework across the analysis window. Segmentation dimensions included product architecture, voltage tier, bandgap material, end-use qualification grade, and regional production cluster. CAGRs were derived from fitted growth curves incorporating automotive electrification timelines, industrial efficiency mandate enforcement schedules, and foundry capacity expansion announcements.
Revisions become necessary when silicon carbide substrate yield breakthroughs, export control regime shifts, or automotive platform architecture changes materialize faster than modeled. Forecasts reflect documented assumptions regarding AEC-Q101 qualification timelines and 200mm wafer defect density trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Varactor Diode Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market