

MCR Based Static VAR Compensator Market Size, Share, and Industry Trends Forecast 2026-2036
MCR Based Static VAR Compensator Market Insights
High-voltage specification-tier upgrades across utility procurement standards is redrawing competitive boundaries in reactive power compensation. ABB leverages its installed base in HVDC-linked grids to sustain technology leadership in magnetically controlled reactor systems. Siemens Energy anchors European utility demand through integrated power transmission solutions that bundle MCR control with grid stabilization software.
An MCR Based Static VAR Compensator employs a magnetically controlled reactor with saturated iron-core technology to deliver continuously variable reactive power compensation across 6 kV to 500 kV systems, with response times under 100 milliseconds for voltage sag mitigation. The device stabilizes grid voltage fluctuations, suppresses flicker from industrial loads, and enables renewable energy integration by dynamically absorbing or injecting VARs as generation intermittency dictates. High voltage systems dominate current utility procurement due to their compatibility with 220 kV and 400 kV transmission backbones where thermal limits constrain conventional capacitor banks. Renewable integration applications are expanding fastest as wind and solar penetration forces grid operators to source dynamic rather than stepped compensation, concentrating margin pools in hybrid models that combine MCR control with thyristor-switched stages.
China's MEE enforces grid-connected reactive power standards that mandate dynamic compensation for renewable assets above 50 MW, while India's CEA technical standards require static VAR support at interstate transmission nodes. The EU F-Gas Regulation indirectly shapes demand by restricting insulating mediums in competing STATCOM topologies, tilting procurement toward dry-type MCR designs. Stakeholders must monitor how grid code convergence between SAMR-mandated Chinese standards and IEC frameworks affects product certification burdens and factory gate access across competing supply bases.
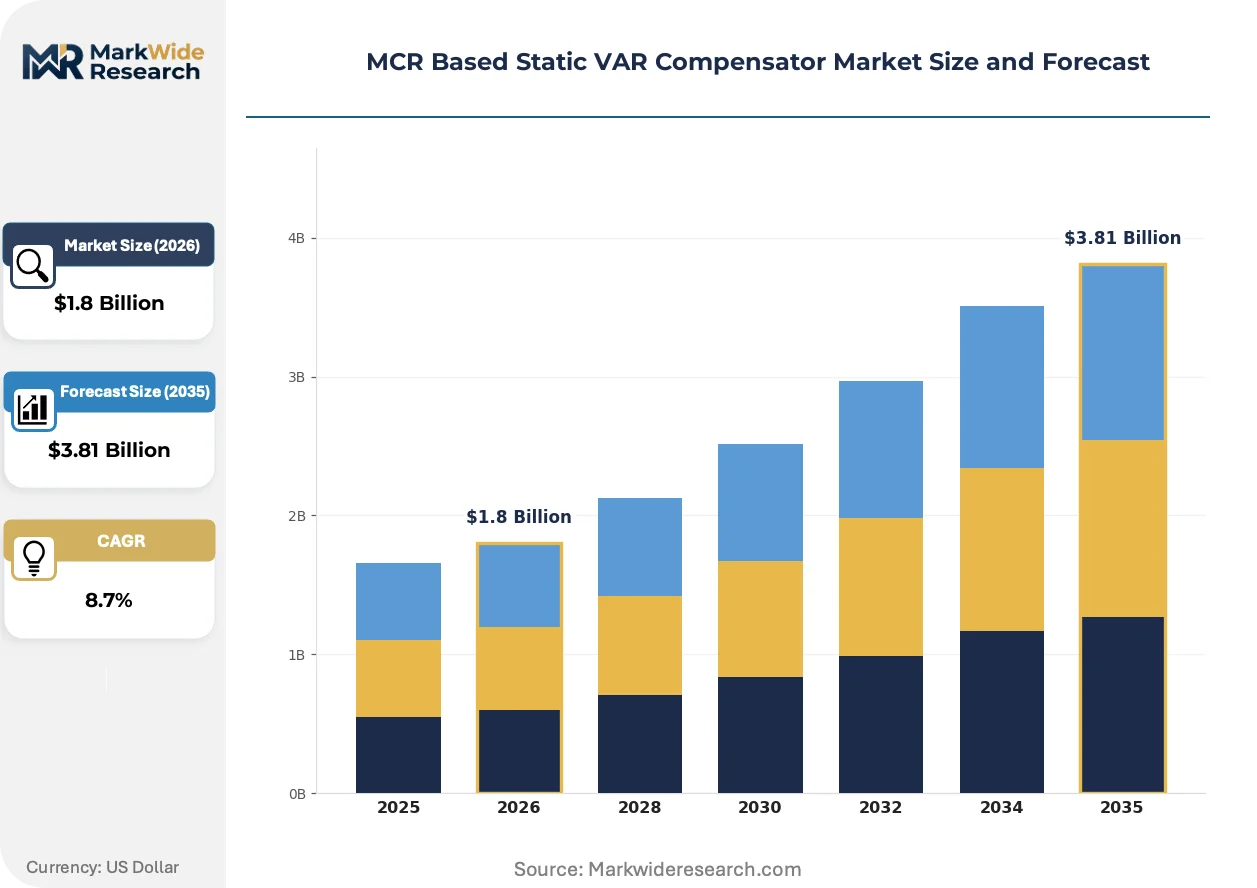
Market Dynamics
Grid code tightening across multiple jurisdictions is forcing utilities to retire stepped capacitor banks in favor of continuously variable reactive power compensation, restructuring procurement specifications and vendor qualification criteria.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on SF6-insulated equipment in competing STATCOM designs tilt utility procurement toward dry-type magnetically controlled reactor systems across Central European transmission networks.
- Renewable integration mandates:China's MEE requires dynamic compensation for wind and solar assets above 50 MW, creating standardized demand pull for MCR-based solutions at utility scale.
- Interstate transmission expansion:India's CEA technical standards mandate static VAR support at key grid nodes, concentrating deployment along high-capacity corridors connecting renewable generation to load centers.
Market Restraints
- Copper and grain-oriented electrical steel volatility:Core material costs for saturated iron-core reactors fluctuate with commodity cycles, compressing margin visibility for equipment manufacturers.
- High-voltage certification timelines:IEC 60076-6 and national type-test requirements for 220 kV and 400 kV systems extend product validation cycles beyond 18 months.
- Thyristor-switched capacitor competition:Hybrid STATCOM architectures with modular multilevel converters offer faster response times for certain flicker suppression applications.
Strategic Opportunities
- Distribution grid retrofit:Medium-voltage MCR deployments at 33 kV and 66 kV substations remain underpenetrated across India's state electricity distribution companies.
- Dual carbon policy alignment:China's SAMR-mandated efficiency standards for grid equipment create certification pathways for next-generation low-loss reactor designs.
- Digital twin convergence:Integration of MCR control systems with real-time grid simulation platforms enables predictive voltage regulation services.
Industry Challenges
- Specialized magnetics engineering scarcity:Design expertise for saturated core reactor optimization is concentrated among aging specialist cohorts in heavy electrical equipment sectors.
- Legacy SCADA integration friction:Utilities operating decades-old control infrastructure face protocol translation complexity when connecting modern MCR controllers to existing substation automation.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MCR Based Static VAR Compensator Market Trends and Innovations
Reactive power compensation technology is pivoting from hardware-centric stepped switching toward software-defined continuous control, with implications for equipment footprint, response latency, and grid operator training requirements.
Solid-state excitation control for magnetically controlled reactors is miniaturizing the auxiliary power electronics that govern core saturation levels. Transmission utilities in Germany and Poland are piloting compact exciter modules that reduce auxiliary cabinet volume by half compared to thyristor-based predecessors. This compression of control hardware footprint is enabling retrofit installations at substations with constrained switchyard space.
The EU F-Gas Regulation is accelerating phase-out timelines for sulfur hexafluoride insulation in high-voltage power equipment. Grid operators in Austria and the Czech Republic are rewriting technical specifications to exclude gas-insulated alternatives, directly benefiting dry-type MCR designs that rely on air and solid insulation. Equipment tenders from TenneT and ČEPS now explicitly score environmental compliance above initial capital cost.
Utility procurement committees are unbundling reactive power compensation from broader substation EPC contracts, creating direct vendor relationships with specialized MCR manufacturers. State Power Grid Corporation of China and Power Grid Corporation of India now issue standalone VAR compensator tenders with performance-based payment terms. This disintermediation of turnkey contractors is most visible in 220 kV greenfield corridors across Shandong and Gujarat.
MCR Based Static VAR Compensator Market Segmentation
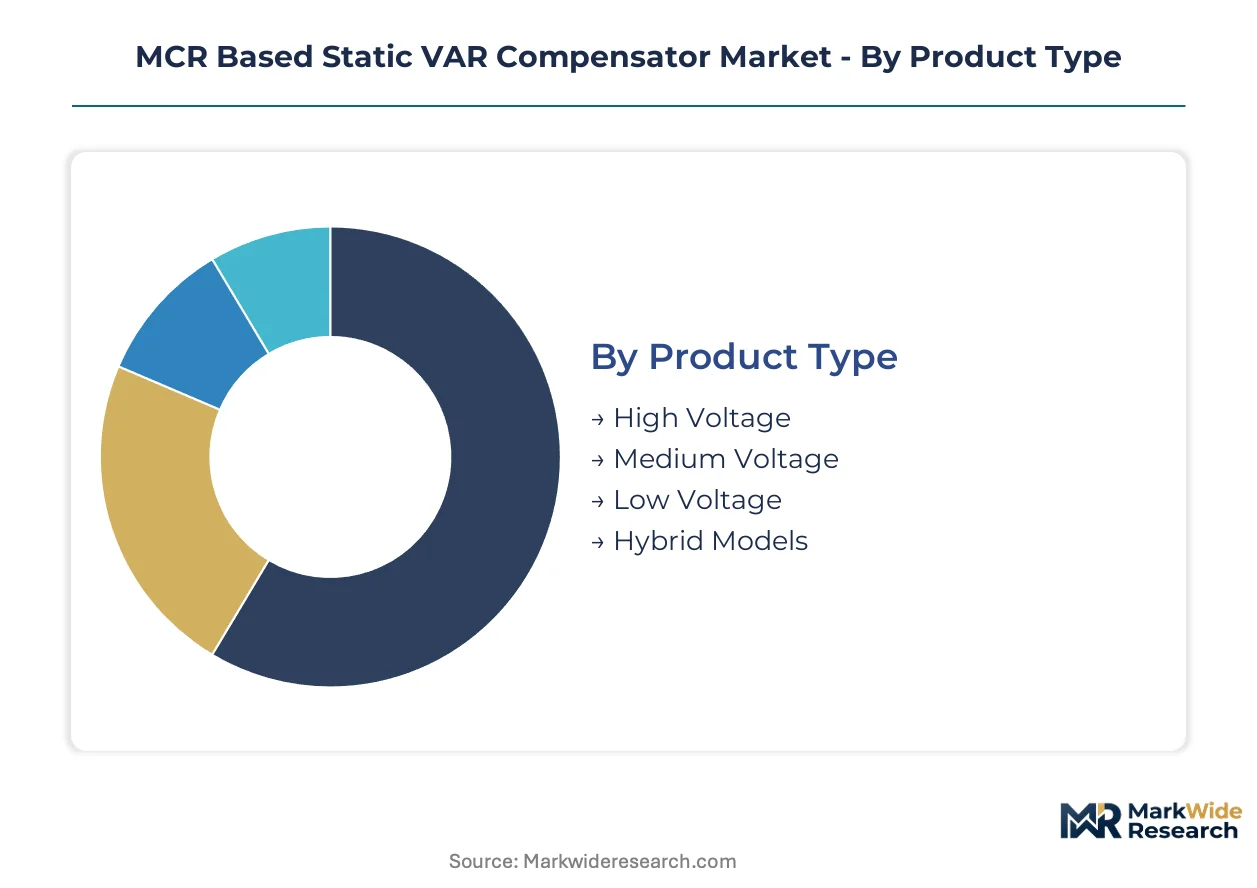
Segmentation of the MCR Based Static VAR Compensator Market reveals how procurement specifications diverge across voltage classes and end-use environments. Utility buyers prioritize continuous reactive power control for grid stabilization, while industrial operators balance response speed against capital constraints in automation and renewable integration contexts.
Product Type:
EU F-Gas Regulation restrictions on gas-insulated equipment have reshaped procurement specifications across voltage tiers, with dry-type designs gaining preference in European transmission corridors.
- High Voltage:Saturated iron-core reactors rated 220 kV to 500 kV serve backbone transmission networks where thermal cycling limits conventional capacitor banks. State Grid Corporation of China and Power Grid Corporation of India concentrate procurement along interstate renewable evacuation corridors in Shandong and Gujarat.
- Hybrid Models:Configurations combining MCR control cores with thyristor-switched capacitor stages deliver stepped-plus-continuous compensation for flicker-intensive industrial loads. German utilities TenneT and ČEPS in the Czech Republic pilot these architectures at steel mill interconnection points.
- Medium Voltage:33 kV to 66 kV systems target distribution substation retrofits where space constraints prohibit conventional SVC footprints.
- Low Voltage:Compact units below 6 kV address power quality in commercial facilities and small-scale renewable installations.
High Voltage handles the majority of throughput; Hybrid Models are expanding most quickly on share as grid codes tighten flicker suppression requirements.
Application:
Cost tier differentiation separates utility-scale transmission investments from industrial automation deployments with shorter payback horizons.
- Power Transmission:Bulk reactive power compensation at 400 kV nodes stabilizes voltage across regional interconnections. India's CEA mandates static VAR support at interstate transmission nodes, concentrating deployment along high-capacity corridors.
- Renewable Integration:Dynamic compensation for wind and solar assets above 50 MW responds to generation intermittency. China's MEE grid-connected standards standardize demand for MCR-based solutions at utility scale.
- Industrial Automation:Arc furnace and rolling mill loads require sub-cycle response for flicker mitigation.
- Railways:Traction power systems use MCR units to manage reactive power from single-phase rectifier loads.
- Data Centers:Hyperscale facilities deploy medium-voltage compensators to manage power factor from uninterruptible power supply banks.
Power Transmission commands the largest installed base; Renewable Integration shows the steepest expansion trajectory as penetration targets force grid operator procurement.
Technology:
Volume concentration favors mature magnetically controlled reactor architectures over emerging solid-state alternatives in current procurement cycles.
- MCR Control:Saturated core technology with continuously variable reactance achieves response times under 100 milliseconds through DC excitation of magnetic biasing windings. Solid-state excitation modules from German and Polish transmission pilots reduce auxiliary cabinet volume by half versus thyristor predecessors.
- Thyristor Switched:Phase-controlled valve assemblies enable stepped reactive power adjustment with faster response for specific flicker applications.
- Capacitor Bank:Conventional switched capacitor stages remain in service for coarse compensation where continuous variability is not required.
- Reactive Power Compensation:Umbrella category encompassing integrated control philosophies rather than discrete hardware topologies.
MCR Control carries the dominant share of new orders; Thyristor Switched architectures are gaining share fastest in hybrid configurations.
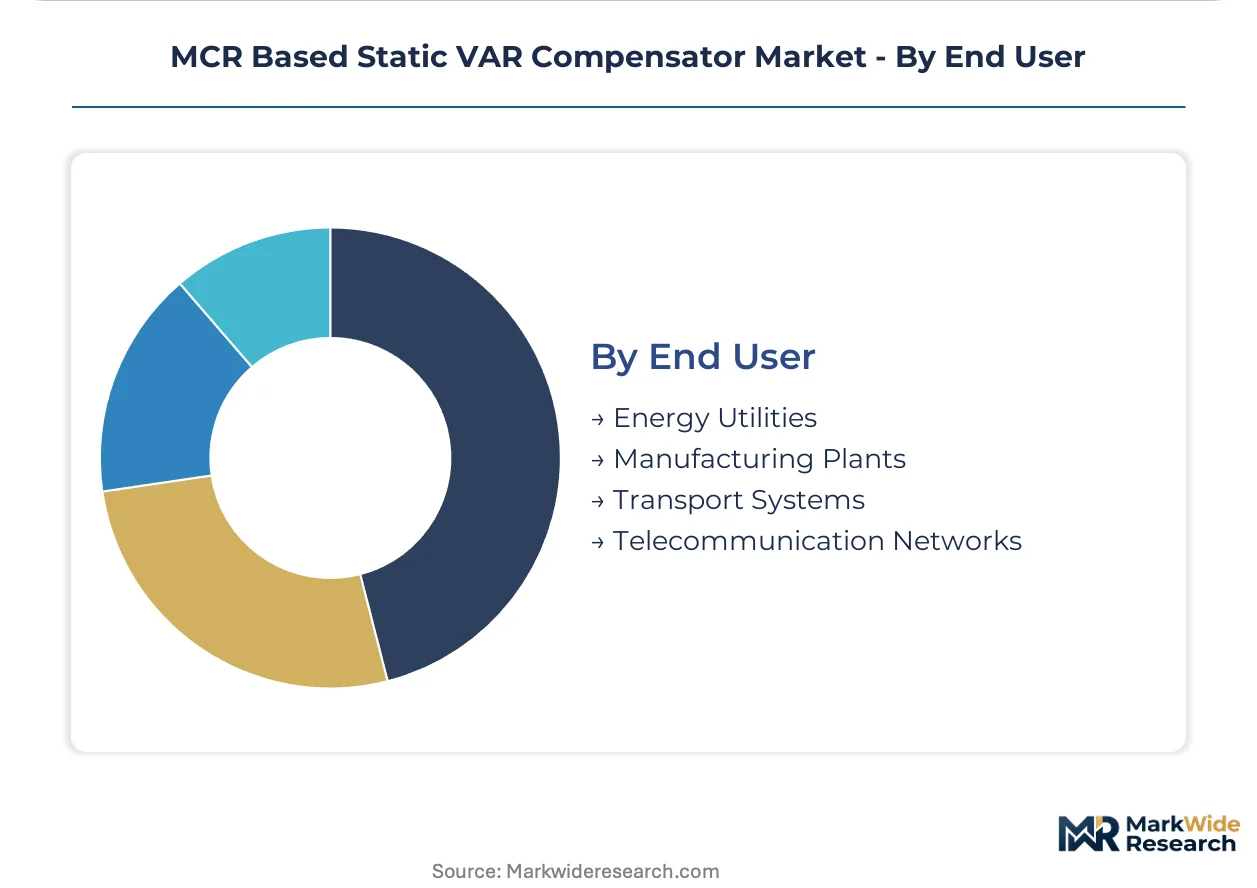
End User:
Customer type determines specification rigor, with energy utilities imposing 18-month certification timelines under IEC 60076-6 that industrial buyers rarely require.
- Energy Utilities:Transmission system operators procure 220 kV and 400 kV systems under standalone VAR compensator tenders with performance-based payment terms. State Power Grid Corporation of China and Power Grid Corporation of India have disintermediated turnkey contractors in recent procurement cycles.
- Manufacturing Plants:Steel, cement, and chemical facilities deploy medium-voltage units for internal power quality management without grid code compliance burdens.
- Transport Systems:Railway electrification authorities and metro operators specify ruggedized designs for traction substation environments.
- Telecommunication Networks:Mobile network operators install compact low-voltage compensators at base station clusters.
Energy Utilities account for the preponderance of revenue; Manufacturing Plants are climbing the fastest as industrial automation intensifies power quality requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment flows from Chinese and Indian manufacturing bases toward European transmission utilities responding to F-Gas Regulation deadlines. Procurement patterns concentrate along renewable evacuation corridors where grid code enforcement is strictest.
China
State Grid Corporation concentrates procurement along Shandong and Xinjiang renewable corridors. MEE mandates dynamic compensation for wind and solar assets above 50 MW. Yangtze River Delta manufacturers supply saturated core reactors to western transmission backbones under SAMR efficiency standards.
India
Power Grid Corporation disintermediates turnkey contractors for standalone VAR compensator tenders. CEA technical standards require static VAR support at interstate nodes. Gujarat and Maharashtra host deployment clusters connecting solar parks to national grid infrastructure.
Germany
TenneT rewrites technical specifications to exclude SF6-insulated alternatives. EU F-Gas Regulation accelerates phase-out timelines for competing STATCOM topologies. Bavarian and North Rhine-Westphalian substations pilot compact solid-state excitation modules from Polish transmission pilots.
United States
FERC Order 2023 compliance drives utility procurement for voltage stability across Texas and California interconnections. Independent system operators source continuously variable compensation for renewable-heavy zones. ERCOT and CAISO procurement concentrates in West Texas solar corridors and Central Valley wind zones.
Poland
ČEPS tenders explicitly score environmental compliance above initial capital cost. Central European transmission networks favor dry-type MCR designs over gas-insulated competitors. Silesian and Masovian grid nodes deploy hybrid configurations for steel mill interconnection points.
MCR Based Static VAR Compensator Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and regional certification capabilities. The vendor base stratifies between diversified electrical conglomerates and magnetics-focused engineering houses. Three archetypes dominate: integrated power transmission solution providers, saturated core reactor specialists, and thyristor control module suppliers. Capacity expansion and strategic partnerships constitute the primary competitive moves as manufacturers position for utility-scale tender participation.
Among diversified electrical conglomerates, ABB and Siemens Energy exemplify the integrated solution archetype, bundling MCR control with grid stabilization software. Hitachi Energy occupies a position bridging Japanese precision manufacturing with European utility relationships. These three represent contrasting geographic anchors—Swiss-Swedish, German, and Japanese—each sitting within distinct regulatory compliance ecosystems.
| Leading Market Players |
|---|
| ABB |
| Siemens Energy |
| Hitachi Energy |
| General Electric |
| Mitsubishi Electric |
| Toshiba Energy Systems & Solutions |
| American Superconductor |
| Delta Electronics |
| NR Electric |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month certification timelines for IEC 60076-6 type-testing compress inventory turnover for high-voltage reactor manufacturers, concentrating pricing power among vertically integrated suppliers in China and Germany while squeezing margin visibility for specialist vendors dependent on spot-market grain-oriented electrical steel.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across medium-voltage MCR deployments, with three-tier pricing stratification across premium certified, standard utility-grade, and economy non-grid-code tiers. Price differentiation hinges on IEC 60076-6 certification status and copper winding purity grades. Cost compression in economy tiers intensifies as Chinese state-owned utilities consolidate procurement volumes. Energy utilities exhibit lowest price sensitivity due to grid code compliance mandates, while manufacturing plants negotiate aggressively on total installed cost.
Supply Chain Analysis
Twenty-four to thirty-six month order backlogs for saturated core reactors signal inventory strain across the magnetics supply base. Manufacturing concentrates in China, Germany, and India, with Yangtze River Delta fabricators feeding domestic renewable corridors and Bavarian specialists serving F-Gas Regulation-driven European demand. Core production draws from grain-oriented electrical steel mills in Japan and South Korea, with copper winding supply anchored in Chilean concentrate flows. Single-source vulnerability sits with specialized magnetics engineering expertise concentrated among aging specialist cohorts. Distribution runs through direct utility procurement channels disintermediating traditional EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation phase-out timelines for SF6-insulated equipment constitute a structural inflection, accelerating displacement of competing STATCOM topologies and expanding addressable market for dry-type MCR architectures across Central European transmission networks.
For Market Incumbents: Fortify technology leadership through captive supply of grain-oriented electrical steel and in-house magnetics engineering capacity, insulating margin structures from commodity volatility. Deepen certification investments under SAMR-mandated Chinese efficiency standards and IEC 60076-6 frameworks to extend factory gate access. Prioritize software-defined control integration with real-time grid simulation platforms as defensive moat against thyristor-switched hybrid architectures. For New Entrants and Emerging Players: Predictive maintenance service layers for installed MCR bases represent underexploited white space where incumbents under-serve legacy SCADA integration requirements. Target India's state electricity distribution companies at 33 kV and 66 kV substations, where medium-voltage retrofit penetration remains lowest. Pursue digital twin convergence partnerships with European transmission utilities as differentiated go-to-market pathway. For Investors and Strategic Acquirers: Long-term, this sits as a grid-infrastructure compounding play because renewable integration mandates hardwire continuous VAR compensation demand regardless of generation technology shifts. Acquisition focus should center on saturated core reactor specialists with intact magnetics engineering cohorts and established IEC certification track records. Monitor convergence between SAMR-mandated Chinese standards and IEC frameworks as signal for certification burden harmonization enabling cross-border supply base consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrical Steel Supply | Captive grain-oriented steel sourcing insulates ABB and Siemens Energy from commodity volatility compressing specialist margins. |
| Solid-State Excitation Module Deployment | German and Polish transmission pilots at TenneT and ČEPS validate compact auxiliary cabinet designs enabling constrained substation retrofits. |
| Digital Twin Platform Integration | Real-time grid simulation convergence creates predictive voltage regulation service revenue streams beyond hardware sales cycles. |
| Standalone VAR Compensator Tender Participation | State Grid Corporation of China and Power Grid Corporation of India procurement disintermediation demands direct manufacturer relationships. |
| Dual Carbon Certification Pathway Investment | SAMR-mandated efficiency standards create preferential access to western Chinese renewable evacuation corridors under MEE grid-connected standards. |
Research Methodology
Desk research of IEC 60076-6 certification databases, FERC Order 2023 compliance filings, and EU F-Gas Regulation implementation timelines preceded structured interviews with transmission planning officers at State Grid Corporation of China and Power Grid Corporation of India, magnetics engineering specialists at German and Japanese heavy electrical equipment manufacturers, and procurement leads at TenneT and ČEPS. Secondary validation drew from CEA technical standard publications, MEE grid-connected reactive power mandates, and SAMR efficiency standard disclosures. Bottom-up equipment shipment tallies by voltage class and top-down utility capex allocation analysis were triangulated against EPC contractor order book visibility.
Variance decomposition across voltage tier, application segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from equipment procurement run-rates normalized against renewable integration targets and interstate transmission expansion schedules. Modeled inputs incorporated copper and grain-oriented electrical steel price elasticity assumptions, certification timeline distributions, and grid code convergence scenarios between Chinese GB standards and IEC frameworks.
Underlying assumptions cover sustained enforcement of MEE 50 MW dynamic compensation thresholds, EU F-Gas Regulation phase-out adherence, and Indian CEA interstate node mandates, with deviation risk concentrated in commodity price volatility for core materials and specialized magnetics engineering labor scarcity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.