
 United States Signal Generator Market | 2026-2036
United States Signal Generator Market Size, Share, and Industry Trends Forecast 2026-2036
United States Signal Generator Market Intelligence
Software-defined calibration subscriptions is restructuring how vendors monetize hardware platforms. Keysight Technologies Inc. leverages its extensive service network to lock in multi-year enterprise contracts. Rohde & Schwarz Gmbh & Co Kg anchors its position through deep R&D investment in mmWave testing. National Instruments Corporation differentiates by integrating signal generation with its LabVIEW software ecosystem.
A signal generator produces electrical waveforms with precisely controlled frequency, amplitude, and modulation characteristics, typically spanning audio through millimeter-wave bands for device validation and system characterization. RF signal generators and vector signal generators command the largest installed base, though software-defined architectures are displacing legacy analog platforms fastest. Microwave signal generators concentrate margin pools in defense and satellite communications, while pulse signal generators serve mature but steady demand from radar systems testing.
The FCC governs spectrum certification requirements that dictate generator bandwidth and purity specifications for commercial equipment testing. NIST traceability standards and DoD procurement regulations further constrain supplier qualification, creating barriers for non-domestic vendors in sensitive applications. Stakeholders must weigh capital deployment between benchtop hardware and cloud-orchestrated test flows as federal R&D priorities shift toward open-architecture systems.
Market Dynamics
Defense electronics procurement is expanding test equipment budgets across Pentagon R&D programs and prime contractor facilities, while FCC spectrum reallocation mandates force laboratories toward wider-bandwidth validation tools.
Growth Catalysts
- Defense Electronics Procurement:Pentagon R&D budgets and prime contractor test facilities are expanding capital equipment purchases for radar and electronic warfare system validation.
- FCC Spectrum Reallocation:Federal mandates for C-band and mmWave spectrum clearing push commercial laboratories toward higher-frequency signal generation capabilities.
- Semiconductor Design Corridors:California's integrated circuit design clusters and Texas aerospace engineering centers concentrate demand for precision waveform instrumentation.
Market Restraints
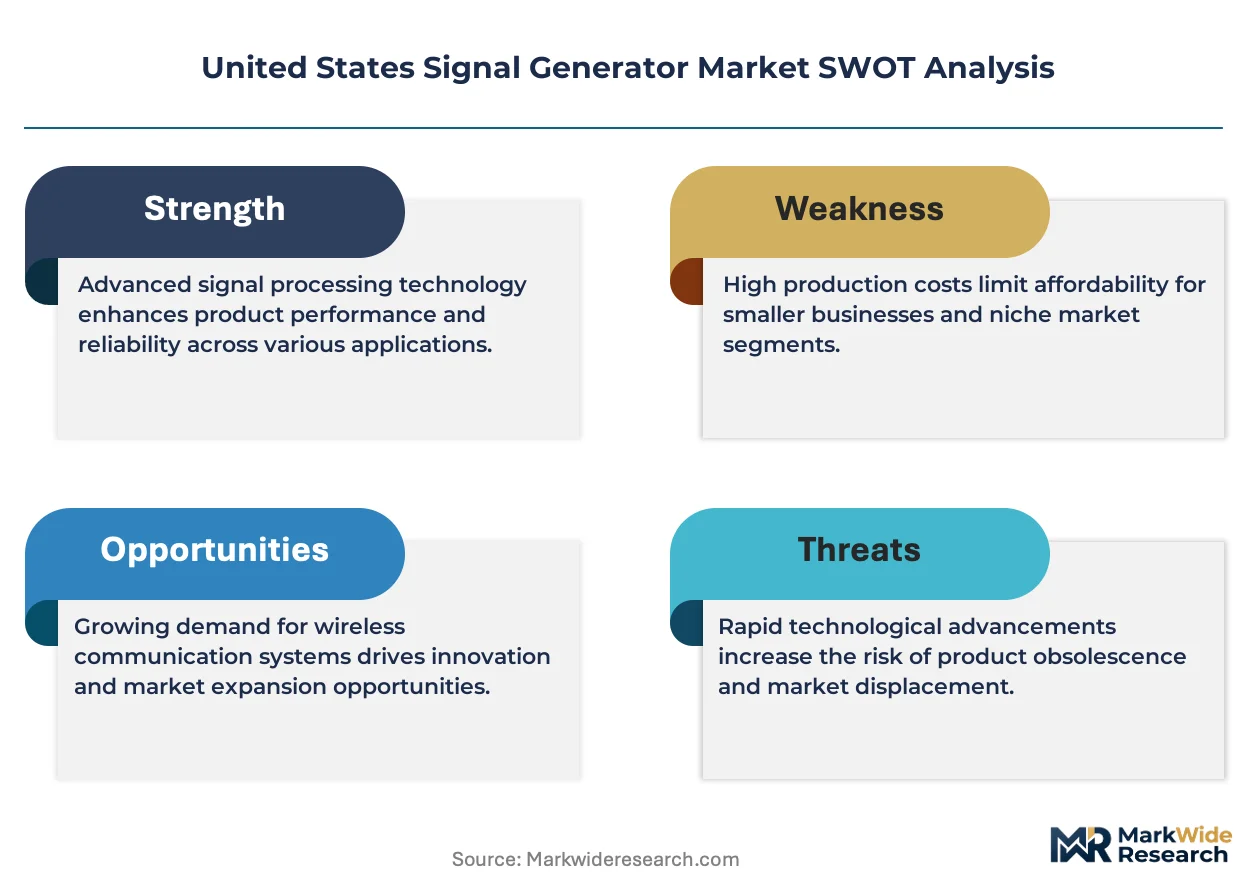
- Precision Component Supply Concentration:Specialized oscillator and synthesizer module production concentrates among a limited supplier base, creating single-source vulnerabilities.
- NIST Traceability Requirements:Federal calibration standards and DoD procurement regulations constrain vendor qualification, filtering non-domestic suppliers from sensitive applications.
- High-Frequency Test Fixture Costs:mmWave and sub-THz validation requires expensive anechoic chambers and probe stations that compound capital intensity.
Strategic Opportunities
- Open-Architecture Federal R&D Priorities:DoD directives toward modular, software-defined test systems create openings for non-traditional hardware-software bundles.
- Cloud-Orchestrated Test Flows:Remote instrument control and distributed measurement networks enable subscription-based service models beyond traditional capital sales.
- 5G-Advanced and 6G Research:University and national laboratory programs in Massachusetts and Colorado drive demand for ultra-wideband arbitrary waveform generation.
Industry Challenges
- RF Engineering Talent Scarcity:mmWave circuit design and electromagnetic simulation expertise pools concentrate among defense contractors and select research universities.
- Legacy Instrument Integration:Decades-old GPIB-controlled equipment in established test facilities complicates migration to Ethernet and USB-based instrument networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Signal Generator Market |
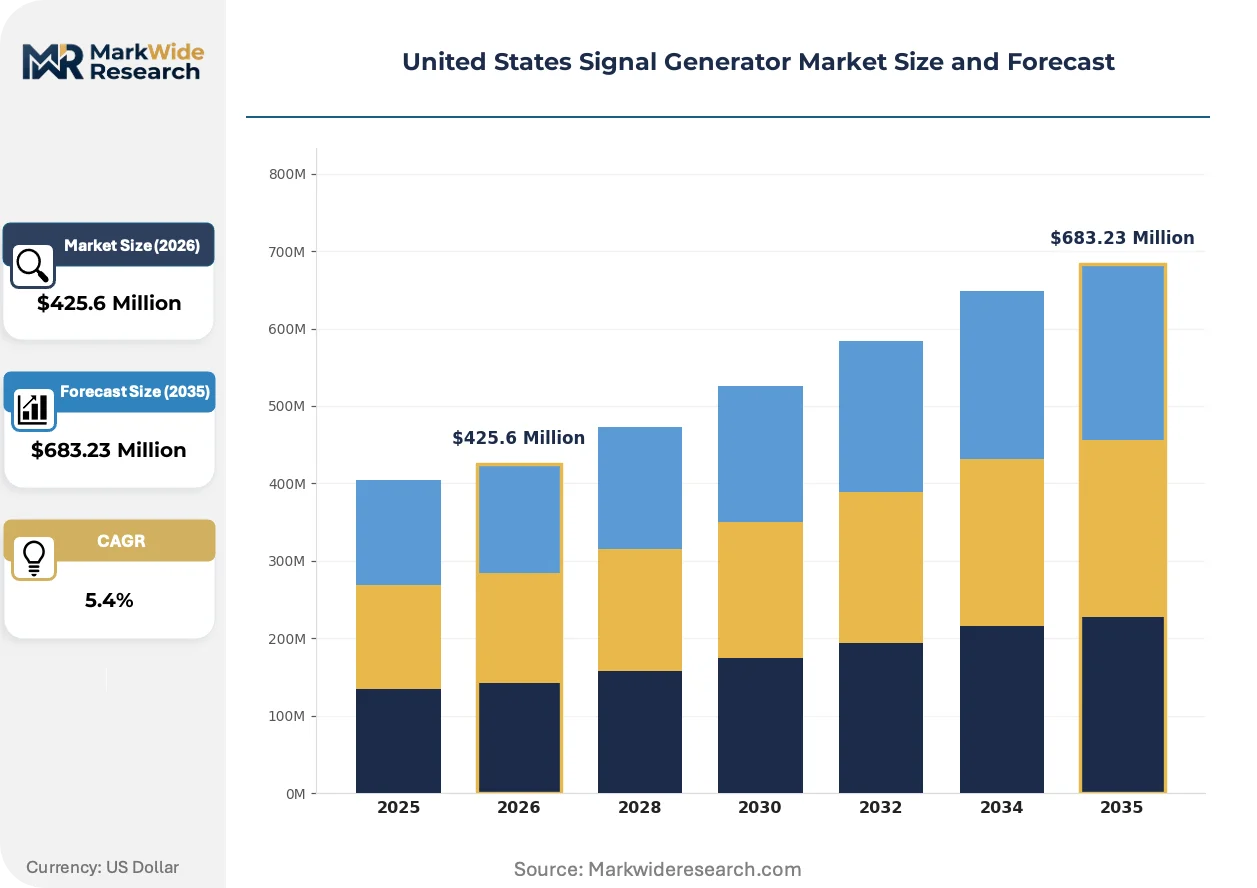
| Market Size in 2026 | $425.6 Million |
| Market Size in 2035 | $683.23 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vector Signal Generators, RF Signal Generators, Microwave Signal Generators, Pulse Signal Generators Deployment: On-premise, Cloud-based, Hybrid, Remote End User: Aerospace, Telecommunications, Automotive, Electronics Technology: Analog, Digital, Software-defined, Modular |
| Companies Covered | Keysight Technologies Inc., Rohde & Schwarz Gmbh & Co Kg, National Instruments Corporation, Anritsu Corporation, Tektronix Inc., Teledyne Technologies Incorporated, B&K Precision Corporation, Fluke Corporation, Keithley Instruments Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Signal Generator Market Strategic Shifts & Innovations
Software-defined architectures are restructuring how signal generation hardware is specified, procured, and monetized across defense, commercial, and academic laboratories.
Software-defined radio platforms with integrated FPGA-based waveform synthesis are decentralizing signal generation from dedicated benchtop boxes to modular PXIe and USB instruments. Defense contractors in Maryland and Arizona are adopting these architectures fastest for programmable threat simulation. This compression of hardware into reprogrammable substrates is decentralizing margin pools from traditional instrument vendors toward semiconductor and software suppliers.
FCC Part 15 and Part 27 certification requirements for unlicensed and licensed radio equipment are tightening spurious emission and spectral purity specifications. Test laboratories must now validate devices across broader instantaneous bandwidths than previous rule cycles mandated. California and Texas commercial labs are responding by upgrading to vector signal generators with integrated real-time modulation analysis.
Enterprise buyers are consolidating test equipment vendors to reduce calibration service fragmentation and spare parts complexity. Aerospace primes in Connecticut and Washington State are trimming approved supplier lists from dozens to single-digit strategic partnerships. This concentration is most visible in Department of Defense supply chains, where multi-year enterprise contracts now bundle hardware, software, and metrology services.
United States Signal Generator Market Segmentation
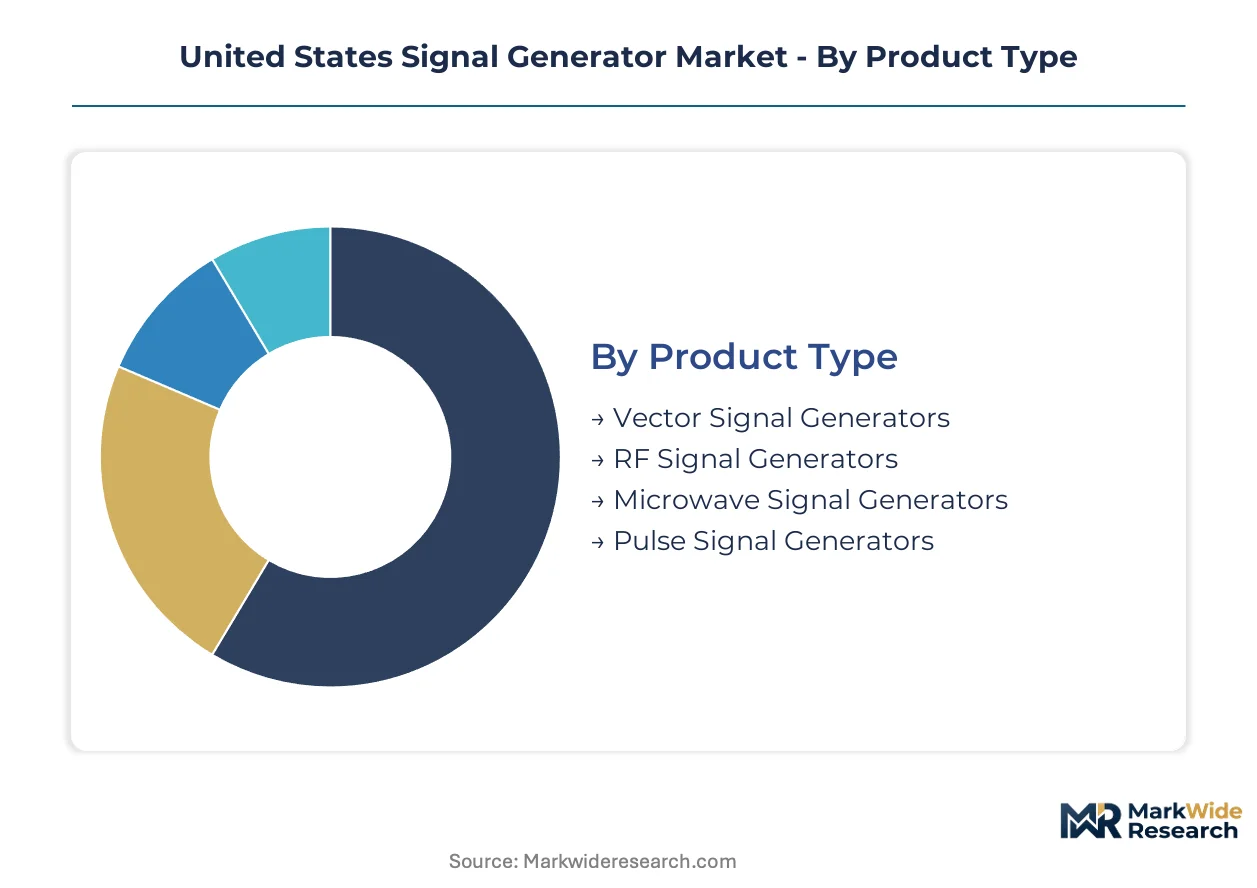
Signal generator procurement patterns diverge sharply across technical specifications, operational models, and end-use certification requirements. Each segmentation axis reveals distinct margin structures and vendor qualification barriers that shape competitive positioning in defense, commercial, and academic channels.
Product Type:
Frequency range and modulation complexity define the technical specification hierarchy, with bandwidth capabilities directly mapping to end-use qualification tiers and pricing bands.
- Vector Signal Generators:These instruments synthesize complex modulated waveforms with precise control over amplitude, phase, and frequency for wireless protocol validation. Demand concentrates in California's 5G baseband design labs and Massachusetts RFIC foundries, driven by FCC Part 27 certification requirements for C-band and mmWave equipment.
- RF Signal Generators:Continuous wave and basic modulation sources spanning sub-6 GHz bands serve the broadest installed base across commercial test floors. Texas aerospace clusters and Florida satellite communications facilities anchor procurement volumes, constrained by NIST traceability mandates for defense-adjacent contracts.
- Microwave Signal Generators:Millimeter-wave and sub-THz sources for radar cross-section and satellite payload testing.
- Pulse Signal Generators:Specialized instruments producing precisely timed pulse trains for radar system characterization.
RF signal generators lead on scale; vector signal generators lead on momentum.
Deployment:
Operational architecture choices reflect capital intensity preferences and workforce distribution across concentrated engineering hubs versus distributed test networks.
- On-premise:Traditional benchtop and rackmount installations in dedicated metrology laboratories with controlled environmental conditions. Defense contractors in Maryland and Arizona maintain these configurations for classified program requirements, though capital cycles stretch longer than commercial equivalents.
- Cloud-based:Browser-accessible instrument control with waveform libraries hosted on vendor-managed infrastructure. Emerging demand from Colorado and North Carolina university research consortia leverages subscription economics for intermittent high-bandwidth testing needs.
- Hybrid:Split architectures combining local signal synthesis with cloud-based analysis and calibration management.
- Remote:Full instrument virtualization enabling geographically distributed teams to share scarce high-frequency assets.
On-premise deployments retain the largest installed base; cloud-based configurations are climbing the fastest.
End User:
Application-specific certification regimes and procurement authorization levels create distinct customer segments with diverging vendor engagement models.
- Aerospace:Prime contractor test facilities and DoD depot maintenance operations requiring MIL-STD-461 and DO-160 environmental qualification. Connecticut and Washington State engineering centers concentrate demand, with procurement gated by Defense Federal Acquisition Regulation Supplement compliance.
- Telecommunications:Carrier labs and equipment manufacturer validation floors for cellular and Wi-Fi protocol conformance. California and Texas facilities drive refresh cycles tied to 3GPP release schedules and FCC equipment authorization timelines.
- Automotive:V2X and radar sensor validation for autonomous driving systems.
- Electronics:Broad consumer and industrial device manufacturing test floors.
Aerospace commands the highest specification premiums; telecommunications shows the steepest expansion trajectory.
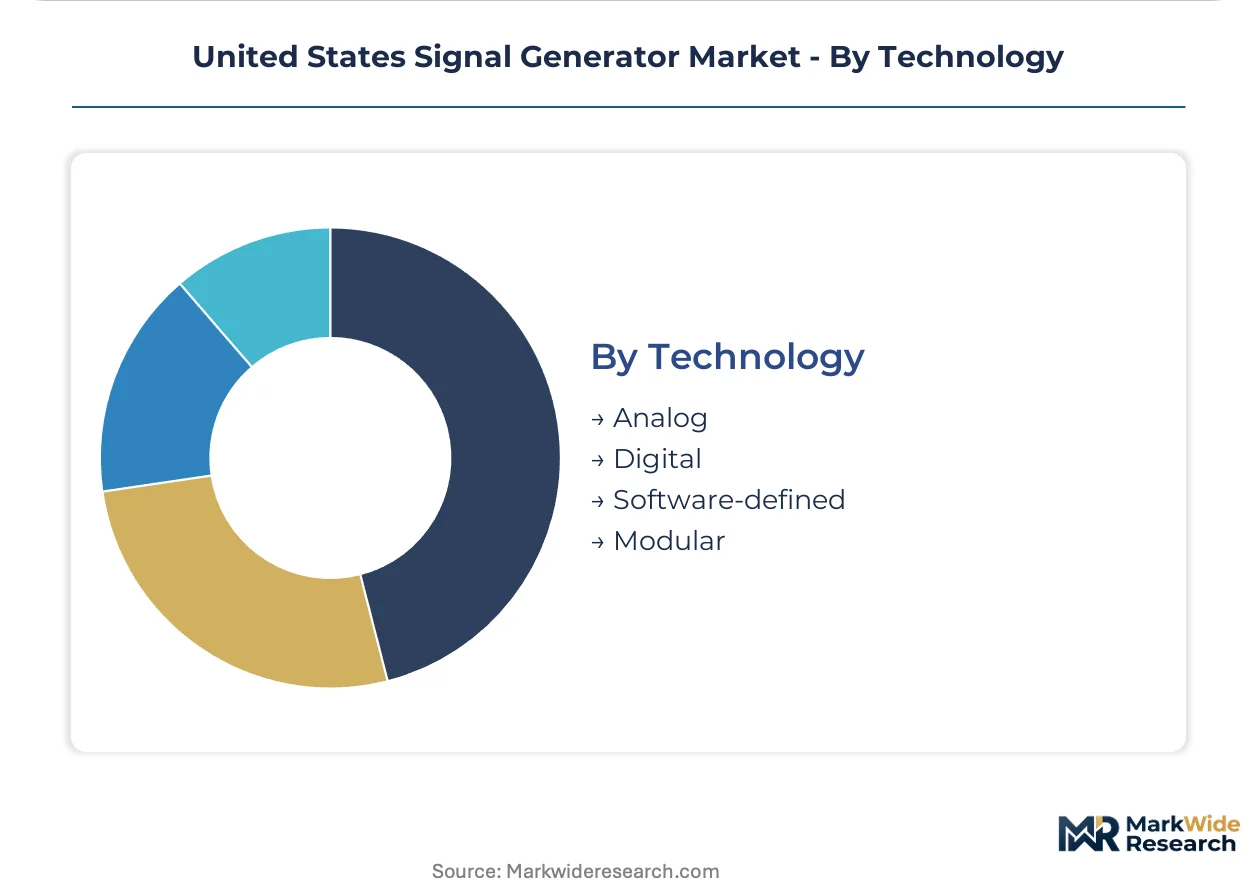
Technology:
Underlying synthesis architectures determine reprogrammability, upgrade paths, and the balance between hardware and software value capture.
- Software-defined:FPGA-based waveform synthesis with firmware-upgradable modulation formats and bandwidth extensions. Defense threat simulation programs in Arizona and Maryland prioritize these architectures for rapid reconfiguration between mission profiles.
- Modular:PXIe and USB instrument formats enabling chassis-based system integration with third-party modules. National laboratory procurement in Tennessee and New Mexico favors this approach for multi-instrument synchronization flexibility.
- Analog:Legacy direct analog synthesis and PLL-based architectures in established test facilities.
- Digital:DDS and AWG-based platforms with deterministic waveform sequencing.
Software-defined platforms are gaining share fastest; modular formats lead on deployment flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement intensity varies sharply across American states, with Pentagon R&D concentration driving equipment demand in coastal corridors while commercial test floors cluster around semiconductor design hubs.
California
5G baseband design labs and RFIC foundries in San Diego and Silicon Valley anchor vector signal generator procurement. FCC Part 27 certification mandates for C-band equipment push commercial laboratories toward higher-bandwidth validation platforms. San Jose and Irvine engineering centers concentrate demand for wireless protocol conformance testing.
Texas
Aerospace prime contractors in Dallas-Fort Worth and Houston drive RF signal generator volumes for satellite communications validation. NIST traceability requirements filter procurement toward qualified domestic vendors for defense-adjacent contracts. Austin semiconductor design clusters add commercial test floor demand alongside established aerospace engineering centers.
Maryland
Classified defense programs around Fort Meade and Aberdeen Proving Ground sustain on-premise benchtop installations for threat simulation applications. DoD procurement regulations constrain vendor qualification to domestic suppliers with established security clearances. Annapolis Junction and Columbia house concentrated electronic warfare system validation facilities.
Massachusetts
University and national laboratory programs in Cambridge and Lowell drive demand for ultra-wideband arbitrary waveform generation in 5G-Advanced and 6G research. Federal R&D funding through NSF and DARPA channels supports instrumentation upgrades at MIT Lincoln Laboratory and affiliated research consortia.
Arizona
Software-defined architectures penetrate fastest here for programmable threat simulation across defense contractor facilities in Tucson and Phoenix. Raytheon and Northrop Grumman operations prioritize FPGA-based waveform synthesis for rapid reconfiguration between mission profiles. Yuma Proving Ground adds military-specific pulse signal generator requirements for radar cross-section testing.
United States Signal Generator Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with full-line instrument vendors commanding enterprise accounts while modular specialists capture research laboratory niches. The vendor base concentrates among three tiers: premium-tier full-platform providers, mid-tier modular specialists, and value-tier calibration service bundlers. Two strategic archetypes dominate—those anchoring position through multi-year enterprise service contracts, and those penetrating through software-integrated hardware ecosystems. Consolidation pressure manifests through approved supplier list trimming at aerospace primes and multi-year bundled contract awards at defense agencies.
Within the premium-tier full-platform segment, Keysight Technologies Inc. and Rohde & Schwarz GmbH & Co. Kg occupy positions defined by extensive service networks and deep R&D investment respectively. National Instruments Corporation exemplifies the software-integrated archetype through its LabVIEW ecosystem anchoring. These three entities represent contrasting competitive postures—service-locked enterprise penetration, hardware performance leadership, and platform ecosystem binding—each capturing distinct procurement authorization levels across defense, commercial, and academic channels.
| Leading Market Players |
|---|
| Keysight Technologies Inc. |
| Rohde & Schwarz Gmbh & Co Kg |
| National Instruments Corporation |
| Anritsu Corporation |
| Tektronix Inc. |
| Teledyne Technologies Incorporated |
| B&K Precision Corporation |
| Fluke Corporation |
| Keithley Instruments Inc. |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up calibration service specialists concentrate ownership of aftermarket revenue streams, anchoring pricing discipline through multi-year enterprise contracts that bundle hardware, software, and metrology services into sticky subscription economics.
Pricing Analysis
Capacity additions in Malaysia and Vietnam are reshaping price floors for RF component substrates, compressing margins on entry-level signal generators while premium-tier vector instruments retain pricing power through NIST-traceable calibration bundling. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified instruments with MIL-STD-461 certification from commercial test floor units and academic laboratory configurations. Price differentiation hinges on bandwidth ceiling and modulation complexity, with defense contractors showing lowest price sensitivity due to procurement authorization tied to program-critical validation requirements.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific semiconductor hubs elevates landed costs for FPGA and high-speed DAC modules that feed software-defined architectures. Manufacturing concentrates in Taiwan for advanced synthesizer chips, Germany for precision oscillator assemblies, and domestic US facilities for defense-qualified final integration. Specialized YIG sphere and sapphire substrate dependencies create single-source vulnerabilities at key tier-two suppliers. Distribution runs through authorized channel partners with calibration service capabilities, bypassing commodity electronics distributors for high-frequency instrumentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Signal Generator Market functions as a regulatory compounder, with FCC spectrum reallocation mandates and DoD open-architecture directives continuously refreshing equipment replacement cycles across defense and commercial laboratories.
For Market Incumbents: To counter modular PXIe specialists encroaching from research laboratory niches, anchor enterprise accounts through multi-year calibration service contracts with guaranteed uptime SLAs, and deepen backward integration into FPGA firmware development to accelerate waveform protocol updates ahead of 3GPP release schedules. For New Entrants and Emerging Players: FCC Part 27 certification requirements for C-band equipment open a window for cloud-orchestrated test flow platforms targeting Colorado and North Carolina university consortia with intermittent high-bandwidth needs, using subscription economics to bypass capital-intensive benchtop competition. For Investors and Strategic Acquirers: Valuations sit cheapest among modular instrument specialists with software-defined architectures but limited service infrastructure, offering platform tuck-in opportunities for premium-tier vendors seeking LabVIEW-equivalent ecosystem binding; watch DARPA and NSF instrumentation grant award velocity as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Bundling | Locks multi-year revenue streams at Keysight and Rohde & Schwarz through NIST-traceable metrology contracts. |
| Software-Defined Architecture Migration | Enables FPGA-based threat simulation reconfiguration for Arizona defense contractor rapid mission profile switching. |
| Cloud-Orchestrated Test Platform Launch | Captures intermittent high-bandwidth demand from Massachusetts and Colorado 6G research consortia via subscription. |
| RF Engineering Talent Acquisition | Addresses mmWave circuit design scarcity concentrated at MIT Lincoln Laboratory and select defense contractors. |
| Open-Architecture Certification Investment | Qualifies vendors for DoD modular test system directives filtering procurement toward non-traditional hardware-software bundles. |
Research Approach
Coverage spans California semiconductor design corridors, Texas aerospace clusters, Maryland defense facilities, and Massachusetts research consortia, with primary inputs from each region triangulated against secondary validation. Primary fieldwork engaged RF test engineers at prime contractors, procurement officers at national laboratories, calibration service managers, and university research facility directors. Secondary sources included FCC equipment authorization databases, DoD R&D budget justification documents, NIST calibration standard filings, and SEC 10-K disclosures from listed instrument vendors. Bottom-up equipment shipment estimates and top-down defense electronics procurement analysis were cross-referenced for convergence.
Rate-of-change decomposition segmented growth across vector versus RF signal generator architectures, on-premise versus cloud deployment models, and aerospace versus telecommunications end-use applications throughout the forecast period. CAGRs were derived from instrument replacement cycle analysis, spectrum reallocation timeline modeling, and federal R&D appropriation trajectory assessment. Modeled inputs included 5G-Advanced protocol release schedules, mmWave certification mandate phasing, and open-architecture test system adoption curves at defense agencies.
Revisions become necessary when FCC spectrum auction timelines shift, DoD procurement regulations tighten domestic content requirements, or semiconductor supply disruptions extend lead times for specialized synthesizer modules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Density Tester Market
Test and Measurement
Slovakia and Czech Republic Calibration Services Market
Test and Measurement
Automated Test Equipment Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
Metrology Software Market
Test and Measurement
Stability Test Chamber Market
Test and Measurement
Permeability Testing Machine Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Capacitance Meter Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
Battery Resistance Tester Market
Test and Measurement
Digital Battery Internal Resistance Tester Market
Test and Measurement
Sound Level Meter Market
Test and Measurement
Ethernet Test Equipment Market