
 Digital Inverter Market | 2026-2036
Digital Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Inverter Market Analysis
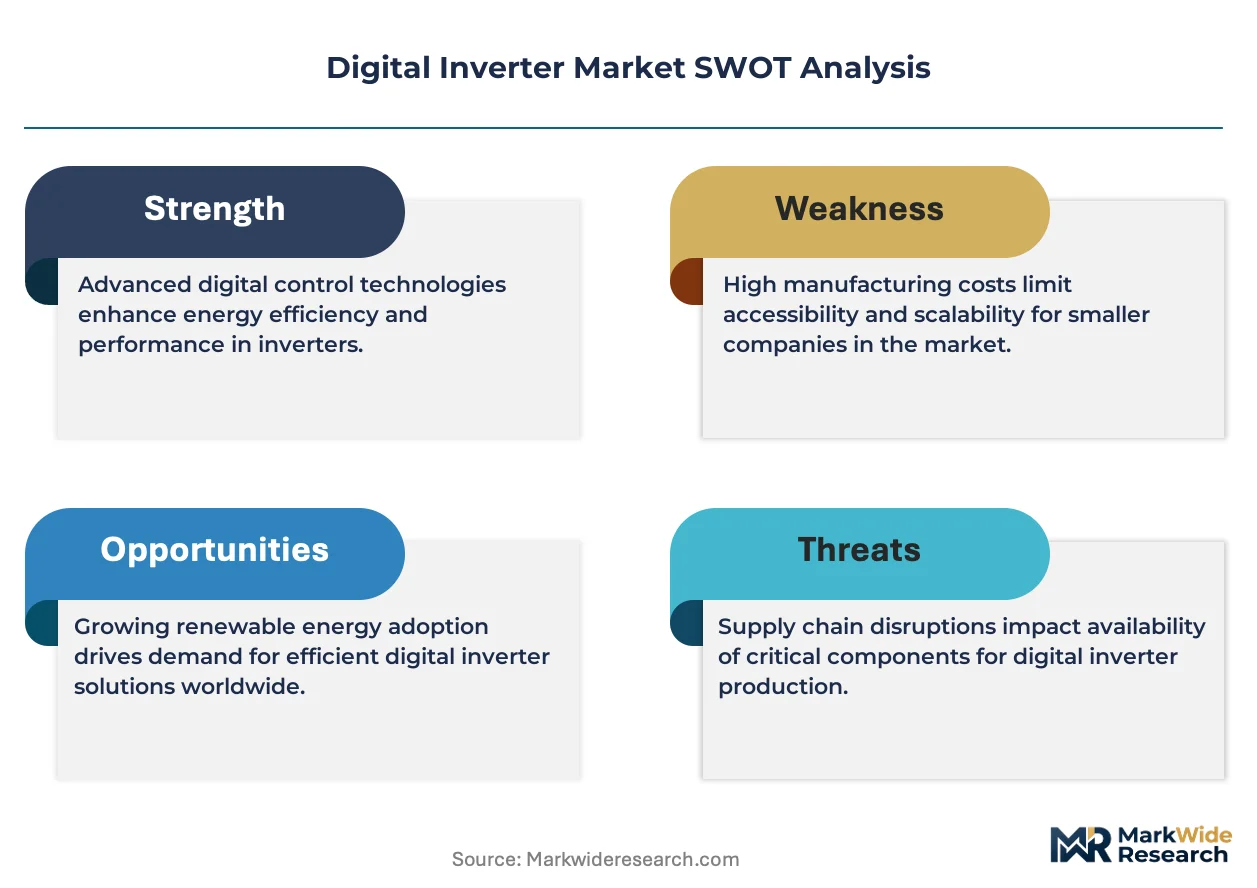
A capital-intensity divergence between integrated semiconductor foundries and pure-play assembly houses is collapsing as foundries move downstream into module packaging. Huawei Technologies Co., Ltd. leverages captive silicon design capabilities to control inverter core architecture. SMA Solar Technology AG anchors its position through deep European service networks and grid-code expertise. Schneider Electric SE differentiates via building-automation integration that extends beyond power conversion into energy management software.
A digital inverter is a power electronic device that converts direct current from solar panels or batteries into alternating current using high-frequency switching controlled by digital signal processors, typically operating at efficiencies above 98% in utility-scale units. Its primary commercial purpose is enabling grid-interactive renewable energy systems with precise voltage and frequency synchronization. Grid-tie inverters dominate volume due to distributed solar mandates, while micro inverters capture premium residential margins where module-level monitoring justifies higher unit costs. Off-grid inverters remain structurally constrained by battery cost curves but serve critical backup applications where grid reliability fails.
China's MIIT enforces GB/T 37408 standards for grid-connected inverter efficiency and electromagnetic compatibility, while the EU F-Gas Regulation and Ecodesign directives push thermal management redesigns that reshape semiconductor packaging choices. India's CEA mandates centralized inverter testing at designated labs, creating market access friction for non-local certifications. Stakeholders must monitor evolving grid-code harmonization between IEC and IEEE frameworks, as divergent ride-through requirements threaten product platform standardization and regional compliance costs.
Market Dynamics
Silicon carbide power semiconductors are collapsing thermal management costs while GB/T 37408 and IEEE 1547 tighten efficiency mandates, forcing simultaneous performance upgrades and certification redesigns across product portfolios.
Growth Catalysts
- Utility-scale solar deployment:China's MIIT renewable targets and state-backed project pipelines are pulling demand for megawatt-class string inverters with 1500V DC architecture.
- Grid-code harmonization:IEC 62109-2 safety standards are converging with UL 1741-SA, reducing duplicate certification burdens for multi-region suppliers.
- Building-automation integration:Schneider Electric's energy management software stacks are demonstrating inverter-to-HVAC data interoperability that unlocks commercial retrofit budgets.
Market Restraints
- IGBT supply concentration:Japanese and German power module foundries control 70% of high-voltage switching capacity, creating input bottlenecks during demand spikes.
- F-Gas thermal regulation:The EU F-Gas Regulation is banning conventional refrigerants in liquid-cooled inverters above 250kW, forcing costly heat sink redesigns.
- Electrolytic capacitor lifespans:Aluminum electrolytic components degrade below 80% rated capacity within 10-12 years in desert climates, constraining warranty economics.
Strategic Opportunities
- India's CEA lab mandate:Centralized testing requirements create first-mover advantages for suppliers establishing Bengaluru or Pune certification partnerships.
- Vehicle-to-grid convergence:Bidirectional charging standards ISO 15118-20 are enabling residential inverters to arbitrage EV battery capacity against peak tariffs.
- Micro inverter residential penetration:Module-level monitoring justifies premium pricing in California NEM 3.0 markets where production visibility determines payback calculations.
Industry Challenges
- DSP firmware talent scarcity:Grid-synchronization algorithms require specialized power electronics programmers, with European and Chinese employers competing for limited pools.
- Ride-through test complexity:IEEE 1547-2018 low-voltage ride-through validation demands multi-megawatt grid simulators that extend certification timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Inverter Market |
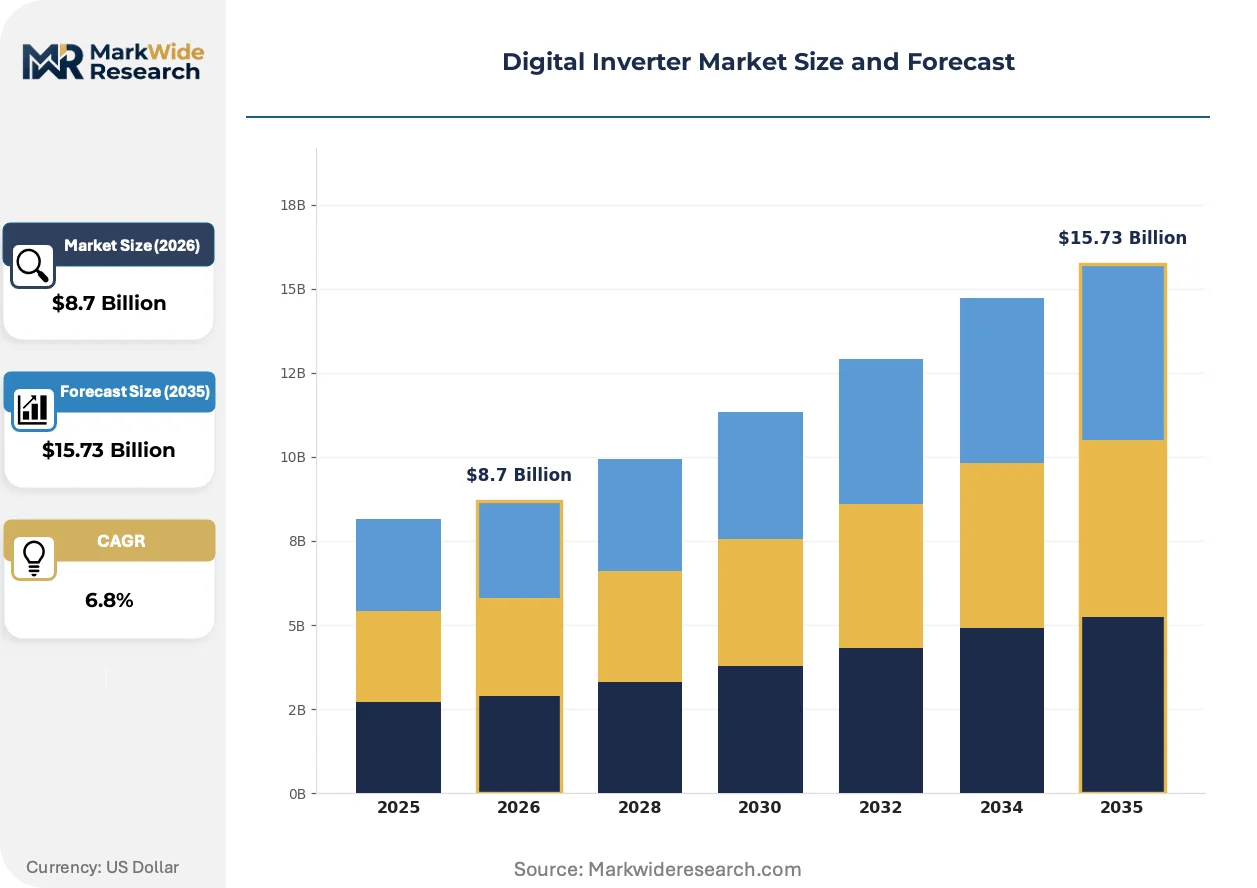
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Inverters, Grid-Tie Inverters, Off-Grid Inverters, Micro Inverters End User: Residential, Commercial, Industrial, Utility Scale Functionality: Voltage Regulation, Frequency Conversion, Battery Management, Power Factor Correction Technology: PWM, MPPT, Sine Wave, Modified Sine Wave |
| Companies Covered | Huawei Technologies Co., Ltd., Sungrow Power Supply Co., Ltd., SMA Solar Technology AG, Schneider Electric SE, ABB Ltd., Siemens AG, Enphase Energy, Inc., Delta Electronics, Inc., Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Inverter Market Emerging Trajectories
Power semiconductor architecture is fragmenting into competing material platforms while digital control firmware absorbs functions previously handled by discrete analog circuits.
Silicon carbide MOSFETs are decomposing the cost premium between string and central inverter topologies by enabling 99% efficiency at switching frequencies above 50kHz. Chinese and European utility-scale developers are specifying SiC-based 250kW string units for 500MW+ solar farms previously reserved for central station designs. This compression is collapsing the historical 15-20% capex gap between distributed and centralized architectures.
The EU F-Gas Regulation is prohibiting hydrofluorocarbon refrigerants in thermal management systems above 100kW rated capacity from 2027. Inverter OEMs are redesigning liquid-cooled platforms around dielectric fluid loops and phase-change materials. European commercial and industrial segments face the steepest compliance cost curves, with German TÜV certification timelines extending 8-10 months for redesigned thermal stacks.
Buyer procurement patterns are consolidating around integrated EPC-inverter service contracts that bundle installation, commissioning, and 20-year performance guarantees. This bundling is displacing component-only purchasing in US utility-scale solar, where project finance requirements favor single-point accountability. The shift is most pronounced in Texas and California ISO markets, where merchant solar developers prioritize bankable warranties over unit cost minimization.
Digital Inverter Market Segmentation
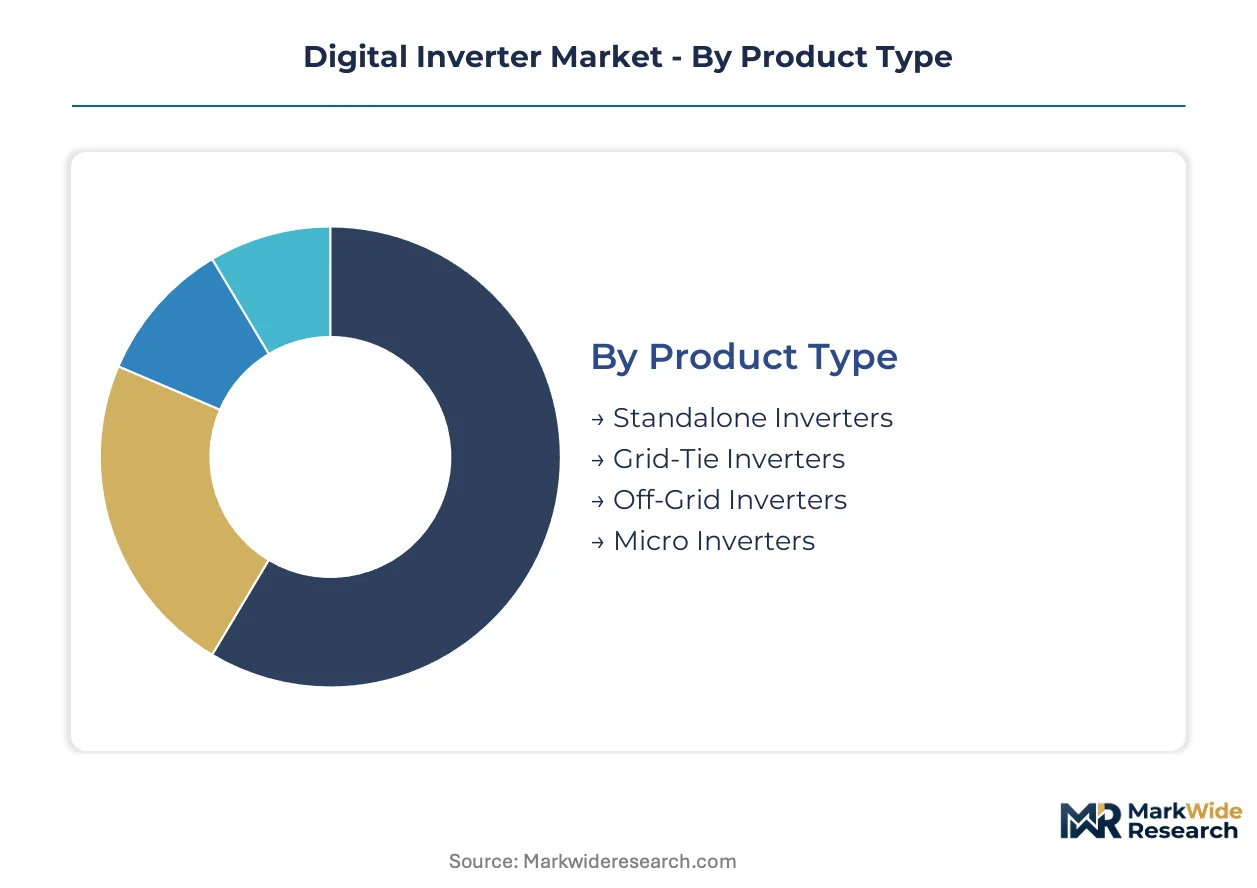
Segmentation in digital inverters reveals how technical specifications, application environments, and grid-interconnection requirements fragment purchasing criteria across customer types. Product architecture choices directly determine certification pathways, thermal management costs, and software integration depth.
Product Type:
Grid-tie inverters face intensifying substitution pressure from module-level electronics as residential buyers prioritize monitoring granularity over central inverter economics.
- Grid-Tie Inverters:Synchronize DC-to-AC conversion with utility frequency and voltage through DSP-controlled IGBT bridges, achieving above 98% efficiency in 1500V utility-scale units. Demand concentrates in Chinese state-backed solar farms where MIIT renewable targets mandate megawatt-class string architectures with centralized grid management.
- Micro Inverters:Perform panel-level DC-to-AC conversion eliminating string mismatch losses while enabling per-module monitoring through powerline communication. California NEM 3.0 markets absorb premium pricing where production visibility directly determines residential payback calculations and interconnection approval timelines.
- Standalone Inverters:Island-mode operation for backup power applications without grid-synchronization requirements.
- Off-Grid Inverters:Battery-coupled designs serving remote installations where grid extension proves economically unviable.
Grid-tie inverters anchor the volume base while micro inverters gain share at the steepest rate.
End User:
Cost tier stratification separates warranty-backed utility procurement from price-sensitive residential self-consumption markets.
- Utility Scale:Megawatt-class installations specifying 1500V DC string inverters with 20-year performance guarantees and single-point EPC accountability. Texas and California ISO markets prioritize bankable warranties from integrated service contracts over unit cost minimization in project finance structures.
- Industrial:C&I rooftop and ground-mount systems requiring building-automation integration and demand-charge optimization through energy management software stacks.
- Residential:Single-phase and split-phase units for behind-the-meter solar and storage pairing.
- Commercial:Three-phase commercial rooftop systems with standard 5-10 year warranty terms.
Utility scale commands the revenue concentration while residential applications expand most quickly behind distributed solar mandates.
Functionality:
Application maturity varies sharply across power quality functions versus emerging battery-interaction capabilities.
- MPPT:Maximum power point tracking algorithms continuously adjust operating voltage to extract peak panel output across irradiance and temperature variation.
- Battery Management:Bidirectional power flow control enabling DC-coupled storage arbitrage against time-of-use tariffs and ISO 15118-20 vehicle-to-grid convergence.
- Voltage Regulation:Reactive power injection and volt-var control for distribution grid stability compliance.
- Power Factor Correction:Capacitive and inductive compensation for industrial load power quality.
Voltage regulation provides the installed base foundation while battery management functionality climbs the fastest as storage attachment rates accelerate.
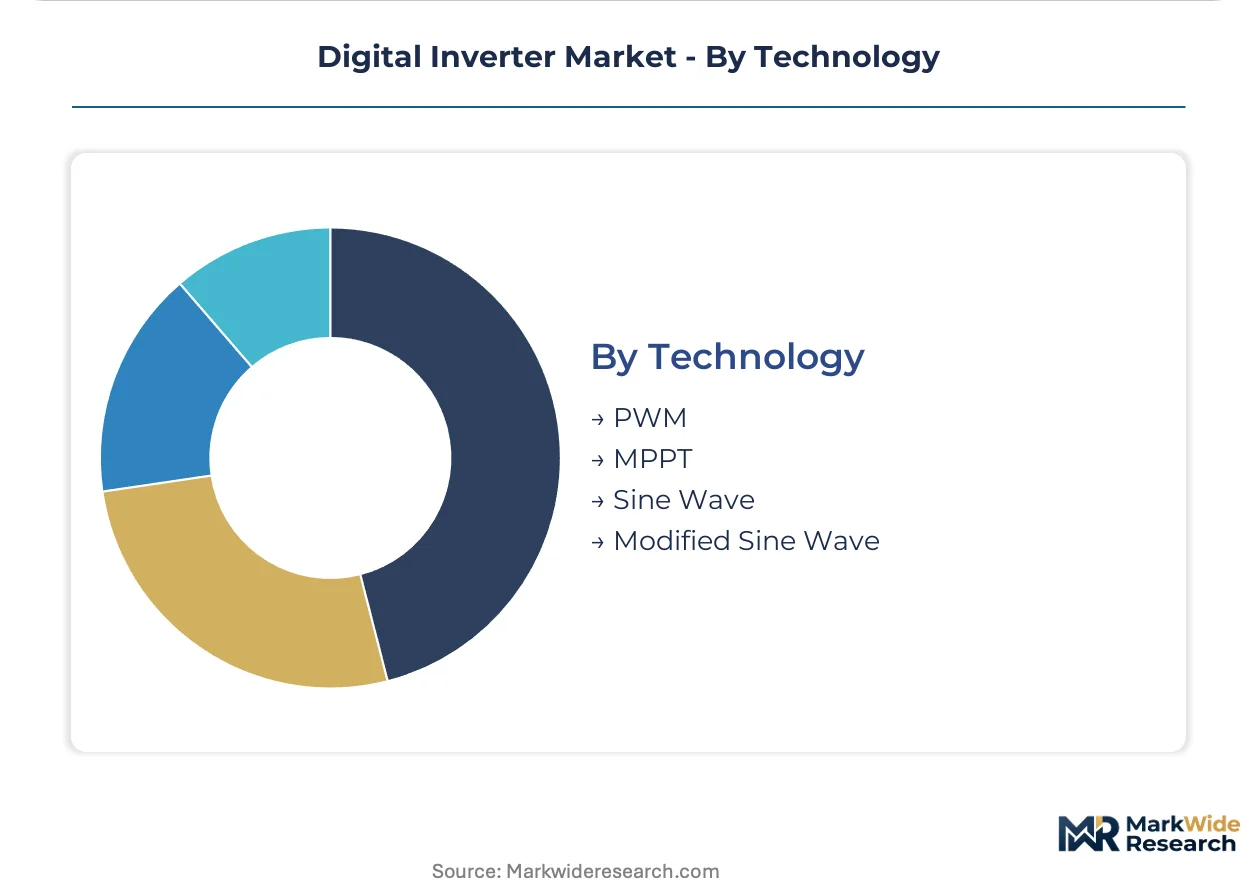
Technology:
Silicon carbide MOSFET adoption is collapsing the performance gap between competing waveform generation approaches.
- Sine Wave:Pure sinusoidal output matching utility waveform quality for sensitive electronics and grid-code compliance.
- MPPT:Algorithmic harvesting optimization now standard across all product tiers.
- PWM:Pulse-width modulation for cost-optimized applications with reduced waveform fidelity requirements.
- Modified Sine Wave:Stepped approximation for basic resistive loads in off-grid budget segments.
Sine wave technology dominates premium positioning while MPPT penetration approaches universality across all price tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes digital inverters through state-backed utility pipelines, while the United States and Germany prioritize residential micro-inverter granularity and building-automation integration respectively.
China
MIIT renewable energy targets pull megawatt-class string inverter demand through state-owned solar farm pipelines. GB/T 37408 standards enforce grid-connected efficiency and electromagnetic compatibility thresholds. Ningbo and Shenzhen industrial clusters concentrate inverter assembly capacity serving domestic utility-scale deployments.
United States
Texas and California ISO markets absorb integrated EPC-inverter service contracts with 20-year performance guarantees. FERC Order 2222 enables distributed energy resource aggregation that expands residential inverter functionality requirements. Arizona and Nevada desert installations stress electrolytic capacitor thermal management design.
Germany
EU F-Gas Regulation mandates refrigerant-free thermal management redesigns for liquid-cooled units above 250kW. TÜV certification timelines extend 8-10 months for phase-change material heat sink validation. Bavaria and North Rhine-Westphalia host inverter service networks anchoring European grid-code expertise.
India
CEA centralized testing mandates at designated Bengaluru and Pune labs create market access friction for non-local certifications. State-level renewable purchase obligations accelerate utility-scale solar procurement. Gujarat and Rajasthan solar parks specify 1500V DC string architectures for gigawatt-scale installations.
Japan
METI feed-in tariff revisions shift residential solar economics toward self-consumption and storage pairing. JIS standards govern grid-interconnection safety for earthquake-resilient installations. Kyushu and Chubu regional utilities enforce strict voltage ride-through requirements that extend product qualification cycles.
Digital Inverter Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across technology platforms and service models. Foundry-backed players control captive silicon supply chains while pure-play assemblers compete on certification speed and regional service density. Two archetypes dominate: vertically integrated semiconductor-inverter houses and grid-code specialists with deep utility relationships. Competitive moves concentrate on SiC semiconductor sourcing partnerships and 20-year performance guarantee bundling with EPC contractors.
Among Asian integrated electronics groups, Huawei Technologies Co., Ltd., Sungrow Power Supply Co., Ltd., and Delta Electronics, Inc. occupy positions that exemplify foundry-to-inverter supply chain control. SMA Solar Technology AG and Schneider Electric SE represent the European archetype of grid-code and building-automation specialization. These five names anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Sungrow Power Supply Co., Ltd. |
| SMA Solar Technology AG |
| Schneider Electric SE |
| ABB Ltd. |
| Siemens AG |
| Enphase Energy, Inc. |
| Delta Electronics, Inc. |
| Eaton Corporation |
| Others |
Supply Flow & Price Mechanics
Foundry-scale silicon carbide wafer production in Ningbo and Shenzhen clusters compresses unit economics for 1500V string inverters while simultaneously concentrating supply leverage among captive semiconductor houses. This scale dynamic anchors price floors for non-integrated assemblers who must absorb IGBT module premiums during demand spikes.
Pricing Analysis
After-sales service contracts spanning 20-year performance guarantees now drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates integrated EPC-inverter bundles from component-only transactions, with certification grade and volume scale as primary differentiation drivers. Cost compression in utility-scale tiers intensifies as Chinese state-backed pipelines force competitive bidding. Residential micro-inverter buyers show least price sensitivity where module-level monitoring justifies premium positioning.
Supply Chain Analysis
Strategic stockpiling of silicon carbide substrates and electrolytic capacitors dominates inventory strategy as lead times for Japanese and German power modules extend during demand surges. Manufacturing concentrates in China, Germany, and Japan, with raw material dependencies spanning high-purity silicon wafers, aluminum electrolytic components, and rare-earth magnetic materials. Single-source vulnerability in IGBT foundry capacity threatens output continuity. Distribution runs through integrated EPC contractors who bundle installation and commissioning with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital inverter markets are approaching a platform-economics inflection where ISO 15118-20 bidirectional charging standards enable residential units to arbitrage EV battery capacity, collapsing the boundary between power conversion and distributed energy resource aggregation.
For Market Incumbents: Compound grid-code expertise into adjacent energy management software stacks before building-automation specialists capture inverter-to-HVAC data interoperability. Deepen captive silicon carbide sourcing partnerships to defend against pure-play foundry supply bottlenecks. Prioritize 20-year performance guarantee bundling with EPC contractors to lock out component-only competitors in Texas and California ISO markets. For New Entrants and Emerging Players: Lead with vehicle-to-grid convergence applications where bidirectional standards create certification-first-mover advantages against legacy unidirectional portfolios. Target India's CEA lab mandate friction by establishing Bengaluru or Pune certification partnerships before centralized testing requirements harden. Pursue micro-inverter residential penetration in California NEM 3.0 markets where production visibility economics favor new software-centric entrants. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated EPC-inverter service providers with 20-year performance guarantee books. Long-term viability over the next decade rests on semiconductor supply chain control and grid-code harmonization agility. Acquisition focus should center on mid-cap specialists with captive SiC sourcing and deep European or Asian utility relationships. Watch for IEEE 1547-2018 ride-through certification backlog as inflection indicator—suppliers with validated multi-megawatt grid simulator access will capture disproportionate utility-scale share.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Captive SiC wafer supply secures 99% efficiency positioning against IGBT-dependent competitors. |
| 20-Year Performance Guarantee Bundling | Single-point EPC accountability meets project finance requirements in merchant solar development. |
| CEA Lab Certification Pre-Positioning | Bengaluru and Pune partnerships create market access before India's centralized testing mandate tightens. |
| ISO 15118-20 Bidirectional Integration | Vehicle-to-grid capability unlocks residential battery arbitrage against time-of-use tariffs. |
| Phase-Change Thermal Management Redesign | F-Gas compliance for liquid-cooled units above 250kW preserves European market participation. |
Methodological Framework
The analysis maps grid-tie, micro-inverter, and off-grid product architectures, each validated through utility procurement officers, EPC project developers, inverter firmware engineers, and grid interconnection specialists. Primary fieldwork combined with secondary validation from IEC 62109 certification databases, IEEE 1547 compliance filings, MIIT renewable target disclosures, and customs trade data enables bottom-up and top-down triangulation.
Consistency checks against EIA solar deployment statistics and IEA renewable capacity additions validate volume and value outputs across the projection horizon. Segmentation dimensions span product type, end-user scale tier, functionality module, and semiconductor technology platform. CAGRs derive from installed base evolution and replacement cycle modeling, with SiC adoption curves and F-Gas compliance timelines as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules, China's MIIT renewable targets, and India's CEA testing mandates; material policy shifts would require re-modeling. Specific risks include IGBT supply concentration disruptions, electrolytic capacitor degradation in desert climates, and divergent IEEE-IEC ride-through standardization. Revision becomes warranted when SiC cost parity thresholds cross central-to-string inverter substitution inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Automotive Power Semiconductor Market
Power Systems
North America Micro Inverter Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Batteries for Semiconductor Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
AC DC Power Adapter Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Charge Controller System Market
Power Systems
Silicon Carbide Power Devices Market
Power Systems
Global Synchronous Motor Market
Power Systems
Shunt Voltage References Market
Power Systems
AC Voltage Transducer Market
Power Systems
Flyback Transformer Market
Power Systems
EV Power Module Market