
 Asia Pacific Low Voltage Drives Market | 2026-2036
Asia Pacific Low Voltage Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Low Voltage Drives Market Analysis
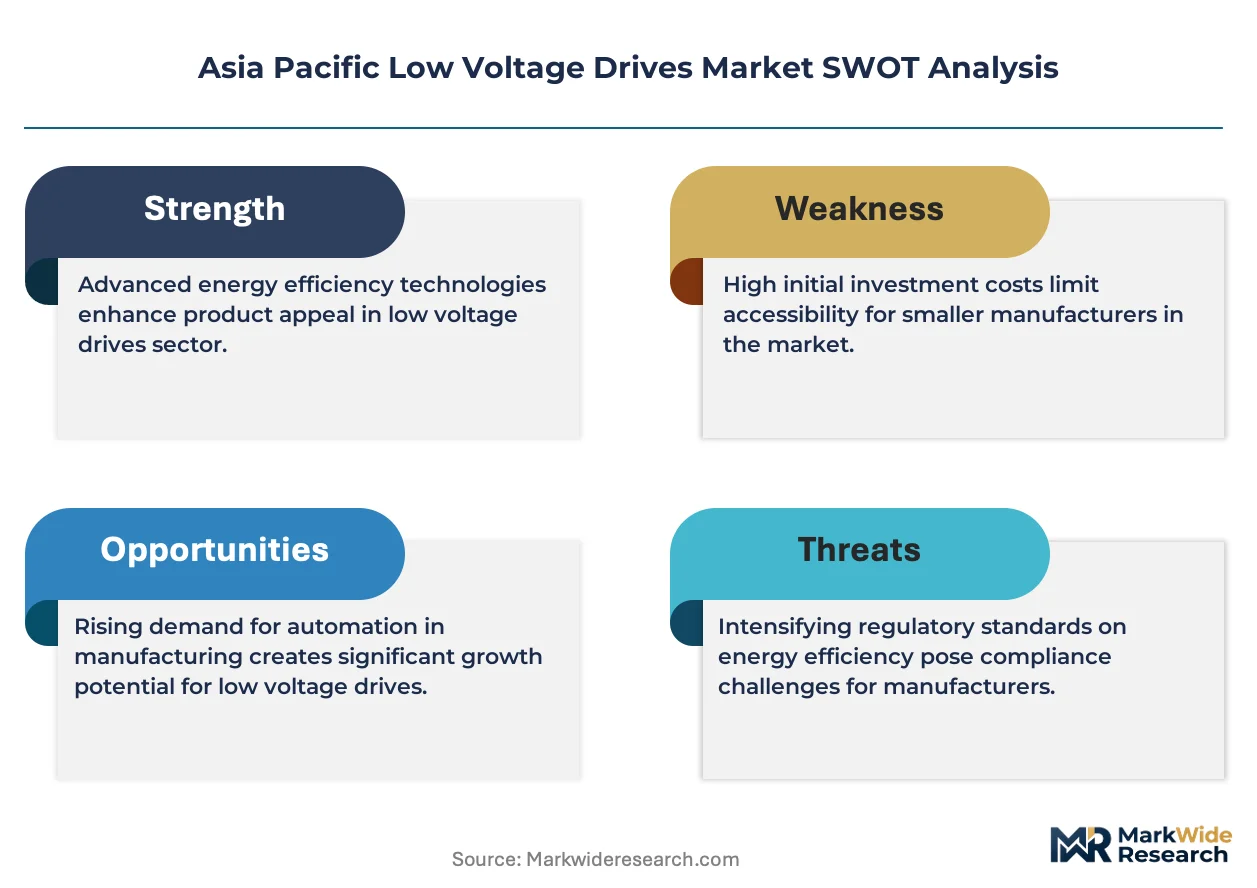
Silicon carbide is recalibrating power module economics across low voltage drives, trimming switching losses and enabling smaller thermal packages. Mitsubishi Electric leverages captive SiC wafer capacity to anchor premium servo drive lines. Siemens competes through its TIA portal ecosystem, extending software-defined control across factory networks. ABB dominates water treatment and HVAC retrofit channels with standardized wall-mount platforms.
Asia Pacific low voltage drives are electromechanical systems that modulate motor speed and torque through adjustable frequency and voltage, typically operating below 690 volts to optimize pump, fan, and conveyor performance. AC drives and VFDs lead volume shipments across the region, while servo drives command concentrated margin pools in precision manufacturing. Direct torque control technology is displacing conventional V/Hz methods in high-inertia applications across Korean and Japanese automotive supply chains.
China's GB/T energy efficiency standards, India's BIS certification regime, and Japan's METI Top Runner program collectively tighten motor system compliance thresholds and accelerate replacement cycles. Australia's MEPS requirements and South Korea's MFDS-adjacent industrial safety rules further fragment certification pathways for multinational suppliers. Stakeholders must monitor evolving efficiency tier migrations and localize test facilities to avoid extended approval timelines.
Market Dynamics
Silicon carbide power modules are compressing thermal management costs across Asia Pacific low voltage drives, forcing incumbent IGBT suppliers to reprice or cede share in high-frequency applications. This material transition is the dominant structural force reshaping competitive economics.
Growth Catalysts
- China's GB/T energy efficiency standards:Tightening motor efficiency tiers are accelerating replacement cycles in Shanghai and Pearl River Delta manufacturing clusters.
- Servo drive demand from precision manufacturing:Korean and Japanese automotive supply chains are deploying direct torque control systems for high-inertia applications.
- India's BIS certification regime:Mandatory efficiency labeling is channeling procurement toward certified vendors in Gujarat and Maharashtra industrial corridors.
Market Restraints
- SiC wafer supply concentration:Japanese and Korean substrate manufacturers control critical feedstock, creating input cost volatility for power module assemblers.
- Fragmented certification pathways:Australia's MEPS requirements diverge from South Korea's MFDS-adjacent safety rules, extending approval timelines for multinational suppliers.
- Technical limitation in legacy motor compatibility:Older squirrel-cage induction motors cannot exploit advanced vector control algorithms, dampening retrofit ROI calculations.
Strategic Opportunities
- Vietnam's underpenetrated industrial zones:Northern provinces around Hai Phong lack established drive service networks, creating first-mover channel advantages.
- Water treatment retrofit applications:ABB's standardized wall-mount platforms demonstrate scalable deployment models for municipal pump stations across Southeast Asia.
- Convergence of predictive analytics and edge computing:Real-time motor health monitoring is opening subscription revenue streams beyond hardware shipments.
Industry Challenges
- Embedded systems firmware expertise:Shortage of engineers proficient in field-oriented control algorithms is constraining product development cycles.
- Integration complexity with legacy SCADA architectures:Proprietary communication protocols in existing plant networks demand costly gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Low Voltage Drives Market |
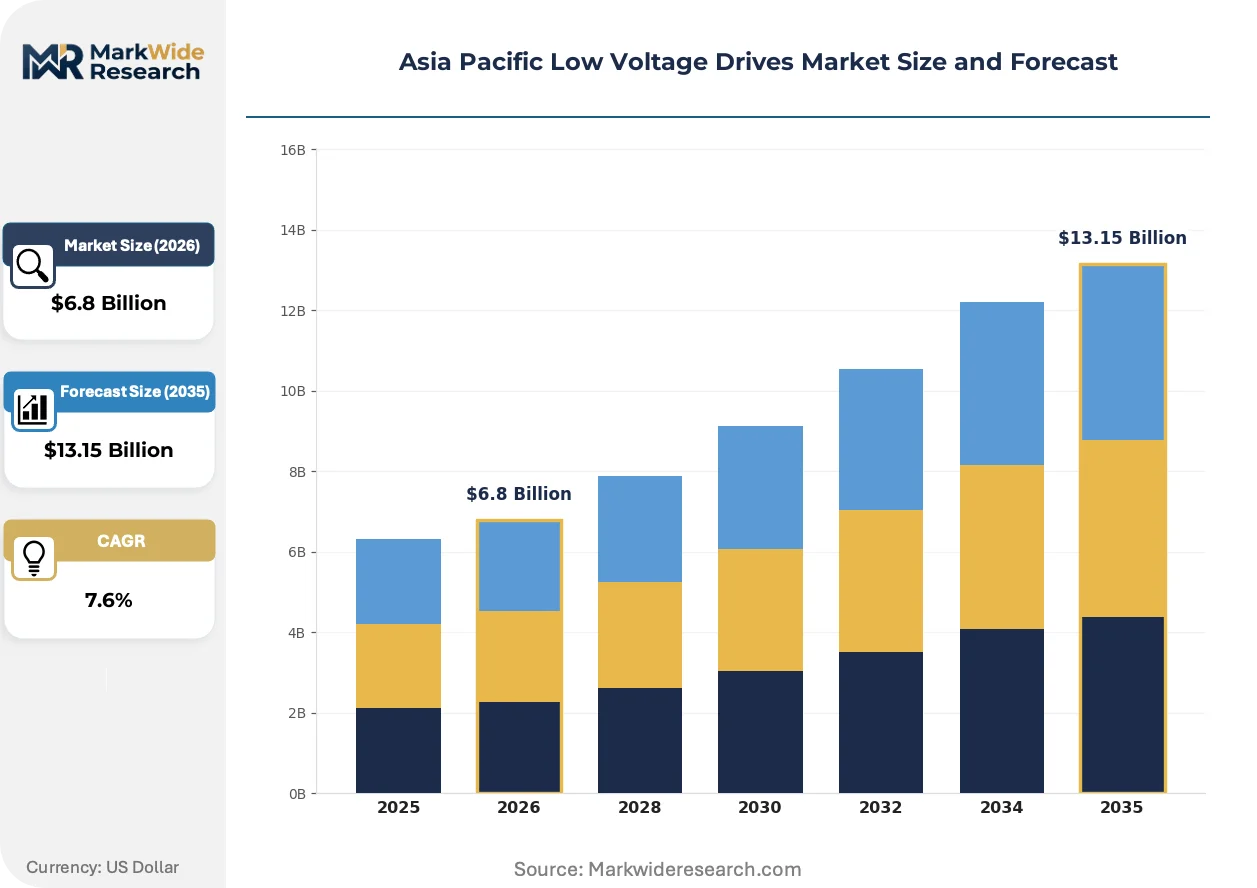
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drives, DC Drives, Servo Drives, VFDs End User: Manufacturing, Oil & Gas, Water Treatment, HVAC Technology: Variable Frequency Drive, Direct Torque Control, Sensorless Control, Closed Loop Control Installation: Panel Mount, Wall Mount, Cabinet Mount, Din Rail Mount |
| Companies Covered | Mitsubishi Electric Corporation, Rockwell Automation, Siemens, Delta Electronics, Danfoss, ABB, Yaskawa Electric, LS ELECTRIC Co., Ltd., Schneider Electric, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Low Voltage Drives Market Emerging Trajectories
Power semiconductor materials, regulatory efficiency mandates, and software-defined control architectures are simultaneously transforming product specifications and procurement criteria across the region.
Silicon carbide MOSFETs are rewriting power conversion economics in low voltage drives by enabling switching frequencies above 50 kHz without thermal derating. Japanese automotive suppliers are adopting these modules fastest, drawn by compact inverter packaging. The technology is compressing cooling system costs and shrinking enclosure footprints by roughly half versus IGBT equivalents.
Japan's METI Top Runner program is tightening motor efficiency benchmarks on a rolling three-year cycle. Manufacturers must now design for two efficiency tiers ahead of current compliance to avoid obsolescence. Premium servo drive lines targeting precision automation are absorbing the largest certification burden.
Factory buyers are unbundling after-sales service from initial hardware contracts, treating maintenance as a separate procurement category. System integrators in China's Yangtze River Delta are capturing this spend through remote monitoring subscriptions. The shift is most pronounced in HVAC and water treatment verticals where uptime penalties are severe.
Asia Pacific Low Voltage Drives Market Segmentation
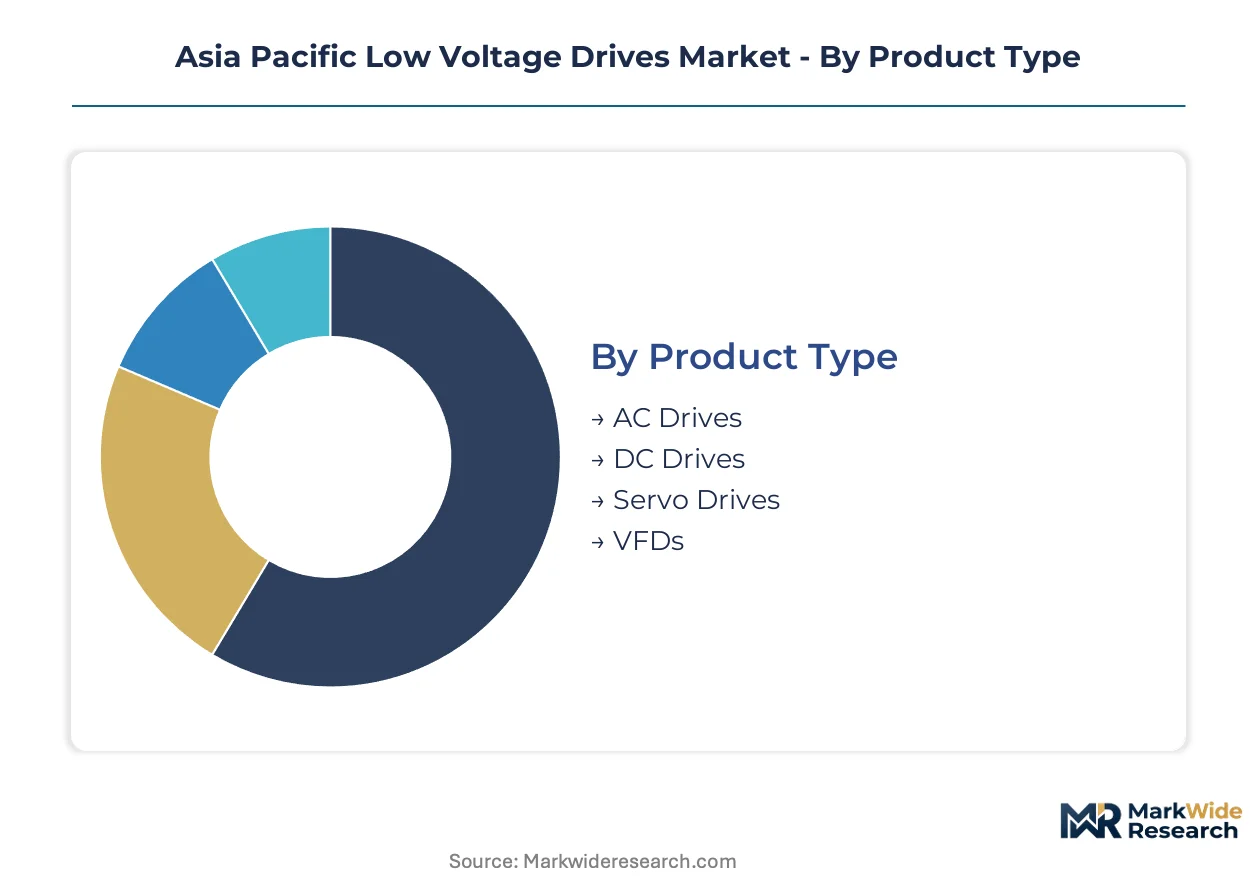
Low voltage drives serve heterogeneous application requirements across Asia Pacific, from precision servo positioning in Korean automotive plants to bulk flow control in Vietnamese water treatment facilities. Segmentation reveals where technology premiums concentrate versus where standardized volume shipments dominate procurement patterns.
Product Type:
AC drives and VFDs anchor volume shipments, while servo drives capture concentrated margin pools in precision automation corridors.
- AC Drives:These units modulate induction motor speed through adjustable frequency output, typically handling pump and fan loads across Shanghai and Pearl River Delta manufacturing clusters. China's GB/T efficiency tiers are accelerating replacement cycles in these high-volume installations.
- Servo Drives:Closed-loop positioning systems delivering precise torque and velocity control for robotics and CNC machinery. Korean and Japanese automotive supply chains in Gyeonggi and Aichi prefectures absorb the bulk of regional demand, driven by direct torque control adoption for high-inertia applications.
- DC Drives:Legacy wound-field motor controllers retaining niche presence in metal rolling and crane hoisting operations across India's Maharashtra industrial belt.
- VFDs:Variable frequency variants optimized for centrifugal load profiles, dominating HVAC retrofit specifications in Australian commercial buildings under MEPS compliance pressure.
Today's leader: AC drives. Tomorrow's challenger: Servo drives.
End User:
Manufacturing absorbs the deepest technology penetration, while water treatment presents the most standardized procurement specifications.
- Manufacturing:Discrete automation and process lines across China's Yangtze River Delta deploy the full spectrum of drive technologies. Japanese METI Top Runner compliance is forcing two-tier-ahead design investments in premium servo lines serving this vertical.
- HVAC:Commercial building climate systems favor compact wall-mount VFD configurations. Australia's MEPS requirements and South Korea's building energy codes are tightening efficiency thresholds for new chiller and air handling installations.
- Water Treatment:Municipal pump stations and wastewater facilities across Southeast Asia specify ruggedized drives with IP55+ enclosures. ABB's standardized platforms have demonstrated scalable deployment models from Hai Phong to Jakarta.
- Oil & Gas:Upstream and midstream operations in Australia's offshore basins and India's Gujarat extraction zones demand explosion-proof drive housings and extended temperature ratings.
Manufacturing commands technology premiums; water treatment offers volume scale.
Technology:
Control algorithm sophistication separates premium pricing tiers from commodity positioning.
- Variable Frequency Drive:Scalar V/Hz control dominates cost-sensitive fan and pump applications. India's BIS certification regime is channeling procurement toward verified efficiency performers in this category across Gujarat and Tamil Nadu corridors.
- Direct Torque Control:Advanced vector algorithms eliminating encoder feedback requirements for high-dynamic response. Korean automotive suppliers in Ulsan and Hwaseong are displacing conventional methods for conveyor and press applications.
- Sensorless Control:Estimator-based speed and position detection reducing wiring complexity. Japanese machine tool builders favor these implementations for spindle drive modernization.
- Closed Loop Control:Encoder-feedback precision for sub-micron positioning in semiconductor fabrication equipment, concentrated around Hsinchu and Pyeongtaek manufacturing zones.
Direct torque control is climbing fastest; V/Hz retains volume dominance.
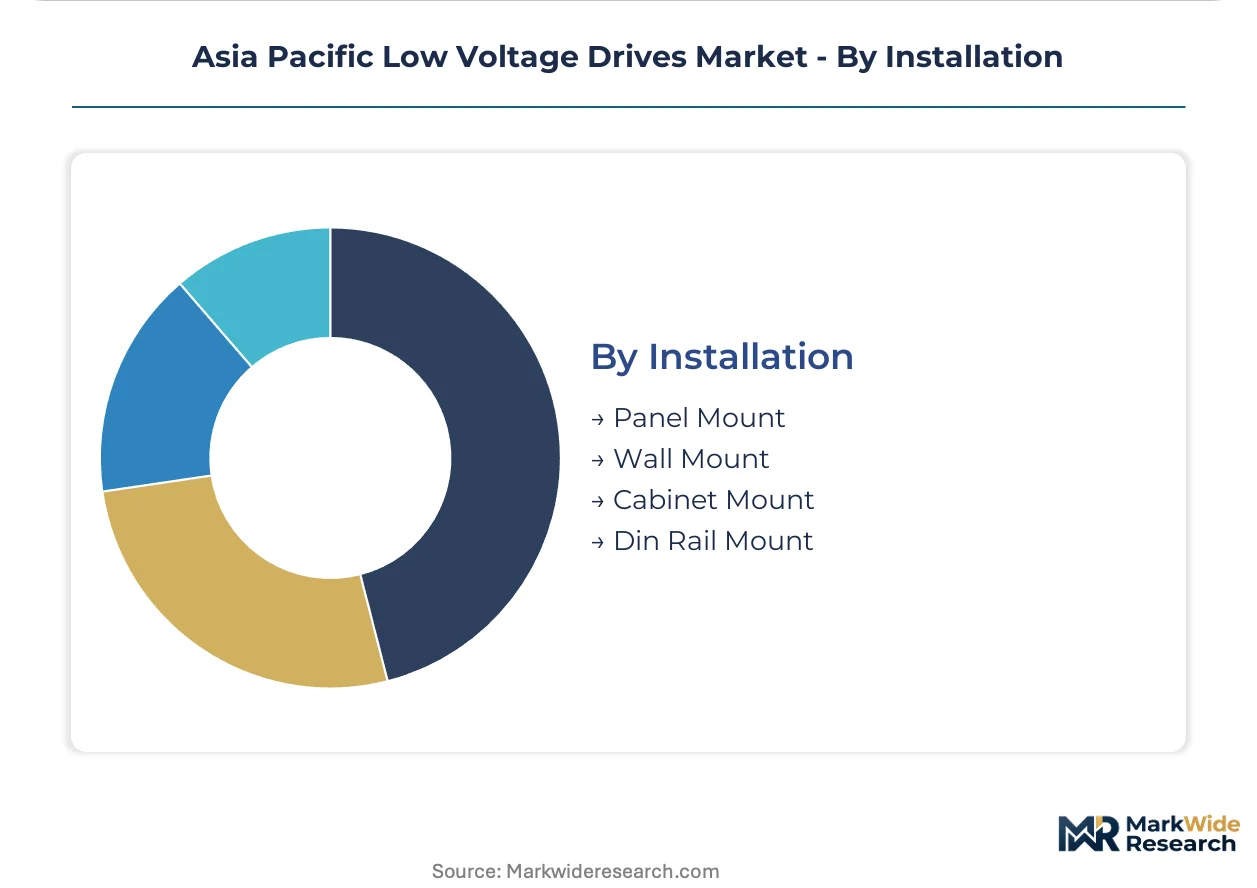
Installation:
Mounting configuration determines thermal management requirements and service accessibility economics.
- Wall Mount:Self-contained enclosures with integrated heatsinking dominate HVAC and water treatment retrofits. Southeast Asian municipal buyers favor these for minimal footprint requirements in aging pump house structures.
- Panel Mount:Chassis-style units integrating into OEM control cabinets, standard for machine tool and packaging machinery builders across China's Pearl River Delta.
- Cabinet Mount:Custom-engineered drive systems with isolated power sections, specified for oil and gas installations in Australia's Northwest Shelf extraction operations.
- Din Rail Mount:Compact fractional-horsepower units for distributed I/O and auxiliary motor control, expanding in Vietnamese electronics assembly facilities around Bac Ninh.
Wall mount leads retrofit demand; panel mount anchors OEM supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and the Pearl River Delta manufacturing clusters concentrate the deepest drive penetration in Asia Pacific, absorbing premium servo systems and standardized AC units alike. China's GB/T efficiency mandates are accelerating replacement cycles across these industrial corridors. India's BIS certification regime and Japan's METI Top Runner program are tightening compliance thresholds throughout the region.
China
GB/T energy efficiency standards are forcing two-tier-ahead design investments in motor systems across Yangtze River Delta factories. MIIT's dual carbon goals are channeling procurement toward verified high-efficiency performers in Shanghai industrial parks. The Pearl River Delta electronics assembly belt is deploying direct torque control systems for precision conveyor applications.
Japan
METI's Top Runner program resets motor efficiency benchmarks on a rolling three-year cycle, compressing product development timelines for domestic suppliers. Aichi prefecture's automotive supply chain is adopting silicon carbide power modules fastest, drawn by compact inverter packaging for robotics lines. Nagoya-area machine tool builders favor sensorless control implementations for spindle drive modernization.
India
BIS mandatory efficiency labeling is redirecting procurement toward certified vendors in Gujarat and Maharashtra industrial corridors. CEA regulations are tightening motor system compliance in Tamil Nadu textile operations. The Delhi-NCR manufacturing belt is seeing accelerated VFD deployment in HVAC retrofit specifications under building energy codes.
South Korea
MFDS-adjacent industrial safety rules are fragmenting certification pathways for multinational drive suppliers entering the market. Ulsan and Hwaseong automotive plants are displacing conventional V/Hz methods with direct torque control for high-inertia press applications. Busan-area shipyards are specifying ruggedized drives with extended temperature ratings for heavy-lift operations.
Vietnam
Northern provinces around Hai Phong lack established drive service networks, creating first-mover channel advantages for organized suppliers. Bac Ninh electronics assembly facilities are expanding DIN rail mount fractional-horsepower units for distributed motor control. The country's national industrial regulator is gradually harmonizing efficiency requirements with ASEAN standards, extending approval timelines for uncertified imports.
Asia Pacific Low Voltage Drives Market Vendor Landscape
Silicon carbide module sourcing dominates the current landscape as incumbents reprice IGBT portfolios or cede share in high-frequency applications. The vendor base separates into three tiers: Japanese and European majors with captive semiconductor capacity, Korean and Taiwanese specialists in precision servo systems, and emerging Chinese suppliers scaling through standardized AC drive volumes. Two competitive moves define current positioning: backward integration into SiC wafer supply and geographic expansion into underpenetrated Southeast Asian industrial zones.
Within the premium-tier vector, Mitsubishi Electric Corporation and Siemens occupy positions anchored by semiconductor supply chain control and software ecosystem integration respectively. Among diversified industrial conglomerates, ABB and Schneider Electric exemplify archetypes focused on vertical application specialization versus broad portfolio coverage. Rockwell Automation and Yaskawa Electric sit within the precision automation specialist tier, serving high-inertia manufacturing applications. Delta Electronics and Danfoss represent scale-driven Asia-Pacific and European fabricators competing through cost-optimized platform architectures. LS ELECTRIC Co., Ltd. anchors the Korean specialist position.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Rockwell Automation |
| Siemens |
| Delta Electronics |
| Danfoss |
| ABB |
| Yaskawa Electric |
| LS ELECTRIC Co., Ltd. |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
China's GB/T energy efficiency tier migrations are forcing manufacturers to absorb semiconductor upgrade costs or cede position to certified competitors, compressing margins across mid-tier AC drive portfolios while premium servo lines retain pricing power through captive SiC sourcing.
Pricing Analysis
Silicon carbide wafer cost pass-through dominates pricing dynamics as Japanese and Korean substrate suppliers command premium terms. Three-tier pricing structure across premium servo, certified standard AC, and economy V/Hz segments separates vendors by efficiency certification grade and after-sales bundling intensity. Cost compression in economy-tier AC drives is intensifying because Chinese suppliers are scaling standardized platforms. Municipal water treatment buyers in Southeast Asia exhibit highest price sensitivity, while Japanese automotive OEMs prioritize performance over unit cost.
Supply Chain Analysis
India's phased manufacturing program and local-content mandates for government procurement are reshaping component sourcing toward domestic assembly partners. Critical feedstock concentrates in Japan, South Korea, and China for SiC substrates, IGBT modules, and rare-earth magnets. Power semiconductor supply rests on single-source vulnerability from two dominant Japanese wafer manufacturers. Distribution runs through authorized service networks in established industrial clusters and direct OEM supply contracts for panel-mount configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where efficiency mandates across China, India, and Japan create replacement-driven demand independent of industrial cycle timing, with METI's three-year Top Runner resets guaranteeing sustained compliance expenditure.
For Market Incumbents: Hedge SiC supply exposure through backward integration into wafer partnerships or long-term offtake agreements with Japanese substrate specialists. Defend channel position in Vietnam's Hai Phong corridor by pre-positioning service infrastructure before competitors establish local presence. Certification burden from Australia's MEPS divergence demands dedicated test facility investment to avoid approval delays. For New Entrants and Emerging Players: Launch via remote monitoring subscription models targeting HVAC and water treatment verticals where buyers unbundle service from hardware procurement. Vietnam's northern industrial zones offer the most penetrable geography given absent incumbent service networks. Bac Ninh electronics assembly facilities present concentrated demand for DIN rail fractional-horsepower units with minimal customization requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with precision servo specialists possessing field-oriented control firmware expertise and established relationships with Korean automotive Tier 1s. Long-term viability hinges on semiconductor supply chain positioning rather than manufacturing scale alone. Watch for SiC module adoption inflection in Japanese machine tool builder procurement specifications as signal of technology transition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Wafer Supply | Captive substrate access insulates margin pressure from Japanese and Korean feedstock concentration. |
| Remote Monitoring Platform Launch | Subscription revenue streams capture unbundled service procurement in HVAC and water treatment verticals. |
| Vietnam Service Network Expansion | First-mover infrastructure in Hai Phong and Bac Ninh industrial corridors locks in channel position. |
| Dual Certification Investment | Parallel BIS and GB/T compliance accelerates market access across India and China manufacturing belts. |
| Predictive Analytics Partnership | Edge computing convergence with motor health monitoring opens recurring revenue beyond hardware shipments. |
Methodological Framework
Direct dialogue with plant engineers, OEM procurement managers, aftermarket service heads, and power electronics R&D directors grounded qualitative findings in operational reality. Secondary validation drew from MIIT efficiency filings, BIS certification registries, METI Top Runner benchmark publications, and customs trade data for power semiconductor imports. Bottom-up unit shipment estimates triangulated against top-down industrial motor stock replacement models.
Top-down macroeconomic drivers and bottom-up segment-level unit economics converged across the analysis window. Segmentation dimensions modeled include product type, control technology sophistication, end-use vertical, installation configuration, and country-level regulatory cluster. CAGRs derived from installed base turnover rates, efficiency mandate compliance deadlines, and semiconductor cost curve projections. Forecast inputs incorporated SiC module adoption curves and direct torque control displacement timelines in Korean automotive supply chains.
Several conditions sit outside the modeled scope, including potential relaxation of China's dual carbon targets, geopolitical disruption to Taiwan semiconductor logistics, and breakthrough motor technologies eliminating variable frequency requirements. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and substrate supply expansion timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Laptop Battery Market
Power Systems
Thermoelectric Coolers Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Battery Equalizer Market
Power Systems
Power Inverter Market
Power Systems
South America DC Distribution Network Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Integrated UPS Market
Power Systems
Europe Variable Frequency Drive Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Shunt Reactor Market
Power Systems
Bypass Thyristor Market
Power Systems
Automotive Inverters Market
Power Systems
Power Electronics Market
Power Systems
HVDC Converters Market
Power Systems
Electric Vehicle Inverter Market