
 Battery Racks Market | 2026-2036
Battery Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Racks Market Analysis
Project finance and power-purchase-agency-backed leasing structures for large-scale battery storage installations is reconfiguring which vendors can bid on multi-megawatt rack contracts. Schneider Electric SE leverages its integrated energy management software to bundle rack hardware with monitoring services. Vertiv Co. anchors its position through thermal-optimized rack designs purpose-built for high-density battery arrays. Eaton Corporation competes by extending its electrical infrastructure portfolio into modular rack architectures for data center and utility clients.
Battery racks are structural mounting systems engineered to house, organize, and protect electrochemical cells, typically fabricated from cold-rolled steel or extruded aluminum with specified load ratings exceeding 2,000 kg per bay and integrated cable management channels. These assemblies serve the primary function of securing battery strings against seismic events while enabling thermal regulation and maintenance access in commercial and industrial settings. Modular racks command the dominant share of new orders because hyperscale data center operators prioritize scalable, hot-swappable configurations over fixed installations. Aluminum material selection is gaining preference in electric vehicle charging infrastructure and telecommunications shelters where weight reduction offsets higher unit costs.
The US EPA and OSHA impose fire suppression and ventilation standards that directly dictate rack spacing, enclosure ratings, and aisle clearance in indoor battery rooms. China's MIIT enforces GB standards for lithium-ion battery system safety that cascade into rack design specifications for domestic manufacturers and export-bound suppliers. India's CEA recently issued draft technical standards for grid-connected battery storage that will reshape certification requirements for rack suppliers entering that procurement pipeline. Stakeholders must track how evolving fire codes and carbon-border adjustment mechanisms alter the cost calculus between steel and aluminum rack platforms across their target geographies.
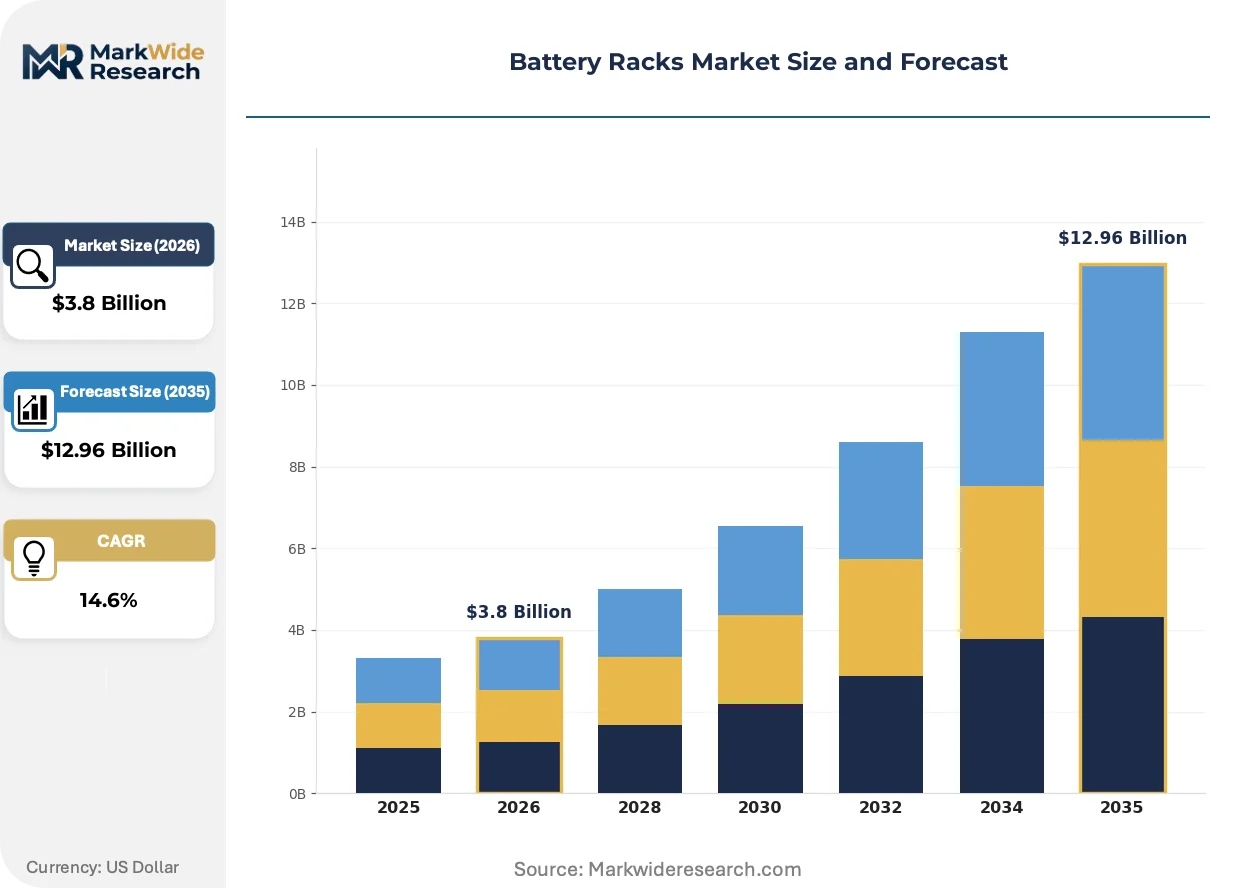
Market Dynamics
The convergence of utility-scale renewable energy buildouts and hyperscale data center expansion is compressing procurement timelines for modular battery rack systems, forcing manufacturers to pre-certify configurations before contract award rather than after.
Growth Catalysts
- US Inflation Reduction Act domestic content incentives:Domestic manufacturing requirements for clean energy tax credits are pulling rack fabrication back to US-based suppliers.
- Lithium-ion battery chemistry maturation:Energy density improvements in cell technology are enabling higher rack load ratings without structural redesign.
- Data center backup power standardization:Hyperscale operators in Northern Virginia and Dallas-Fort Worth are mandating hot-swappable rack architectures across all new facilities.
Market Restraints
- Cold-rolled steel price volatility:Input cost swings from integrated mill capacity constraints in Germany and Japan are compressing fabricator margins.
- Aluminum supply concentration:Smelter output limitations in Sichuan Province create single-source vulnerability for lightweight rack programs.
- Seismic certification bottlenecks:Extended testing timelines at accredited laboratories in California delay project commissioning for West Coast utility installations.
Strategic Opportunities
- India grid-connected storage procurement:CEA draft technical standards are opening certification pathways for rack suppliers entering state-level tender pipelines.
- Electric vehicle charging infrastructure:DC fast-charging hubs in Germany require weight-optimized aluminum racks for outdoor enclosure mounting.
- Digital twin integration:Convergence of rack-mounted sensor arrays with predictive maintenance software is creating attach-rate expansion for hardware vendors.
Industry Challenges
- Thermal engineering talent scarcity:Battery rack suppliers compete with automotive and semiconductor sectors for computational fluid dynamics specialists.
- Multi-jurisdiction certification stacking:Simultaneous UL, IEC, and GB standard compliance extends product development cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Racks Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Racks, Fixed Racks, Portable Racks, Wall-Mounted Racks Material: Steel, Aluminum, Composite, Plastic Application: Renewable Energy Storage, UPS Systems, Electric Vehicles, Telecommunications End User: Residential, Commercial, Industrial, Government |
| Companies Covered | Schneider Electric SE, Vertiv Co., Eaton Corporation, Delta Electronics, Inc., Rittal GmbH & Co. KG, Huawei Technologies Co., Ltd., ABB Ltd., Newton Instrument Co., Storage Battery Systems, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Racks Market Emerging Trajectories
Active redesign of rack architectures is compressing the boundary between structural hardware and intelligent infrastructure, embedding sensing and control layers directly into formerly passive mounting systems.
Digital twin software for thermal modeling is virtualizing rack design validation before physical prototyping. Engineering teams at hyperscale data center operators in Texas and California are deploying these tools to simulate cell-level temperature distribution across thousands of rack configurations. The technology is virtualizing what previously required months of physical testing into compressed computational workflows.
China's MIIT enforcement of updated GB standards for lithium-ion battery system safety is cascading into mandatory rack spacing and ventilation specifications. Domestic manufacturers in Jiangsu Province are redesigning enclosure geometries to meet flame propagation containment requirements. Export-bound suppliers must dual-certify to these specifications to maintain access to Chinese utility procurement channels.
Power-purchase-agency-backed leasing structures are fragmenting traditional equipment procurement into service-based contracts. Independent power producers in Texas are shifting from direct rack purchase to operational expenditure models bundled with installation and maintenance. This restructuring is most visible in utility-scale solar-plus-storage projects where developers prioritize balance-sheet flexibility over asset ownership.
Battery Racks Market Segmentation
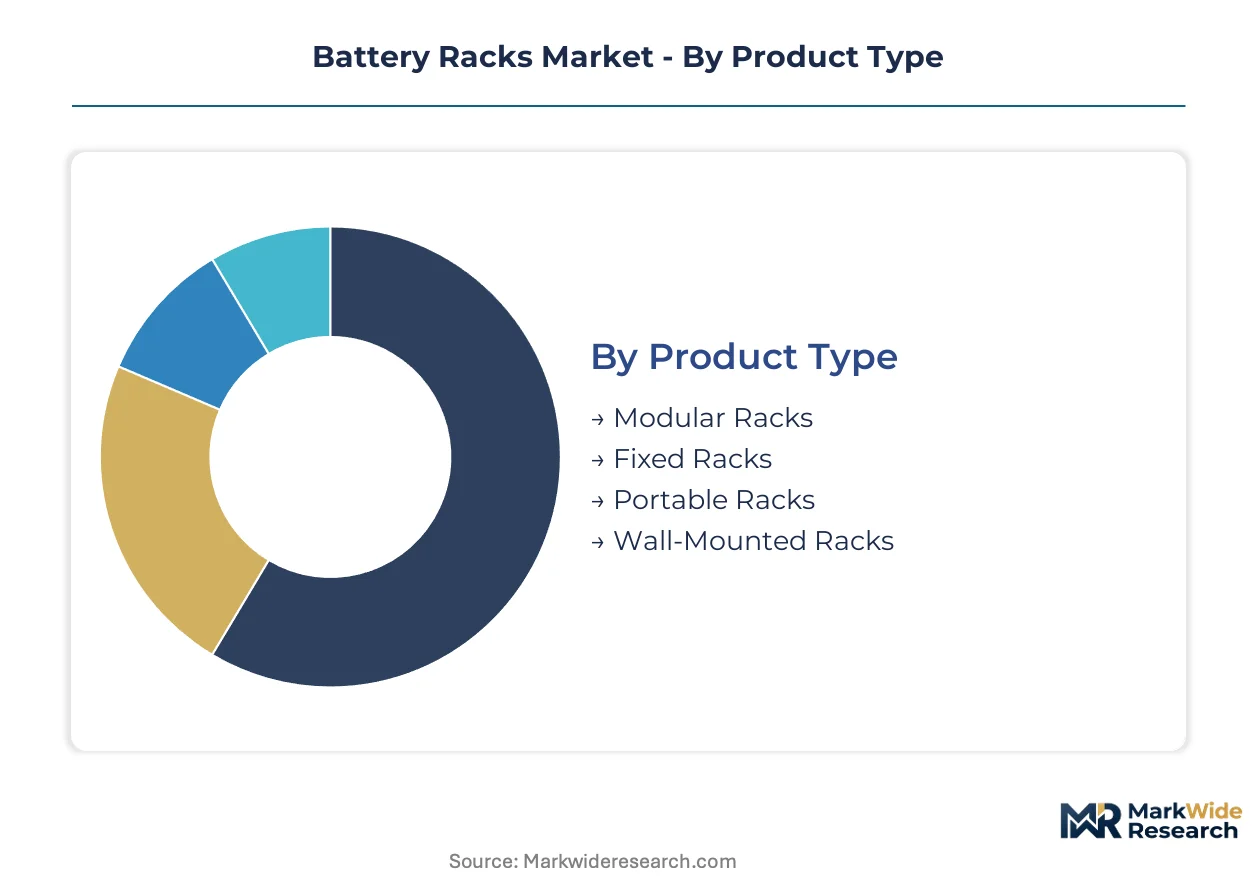
Battery rack procurement patterns diverge sharply across structural formats, material specifications, and deployment environments. Segmentation clarity enables suppliers to align certification investments with actual demand concentration rather than spreading compliance costs uniformly.
Product Type:
Mature configurations dominate utility-scale procurement while emerging formats capture specialized edge deployments.
- Modular Racks:Hot-swappable bay architectures fabricated from cold-rolled steel or extruded aluminum enable incremental capacity expansion without facility shutdown. Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth mandate these configurations for all new backup power installations. Rack-level redundancy requirements from FERC Order 2222 implementation are accelerating specification standardization across independent system operators.
- Fixed Racks:Welded structural frames with permanent cell mounting positions offer lower unit cost for single-installation renewable energy projects. Utility-scale solar-plus-storage developers in Texas and California specify fixed racks for 20-year asset life projections where reconfiguration probability remains minimal. Seismic certification timelines at California laboratories create procurement bottlenecks for West Coast deployments.
- Portable Racks:Skid-mounted or caster-based designs serve temporary power applications and mobile grid stabilization.
- Wall-Mounted Racks:Vertical space-optimized configurations address constrained floorplan environments in telecommunications shelters and urban commercial buildings.
Modular racks retain volume leadership; portable racks hold the steepest expansion curve.
Material:
Cost tier stratification separates commodity steel specifications from performance-optimized aluminum and composite alternatives.
- Steel:Cold-rolled carbon steel dominates utility-scale installations where load ratings exceed 2,000 kg per bay and cost sensitivity outweighs weight considerations. Integrated mill capacity constraints in Germany and Japan are compressing fabricator margins through input price volatility. Domestic content requirements under the US Inflation Reduction Act are pulling fabrication toward US-based suppliers.
- Aluminum:Extruded aluminum alloys reduce rack weight by 40-60% compared to steel equivalents, enabling outdoor enclosure mounting for DC fast-charging infrastructure. Smelter output limitations in Sichuan Province create single-source vulnerability for lightweight rack programs. Electric vehicle charging hub developers in Germany specify aluminum for weight-optimized outdoor installations.
- Composite:Fiber-reinforced polymer structures address corrosion-critical marine and chemical processing environments.
- Plastic:Injection-molded polymer racks serve low-load residential and light commercial applications with minimal thermal management requirements.
Steel maintains cost-driven volume dominance; aluminum captures the fastest share gains in mobility-critical applications.
Application:
Customer type concentration varies across grid-connected storage, critical power backup, and transportation electrification use cases.
- Renewable Energy Storage:Utility-scale lithium-ion installations require seismic-rated rack systems with integrated fire suppression compatibility. Procurement timelines compress as developers pre-certify configurations before contract award. Texas and California project pipelines account for the majority of North American rack demand in this segment.
- UPS Systems:Uninterruptible power supply installations in data centers demand hot-swappable architectures with redundant power distribution. Hyperscale operators are standardizing rack specifications across Northern Virginia, Dallas-Fort Worth, and Frankfurt metro areas.
- Electric Vehicles:Battery pack assembly lines and charging infrastructure deploy weight-optimized racks for automated handling and outdoor mounting.
- Telecommunications:Remote shelter installations prioritize corrosion resistance and compact footprints for backup power systems.
Renewable energy storage commands current procurement volume; electric vehicle applications are climbing the fastest.
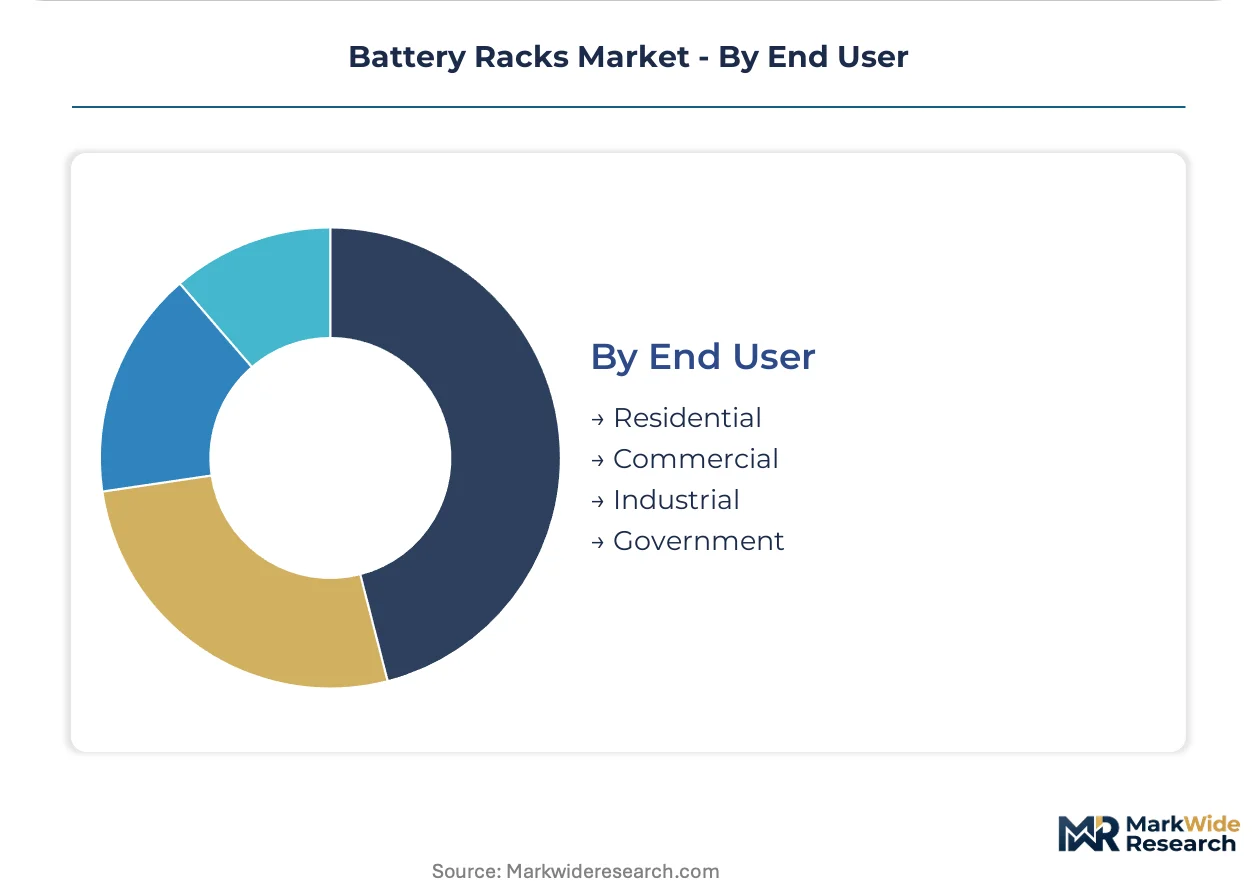
End User:
Volume scale and margin structure diverge across residential distributed generation, commercial critical power, and industrial grid-scale deployments.
- Industrial:Manufacturing facilities, mining operations, and grid-scale storage developers specify heavy-duty racks with integrated thermal management and seismic certification. India's CEA draft technical standards for grid-connected battery storage are opening certification pathways for rack suppliers entering state-level tender pipelines.
- Commercial:Data centers, healthcare facilities, and retail distribution centers prioritize hot-swappable configurations with predictive maintenance integration. Schneider Electric and Vertiv compete through bundled monitoring services and thermal-optimized designs.
- Residential:Home energy storage systems utilize compact wall-mounted or floor-standing racks with simplified installation requirements.
- Government:Military, municipal, and research facility procurements emphasize domestic content compliance and extended warranty terms.
Industrial end users retain volume leadership; commercial installations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of battery rack systems concentrate in Chinese and German manufacturing hubs while import demand clusters in North American and Middle Eastern deployment zones. Domestic content requirements in multiple jurisdictions are reshaping traditional trade patterns. Regional procurement timelines now hinge on pre-certification availability rather than manufacturing capacity alone.
United States
Utility-scale solar-plus-storage developers in Texas and California are compressing rack procurement cycles to meet interconnection deadlines. The Inflation Reduction Act's domestic manufacturing tax credits are pulling fabrication capacity back from Asian suppliers to US-based producers. Northern Virginia data center clusters now mandate hot-swappable rack architectures as standard backup power infrastructure.
China
Jiangsu Province manufacturers are redesigning enclosure geometries to comply with updated MIIT GB standards for lithium-ion battery system safety. State grid procurement pipelines in Sichuan and Guangdong provinces are absorbing record volumes of seismic-rated rack systems for renewable integration projects. Export-bound suppliers must dual-certify to domestic specifications to maintain access to Chinese utility channels.
Germany
DC fast-charging hub developers specify weight-optimized aluminum racks for outdoor enclosure mounting across Bavaria and North Rhine-Westphalia. The EU Green Deal's carbon border adjustment mechanisms are altering cost calculations between imported steel and domestic aluminum rack platforms. Industrial fabricators in Baden-Württemberg are expanding capacity to serve automotive battery pack assembly lines.
India
State-level tender pipelines in Maharashtra and Gujarat are opening certification pathways for rack suppliers following CEA draft technical standards for grid-connected battery storage. Domestic manufacturing incentives under the PLI scheme are attracting joint ventures between international fabricators and Indian steel producers. Telangana's renewable energy parks are emerging as concentrated demand clusters for heavy-duty seismic-rated installations.
Japan
Data center operators in Tokyo and Osaka metro areas are standardizing rack specifications to align with METI efficiency guidelines for critical power infrastructure. JIS certification requirements are extending product development timelines for foreign suppliers seeking utility access. Kyushu-based battery manufacturers are driving demand for precision-engineered racks with integrated thermal management channels.
Battery Racks Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with fabrication and materials expertise. The vendor base stratifies across three functional layers: electrical infrastructure conglomerates bundling hardware with software services, precision metal fabricators optimizing structural geometries for thermal performance, and regional steel processors serving cost-sensitive utility procurement. Consolidation pressure is accelerating as project finance structures favor vendors with pre-certified configuration libraries over custom engineering capabilities.
Among diversified electrical infrastructure providers, Schneider Electric SE, Vertiv Co., and Eaton Corporation exemplify the platform-integrator archetype. Schneider Electric SE anchors the European tier through bundled energy management offerings. Vertiv Co. occupies a position emphasizing thermal-optimized structural designs. Eaton Corporation represents the portfolio-extension strategy from upstream electrical components into modular rack architectures. These three entities illustrate how incumbent infrastructure players are capturing margin through service attach-rates rather than hardware differentiation alone.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Co. |
| Eaton Corporation |
| Delta Electronics, Inc. |
| Rittal GmbH & Co. KG |
| Huawei Technologies Co., Ltd. |
| ABB Ltd. |
| Newton Instrument Co. |
| Storage Battery Systems, LLC |
| Others |
Supply Flow & Price Mechanics
Jiangsu Province's concentrated fabrication capacity for cold-rolled steel battery racks translates directly into pricing leverage for domestic Chinese suppliers serving utility-scale procurement pipelines. This geographic supply anchor shapes how international buyers negotiate contract terms, particularly when German and Japanese mill constraints tighten input availability for Western fabricators.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the battery racks market. Price differentiation separates seismic-certified aluminum configurations for California utility installations from commodity cold-rolled steel racks for Texas solar-plus-storage projects. Cost compression in the steel tier is intensifying because integrated mill capacity constraints in Germany and Japan are transmitting volatility downstream. Data center operators in Northern Virginia exhibit the lowest price sensitivity due to mandated hot-swappable architectures, while state-level tender bidders in India face acute margin pressure from domestic content requirements.
Supply Chain Analysis
Cold-rolled steel feedstock draws from integrated mills in Germany, Japan, and domestic US producers under Inflation Reduction Act incentives. Aluminum supply rests on smelter output from Sichuan Province, Chilean bauxite refining, and Australian alumina processing. Single-source vulnerability concentrates in Chinese lightweight alloy production, where power rationing protocols disrupt rack fabrication schedules. Distribution runs through direct OEM contracts for hyperscale data center deployments and EPC contractor intermediaries for utility-scale renewable projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery rack procurement is recovering from a cyclical trough as utility-scale renewable buildouts and hyperscale data center expansion compress order timelines. This cyclical upswing favors vendors with pre-certified configuration libraries over custom engineering capabilities.
For Market Incumbents: Harden certification moats by pre-positioning UL 9540A-tested configurations for California utility procurement before seismic laboratory bottlenecks worsen. Deepen upstream control over aluminum extrusion capacity through joint ventures with Sichuan-based smelters to offset single-source vulnerability. Vertiv and Schneider Electric exemplify this defensive posture through thermal-optimized design IP and bundled monitoring service attach-rates.
For New Entrants and Emerging Players: Establish a beachhead in India's state-level tender pipelines following CEA draft technical standards for grid-connected battery storage. Target Maharashtra and Gujarat procurement channels where domestic manufacturing incentives under the PLI scheme are attracting first-mover international fabricators. Lead with weight-optimized aluminum rack configurations for electric vehicle charging infrastructure in Germany, where DC fast-charging hub developers prioritize outdoor enclosure mounting specifications.
For Investors and Strategic Acquirers: Long-term, this sits as an infrastructure-software convergence play because digital twin integration for thermal modeling is virtualizing rack design validation and creating recurring software attach-rate expansion. Acquisition targets should cluster around precision metal fabricators with computational fluid dynamics capabilities and pre-certified configuration libraries spanning UL, IEC, and GB standards. Watch FERC Order 2222 implementation timelines as the signal for accelerated standardization across independent system operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Certification Pre-Positioning | California laboratory bottlenecks reward vendors with pre-tested configurations for West Coast utility installations. |
| Domestic Content Compliance Investment | US Inflation Reduction Act tax credits pull fabrication capacity from Asian suppliers to US-based producers. |
| Digital Twin Platform Integration | Virtual thermal modeling compresses design validation timelines for hyperscale data center operators in Texas. |
| Aluminum Supply Chain Backward Integration | Sichuan smelter output limitations create acquisition value for extrusion-capable mid-tier fabricators. |
| Multi-Jurisdiction Certification Stacking | Simultaneous UL, IEC, and GB compliance extends product development cycles by eight to fourteen months. |
Methodological Framework
Initial hypotheses were tested against primary input from utility procurement officers, data center infrastructure directors, EPC project managers, and precision metal fabrication executives and refined through secondary validation. Primary fieldwork combined structured interviews with rack specification leads at hyperscale operators in Northern Virginia and Dallas-Fort Worth with technical consultations at seismic certification laboratories in California. Secondary sources included FERC interconnection filings, EIA utility-scale storage databases, CEA draft technical standards, and SEC 10-K disclosures from electrical infrastructure conglomerates. Bottom-up unit economics triangulated against top-down addressable market sizing across the analysis window.
Demand-supply balance framing anchored the forecast framework, modeling procurement volume against fabrication capacity expansion across cold-rolled steel and aluminum supply tiers. Segmentation dimensions spanned product type (modular, fixed, portable, wall-mounted), material specification (steel, aluminum, composite, plastic), application (renewable energy storage, UPS systems, electric vehicles, telecommunications), and end user (industrial, commercial, residential, government). CAGRs were derived from installed base growth rates and replacement cycle compression in data center backup power. Industry-specific inputs included lithium-ion battery chemistry maturation curves and evolving fire code enforcement timelines from the US EPA and China's MIIT.
Macroeconomic conditions sit as an overlay; deviation in cold-rolled steel input costs, aluminum smelter power availability, or clean energy tax credit policy would shift the trajectory materially. Forecasts reflect documented assumptions regarding interconnection queue clearance rates and hyperscale data center construction schedules. Cross-checking against FERC Order 2222 implementation progress and state-level renewable portfolio standard mandates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Electrical and Automation System Market
Power Systems
Global Rectifier Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Voltage Regulators Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
North America Telecom Power Systems Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Power Supply and Charger Market
Power Systems
North America Electric Vehicle Power Inverter Market
Power Systems
Battery Cyclers Market
Power Systems
Global Flexible Batteries Market
Power Systems
AC DC Power Adapter Market
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Space DC-DC Converters Market