
 Global Frequency Converter Market | 2026-2036
Global Frequency Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Frequency Converter Market Foresight
ISO 9001:2015 certification is rotating as a baseline qualifier for frequency converter suppliers bidding into utility-scale and data center procurement frameworks. Siemens AG leverages its European manufacturing footprint to sustain long-term service contracts with industrial automation clients. ABB Ltd anchors its position through deep expertise in medium-voltage drive architectures for heavy process industries. Danfoss A/S differentiates via specialized HVAC and refrigeration compressor control solutions that dominate building efficiency retrofits.
A frequency converter is an electromechanical or solid-state power electronic device that transforms input AC power at one frequency to output AC power at a variable or fixed different frequency, typically operating across voltage classes from 230V to 13.8kV and power ratings from fractional horsepower to multi-megawatt scale. Its primary industrial purpose is to enable precise motor speed control, energy recovery, and grid-frequency matching for equipment deployed across incompatible electrical standards. Voltage Source Inverter configurations lead installed base volumes due to mature IGBT and SiC semiconductor supply chains, while Matrix Converter architectures represent the fastest-growing technology segment as silicon carbide switching devices reduce harmonic distortion and eliminate DC-link capacitors. End user demand from Data Centers is expanding rapidly as hyperscale facilities deploy frequency converters to bridge between 50Hz and 60Hz grid supplies and IT load requirements.
The EU Ecodesign Directive and associated IEC 61800-9 efficiency standards shape product design mandates across European manufacturing supply chains, while China's GB standards and NMPA-equivalent quality certifications govern market access for imported drive equipment. The US Department of Energy enforces NEMA MG1 and IEEE 519 compliance that dictates harmonic emission limits and minimum efficiency performance standards for motor-drive systems. Stakeholders must monitor semiconductor substrate transitions from silicon to silicon carbide and the evolving efficiency tier thresholds that regulators in Germany, China, and the United States are calibrating independently.
Market Dynamics
The transition from silicon IGBTs to silicon carbide power semiconductors is compressing converter footprints while elevating switching frequencies, forcing incumbent suppliers to retool manufacturing lines and recalibrate service architectures around higher-efficiency hardware platforms.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency tiers for motor-drive systems are compelling industrial facility operators across Germany, France, and Italy to accelerate replacement cycles for legacy fixed-speed equipment.
- Data center load bridging:Hyperscale facilities in Northern Virginia, Frankfurt, and Singapore require frequency converters to reconcile 50Hz grid supplies with 60Hz IT infrastructure, creating dedicated product demand.
- Subsea pumping electrification:Offshore oil and gas platforms in the North Sea and Gulf of Mexico are deploying medium-voltage drives for subsea processing, extending converter operational envelopes to 3,000-meter depths.
Market Restraints
- Silicon carbide substrate scarcity:Wolfspeed, Coherent, and II-VI control 80% of merchant SiC wafer supply, concentrating input cost volatility and allocation risk among converter OEMs.
- Medium-voltage certification timelines:IEC 61800-4 type testing for 3.3kV through 13.8kV classes requires 18-24 month validation cycles, freezing product launch cadence regardless of R&D completion.
- Integrated motor-drive substitution:Permanent magnet synchronous motors with embedded variable frequency control are capturing fractional horsepower applications below 75kW, eroding discrete converter attach rates.
Strategic Opportunities
- India industrial automation retrofit:The BIS energy efficiency labeling program and state-level electricity duty exemptions for efficient drives are unlocking replacement demand in Maharashtra, Gujarat, and Tamil Nadu manufacturing corridors.
- Hydrogen electrolyzer integration:100MW+ proton exchange membrane and alkaline electrolysis plants require precision AC-AC conversion for stack frequency matching, creating a new power class specification.
- Direct-to-fleet digital distribution:OEMs are bypassing electrical distributors to sell configured drive packages through Amazon Business and Alibaba 1688, capturing margin and reducing lead times for standard ratings.
Industry Challenges
- Power electronics engineering scarcity:Converter manufacturers compete with electric vehicle and renewable inverter sectors for SiC device characterization and thermal management specialists, elongating product development timelines.
- Legacy fieldbus integration complexity:Brownfield installations in process industries require backward compatibility with PROFIBUS DP, DeviceNet, and Modbus RTU protocols, forcing redundant communication hardware and software validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Frequency Converter Market |
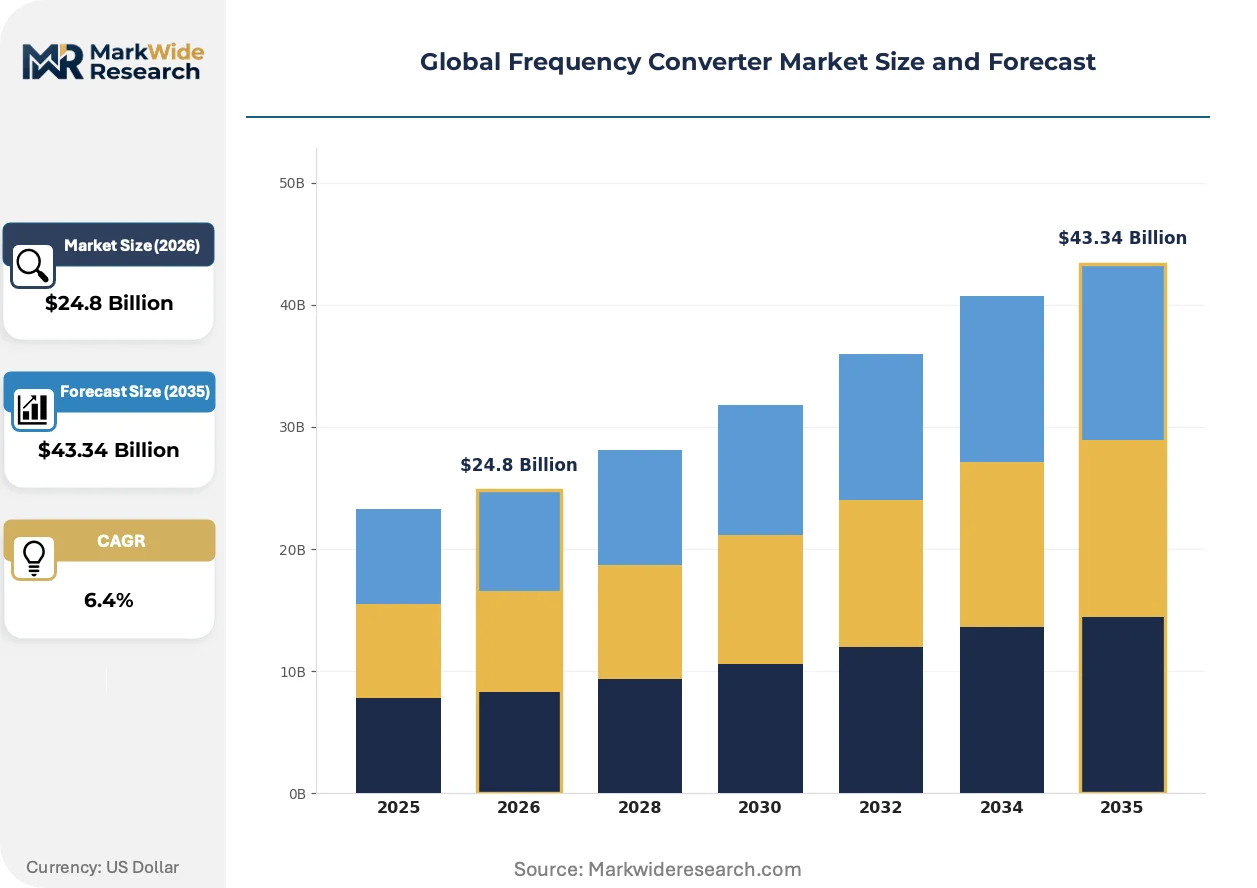
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voltage Source Inverter, Current Source Inverter, Cycloconverter, Matrix Converter Technology: PWM Control, V/F Control, Sensorless Vector Control, Direct Torque Control Application: Pumps, Compressors, HVAC Systems, Conveyor Systems End User Industry: Manufacturing Plants, Data Centers, Mining Operations, Commercial Buildings |
| Companies Covered | General Electric Company, Georator Corporation, ABB Ltd, Magnus Power Private Limited, Aplab Ltd, Siemens AG, NR Electric Co. Ltd., KGS Electronics, Inc., Danfoss A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Frequency Converter Market Shifts & Advancements
Power semiconductor substrate transitions and regulatory efficiency tier escalations are simultaneously redefining product architectures and procurement criteria across industrial, infrastructure, and energy verticals.
Silicon carbide MOSFETs are supplanting silicon IGBTs in 600V through 1.7kV converter designs, enabling 50kHz switching frequencies that reduce filter component volume by 60%. Data center operators in Singapore and Ireland are specifying SiC-based units for 400Hz ground power applications. This platform shift is miniaturizing cabinet footprints while elevating power density benchmarks that now govern competitive tender evaluations.
China's GB 30253-2013 efficiency standards and forthcoming tier upgrades are mandating IE4-equivalent performance for motors above 7.5kW, which cascades into converter efficiency requirements under GB/T 12668. Domestic manufacturers in Jiangsu and Zhejiang are accelerating IGBT-to-SiC transitions to maintain market access. The enforcement pattern is compressing product lifecycles and elevating R&D intensity for suppliers serving Chinese industrial automation.
Equipment-as-a-service contracting is displacing capital purchase models for drives above 500kW in pulp and paper and mining operations. Wärtsilä and Siemens Energy are piloting performance-guaranteed availability contracts in Finnish and Australian installations. Finland and Western Australia represent the geographies where outcome-based arrangements are achieving contractual scale and reshaping vendor-customer relationships.
Global Frequency Converter Market Segmentation
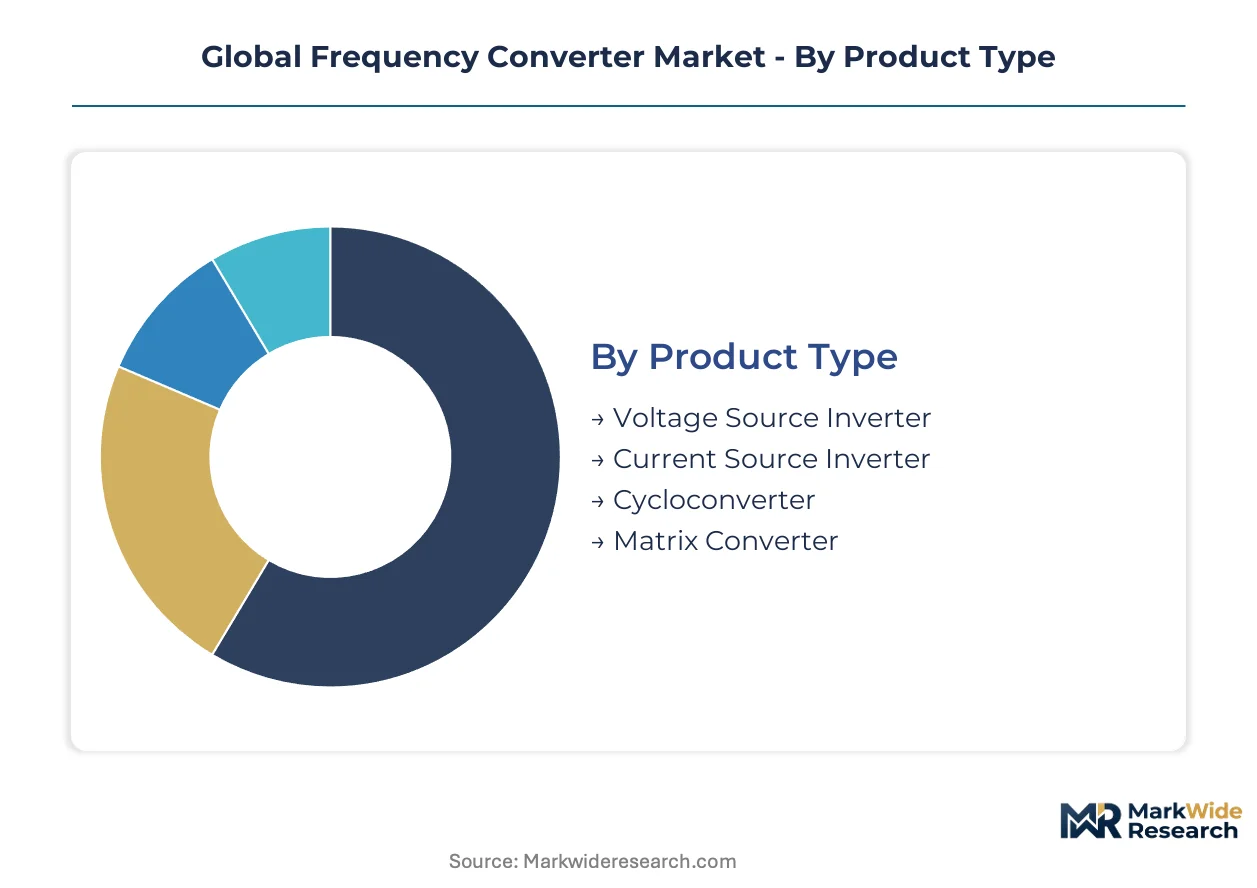
Frequency converter procurement patterns diverge sharply across product architectures and control methodologies, with semiconductor substrate choices and efficiency tier compliance creating distinct margin profiles that reshape supplier positioning.
Product Type:
Margin pools concentrate in medium-voltage architectures where IEC 61800-4 certification barriers protect pricing power and long-term service attach rates.
- Voltage Source Inverter:These units deploy IGBT or SiC semiconductor bridges to synthesize variable-frequency output from DC-link capacitors, dominating installed volumes across 230V through 690V industrial applications. Demand clusters in German automotive manufacturing and Chinese steel rolling mills where retrofit cycles accelerate under tightening efficiency mandates.
- Matrix Converter:Direct AC-AC conversion eliminates DC-link energy storage through bidirectional switching arrays, cutting harmonic distortion and component count. Offshore platforms in the North Sea and Gulf of Mexico specify these for subsea pumping at 3,000-meter depths where capacitor reliability fails.
- Current Source Inverter:Inductor-based DC-link designs excel in regenerative braking and high-inertia loads above 1MW.
- Cycloconverter:Line-commutated thyristor arrays serve synchronous motor drives in mining hoists and cement mills.
The dominant share belongs to Voltage Source Inverter configurations, while Matrix Converter architectures are climbing the fastest as silicon carbide switching costs decline.
Technology:
Control algorithm sophistication determines competitive differentiation in applications requiring precise torque response or energy recovery.
- PWM Control:Pulse-width modulation remains the baseline methodology for general-purpose drives, using carrier frequencies between 2-16kHz to approximate sinusoidal output. German machine tool builders and Japanese robotics OEMs specify PWM units for cost-sensitive positioning tasks.
- Direct Torque Control:Flux and torque estimation without encoder feedback enables sub-millisecond response for high-dynamic applications. Mining conveyors in Western Australia and Chilean copper operations deploy DTC for regenerative downhill braking.
- V/F Control:Scalar voltage-frequency ratio methods serve fan and pump loads where precise speed control is unnecessary.
- Sensorless Vector Control:Model-based rotor position estimation eliminates encoder hardware in harsh environments.
PWM Control retains the largest installed base, though Direct Torque Control is expanding most quickly in heavy process industries.
Application:
Application-specific duty cycles and environmental envelopes create divergent specification requirements that fragment procurement patterns.
- HVAC Systems:Centrifugal chiller and air-handling unit drives prioritize partial-load efficiency under ASHRAE 90.1 and EU Ecodesign Directive benchmarks. Building retrofits in Singapore and Frankfurt specify integrated bypass and harmonic filtering.
- Compressors:Oil-free and lubricated rotary screw applications demand precise pressure control and energy recovery. Food and beverage facilities in Denmark and cold storage warehouses in the Netherlands specify these for refrigeration duty.
- Pumps:Variable-flow water and process fluid handling dominates municipal and industrial infrastructure.
- Conveyor Systems:Long-distance material handling requires coordinated multi-drive control and regenerative capability.
HVAC Systems command the broadest addressable market, while Compressor applications are gaining share fastest on cold chain investment cycles.
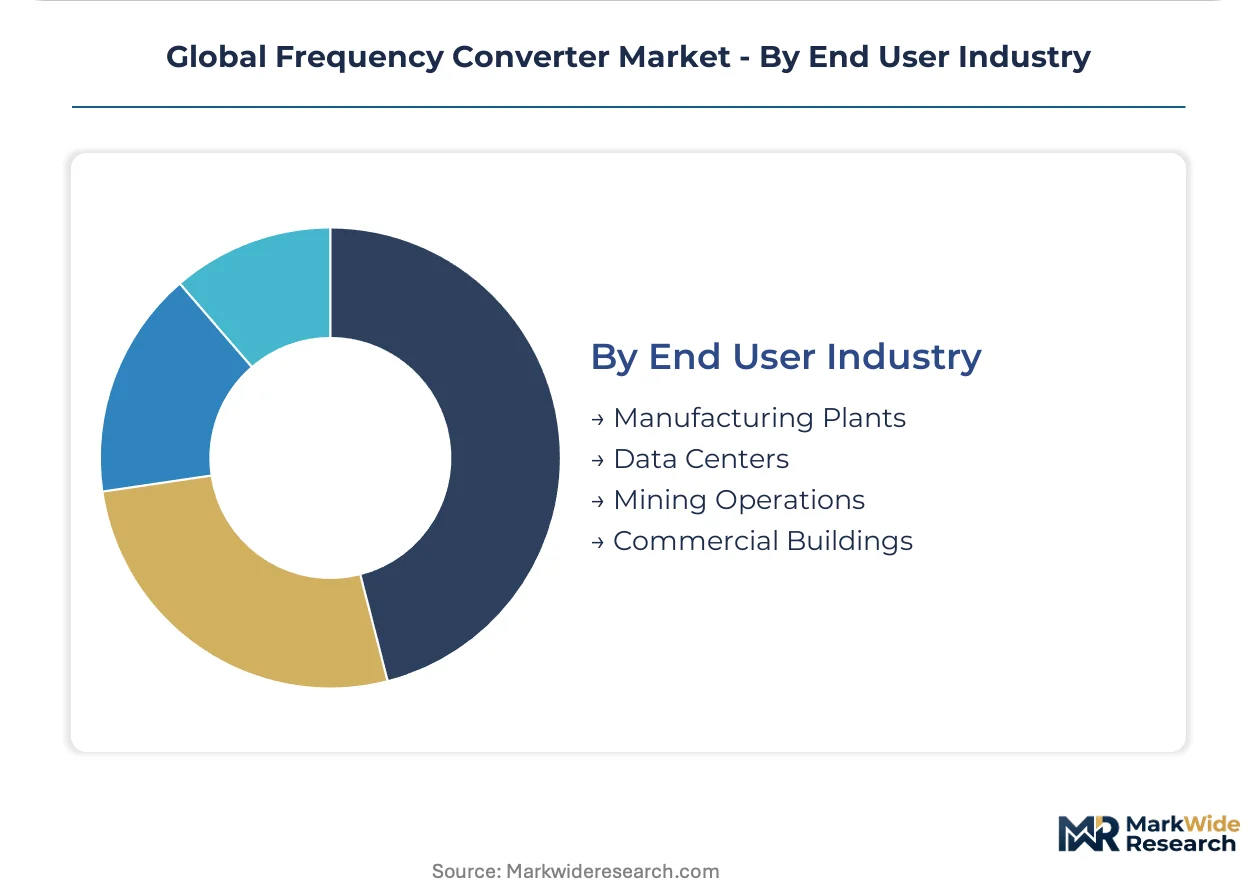
End User Industry:
End-use concentration in capital-intensive sectors creates project-based demand volatility and extended sales cycles.
- Data Centers:Hyperscale facilities in Northern Virginia, Frankfurt, and Singapore require 50Hz/60Hz bridging converters alongside 400Hz ground power units for aircraft and IT load simulation. Efficiency specifications now mandate 97%+ conversion efficiency at 50% load.
- Mining Operations:Open-pit and underground extraction sites deploy medium-voltage drives for hoists, mills, and conveyors in Western Australia and Chile. Dust ingress protection and vibration tolerance dominate specification criteria.
- Manufacturing Plants:Discrete and process automation spans the widest power range and control complexity.
- Commercial Buildings:Elevator, escalator, and HVAC retrofit demand concentrates in urban density corridors.
Manufacturing Plants represent the largest historical volume, yet Data Centers are expanding most rapidly on cloud infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators and industrial automation buyers concentrate procurement authority in Germany, China, and the United States, where efficiency mandates and infrastructure buildouts create synchronized replacement cycles across incompatible grid standards.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives 50Hz/60Hz bridging converter demand for IT load matching. The Department of Energy enforces NEMA MG1 and IEEE 519 compliance that dictates harmonic emission limits for motor-drive systems. Oil and gas platforms in the Gulf of Mexico deploy medium-voltage drives for subsea pumping electrification at extreme depths.
Germany
Automotive manufacturing retrofits and steel rolling mill automation accelerate voltage source inverter replacement under tightening EU Ecodesign Directive efficiency tiers. The country's Federal Network Agency coordinates grid interconnection standards that influence converter specification for industrial facilities. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate procurement of precision motor control systems for machine tool applications.
China
Steel rolling mills and manufacturing automation in Jiangsu and Zhejiang provinces drive voltage source inverter volumes as domestic manufacturers accelerate IGBT-to-SiC transitions. GB 30253-2013 efficiency standards and forthcoming tier upgrades mandate IE4-equivalent performance for motors above 7.5kW. Yangtze River Delta industrial corridors concentrate demand for medium-voltage drive architectures in heavy process industries.
India
State-level electricity duty exemptions for efficient drives unlock replacement demand in Maharashtra, Gujarat, and Tamil Nadu manufacturing corridors. The Bureau of Indian Standards energy efficiency labeling program shapes procurement criteria for industrial automation retrofits. Pulp and paper operations in Western India pilot equipment-as-a-service contracting models for drives above 500kW.
Singapore
Hyperscale data center facilities require 400Hz ground power units and grid bridging converters for aircraft and IT load simulation. Building retrofits specify integrated bypass and harmonic filtering for centrifugal chiller and air-handling unit drives under ASHRAE 90.1 benchmarks. The city-state's position as a regional cloud infrastructure hub concentrates procurement authority for high-efficiency conversion systems.
Global Frequency Converter Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive power electronics divisions, creating a tiered structure where scale-driven manufacturers compete against specialized drive architects. Siemens AG and ABB Ltd anchor the premium tier through integrated automation portfolios, while Danfoss A/S occupies a focused position in building efficiency applications. Strategic moves concentrate on semiconductor substrate transitions and outcome-based service contracting that displaces capital purchase models for large-scale installations.
Within the diversified industrial tier, Siemens AG, ABB Ltd, and Danfoss A/S represent distinct geographic and application anchoring strategies. Siemens AG leverages its European manufacturing footprint to sustain long-term service relationships with industrial automation clients. ABB Ltd anchors its positioning through medium-voltage drive expertise for heavy process industries. Danfoss A/S exemplifies specialization dominance via HVAC and refrigeration compressor control solutions that capture building efficiency retrofit cycles.
| Leading Market Players |
|---|
| General Electric Company |
| Georator Corporation |
| ABB Ltd |
| Magnus Power Private Limited |
| Aplab Ltd |
| Siemens AG |
| NR Electric Co. Ltd. |
| KGS Electronics, Inc. |
| Danfoss A/S |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month IEC 61800-4 certification timelines compress inventory buffers for medium-voltage architectures and concentrate pricing power among pre-qualified suppliers serving German steel mills and Gulf of Mexico offshore platforms.
Pricing Analysis
Cost-plus contracts with silicon carbide wafer indexation dominate procurement above 500kW, tethering converter margins to Wolfspeed and Coherent substrate pricing. Price differentiation separates IEC 61800-9-2 IE4-certified units from standard-efficiency drives in European tenders. Pricing pressure stems from integrated motor-drive substitution below 75kW, where permanent magnet synchronous motors erode discrete converter attach rates. Data center operators exhibit lowest price sensitivity due to 97% efficiency mandates, while Indian manufacturing corridors show highest sensitivity under BIS labeling programs.
Supply Chain Analysis
Forty-five to sixty days of strategic SiC MOSFET inventory anchors converter production schedules against Wolfspeed substrate allocation volatility. Supply concentrates in Germany for precision machine tool drives, China for steel rolling mill volumes, and the United States for data center bridging units. Raw material dependencies span silicon carbide wafers, IGBT modules, and DC-link film capacitors. Single-source vulnerability in 6-inch SiC substrate supply creates allocation risk. Distribution runs through Amazon Business and Alibaba 1688 for standard ratings below 100kW, bypassing traditional electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frequency converter market sits in early-cycle expansion as silicon carbide semiconductor transitions unlock new efficiency tiers and data center load bridging creates dedicated product demand across incompatible grid standards.
For Market Incumbents: Secure captive SiC wafer supply through long-term offtake agreements with Wolfspeed or Coherent to insulate margins from substrate allocation volatility. Anchor service revenue through equipment-as-a-service contracting for mining and pulp and paper installations above 500kW, displacing capital purchase models that commoditize hardware. For New Entrants and Emerging Players: Lead with specialized HVAC and refrigeration compressor control solutions targeting building efficiency retrofits in Singapore and Frankfurt under ASHRAE 90.1 and EU Ecodesign Directive mandates. Penetrate through direct-to-fleet digital distribution on Amazon Business, capturing margin and lead time advantages over incumbent channel structures. For Investors and Strategic Acquirers: Long-term, this sits as a semiconductor-transition play because SiC MOSFET adoption redefines product architectures and creates acquisition opportunities among IGBT-dependent mid-tier suppliers. Target medium-voltage drive specialists with IEC 61800-4 certification capabilities. Watch hydrogen electrolyzer integration as the inflection signal, where 100MW+ PEM and alkaline plants require precision AC-AC conversion specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Semiconductor Transition | Enables 50kHz switching frequencies that reduce filter volumes by 60% in data center applications. |
| Equipment-as-a-Service Contracting | Finnish and Australian mining pilots reshape vendor-customer relationships through performance-guaranteed availability. |
| Direct-to-Fleet Digital Distribution | Amazon Business and Alibaba 1688 bypass electrical distributors for standard ratings below 100kW. |
| Hydrogen Electrolyzer Integration | 100MW+ PEM and alkaline plants create new power class specifications for precision frequency matching. |
| India Industrial Automation Retrofit | Maharashtra and Gujarat manufacturing corridors unlock replacement demand under BIS efficiency labeling. |
Research Methodology
A spread of perspectives from plant engineers at German automotive manufacturers, procurement leads at hyperscale data center operators, aftermarket service heads at mining installations, and channel partners in electrical distribution converged on the working assumptions. Primary interview insights combined with secondary validation from SEC filings, customs and trade data, IEC standard documentation, and hyperscaler capex disclosures. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates.
Segmentation dimensions modeled span product architecture, control methodology, semiconductor substrate, application duty cycle, and end-user industry vertical across the projection horizon. CAGRs derived from regression analysis against industrial automation capex cycles, efficiency regulation enforcement patterns, and data center construction pipelines. Forecast inputs include SiC substrate cost curves, IEC 61800 efficiency tier adoption rates, and integrated motor-drive penetration in fractional horsepower classes.
Forecasts assume regulatory continuity in EU Ecodesign Directive enforcement, China's GB 30253 tier upgrades, and US Department of Energy NEMA MG1 compliance; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Distribution Voltage Regulator Market
Power Systems
Global Fault Current Limiter Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
PV Inverter Market
Power Systems
Global Gan Power Device Market
Power Systems
Global Flexible Batteries Market
Power Systems
Digital Inverter Market
Power Systems
North America Telecom Power Systems Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Battery Racks Market
Power Systems
Grid Forming Inverters Market
Power Systems
Automotive Inverters Market
Power Systems
E-Axle Inverter and Control Unit Systems Market
Power Systems
Global Plasma Generators Market
Power Systems
Battery Charge Controller Market