
 Latin America Rigid Bulk Packaging Market | 2026-2036
Latin America Rigid Bulk Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Rigid Bulk Packaging Market Insights
Food and beverage processing is shifting toward intermediate bulk containers for liquid ingredient handling across Latin America. Greif Inc. dominates steel drum fabrication for chemical exporters in Chile and Peru. Mauser Packaging Solutions leverages its reconditioning network to extend container life cycles for agricultural cooperatives. Schoeller Allibert specializes in foldable large containers for automotive parts distribution from Mexican assembly plants.
Latin America Rigid Bulk Packaging comprises durable, stackable shipping receptacles typically exceeding 450 liters in capacity, engineered from high-density polyethylene, galvanized steel, or treated hardwood to withstand multi-trip logistics cycles and forklift handling stresses. The category serves primarily for transporting raw materials, semi-finished goods, and bulk commodities between manufacturing sites and distribution hubs. Plastic containers lead volume adoption due to corrosion resistance and lightweight properties, while metal drums retain premium positioning for hazardous chemical compliance. Wood pallets constitute the most mature segment with thin margin pools, whereas custom-sized plastic crates represent the fastest structural expansion as pharmaceutical cold chains proliferate.
Brazil's ANVISA pharmaceutical serialization mandates and Mexico's NOM-252 environmental packaging standards shape product certification requirements for cross-border shipments. Argentina's INTI quality institute enforces dimensional tolerances for wooden pallets entering Mercosur trade corridors. Stakeholders must monitor evolving extended producer responsibility frameworks across Andean Community nations to anticipate compliance-driven material substitutions.
Market Dynamics
Intermediate bulk containers are displacing traditional steel drums across Brazil's agrochemical export corridors as soybean processors seek lightweight, collapsible alternatives for multi-modal grain shipments.
Growth Catalysts
- ANVISA pharmaceutical serialization mandates:Brazil's track-and-trace requirements for drug packaging are accelerating demand for RFID-enabled plastic bulk containers in pharmaceutical distribution networks.
- Post-industrial resin formulations:Mexico's NOM environmental standards for plastic recyclability are redirecting procurement toward reprocessed HDPE formulations in food-grade applications.
- Automotive assembly consolidation:Querétaro's manufacturing belt is driving foldable large container adoption for just-in-time parts sequencing from tier-one suppliers.
Market Restraints
- Galvanized steel price volatility:Input cost swings for zinc-coated steel sheet are compressing margins for drum fabricators serving Chilean chemical exporters.
- Single-source HDPE concentration:Brazil's southeastern petrochemical corridor dominates resin supply, creating vulnerability for container molders in Argentina and Colombia.
- Wooden pallet dimensional enforcement:Argentina's INTI quality institute mandates are raising compliance costs for cross-border Mercosur pallet movements.
Strategic Opportunities
- Peruvian mining logistics:Untapped demand for corrosion-resistant IBCs exists in copper concentrate transport from Andean highland extraction sites to Pacific port terminals.
- Extended producer responsibility frameworks:Emerging Andean Community regulations will create closed-loop container services for agricultural cooperatives seeking compliance arbitrage.
- RFID-embedded tracking convergence:Integration of IoT sensors with collapsible bulk containers is enabling real-time inventory visibility for cold chain pharmaceutical distributors.
Industry Challenges
- Reconditioning technician scarcity:Mexico's container washing and repair networks lack certified personnel for hazardous chemical residue handling under NOM standards.
- Multi-jurisdiction certification timelines:Cross-border shipments require simultaneous ANVISA, COFEPRIS, and INVIMA approvals, extending product launch cycles for pharmaceutical packaging.
- Legacy wooden pallet infrastructure:Established hardwood supplier relationships and sunk capital in existing pool systems resist conversion to plastic pallet pooling models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Rigid Bulk Packaging Market |
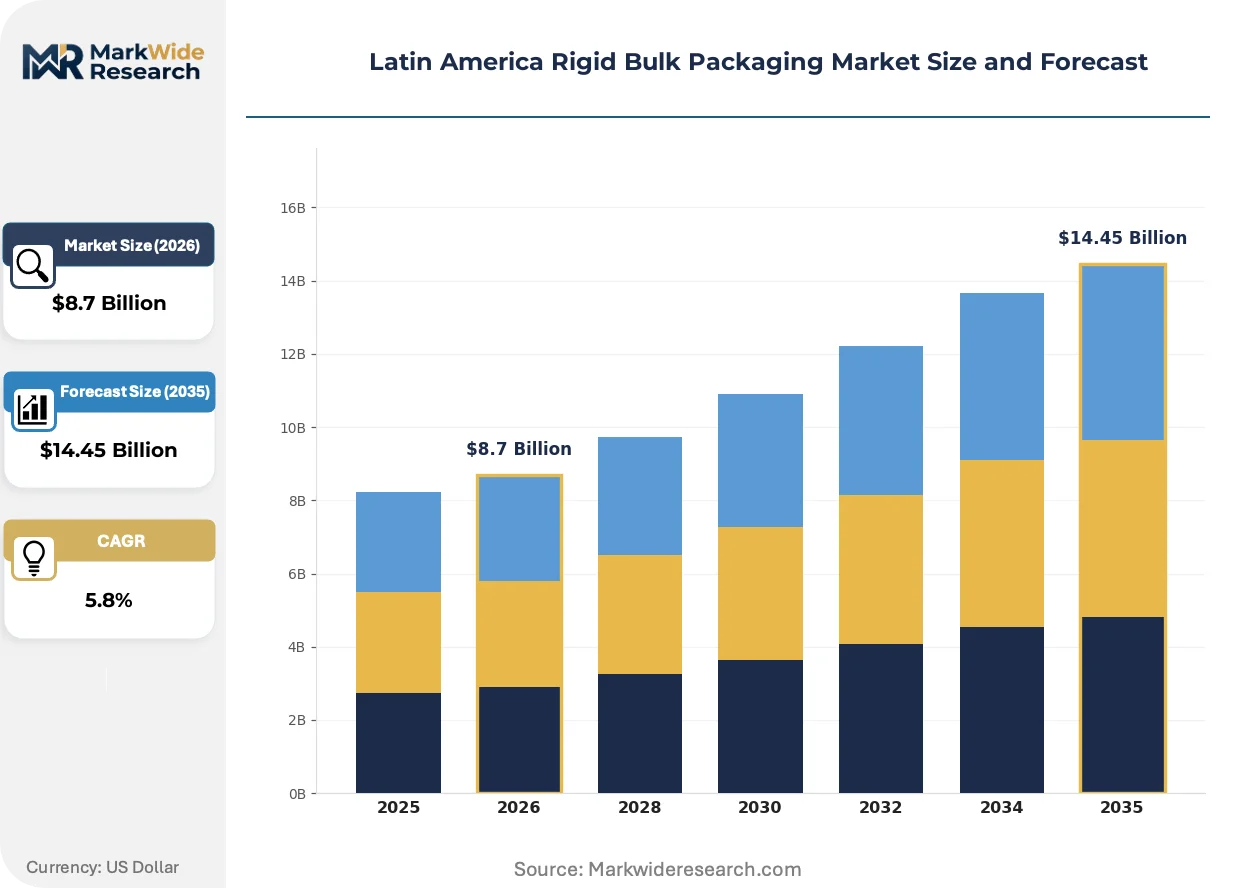
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pallets, Crates, Containers, Drums Material: Plastic, Wood, Metal, Glass End Use Industry: Food & Beverage, Pharmaceuticals, Chemicals, Agriculture Size: Small, Medium, Large, Custom |
| Companies Covered | ORBIS Corporation, ALPLA Group, Greif Inc., Monoflo International, Rheem Chilena SpA, Mauser Packaging Solutions, SCHUTZ GmbH and Co KGaA, Schoeller Allibert, Berry Global Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Rigid Bulk Packaging Market Trends and Innovations
Material substitution and digital traceability are converging to reshape container specifications across Latin American logistics networks, with sustainability mandates accelerating format experimentation.
Co-extruded barrier-layer HDPE is unifying oxygen and moisture protection within single-wall IBC constructions. Brazilian orange juice concentrate exporters are adopting these vessels at pace to replace laminated bag-in-box formats for ocean freight. This unifying construction is compressing the traditional separation between bulk liquid handling and aseptic packaging tiers.
Mexico's NOM-252 environmental packaging standards are mandating minimum post-consumer recycled content thresholds for plastic shipping containers. Industrial consequence includes reformulation investments by domestic resin compounders and qualification delays for imported virgin-material containers. Food processors in Guadalajara's manufacturing cluster are responding by qualifying local reprocessed resin suppliers ahead of enforcement deadlines.
Container pooling models are replacing outright purchase arrangements among agricultural cooperatives in São Paulo state logistics corridors. Leasing platforms with integrated washing and tracking services are displacing single-use corrugated bulk bins for seasonal harvest cycles. This shift is most visible in corn and soybean handling operations where asset utilization rates determine per-ton logistics costs.
Latin America Rigid Bulk Packaging Market Segmentation
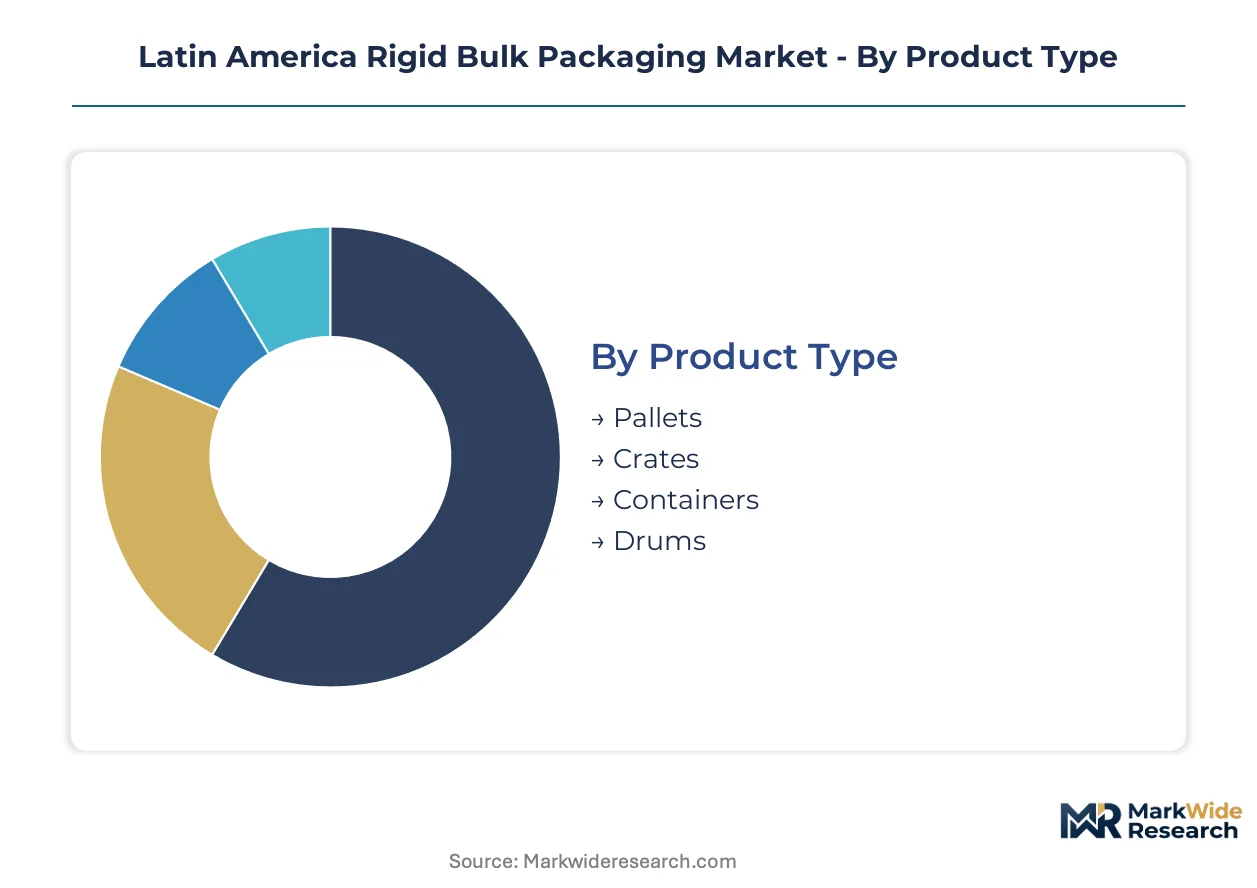
Container specifications across Latin America diverge sharply between standalone logistics assets and integrated supply chain systems. Procurement patterns in São Paulo and Querétaro reveal how material choices and size configurations map to distinct handling requirements across agrochemical corridors and pharmaceutical cold chains.
Product Type:
Standalone pallet and crate formats dominate commodity flows, while embedded container systems serve specialized chemical and pharmaceutical handling protocols.
- Pallets:Hardwood and plastic pallet platforms constitute the foundational layer for forklift-accessible bulk handling across Brazilian soybean export terminals. Argentina's INTI dimensional mandates are forcing harmonization with Mercosur cross-border specifications, raising compliance costs for wooden pallet pool operators.
- Containers:Intermediate bulk containers with collapsible sidewalls are displacing fixed-wall alternatives in Mexico's Querétaro automotive parts sequencing networks. ANVISA pharmaceutical serialization requirements are accelerating RFID-embedded plastic container adoption for drug distribution across Brazil's state logistics corridors.
- Crates:Custom-sized plastic crates serve pharmaceutical cold chain requirements with integrated insulation layers for temperature-sensitive biologics.
- Drums:Steel drum fabrication retains premium positioning for hazardous chemical compliance in Chilean and Peruvian mining chemical exports.
Pallets lead volumes today; containers are gaining share fastest.
Material:
Cost tiers separate commodity-grade wood from performance-engineered synthetics, with metal commanding premium positioning for regulated hazardous applications.
- Plastic:High-density polyethylene formulations dominate corrosion-resistant applications across Brazil's agrochemical export corridors. Mexico's NOM-252 post-consumer recycled content thresholds are redirecting procurement toward reprocessed resin compounders in Guadalajara's manufacturing cluster.
- Metal:Galvanized steel drums serve hazardous chemical compliance requirements for Chilean copper concentrate transport and Peruvian mining chemical shipments. Zinc-coated steel sheet price volatility is compressing fabricator margins serving Pacific port terminal operators.
- Wood:Treated hardwood pallets constitute the most mature segment with thin margin pools and established supplier relationships resisting conversion to plastic pooling models.
- Glass:Specialized glass-lined containers serve ultra-pure pharmaceutical ingredient handling for ANVISA-regulated drug manufacturing facilities.
Plastic leads volumes today; metal retains the steepest premium pricing power.
End Use Industry:
Application-driven specifications range from aseptic food-grade barriers to explosion-proof chemical handling systems across Latin American manufacturing belts.
- Agriculture:Seasonal harvest cycles in São Paulo state logistics corridors are driving container pooling model adoption over outright purchase arrangements for corn and soybean handling. Asset utilization rates determine per-ton logistics costs for agricultural cooperatives.
- Chemicals:Hazardous material transport from Andean highland extraction sites to Pacific port terminals demands corrosion-resistant IBC specifications for copper concentrate movements.
- Food & Beverage:Co-extruded barrier-layer HDPE vessels are unifying oxygen and moisture protection for Brazilian orange juice concentrate ocean freight exports.
- Pharmaceuticals:ANVISA track-and-trace mandates combined with COFEPRIS and INVIMA multi-jurisdiction approvals are extending product launch cycles for RFID-enabled bulk packaging in regional drug distribution networks.
Agriculture leads volumes today; pharmaceuticals are expanding most quickly.
Size:
Volume configurations align with handling infrastructure constraints across Latin America's fragmented logistics networks, from manual lift gates to automated port systems.
- Large:Exceeding 450-liter capacities, these formats serve multi-modal grain shipments and bulk liquid handling for soybean processors seeking lightweight alternatives to traditional steel drums.
- Custom:Tailored dimensional specifications address pharmaceutical cold chain proliferation and automotive just-in-time parts sequencing requirements in Mexican assembly plant supply networks.
- Medium:Standardized intermediate capacities balance forklift handling efficiency with warehouse space optimization for regional distribution hubs.
- Small:Compact formats serve last-mile pharmaceutical delivery and specialized chemical sampling applications with manual handling requirements.
Large formats lead volumes today; custom specifications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting procurement flows as manufacturers relocate to jurisdictions with lower compliance burdens. Brazil's ANVISA mandates and Mexico's NOM standards create divergent cost structures that shape cross-border investment decisions. Container fabricators exploit these gaps by qualifying production in lower-cost corridors while maintaining distribution proximity to demand centers.
Brazil
São Paulo state logistics corridors drive container pooling adoption for corn and soybean handling. ANVISA pharmaceutical serialization mandates accelerate RFID-enabled plastic bulk container demand in drug distribution networks. Campinas and Santos port clusters concentrate reconditioning infrastructure for agricultural cooperatives.
Mexico
Querétaro's automotive manufacturing belt demands foldable large containers for just-in-time parts sequencing. NOM-252 environmental standards redirect procurement toward post-industrial resin formulations in food-grade applications. Guadalajara's manufacturing cluster hosts domestic reprocessed resin compounders.
Argentina
INTI quality institute dimensional mandates raise compliance costs for wooden pallet movements across Mercosur corridors. Buenos Aires province agricultural terminals require harmonized specifications for cross-border grain shipments. Rosario's river port complex anchors soybean export logistics infrastructure.
Chile
Copper concentrate transport from Andean highland extraction sites to Pacific port terminals demands corrosion-resistant IBC specifications. Mining chemical exports retain galvanized steel drum requirements despite zinc price volatility. Antofagasta and Valparaíso port operators handle hazardous material compliance for Pacific trade.
Peru
Untapped demand exists for corrosion-resistant IBCs in mining logistics from Andean extraction sites to Callao port terminals. The country's national mining regulator enforces transport container specifications for concentrate movements. Arequipa's industrial corridor hosts emerging container service providers.
Latin America Rigid Bulk Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The market exhibits moderate consolidation with tiered positioning between multinational fabricators and regional reconditioning networks. Three archetypes dominate: steel drum specialists serving hazardous chemical compliance, plastic container molders leveraging resin proximity, and pooling platform operators managing asset utilization cycles. Capacity expansion and strategic partnerships represent the primary competitive vectors as players seek geographic coverage and regulatory qualification breadth.
Among North American-based fabricators, ORBIS Corporation and Greif Inc. exemplify the scale-driven archetype with established regional production footprints. Mauser Packaging Solutions occupies a position within the reconditioning and life-cycle extension tier, leveraging service network density. Schoeller Allibert represents the foldable container specialization vector for automotive and pharmaceutical logistics applications.
| Leading Market Players |
|---|
| ORBIS Corporation |
| ALPLA Group |
| Greif Inc. |
| Monoflo International |
| Rheem Chilena SpA |
| Mauser Packaging Solutions |
| SCHUTZ GmbH and Co KGaA |
| Schoeller Allibert |
| Berry Global Inc |
| Others |
Pricing and Supply Chain Analysis
Galvanized steel sheet costs cascade from zinc price volatility through Chilean drum fabricator margins into premium pricing tiers for hazardous chemical compliance. HDPE resin concentration in Brazil's southeastern petrochemical corridor concentrates pricing power among domestic compounders serving São Paulo state logistics networks.
Pricing Analysis
Distributor margins compress where reconditioning networks compete with virgin container sales for agricultural cooperative procurement in Brazil. Three-tier pricing structure across premium certified, standard industrial, and economy pooled tiers separates ANVISA-compliant pharmaceutical containers from commodity-grade agricultural formats. Pricing pressure stems from zinc-coated steel input volatility hitting Chilean mining chemical drum fabricators. Agricultural cooperatives exhibit highest price sensitivity due to seasonal asset utilization cycles, while pharmaceutical distributors accept premium tiers for serialization compliance.
Supply Chain Analysis
HDPE resin supply rests on Brazil's southeastern petrochemical corridor, creating single-source vulnerability for Argentine and Colombian container molders. Raw material dependencies center on high-density polyethylene formulations, zinc-coated steel sheet, and treated hardwood pallet stock. Logistics chokepoints emerge at Pacific port terminals handling copper concentrate IBC movements from Andean highland extraction sites. Distribution runs through reconditioning networks with integrated washing services displacing outright purchase arrangements among São Paulo agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where ANVISA pharmaceutical serialization mandates shift procurement toward RFID-enabled premium container specifications.
For Market Incumbents: Cement market position by deepening backward integration into reprocessed resin compounding ahead of NOM-252 enforcement deadlines in Guadalajara. Extend reconditioning network density across Campinas and Santos port clusters to capture agricultural cooperative pooling demand. Channel control through integrated washing and tracking services defends against emerging platform operators. For New Entrants and Emerging Players: Peruvian mining cooperatives represent an underserved buyer archetype with untapped demand for corrosion-resistant IBC specifications in copper concentrate transport. Arequipa's industrial corridor offers geographic white space with limited incumbent reconditioning infrastructure. A service-led go-to-market bundling container leasing with Pacific port terminal logistics integration penetrates fastest. For Investors and Strategic Acquirers: Consolidation pressure builds where reconditioning technician scarcity under NOM standards fragments service quality across Mexican container washing networks. Long-term viability favors platform operators with asset utilization software and closed-loop compliance services for Andean Community extended producer responsibility frameworks. Watch RFID-embedded tracking adoption rates in Brazilian pharmaceutical distribution as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reprocessed Resin | Guadalajara compounders qualify local suppliers ahead of NOM-252 recycled content thresholds. |
| RFID-Enabled Container Platform Launch | ANVISA serialization mandates create premium tier for real-time pharmaceutical inventory visibility. |
| Reconditioning Network Expansion | Campinas and Santos clusters capture agricultural cooperative pooling demand in São Paulo corridors. |
| Peruvian Mining Logistics Partnership | Arequipa service providers bridge Andean extraction sites to Callao port terminal IBC specifications. |
| Extended Producer Responsibility Compliance Service | Closed-loop container services arbitrage emerging Andean Community regulatory frameworks for cooperatives. |
Research Methodology
Direct dialogue with container fabricator plant managers, agricultural cooperative procurement leads, pharmaceutical distribution channel partners, and resin compounder technical directors grounded qualitative findings. Secondary validation drew from ANVISA regulatory filings, NOM-252 enforcement documentation, Mercosur customs trade data, and Brazilian petrochemical corridor production disclosures. Bottom-up demand modeling triangulated against top-down market sizing across material and end-use dimensions.
Bottom-up volume builds aggregated segment outputs across plastic, metal, wood, and glass material tiers combined with agriculture, chemicals, food and beverage, and pharmaceutical end-use applications. Top-down cross-checks validated through HDPE resin consumption patterns and container pooling fleet deployment rates across São Paulo and Querétaro logistics corridors. CAGRs derived from trend extrapolation of regulatory compliance-driven substitution cycles and asset utilization optimization in seasonal harvest handling.
Underlying measurement precision varies by segment; pharmaceutical and automotive container specifications carry tighter precision than commodity wooden pallet volumes. Forecasts embed assumptions regarding NOM-252 enforcement timing and ANVISA serialization rollout pace. Regulatory delay or accelerated Andean Community extended producer responsibility adoption warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Rigid Industrial Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
Rigid Sleeve Boxes Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
US Rigid Thermoform Plastic Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Mono-Material Trays Market