
 Morocco Rigid Plastic Packaging Market | 2026-2036
Morocco Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Rigid Plastic Packaging Market Insights
Market Context
Polyethylene terephthalate is restructuring rigid packaging economics as converters substitute heavier glass and metal formats across Morocco's beverage supply chain. Plastipak Holdings Inc. leverages its preform manufacturing footprint to serve carbonated soft drink bottlers near Casablanca. Alpla Group anchors regional supply through blow-molding operations that reduce resin transport costs for personal care brands. Sumilon Eco PET SARL differentiates via recycled-content capabilities that align with European export requirements.
Technical Definition and Segment Structure
Morocco rigid plastic packaging encompasses thermoformed and blow-molded containers with wall thickness exceeding 0.25 millimeters, engineered from polyethylene, polypropylene, PVC, or polystyrene to provide dimensional stability during filling, transport, and shelf display. Bottles command the largest volume share within product type segmentation, though trays exhibit faster conversion growth as fresh produce exporters adopt modified-atmosphere formats. Food and beverage end users generate the dominant value pool, while healthcare applications concentrate margin where sterilization-grade polypropylene commands certification premiums.
Regulatory Framework and Outlook
BIS-equivalent Moroccan standards authority and CDSCO-aligned national pharmaceutical regulator enforce migration limits and material traceability rules that dictate resin grade selection across food and drug contact applications. The country's central environmental agency advances extended producer responsibility consultations that would obligate post-consumer collection infrastructure investment. Stakeholders must monitor draft packaging waste decrees that could mandate minimum recycled content thresholds before committing to virgin resin capacity expansion.
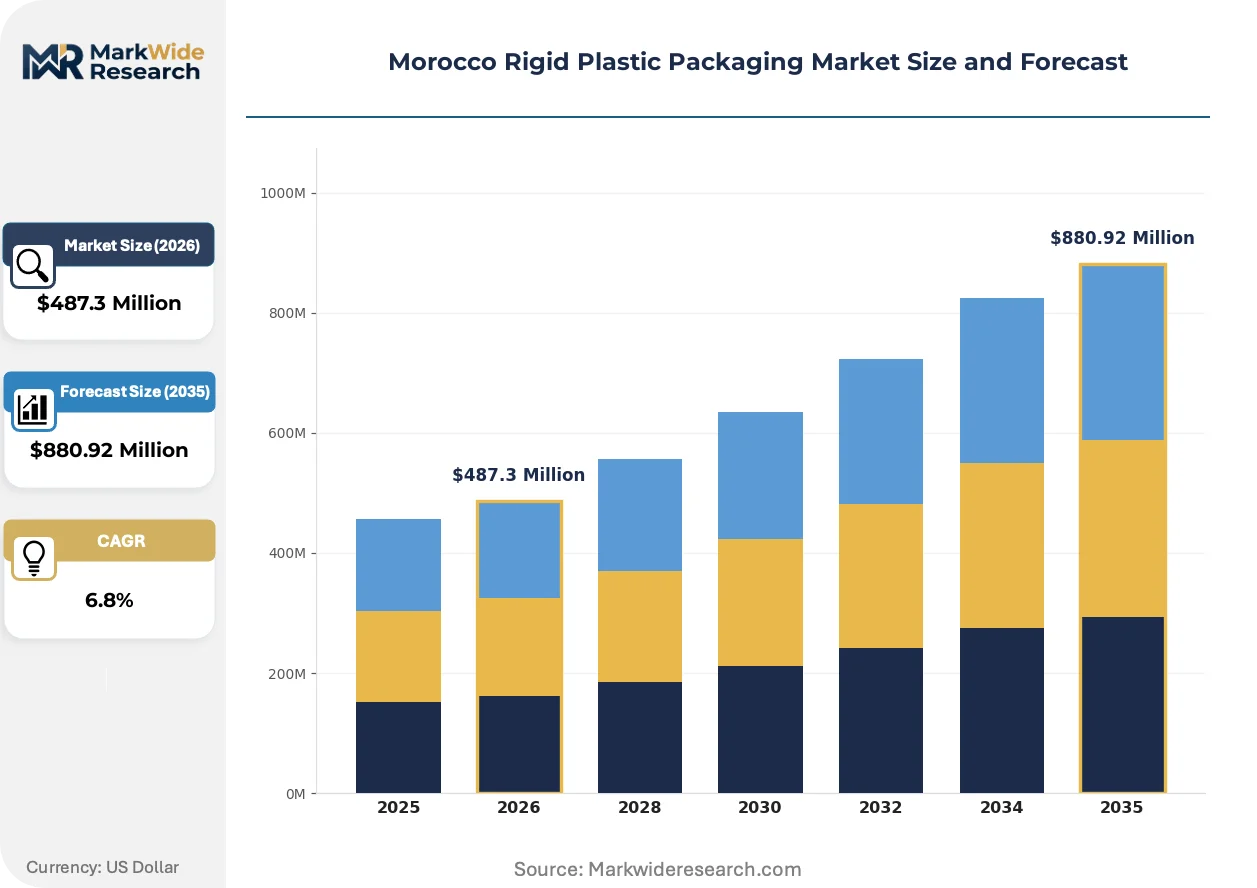
Market Dynamics
Polyethylene terephthalate preform localization is compressing supply chains as Moroccan converters backward-integrate blow-molding capacity to serve Casablanca-Settat beverage clusters. This resin-grade standardization is forcing equipment upgrades across mid-tier processors.
Growth Catalysts
- Extended Producer Responsibility consultations:Morocco's central environmental agency is advancing draft decrees that would mandate post-consumer collection infrastructure, creating investment certainty for recycling capacity.
- Dairy sector PET conversion:Food and beverage processors are expanding procurement of barrier-enhanced bottles for ultra-high-temperature milk distribution, displacing multilayer carton formats.
- Casablanca-Settat industrial corridor concentration:Port-proximate conversion clusters reduce inland resin transport costs and enable just-in-time delivery to export-oriented bottlers.
Market Restraints
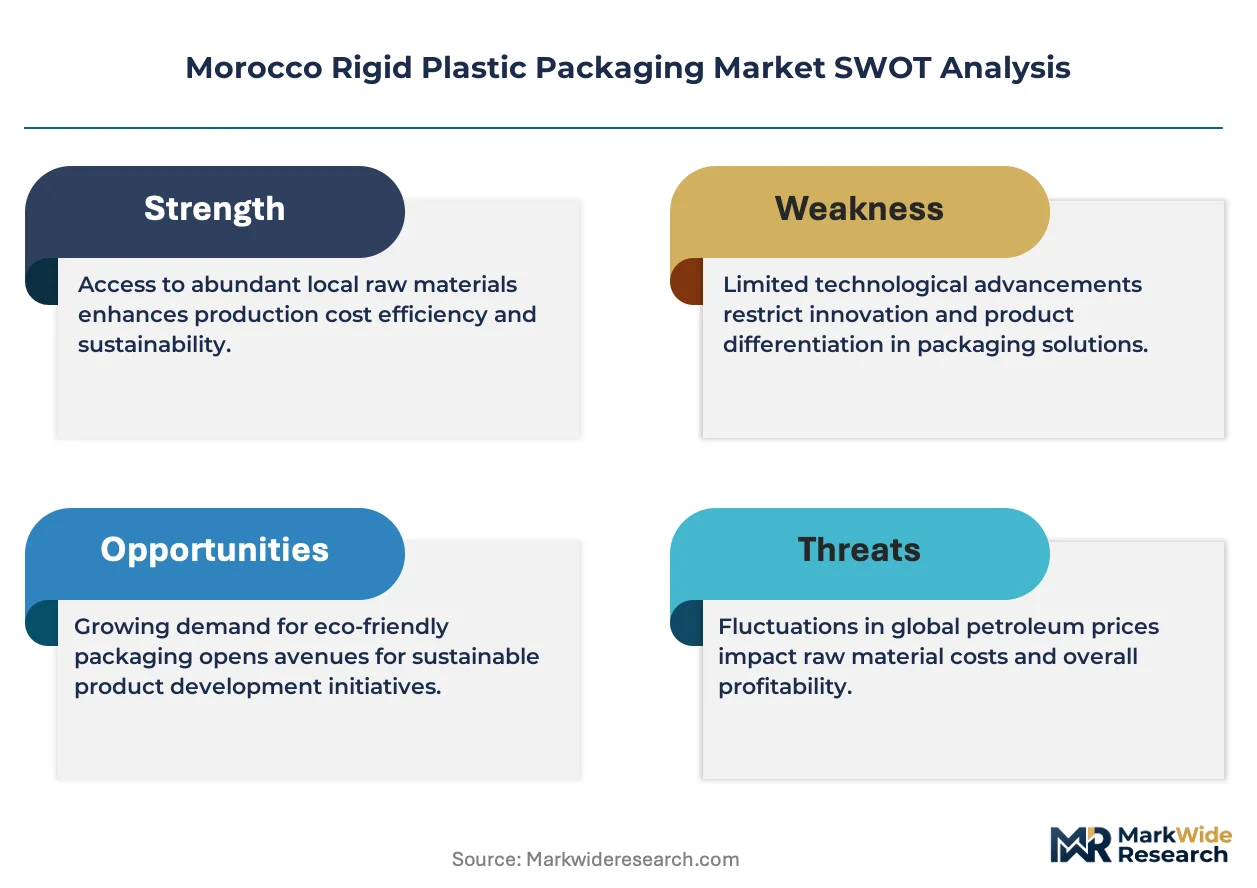
- Polymer price volatility:Virgin polyethylene terephthalate resin costs fluctuate with crude oil benchmarks, squeezing converter margins during upstream spikes.
- Import dependency for barrier additives:Oxygen-scavenging masterbatches and multilayer coextrusion equipment concentrate among European suppliers, exposing Moroccan processors to euro-denominated procurement risk.
- Glass persistence in premium edible oils:Traditional packaging formats retain shelf presence in high-margin olive oil segments where consumer perception favors inert materials.
Strategic Opportunities
- Recycled-content certification for European export:EU Packaging and Packaging Waste Regulation alignment creates premium positioning for Moroccan converters achieving food-grade rPET traceability.
- Modified-atmosphere tray adoption:Fresh produce exporters to European markets are converting from bulk shipment to retail-ready packaging, opening thermoforming equipment demand.
- Healthcare sterilization-grade polypropylene:CDSCO-aligned national pharmaceutical regulator certification requirements create margin pools for converters investing in cleanroom blow-molding capability.
Industry Challenges
- Food-contact migration testing capacity:BIS-equivalent Moroccan standards authority protocol compliance requires specialized analytical laboratories that remain scarce outside Casablanca.
- Multilayer coextrusion technician shortage:Barrier-performance engineering demands skilled operators for tie-layer optimization and defect detection, with training programs lagging equipment installation.
- Legacy injection-stretch-blow equipment retrofit:Existing preform production lines require substantial capital outlay for hot-fill and aseptic compatibility upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Rigid Plastic Packaging Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Trays End User: Food & Beverage, Healthcare, Personal Care, Household Material: Polyethylene, Polypropylene, PVC, Polystyrene Application: Packaged Food, Pharmaceuticals, Cosmetics, Cleaning Agents |
| Companies Covered | Alpla Group, Plastipak Holdings Inc., Grief Inc., Pet Preforms Morocco, Bericap Holding GmbH, Sumilon Eco PET SARL, Blowtec Morocco, Intel Plast, Mikafric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Rigid Plastic Packaging Market Trends and Innovations
Lightweighting algorithms and recycled-content traceability systems are restructuring competitive requirements across Moroccan rigid packaging procurement. These shifts are compressing the viable supplier base while opening specialty niches.
Mono-material polyethylene terephthalate structures with integrated barrier coatings are absorbing functions previously delivered by multilayer coextrusion or metallized films. Dairy processors are adopting these formats for extended-shelf-life applications at accelerated trial-to-contract cycles. The technology is absorbing capital allocation that would otherwise flow to aluminum-laminated carton lines, consolidating equipment vendor relationships around coating-system specialists.
Morocco's central environmental agency is advancing extended producer responsibility frameworks that would obligate brand owners to finance post-consumer collection infrastructure. This policy trajectory is redirecting converter investment toward rPET decontamination and reprocessing capability. Food-contact applications face the steepest compliance timelines, with exporters to European markets already certifying chain-of-custody documentation.
Consolidated procurement by multinational beverage bottlers is compressing supplier qualification cycles and unbundling technical service from resin supply contracts. Moroccan converters are responding by embedding application-development engineers directly at customer formulation facilities. This pattern concentrates most visibly in Casablanca-Settat, where carbonated soft drink volume anchors regional preform demand.
Morocco Rigid Plastic Packaging Market Segmentation
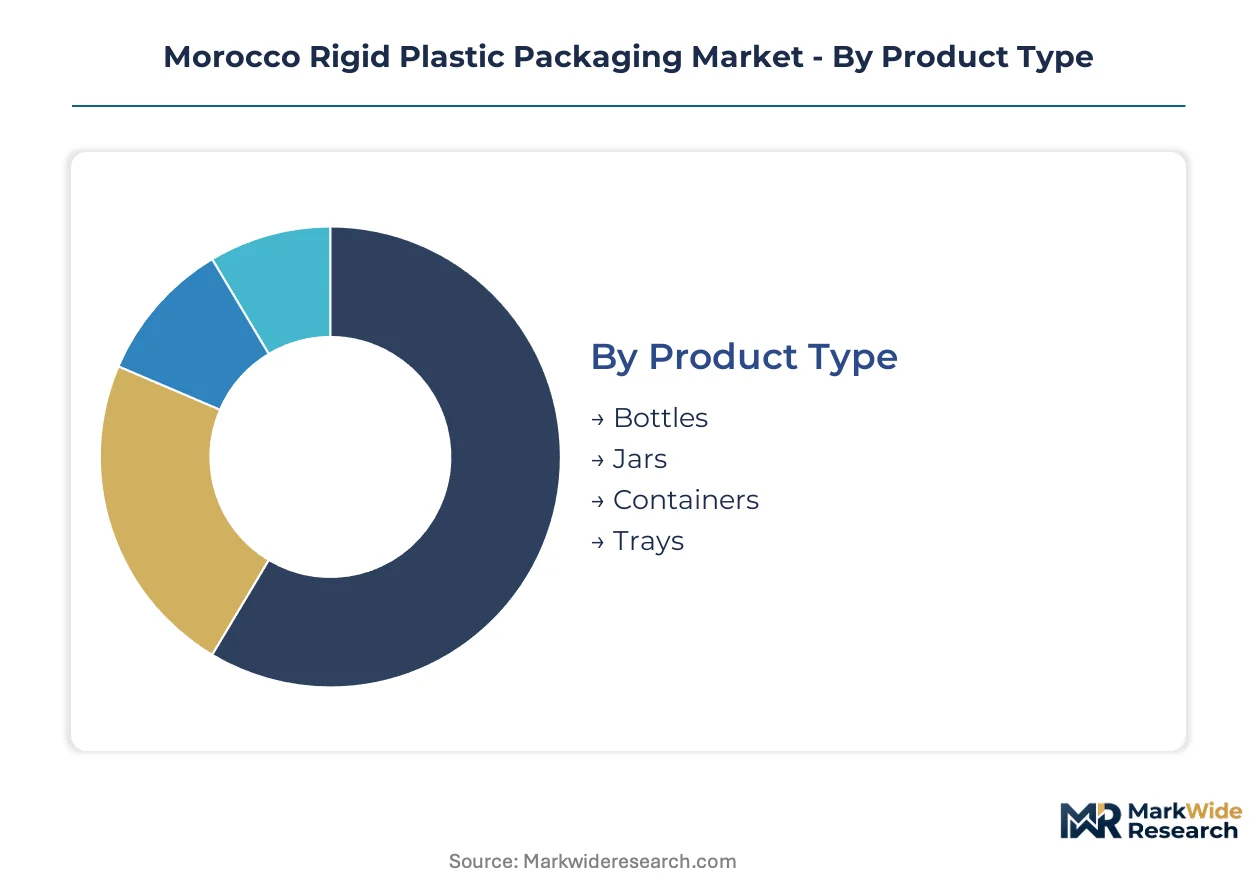
Rigid plastic packaging in Morocco fragments across material grades, forming technologies, and end-use specifications that dictate barrier requirements and regulatory compliance pathways. Understanding these segment boundaries clarifies where converters can capture margin premiums versus competing on throughput.
Product Type:
Wall thickness and forming method distinguish structural performance across container geometries, with blow-molding and thermoforming equipment choices locking in production economics for years.
- Bottles:Stretch-blow-molded polyethylene terephthalate dominates carbonated soft drink and edible oil distribution, with preform localization near Casablanca-Settat reducing resin logistics costs for high-volume bottlers.
- Trays:Thermoformed polypropylene and polystyrene structures are expanding fastest as fresh produce exporters adopt modified-atmosphere formats for European retail compliance, displacing bulk shipment methods.
- Containers:Injection-molded polypropylene tubs serve dairy and margarine segments where snap-fit lids and stackability reduce secondary packaging.
- Jars:Wide-mouth polyethylene terephthalate and PVC formats retain position in preserves and condiments where hand-scoop access and clarity drive consumer preference.
Mature deployment sits with bottles. Newer deployment is concentrated in trays.
End User:
Customer procurement sophistication varies sharply, with multinationals imposing chain-of-custody requirements that filter accessible supplier pools.
- Food & Beverage:Dairy processors and edible oil bottlers in Casablanca-Settat drive polyethylene terephthalate preform demand, with ultra-high-temperature milk applications requiring barrier-enhanced bottle structures that displace multilayer cartons.
- Healthcare:Sterilization-grade polypropylene bottles and containers for pharmaceutical distribution command certification premiums under the country's national pharmaceutical regulator protocols, concentrating margin with converters investing in cleanroom blow-molding.
- Personal Care:Shampoo and lotion bottles in polyethylene and polyethylene terephthalate compete on shelf differentiation through decoration and shape complexity.
- Household:Cleaning agent containers in high-density polyethylene prioritize chemical resistance and cost minimization over aesthetic refinement.
Procurement consolidation concentrates in food and beverage. Margin extraction succeeds most reliably in healthcare.
Material:
Resin selection locks in recycling pathway compatibility and migration limit compliance across food-contact applications.
- Polyethylene terephthalate:Dominates beverage and edible oil bottles with established mechanical recycling streams and European export alignment for rPET content claims.
- Polypropylene:Serves dairy tubs, pharmaceutical containers, and modified-atmosphere trays where steam sterilization tolerance and thermal stability justify premium positioning.
- Polystyrene:Retains cost-sensitive tray and disposable cutlery applications despite pressure from substitution campaigns in European export markets.
- PVC:Persists in pharmaceutical blister packs and certain chemical containers where barrier performance and clarity requirements resist material switching.
Volume leadership belongs to polyethylene terephthalate. Polypropylene delivers the steepest expansion trajectory in healthcare and fresh produce applications.
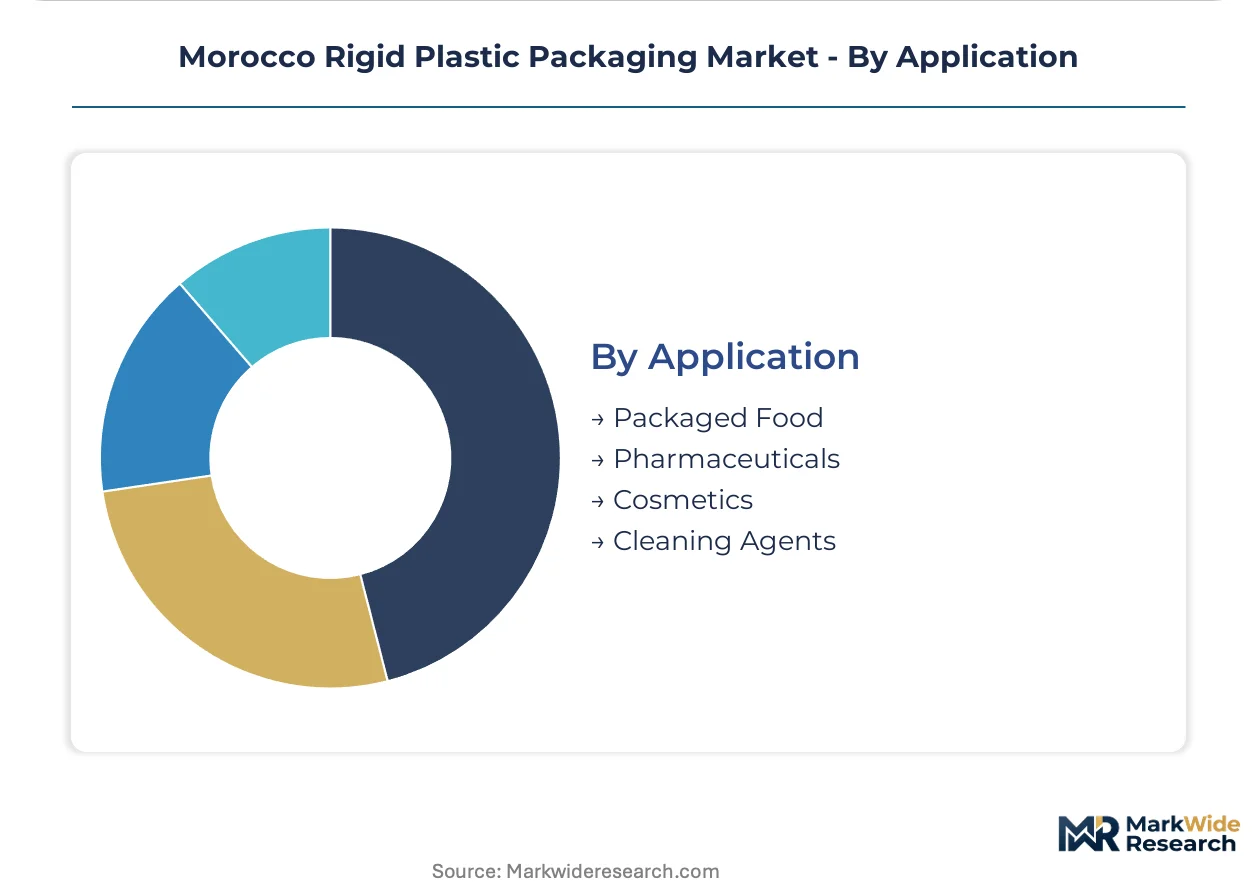
Application:
Regulatory intensity and shelf-life requirements segment the market into distinct specification tiers that reshape competitive dynamics.
- Packaged Food:Modified-atmosphere trays and barrier bottles for dairy, edible oils, and ready meals absorb capital investment as exporters upgrade for European retail compliance.
- Pharmaceuticals:Sterilization-grade containers and blister packs face the country's national pharmaceutical regulator migration testing and material traceability mandates, creating qualification barriers for new entrants.
- Cosmetics:Premium bottles and jars compete through decoration sophistication and shape differentiation rather than functional barrier performance.
- Cleaning Agents:Chemical-resistant containers prioritize cost minimization and stackability for logistics efficiency in distribution to traditional trade channels.
Specification complexity peaks in pharmaceuticals. Volume scaling succeeds most directly in packaged food.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for rigid plastic packaging concentrates in Morocco's Casablanca-Settat corridor, where beverage bottlers and dairy processors cluster near port infrastructure. This coastal concentration shapes resin logistics, conversion capacity placement, and regulatory compliance investment across the national market.
Casablanca-Settat
Carbonated soft drink bottlers and edible oil processors drive polyethylene terephthalate preform procurement throughout this industrial corridor. The country's national standards body enforces food-contact migration limits that elevate barrier-performance requirements for ultra-high-temperature milk distribution. Port-proximate conversion facilities near Mohammedia reduce inland resin transport costs while enabling just-in-time delivery schedules for export-oriented customers.
Rabat-Salé-Kénitra
Pharmaceutical manufacturers in this northern corridor generate sterilization-grade polypropylene demand for drug distribution packaging. The country's national pharmaceutical regulator mandates material traceability protocols that create qualification barriers for new converter entrants. Cleanroom blow-molding operations cluster near Rabat's administrative centers where regulatory filing proximity accelerates certification timelines.
Marrakesh-Safi
Agricultural processing and argan oil bottling sustain regional demand for barrier-enhanced bottles and decorative jars. Extended producer responsibility consultations from the central environmental agency are redirecting investment toward post-consumer collection infrastructure in this tourism-dependent economy. Local converters near Marrakesh are retrofitting equipment for hot-fill compatibility to serve premium edible oil segments.
Fès-Meknès
Dairy cooperatives and olive oil processors in this interior region source preforms from coastal suppliers while pressing for localized blow-molding capacity. Food safety protocols from the national standards body require specialized analytical testing that remains scarce outside major metropolitan laboratories. Industrial zones near Fès are attracting thermoforming investment for modified-atmosphere tray production serving European fresh produce export channels.
Tanger-Tetouan-Al Hoceima
Free zone manufacturing and automotive supplier parks are stimulating demand for industrial containers and chemical-resistant packaging formats. Port modernization at Tanger Med is drawing multinational beverage bottlers seeking re-export platforms into European markets. Regional converters are certifying recycled-content traceability systems to align with EU Packaging and Packaging Waste Regulation requirements for cross-border shipments.
Morocco Rigid Plastic Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational preform suppliers commanding beverage volumes while domestic converters capture regional dairy and produce packaging. The market structure tiers around three archetypes: global resin-integrated players with captive preform supply, regional specialists leveraging recycled-content certification for export compliance, and domestic fabricators serving traditional trade channels through cost-minimization strategies. Competitive moves concentrate on backward integration into blow-molding capacity and strategic partnerships with European equipment vendors for barrier-coating technology access.
Within the multinational tier, Plastipak Holdings Inc. and Alpla Group exemplify resin-integrated positioning through preform manufacturing footprints that compress supply chains for high-volume bottlers. Among domestic specialists, Sumilon Eco PET SARL occupies a position aligned with recycled-content capabilities that serve European export requirements. These named entities represent archetype anchors rather than exhaustive market coverage, with additional competition from regional specialists and unbranded converters serving price-sensitive traditional trade segments.
| Leading Market Players |
|---|
| Alpla Group |
| Plastipak Holdings Inc. |
| Grief Inc. |
| Pet Preforms Morocco |
| Bericap Holding GmbH |
| Sumilon Eco PET SARL |
| Blowtec Morocco |
| Intel Plast |
| Mikafric |
| Others |
Pricing and Supply Chain Analysis
Multilayer coextrusion technician scarcity in Casablanca-Settat widens labor-cost spreads between barrier-certified converters and commodity blow-molders. This skill differential props premium pricing for oxygen-scavenging bottle structures while compressing margins in standard PET formats.
Pricing Analysis
Volume leadership sits with commodity-grade polyethylene terephthalate bottles where per-unit transactional pricing faces compression from resin cost pass-through volatility. Price differentiation hinges on barrier-performance certification tier and volume scale commitments from multinational bottlers. Cost compression in standard formats is intensifying because virgin PET resin tracks crude oil benchmarks. Dairy processors in Casablanca-Settat exhibit highest price sensitivity, while pharmaceutical distributors under the country's national pharmaceutical regulator protocols accept sterilization-grade polypropylene premiums.
Supply Chain Analysis
Regional distribution centers near Mohammedia and Tanger Med anchor hub-and-spoke patterns that feed conversion clusters across Casablanca-Settat. Raw material flows draw from Saudi Arabia, Spain, and Turkey for virgin resin, while barrier additives and coextrusion equipment feed from Germany and Italy. Single-source vulnerability concentrates in European oxygen-scavenging masterbatch supply, exposing Moroccan processors to euro-denominated procurement risk. Distribution runs through port-proximate warehouses with just-in-time delivery to beverage bottlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier-coating equipment capacity scarcity props pricing for extended-shelf-life dairy formats. This bottleneck limits supply response to ultra-high-temperature milk conversion demand.
For Market Incumbents: Deepen backward integration into preform manufacturing to defend margin against resin-integrated multinational entrants. Capture tie-layer optimization expertise through partnerships with Italian equipment vendors before technician shortages worsen. Lock in multiyear barrier-additive supply contracts to hedge euro exposure. For New Entrants and Emerging Players: Recycled-content decontamination systems offer a technology-first wedge into European export certification requirements. Target modified-atmosphere tray production for fresh produce exporters in Fès-Meknès where coastal incumbent presence remains thin. Lead with chain-of-custody documentation capabilities as the go-to-market anchor. For Investors and Strategic Acquirers: The window for entry favors cleanroom blow-molding specialists with pharmaceutical regulator certification already in place. Long-term viability centers on converters bridging food-contact rPET capabilities with EU Packaging and Packaging Waste Regulation alignment. Watch draft extended producer responsibility decree implementation as the inflection signal for recycling infrastructure investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coating Technology Licensing | Enables mono-material PET structures that displace multilayer carton formats in dairy applications. |
| rPET Decontamination Capacity Buildout | Aligns with EU Packaging and Packaging Waste Regulation requirements for European export compliance. |
| Cleanroom Blow-Molding Certification | Unlocks sterilization-grade polypropylene margins under the country's national pharmaceutical regulator protocols. |
| Backward Integration into Preform Manufacturing | Compresses supply chains for Casablanca-Settat beverage clusters while reducing resin logistics exposure. |
| Modified-Atmosphere Tray Production Expansion | Serves European fresh produce export channels migrating from bulk shipment to retail-ready packaging. |
Research Methodology
Multi-period observation of preform localization rates, barrier-technology adoption curves, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with blow-molding plant managers, dairy procurement leads, pharmaceutical packaging engineers, and European equipment vendor technical directors. Secondary validation drew from customs trade data, the country's national standards body protocol documentation, central environmental agency consultation records, and SEC filings of multinational resin suppliers. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates.
Segment-weighting across material grades, forming technologies, and end-use specifications shaped the analytical framework throughout the projection horizon. Modeled dimensions included resin type, barrier-performance tier, regulatory compliance pathway, and regional production cluster. CAGRs derived from fitted growth curves applied to segment-level baseline estimates. Industry-specific inputs encompassed virgin PET resin price trajectories and extended producer responsibility policy implementation probability.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt polymer price spikes or accelerated regulatory decree enactment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Rigid Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
Rigid Sleeve Boxes Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market