
 Mexico Rigid Packaging Market | 2026-2036
Mexico Rigid Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Rigid Packaging Market Foresight
CE marking alignment for export-ready packaging is collapsing the supplier base to firms with dual-certification capability. Amcor plc leverages its integrated film-to-container operations across Mexican manufacturing zones. Altopro SA de CV anchors regional supply through specialized PET bottle production for domestic beverage brands. Berry Global Group Inc. differentiates via multi-layer barrier technologies for pharmaceutical-grade rigid formats.
Mexico rigid packaging encompasses non-flexible containment structures—typically blow-molded HDPE, injection-stretched PET, or drawn aluminum—engineered to 0.5–2.0 mm wall thicknesses and designed for dimensional stability during filling, transport, and shelf display. These structures protect contents from mechanical damage, gas permeation, and UV degradation across ambient and chilled supply chains. Plastic bottles lead volume throughput due to lightweighting economics and resin localization near Veracruz petrochemical complexes. Glass jars sustain premium positioning in tequila and artisanal food segments where barrier inertness commands price premiums. Metal containers occupy industrial chemical and aerosol applications where pressure retention and corrosion resistance remain non-negotiable.
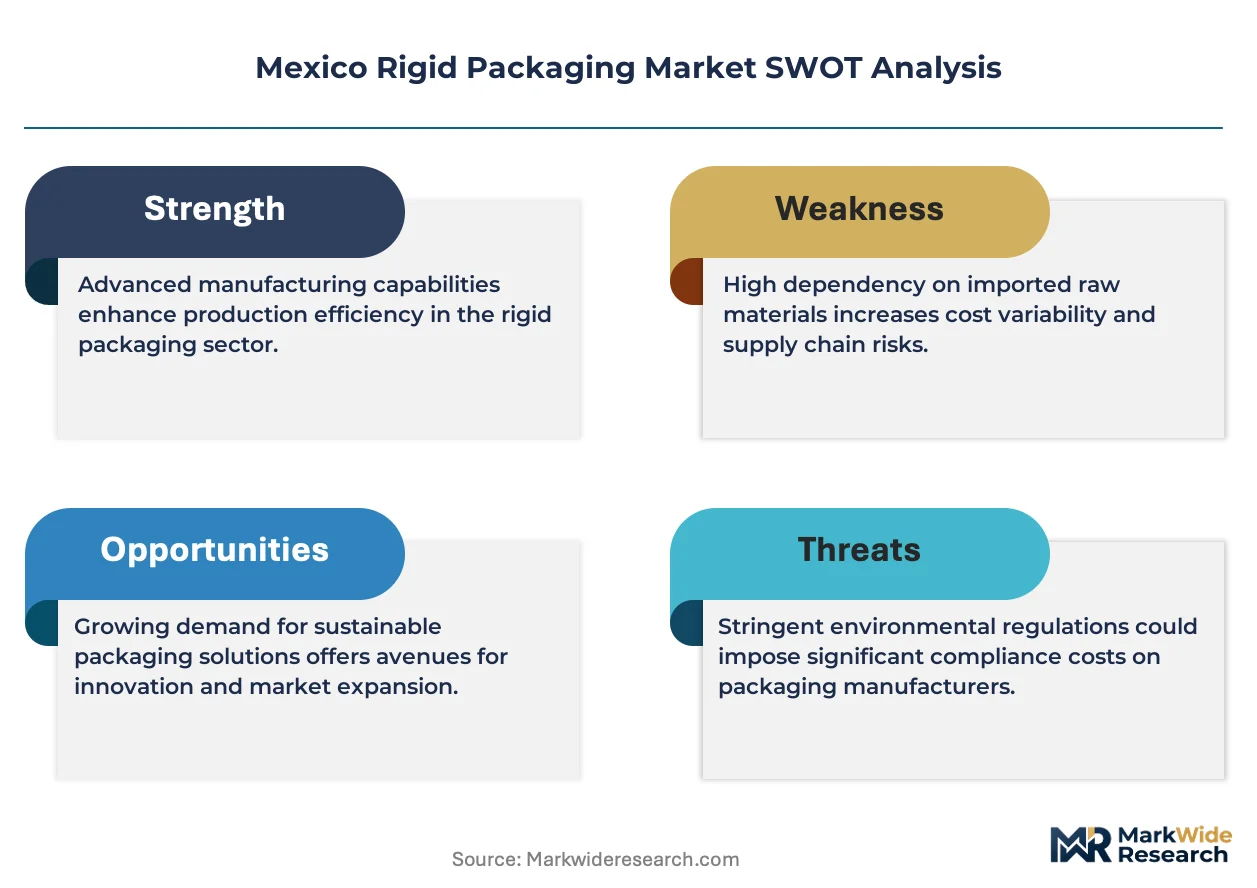
SEMARNAT enforces Extended Producer Responsibility frameworks that mandate post-consumer recycled content thresholds in primary packaging, directly elevating demand for rPET-compatible bottle designs and closed-loop collection infrastructure. NOM-252-SSA1-2011 governs food-contact material migration limits, compelling resin reformulation and additive substitution across the supplier tier. COFEPRIS pharmaceutical packaging regulations require batch-level traceability and child-resistant closure compliance, segmenting qualification costs between approved and non-approved molders. Stakeholders must monitor how state-level waste management concessions reshape collection economics ahead of federal recycled-content mandates tightening.
Market Dynamics
SEMARNAT's Extended Producer Responsibility mandates are forcing resin localization and closed-loop collection infrastructure buildout across Mexican manufacturing corridors, collapsing supplier qualification timelines and elevating capital requirements for molders serving regulated end-uses.
Growth Catalysts
- rPET-compatible bottle designs:Post-consumer recycled content thresholds under SEMARNAT frameworks are pulling demand for mechanically recycled feedstocks into primary packaging specifications, favoring suppliers with captive flake washing and solid-state polymerization capabilities.
- Bajío industrial corridor concentration:Querétaro-Aguascalientes-Guanajuato automotive and electronics clusters are generating parallel demand for rigid industrial containers, creating shared logistics economies for HDPE drum and pail producers.
- NOM-252-SSA1-2011 migration compliance:Food-contact material reformulation requirements are segmenting the supplier base between qualified resin compounders and commodity distributors, tightening procurement relationships with certified molders.
Market Restraints
- Veracruz petrochemical complex concentration:Virgin resin supply hinges on Pemex derivative output and imported feedstock through Gulf Coast ports, exposing converters to freight volatility and foreign exchange compression on resin landed costs.
- Aluminum drawn-wall technical limitation:Sub-0.3mm gauge reduction for aerosol cans hits metallurgical constraints on alloy temper control, capping lightweighting potential against polymer alternatives in personal care applications.
- COFEPRIS pharmaceutical batch-traceability friction:Serialization and child-resistant closure mandates extend mold qualification cycles, freezing smaller molders out of high-margin pharma-grade formats.
Strategic Opportunities
- Yucatán Peninsula underpenetration:Merida-Progreso logistics corridors lack dedicated rigid packaging conversion capacity, creating first-mover positioning for PET preform and bottle producers serving southeastern beverage distribution.
- Dual-certification CE marking tailwind:Export-ready packaging specifications for European-bound agro-industrial goods are collapsing supplier pools to firms with parallel NOM and CE compliance, rewarding upfront certification investment.
- Barrier technology convergence:Multi-layer co-injection of EVOH and tie-layer adhesives into PET structures is enabling hot-fill and retort applications previously reserved for glass and metal, opening CPG shelf-stable segments.
Industry Challenges
- Tooling engineer skill scarcity:Complex multi-cavity hot-runner mold maintenance and process optimization expertise concentrates with aging technician cohorts in Toluca and Monterrey industrial zones, constraining expansion timelines for new entrants.
- Legacy ERP integration friction:Batch-level traceability requirements for COFEPRIS compliance force retrofit of MES and serialization software onto decades-old injection molding lines, elevating downtime risk during qualification.
- Recycled-content verification capex intensity:Near-infrared sorting and blockchain-backed chain-of-custody systems required for SEMARNAT audit trails demand seven-figure capital deployment before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Rigid Packaging Market |
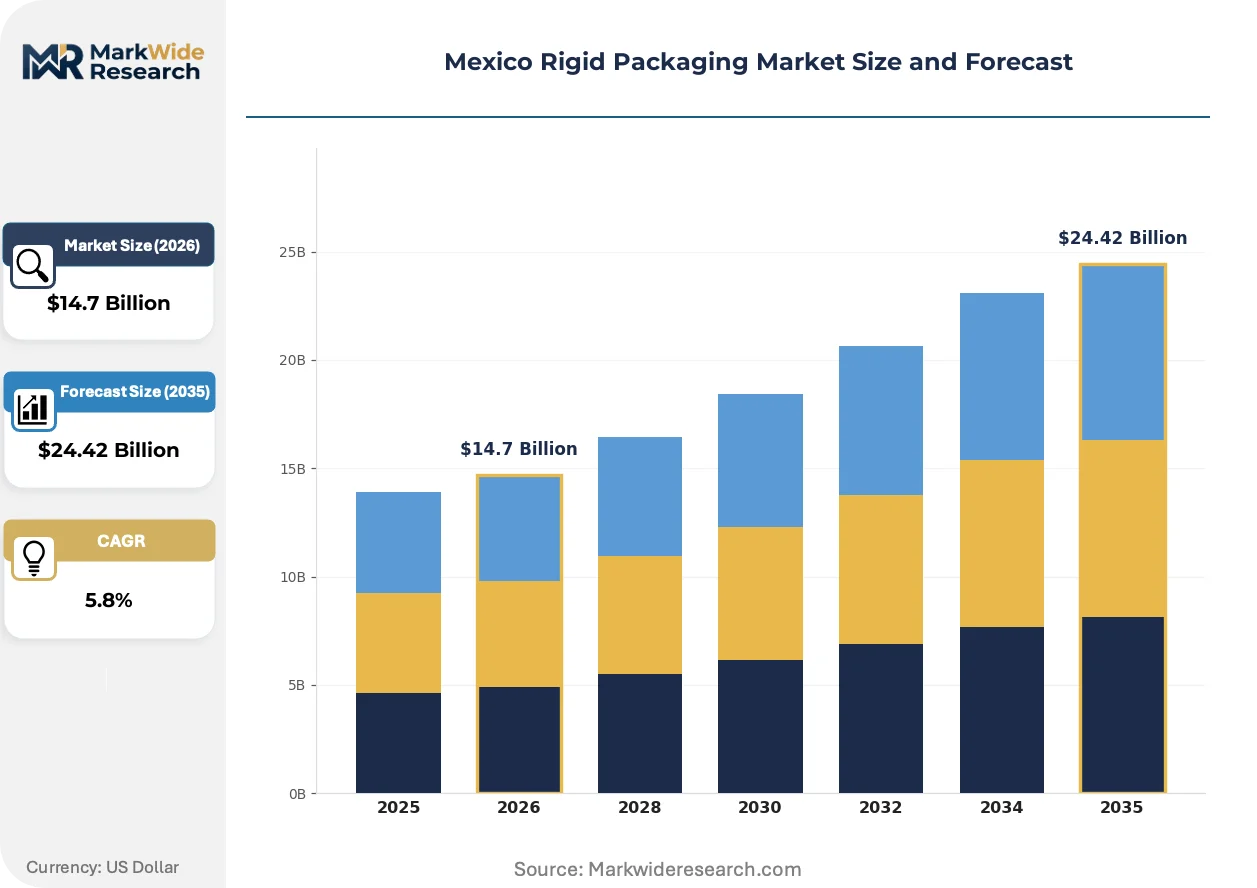
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Metal, Paperboard End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Product Type: Bottles, Jars, Boxes, Containers Design Type: Straight Wall, Cylindrical, Rectangular, Custom Shapes |
| Companies Covered | Amcor plc, Altopro SA de CV, Coexpan S.A., Berry Global Group Inc., AptarGroup Inc., Smurfit Kappa, Vitro S.A.B. de CV, Ball Corporation, Mondi plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Rigid Packaging Market Shifts & Advancements
Material science advances and regulatory stringency are compressing format substitution cycles, with lightweighting economics and circularity mandates converging to redefine competitive qualification thresholds across Mexican conversion capacity.
Mono-material PET bottle designs with integrated barrier coatings are supplanting multi-layer constructions in oxygen-sensitive beverage applications. Grupo Modelo and Coca-Cola FEMSA procurement teams have accelerated qualification timelines for plasma-enhanced chemical vapor deposition treatments, collapsing the cost gap against glass for premium beer and juice segments while preserving bottle-to-bottle recycling streams.
SEMARNAT's 2024 recycled-content mandates are forcing resin procurement restructuring across the supplier tier. Compounders must now document post-consumer flake provenance through certified collection cooperatives, segmenting molders between integrated recyclers and virgin-dependent converters. Food-contact rPET approvals under NOM-252-SSA1-2011 are compressing fastest in Guadalajara metropolitan bottling corridors.
Direct-to-retailer procurement consolidation is displacing traditional distributor networks for standardized HDPE pails and drums. Cemex and Bimbo procurement teams now contract molders on multi-year volume agreements with indexed resin pass-throughs, compressing margin capture for intermediaries while rewarding scale-backed logistics integration in Querétaro and Toluca manufacturing zones.
Mexico Rigid Packaging Market Segmentation
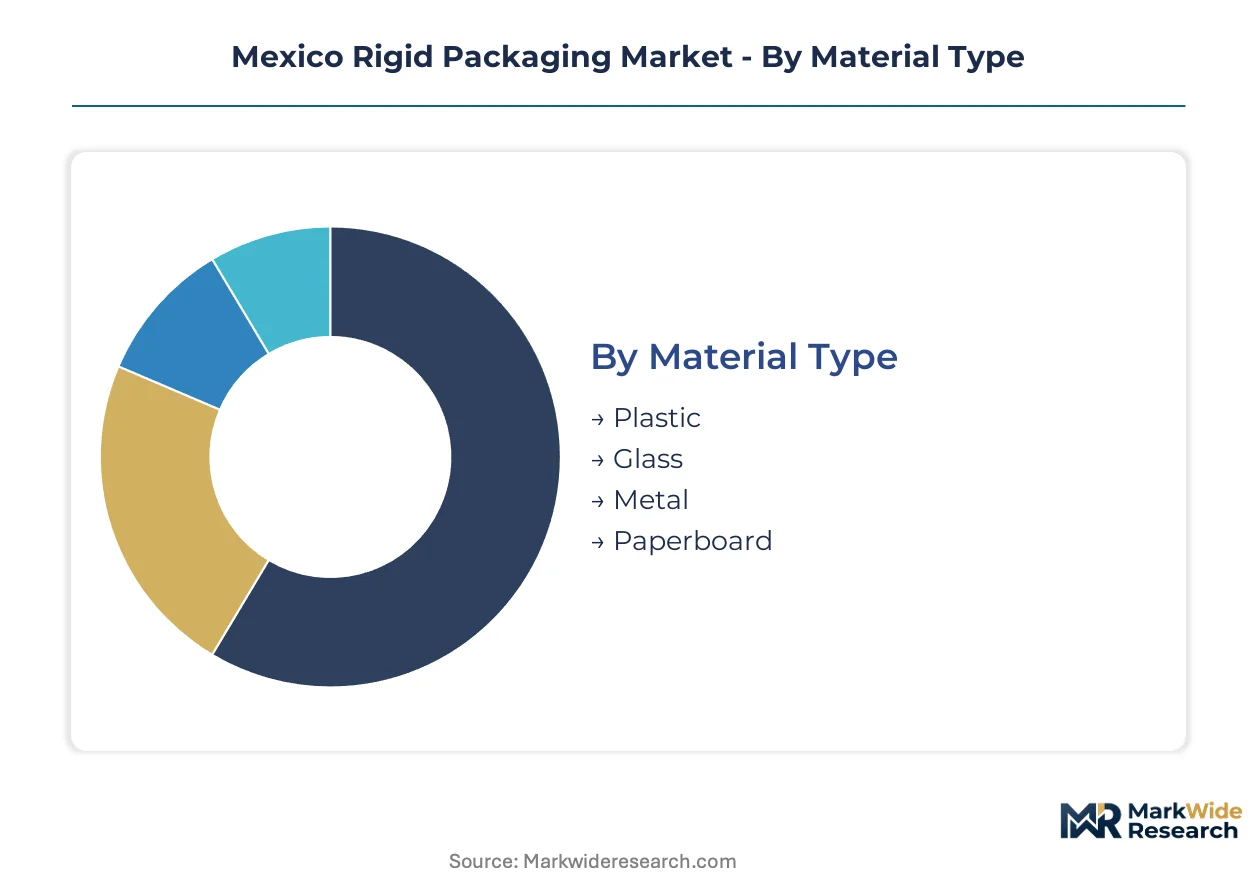
Material specifications and regulatory compliance requirements segment the Mexican rigid packaging supplier base into distinct qualification tiers. Each segmentation dimension carries specific NOM certification obligations that reshape procurement relationships and mold qualification timelines across the Bajío and Toluca manufacturing corridors.
Material Type:
SEMARNAT's recycled-content mandates and NOM-252-SSA1-2011 food-contact compliance create divergent material qualification pathways for molders serving regulated end-uses.
- Plastic:HDPE and PET dominate volume throughput, with rPET-compatible designs commanding premium positioning under Extended Producer Responsibility frameworks. Demand concentrates in Querétaro beverage bottling corridors where Grupo Modelo and Coca-Cola FEMSA procurement teams enforce post-consumer recycled content thresholds.
- Glass:Soda-lime and borosilicate compositions sustain premium tequila and artisanal food positioning where barrier inertness justifies weight penalties. Jalisco highland distillers anchor demand through heritage-format specifications that resist polymer substitution despite lightweighting economics.
- Metal:Drawn aluminum and tinplate occupy aerosol and industrial chemical applications where pressure retention remains non-negotiable.
- Paperboard:Rigid carton formats serve secondary packaging and display-ready applications with lower barrier requirements.
Established volume favors Plastic; emerging adoption favors Glass.
End Use Industry:
Customer procurement consolidation and batch-traceability mandates segment molders between commodity distributors and certified direct suppliers.
- Food & Beverage:Shelf-stable and chilled supply chain requirements drive specification complexity, with hot-fill and retort applications demanding multi-layer barrier engineering. Bimbo and Cemex procurement teams now contract on multi-year volume agreements with indexed resin pass-throughs, compressing intermediary margins.
- Pharmaceuticals:COFEPRIS serialization and child-resistant closure compliance extend mold qualification cycles, freezing smaller molders out of high-margin formats. Guadalajara metropolitan bottling corridors show fastest rPET food-contact approval compression under NOM-252-SSA1-2011.
- Personal Care:Aerosol and pump-dispense formats favor aluminum drawn-wall constructions hitting metallurgical gauge constraints.
- Electronics:ESD-safe and moisture-barrier specifications serve Querétaro-Aguascalientes automotive and electronics cluster demand.
Procurement consolidation accelerates fastest in Food & Beverage; qualification barriers rise steepest in Pharmaceuticals.
Product Type:
Logistics integration economies and filling line compatibility requirements shape format selection across Mexican manufacturing zones.
- Bottles:Blow-molded HDPE and injection-stretched PET structures engineered to 0.5–2.0 mm wall thicknesses protect contents from mechanical damage and gas permeation. Veracruz petrochemical complex proximity enables resin localization for lightweighting economics.
- Jars:Wide-mouth glass and PET formats preserve premium positioning in tequila, honey, and artisanal condiment segments.
- Boxes:Rigid paperboard and corrugated formats serve secondary containment and retail display functions.
- Containers:HDPE drums and pails generate shared logistics economies with Bajío industrial corridor automotive and electronics demand.
Throughput concentration sits with Bottles; margin expansion favors Jars.
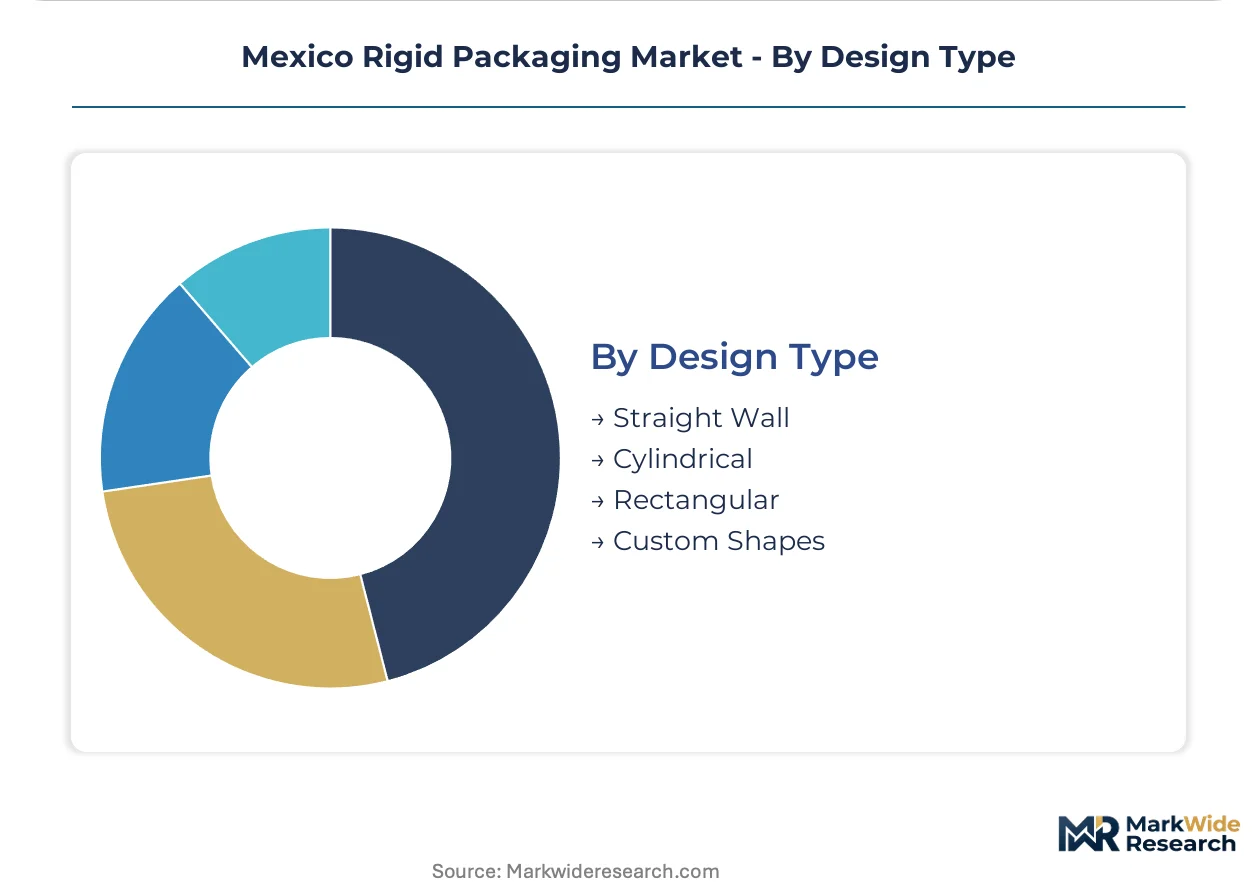
Design Type:
Tooling complexity and shelf-space optimization requirements differentiate mold investment recovery timelines across format geometries.
- Straight Wall:Simplified mold cavity engineering reduces tooling lead times for standardized HDPE pail and drum production serving Cemex industrial chemical distribution.
- Cylindrical:Rotational symmetry optimizes blow-molding cycle times and label adhesion for beverage applications across Toluca and Monterrey conversion zones.
- Rectangular:Cube efficiency maximizes pallet utilization and retail shelf density for food and personal care distribution.
- Custom Shapes:Proprietary geometries command brand differentiation premiums in premium spirits and gift-format positioning.
Standardized tooling favors Cylindrical; brand differentiation investment flows toward Custom Shapes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEMARNAT's Extended Producer Responsibility frameworks and recycled-content mandates are redistributing conversion capacity across Mexican manufacturing corridors. State-level waste management concessions and federal compliance deadlines are accelerating infrastructure buildout in historically underpenetrated zones.
Bajío Region
Querétaro-Aguascalientes-Guanajuato automotive and electronics clusters generate parallel demand for rigid industrial containers. SEMARNAT enforcement timelines compress supplier qualification windows. Shared logistics economies emerge for HDPE drum and pail producers serving Cemex and Bimbo procurement teams.
Central Mexico
Mexico City Metro and Toluca industrial zones concentrate tooling engineer expertise for complex multi-cavity hot-runner mold maintenance. NOM-252-SSA1-2011 food-contact compliance segments the supplier base between qualified resin compounders and commodity distributors. Aging technician cohorts constrain expansion timelines for new entrants.
Jalisco
Guadalajara metropolitan bottling corridors show fastest rPET food-contact approval compression under SEMARNAT mandates. Highland tequila distillers anchor glass jar demand through heritage-format specifications. COFEPRIS pharmaceutical serialization requirements extend mold qualification cycles for child-resistant closure compliance.
Nuevo León
Monterrey conversion zones sustain blow-molding cycle optimization for cylindrical beverage formats. Veracruz petrochemical complex proximity enables resin localization for lightweighting economics. Direct-to-retailer procurement consolidation displaces traditional distributor networks for standardized HDPE containers.
Yucatán Peninsula
Mérida-Progreso logistics corridors lack dedicated rigid packaging conversion capacity for southeastern beverage distribution. First-mover positioning opens for PET preform and bottle producers. Federal recycled-content mandates tightening ahead of state-level collection infrastructure maturity create timing arbitrage.
Mexico Rigid Packaging Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with dual NOM-CE compliance capability collapsing supplier pools for export-ready formats. The market structures around three archetypes: integrated multinationals with captive flake washing, regional compounders with localized resin procurement, and specialized molders with pharma-grade qualification. M&A activity concentrates on rPET-compatible asset acquisition, while capacity expansion targets Bajío corridor logistics integration.
Within the integrated multinational tier, Amcor plc and Berry Global Group Inc. exemplify scale-backed certification breadth, while Altopro SA de CV occupies a position as a private specialist anchoring regional PET bottle supply for domestic beverage brands. These three represent divergent competitive positions: the first two sit within archetypes defined by cross-border compliance infrastructure and multi-layer barrier technology portfolios, while the third exemplifies geographic focus on procurement relationships with Grupo Modelo and Coca-Cola FEMSA sourcing teams.
| Leading Market Players |
|---|
| Amcor plc |
| Altopro SA de CV |
| Coexpan S.A. |
| Berry Global Group Inc. |
| AptarGroup Inc. |
| Smurfit Kappa |
| Vitro S.A.B. de CV |
| Ball Corporation |
| Mondi plc |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day resin inventory cycles at Veracruz petrochemical complexes concentrate pricing power with integrated compounders serving SEMARNAT-mandated rPET specifications, while smaller molders absorb foreign exchange volatility on imported feedstock landed costs.
Pricing Analysis
Certification level under NOM-252-SSA1-2011 and CE marking creates the primary spread between qualified resin compounders and commodity distributors. Three-tier pricing structure across pharma-grade, food-contact, and industrial tiers segments the supplier base, with COFEPRIS serialization compliance commanding premium positioning. Cost compression in standard HDPE pail and drum formats is intensifying because direct-to-retailer procurement consolidation eliminates intermediary margin capture. Small-to-mid molders serving unregulated industrial applications exhibit highest price sensitivity, while pharma-qualified converters with child-resistant closure capabilities maintain pricing resilience.
Supply Chain Analysis
Forty-five-day blow-molding tool lead times from Toluca and Monterrey engineering clusters anchor supply chain responsiveness for complex multi-cavity hot-runner molds. Virgin resin supply draws from Veracruz petrochemical complexes and Gulf Coast import corridors, with rPET flake sourcing concentrating in Guadalajara metropolitan collection zones. Single-source vulnerability persists for specialized EVOH barrier resins and tie-layer adhesives. Distribution runs through direct-to-retailer volume agreements with Cemex and Bimbo procurement teams, displacing traditional distributor networks for standardized formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop collection infrastructure and blockchain-backed chain-of-custody verification represent service-attach layers expanding faster than virgin resin conversion capacity, creating recurring revenue streams independent of molding throughput cycles.
For Market Incumbents: Secure captive flake washing and solid-state polymerization capabilities ahead of SEMARNAT recycled-content threshold tightening, while consolidating tooling engineer expertise in Toluca and Monterrey zones against aging technician cohort attrition. Defensive positioning requires backward integration into post-consumer collection cooperatives to guarantee feedstock provenance for NOM-252-SSA1-2011 compliance. For New Entrants and Emerging Players: Aftermarket mold maintenance and process optimization services for legacy injection lines present a service-layer gap where incumbents under-serve COFEPRIS compliance retrofit demand. Yucatán Peninsula beverage distribution corridors offer the most penetrable geography for PET preform capacity, with first-mover positioning enabled by Mérida-Progreso logistics buildout. Target procurement relationships with southeastern regional bottlers bypassing established Bajío supplier networks. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because SEMARNAT mandates structurally elevate capital requirements for audit-trail compliance, collapsing the supplier base to integrated recyclers. Acquisition targets cluster around rPET-compatible molders with Guadalajara corridor positioning and existing food-contact approvals. Monitor state-level waste management concession awards as the inflection signal for collection infrastructure economics.| Strategic Initiative | Industry Significance |
|---|---|
| rPET-Compatible Capacity Expansion | Captures SEMARNAT recycled-content mandate pull-through in Querétaro beverage bottling corridors. |
| Backward Integration into Collection Infrastructure | Secures post-consumer flake provenance for NOM-252-SSA1-2011 food-contact compliance verification. |
| Dual-Certification CE Marking Investment | Collapses supplier pools for European-bound agro-industrial export packaging procurement. |
| Tooling Engineer Capability Consolidation | Addresses scarcity of hot-runner mold maintenance expertise in Toluca and Monterrey zones. |
| Blockchain Chain-of-Custody Deployment | Enables SEMARNAT audit-trail compliance for seven-figure capital deployment before revenue recognition. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, SEC filings from listed packaging multinationals, and SEMARNAT regulatory disclosures, with inputs gathered from resin procurement managers at beverage bottlers, tooling engineers in Toluca industrial zones, and COFEPRIS compliance officers. Bottom-up volume modeling triangulates against top-down macroeconomic indicators across the Mexican manufacturing corridor.
Segmentation dimensions modeled include material type, end-use industry, product format, and design geometry across the projection horizon. CAGRs derive from trend extrapolation of resin localization patterns, recycled-content mandate phase-ins, and procurement consolidation trajectories. Industry-specific inputs incorporate rPET food-contact approval timelines under NOM-252-SSA1-2011 and hot-fill barrier technology adoption curves.
Underlying assumptions cover SEMARNAT enforcement consistency, Pemex derivative output stability, and foreign exchange band containment, with deviation risk concentrated in state-level waste management concession delays and aluminum alloy temper control limitations. Revision becomes warranted when federal recycled-content mandate timelines accelerate beyond current infrastructure buildout capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Rigid Industrial Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Nigeria Rigid Plastic Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market