
 Bulk Liquid Transport Packaging Market | 2026-2036
Bulk Liquid Transport Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Liquid Transport Packaging Market Outlook
Buyer concentration among multinational chemical and food producers is consolidating procurement volumes toward fewer, larger packaging contracts. Greif Inc. leverages its integrated steel drum and IBC manufacturing network to serve these consolidated accounts with consistent supply assurance. Mauser Packaging Solutions anchors its position through closed-loop reconditioning services that reduce per-trip packaging costs for high-volume shippers. Schoeller Allibert competes in the plastic intermediate bulk container segment with foldable designs that cut return freight expenses.
Bulk liquid transport packaging encompasses reusable and single-use containers engineered to move non-hazardous and hazardous liquids in volumes typically ranging from 220 to 3,000 liters, with flexitanks fitting inside standard twenty-foot containers holding up to 24,000 liters. These systems employ multi-layer polyethylene films, galvanized steel cages, or blow-molded high-density polyethylene to prevent contamination, spillage, and degradation during multimodal transit. Flexitanks and IBC tanks capture expanding share in food-grade and chemical applications where single-use hygiene and collapsible return logistics offset higher unit costs. Metal drums retain dominance in hazardous chemical segments where UN certification and impact resistance command premium positioning and sustained replacement cycles.
The EPA regulates hazardous material container integrity under 49 CFR standards, while the EU F-Gas Regulation and REACH framework constrain fluorinated barrier films and chemical contact materials used in composite IBC construction. FDA food contact substance notifications govern polyethylene and epoxy-phenolic linings in tanks carrying edible oils, juices, and pharmaceutical intermediates. Stakeholders must track evolving extended producer responsibility schemes and chemical compatibility testing protocols as sustainability mandates and product safety requirements tighten in parallel across North American and European jurisdictions.
Market Dynamics
Consolidation among multinational chemical and food producers is concentrating procurement volumes toward fewer packaging contracts, forcing suppliers to demonstrate integrated manufacturing networks and closed-loop service capabilities to retain strategic accounts.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening recyclability mandates for plastic IBCs are accelerating demand for reconditioning services and circular material flows across German chemical corridors.
- Wine exporters:Flexitank adoption for bulk liquid shipments is expanding as food-grade hygiene requirements and collapsible return logistics offset higher unit costs in transoceanic routes.
- REACH framework constraints:Chemical compatibility testing protocols for barrier films are pushing shippers toward certified composite IBC constructions with documented substance safety profiles.
Market Restraints
- Galvanized steel cage supply:Input cost volatility for metal drum components constrains margin flexibility, particularly for UN-certified hazardous chemical containers requiring impact-resistant specifications.
- Fluorinated barrier film availability:The EU F-Gas Regulation limits production capacity for high-performance composite IBC liners, creating supply bottlenecks for chemical contact applications.
- Multi-layer polyethylene resin concentration:Feedstock supply for flexitank films clusters among petrochemical producers in the US Gulf Coast and Middle Eastern hubs, exposing converters to geographic concentration risk.
Strategic Opportunities
- India's chemical manufacturing expansion:Underpenetrated demand for intermediate bulk containers in specialty chemical production zones around Gujarat and Maharashtra offers first-mover positioning for compliant suppliers.
- Extended producer responsibility schemes:Mandatory take-back programs in EU member states are creating service revenue streams through integrated collection, reconditioning, and redeployment networks.
- Smart tracking convergence:Integration of RFID sensors with IBC fleets is enabling real-time location and condition monitoring for high-value pharmaceutical and food-grade liquid shipments.
Industry Challenges
- UN certification timelines:Hazardous material container testing protocols under 49 CFR standards extend product development cycles, compressing competitive response windows for new drum and tank designs.
- Reconditioning facility capex:Automated cleaning and inspection lines for closed-loop IBC services require substantial capital deployment, favoring scaled operators over regional service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Liquid Transport Packaging Market |
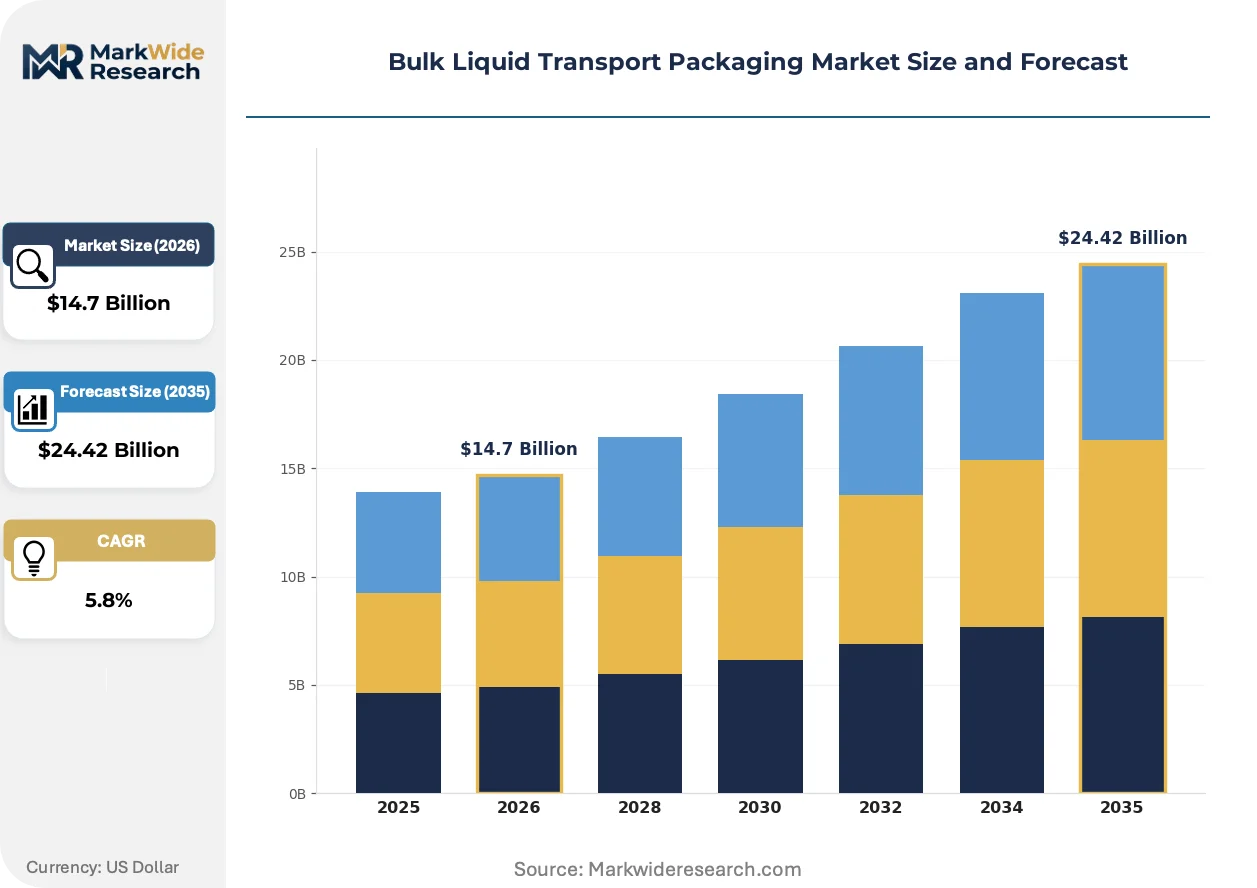
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IBC Tanks, Drums, Flexitanks, Tote Tanks Material: Plastic, Metal, Composite, Glass End User: Chemical, Food & Beverage, Pharmaceutical, Oil & Gas Distribution Channel: Online, Retail, Distributors, Direct Sales |
| Companies Covered | Greif Inc., Scholle IPN, Mauser Packaging Solutions, Berry Global, DS Smith Plc, Schoeller Allibert, TPS Rental Systems Ltd., Hoover Ferguson Group, BLT Flexitank Industrial Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Liquid Transport Packaging Market Strategic Shifts
Active transformation in bulk liquid packaging centers on material science advances, regulatory compliance automation, and procurement model restructuring that rewards integrated service providers over transactional suppliers.
Barrier-coated polyethylene films with oxygen scavenging layers are electrifying wine and edible oil transport by eliminating flavor degradation during extended ocean voyages. European exporters are converting flexitank volumes at accelerated rates as quality-sensitive buyers reject traditional drum alternatives. The technology is compressing replacement cycles for conventional single-use containers while enabling premium product positioning in destination markets.
REACH chemical safety dossier requirements are forcing composite IBC manufacturers to document every substance in multi-layer constructions down to 0.1 percent concentration. German chemical producers around Ludwigshafen now mandate supplier certification through ECHA-registered testing protocols before contract award. The regulatory burden is favoring established producers with dedicated compliance teams over smaller converters lacking toxicological assessment capabilities.
Buyer concentration among multinational food and chemical producers is compressing vendor lists and extending contract durations in exchange for volume guarantees and dedicated inventory positions. Procurement teams are unbundling packaging supply from logistics services, then rebundling them through single-source agreements with integrated manufacturers. This pattern is most visible in German industrial chemical clusters and US specialty chemical production regions where procurement rationalization programs have eliminated secondary suppliers.
Bulk Liquid Transport Packaging Market Segmentation
Packaging procurement decisions in bulk liquid transport hinge on liquid hazard classification, multimodal routing requirements, and total cost per trip including return logistics. Segmentation reveals where material science investments concentrate and which customer verticals sustain premium pricing for certified constructions.
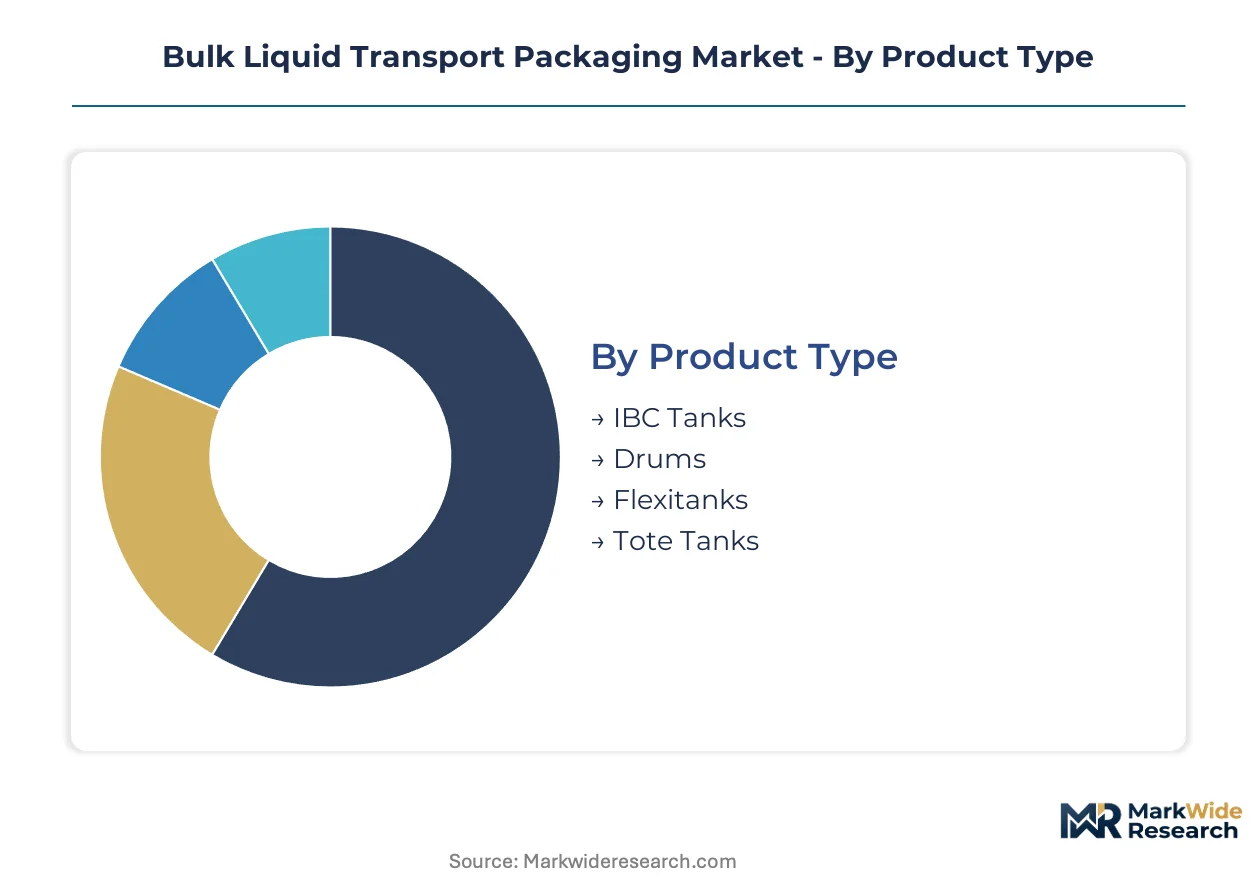
Product Type:
Buyers select container formats based on liquid volume, reusability requirements, and the trade-off between single-use hygiene assurance and return freight economics.
- IBC Tanks:Blow-molded HDPE or composite constructions with galvanized steel cages handle 1,000-liter volumes for chemical and food-grade applications. German chemical producers around Ludwigshafen mandate IBC fleets with RFID tracking for high-value pharmaceutical intermediates where contamination traceability is non-negotiable.
- Flexitanks:Multi-layer polyethylene film systems fit standard twenty-foot containers holding up to 24,000 liters for single-use wine and edible oil shipments. Wine exporters from France and Spain are converting volumes at accelerated rates as quality-sensitive buyers reject traditional drum alternatives for transoceanic routes.
- Drums:Cylindrical steel or plastic containers remain dominant for hazardous chemicals requiring UN certification and impact resistance.
- Tote Tanks:Rigid rectangular containers serve niche applications in specialty chemical distribution with dedicated filling infrastructure.
Volume sits with drums; growth tilts toward flexitanks.
Material:
Material selection follows regulatory pressure on recyclability, chemical compatibility mandates, and the cost structure of reconditioning versus replacement.
- Plastic:HDPE and polyethylene formulations dominate food-grade and non-hazardous chemical applications with blow-molding cost advantages. The EU Packaging and Packaging Waste Regulation is tightening recyclability mandates for plastic IBCs, accelerating demand for reconditioning services and circular material flows.
- Metal:Cold-rolled steel and stainless steel constructions retain dominance in hazardous chemical segments where UN certification and impact resistance command premium positioning.
- Composite:Multi-layer constructions with barrier films serve aggressive chemical applications requiring documented substance safety profiles under REACH protocols.
- Glass:Borosilicate and soda-lime containers capture limited pharmaceutical and high-purity chemical niches where inertness outweighs fragility costs.
Plastic captures the largest installed base; composite materials are climbing the fastest as REACH chemical safety dossier requirements intensify.
End User:
End-use verticals impose divergent certification requirements, from FDA food contact notifications to EPA hazardous material handling protocols.
- Chemical:Specialty and industrial chemical producers drive demand for UN-certified containers with documented compatibility testing. Procurement concentration among multinational producers is compressing vendor lists and extending contract durations in exchange for volume guarantees.
- Food & Beverage:Edible oil and juice processors require FDA-compliant polyethylene linings and oxygen-scavenging barrier films to prevent flavor degradation.
- Pharmaceutical:Drug manufacturers mandate container integrity documentation and real-time condition monitoring for high-value liquid intermediates.
- Oil & Gas:Lubricant and drilling fluid distributors prioritize cost-efficient bulk handling with less stringent hygiene protocols than food or pharmaceutical applications.
Chemical sector procurement dominates contract value; food and beverage applications are gaining share fastest as flexitank technology matures.
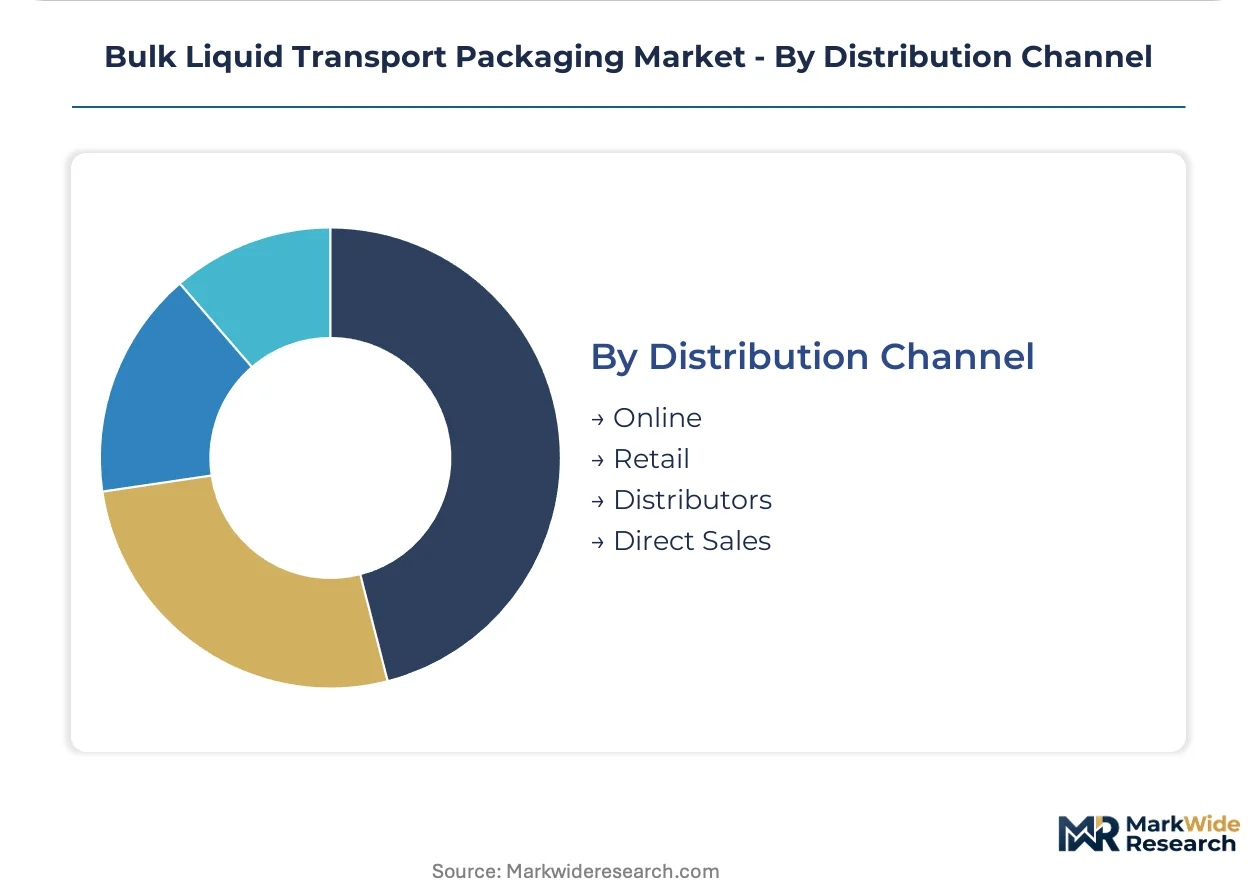
Distribution Channel:
Channel structure reflects customer scale, technical support requirements, and the economics of inventory positioning near chemical production clusters.
- Distributors:Regional packaging specialists maintain local inventory positions and provide technical consultation on chemical compatibility and regulatory compliance.
- Direct Sales:Integrated manufacturers serve multinational accounts with dedicated supply agreements and closed-loop reconditioning networks.
- Online:Digital procurement platforms capture standardized drum and small-volume IBC transactions where specification complexity is low.
- Retail:Limited presence in consumer-facing lubricant and agricultural chemical segments with walk-up purchase patterns.
Direct sales anchor strategic accounts; distributor relationships sustain mid-market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration among multinational chemical and food producers is pulling demand toward specific industrial corridors where production scale meets regulatory stringency. Container selection varies sharply by regional compliance frameworks and logistics infrastructure maturity.
Germany
Chemical producers in the Ludwigshafen-Leverkusen corridor drive premium IBC demand for pharmaceutical intermediates and specialty chemicals. ECHA-registered REACH compliance testing now precedes contract awards, favoring suppliers with dedicated toxicological assessment capabilities. The country's Packaging and Packaging Waste Regulation implementation is accelerating closed-loop reconditioning network investments.
United States
Specialty chemical manufacturers along the Gulf Coast and food-grade processors in California's Central Valley sustain drum and flexitank procurement volumes. EPA 49 CFR hazardous material container standards govern UN certification requirements, extending product development timelines for new constructions. Houston-area petrochemical feedstock concentration exposes converters to resin supply volatility.
China
Expanding chemical production in Jiangsu and Zhejiang provinces is generating container demand for both domestic distribution and export shipment. NMPA and GB standards govern pharmaceutical and food-contact packaging specifications, with dual carbon goals pressuring HDPE recycling rates. Yangtze River Delta manufacturers are consolidating procurement toward fewer packaging suppliers with integrated service networks.
India
Specialty chemical zones in Gujarat and Maharashtra present underpenetrated IBC demand as domestic production scales for export markets. BIS certification requirements and FSSAI food-contact notifications govern polyethylene and epoxy-phenolic lining specifications. Mumbai-Pune industrial corridor producers are converting from traditional drum shipments to flexitank configurations for edible oil exports.
France
Wine exporters from Bordeaux and Burgundy regions are accelerating flexitank adoption for transoceanic bulk shipments to preserve quality-sensitive product positioning. ANSM pharmaceutical packaging regulations and EU F-Gas constraints on fluorinated barrier films are shaping composite IBC material selection. Lyon-based chemical distributors are mandating RFID-trackable container fleets for high-value liquid intermediates.
Bulk Liquid Transport Packaging Market Competitive Environment
North American producers anchor one tier; European specialists hold differentiated positions through regulatory compliance depth. The market structure splits between integrated manufacturers with captive steel and plastic production and regional service providers focused on reconditioning networks. Three archetypes dominate: vertically integrated drum-IBC combinations, flexitank film converters with barrier technology, and closed-loop logistics operators. Competitive moves center on reconditioning facility expansion and smart tracking integration rather than raw capacity addition.
Among integrated packaging manufacturers, Greif Inc. and Mauser Packaging Solutions exemplify the scale-driven archetype with combined drum and intermediate bulk container production networks. Schoeller Allibert occupies a position within the foldable plastic IBC segment where return freight economics drive procurement decisions. These three companies represent the consolidation pattern where multinational chemical accounts are compressing vendor lists toward suppliers with manufacturing breadth and service integration.
| Leading Market Players |
|---|
| Greif Inc. |
| Scholle IPN |
| Mauser Packaging Solutions |
| Berry Global |
| DS Smith Plc |
| Schoeller Allibert |
| TPS Rental Systems Ltd. |
| Hoover Ferguson Group |
| BLT Flexitank Industrial Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Galvanized steel cage costs cascade from US Gulf Coast and Chinese mill complexes through UN-certified drum pricing tiers, with food-grade flexitank films commanding premium spreads over standard polyethylene formulations due to oxygen-barrier specifications and FDA compliance documentation.
Pricing Analysis
Volume sits with steel drums; margins concentrate in composite IBCs and flexitank barrier films. Price differentiation rests on UN certification tier and REACH dossier completeness, with German chemical buyers paying substantial premiums for ECHA-registered constructions. Cost compression in standard plastic drums is intensifying as HDPE resin supply volatility feeds through converter margins. Small regional reconditioners exhibit highest price sensitivity; multinational chemical producers with closed-loop service contracts show lowest.
Supply Chain Analysis
Multi-layer polyethylene resin supply rests on petrochemical complexes clustered along the US Gulf Coast, Middle Eastern production hubs, and coastal Chinese refineries. HDPE blow-molding feedstock and galvanized steel sheet constitute the critical input dependencies. Single-source vulnerability concentrates in fluorinated barrier film production constrained by EU F-Gas Regulation capacity limits. Distribution runs through integrated manufacturer direct sales for multinational accounts, with regional distributors sustaining mid-market chemical and food processor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
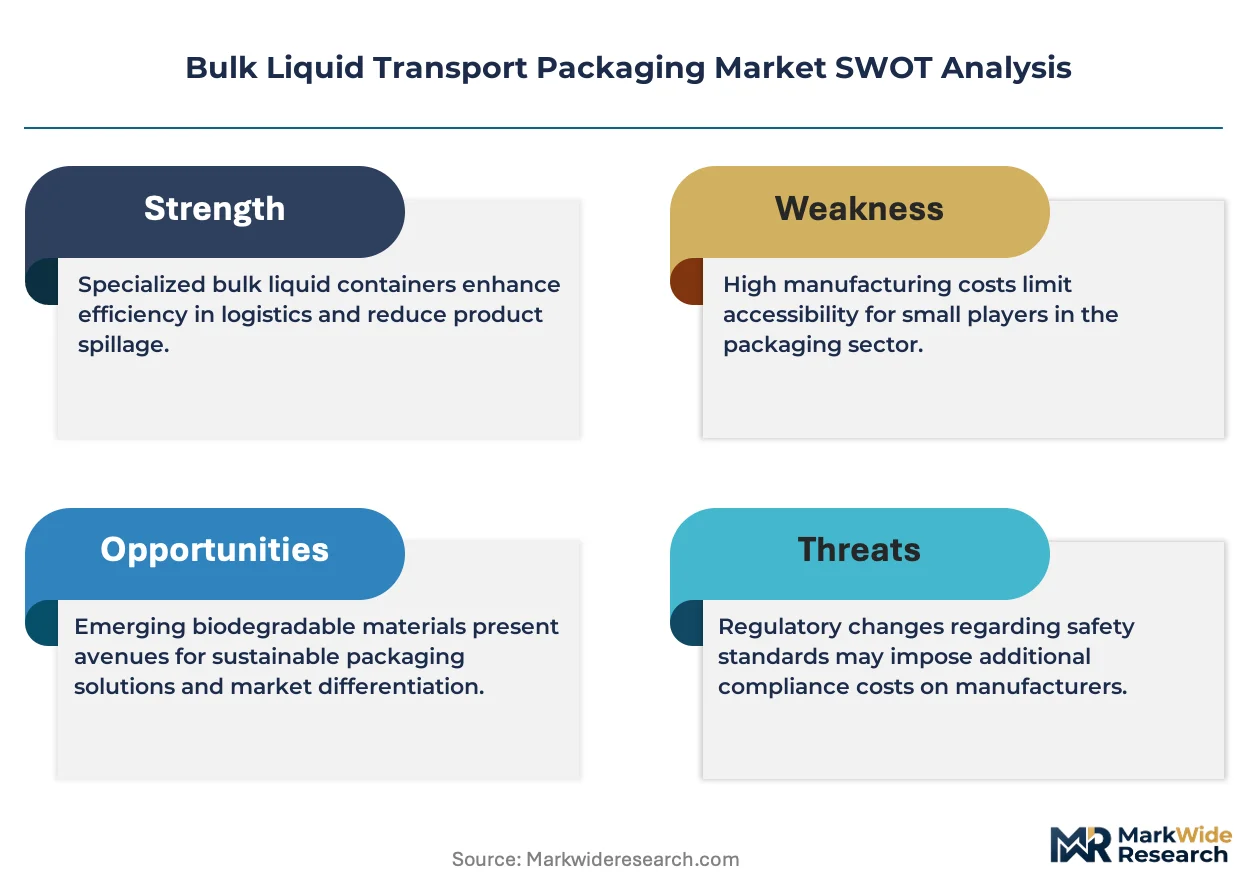
Flexitank film production capacity is the binding constraint propping pricing power for compliant converters, as wine exporter demand outstrips qualified supply from REACH-certified manufacturers.
For Market Incumbents: Deploy closed-loop reconditioning network expansion to capture EU Packaging and Packaging Waste Regulation-mandated take-back revenue streams. Anchor procurement consolidation defense through RFID-trackable IBC fleet integration for pharmaceutical intermediate accounts. Counter flexitank substitution threats by demonstrating steel drum total-cost-per-trip parity on transoceanic routes with return logistics optimization. For New Entrants and Emerging Players: Launch via distributor partnerships targeting India's Gujarat and Maharashtra specialty chemical zones where IBC penetration lags drum-based shipment conventions. Prioritize BIS-certified composite constructions for edible oil exporters converting from traditional packaging. Exploit fluorinated film supply bottlenecks by qualifying alternative barrier technologies under REACH frameworks. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional reconditioning operators with automated cleaning line infrastructure in German chemical corridors. Five-to-ten year viability hinges on extended producer responsibility scheme participation rights and reconditioning facility licensing. Monitor EU F-Gas Regulation enforcement intensity as inflection signal for composite IBC liner supply restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Reconditioning Network Expansion | Captures mandatory take-back revenue under EU Packaging and Packaging Waste Regulation implementation. |
| Barrier Film Technology Licensing | Qualifies alternative oxygen-scavenging constructions as EU F-Gas Regulation constrains fluorinated supply. |
| RFID Fleet Integration | Enables real-time tracking for pharmaceutical intermediate shipments per German chemical producer mandates. |
| Backward Integration into HDPE Resin | Hedges Gulf Coast feedstock volatility exposure for blow-molded IBC cost structures. |
| REACH Dossier Registration Investment | Secures ECHA certification prerequisite for Ludwigshafen-Leverkusen corridor contract eligibility. |
Study Parameters
Trade databases, chemical industry association publications, and regulatory filing repositories formed the secondary backbone for this analysis. Primary fieldwork incorporated structured interviews with packaging procurement leads at multinational chemical producers, plant managers at German industrial chemical clusters, flexitank logistics coordinators at wine export houses, and reconditioning facility operators across EU member states. Bottom-up and top-down triangulation validated volume estimates against customs shipment records and converter capacity disclosures.
Bottom-up modeling anchored projections across the analysis window, with top-down macroeconomic cross-checks. Segmentation dimensions encompassed container format, material construction, end-use vertical, and geographic production cluster. CAGRs derived from historical shipment trajectory analysis and capacity expansion announcements. Forecast inputs incorporated REACH regulatory timeline assumptions and flexitank adoption curve parameters from wine and edible oil trade flow data.
EU F-Gas Regulation enforcement intensity, REACH dossier approval delays, and HDPE resin supply disruptions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory implementation pace and converter capacity expansion schedules. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Global Dunnage Packaging Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Overpack Drum Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
MENA Industrial Packaging Market