
 Colombia Rigid Plastic Packaging Market | 2026-2036
Colombia Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Rigid Plastic Packaging Market Insights
Multi-source procurement among Andean beverage bottlers is shifting toward consolidated supplier partnerships with technical audit requirements. ALPLA Werke Alwin Lehner GmbH & Co KG anchors blow-molding capacity through its regional production network. Berry Global Inc. leverages lightweighting expertise to sustain polymer efficiency programs across dairy and juice accounts. Amcor Group GmbH competes on preform-to-bottle integration, controlling design-to-delivery timelines for carbonated soft drink clients.
Colombia rigid plastic packaging encompasses thermoformed and injection-molded containers fabricated from polyethylene, polypropylene, PVC, and polystyrene resins, engineered to provide dimensional stability, moisture barriers, and stack strength for shelf-stable distribution. Its primary commercial purpose centers on protecting packaged contents through filling, transport, and retail display cycles while minimizing unit weight versus glass or metal alternatives. Bottles lead the packaging type hierarchy, capturing the majority of resin throughput due to beverage sector scale and blow-molding automation maturity. Polypropylene represents the fastest-expanding material category, displacing polystyrene in dairy and prepared food trays as recyclability specifications tighten across buyer specifications.
Colombia's Ministry of Environment and Sustainable Development enforces Law 2232 of 2022 provisions on single-use plastics, compelling converters to certify recycled content thresholds and redesign formats for mechanical recycling compatibility. BIS-equivalent technical standards through ICONTEC govern migration limits and food-contact safety, conditioning import approvals and domestic production qualifications. Stakeholders must monitor regulatory harmonization with Pacific Alliance neighbors, as diverging extended producer responsibility schemes could fragment compliance costs and reshape cross-border supply routing decisions.
Market Dynamics
Colombia's rigid plastic packaging sector operates under the compressive force of Law 2232 of 2022, which mandates recycled content thresholds and mechanical recycling compatibility redesigns. This regulatory pressure is restructuring converter operations, resin sourcing patterns, and end-user procurement specifications across Bogotá's industrial corridor.
Growth Catalysts
- Extended Producer Responsibility Mandates:Colombia's Ministry of Environment advances post-consumer plastic recovery targets, compelling beverage bottlers to expand PET container procurement and fund collection infrastructure.
- Polypropylene Material Transition:Dairy and prepared food processors are accelerating PP tray adoption as recyclability specifications tighten across buyer contracts, displacing polystyrene formats.
- Bogotá Industrial Cluster Concentration:Food processors and personal care formulators cluster near conversion facilities, reducing logistics costs and enabling just-in-time supply relationships.
Market Restraints
- Resin Import Dependency:Domestic converters rely on imported polyethylene and polypropylene feedstock, exposing margins to currency volatility and international polymer pricing swings.
- Mechanical Recycling Technical Limits:Current reprocessing infrastructure cannot handle multi-layer barrier structures, restricting format options for shelf-stable food applications.
- ICONTEC Certification Friction:BIS-equivalent migration limit testing creates extended approval timelines for imported packaging materials, delaying new supplier qualification.
Strategic Opportunities
- Antioquia Processing Corridor Expansion:Medellín's manufacturing hinterland remains underpenetrated for rigid plastic packaging, offering greenfield site potential for thermoforming operations.
- Pacific Alliance Regulatory Harmonization:Convergence of extended producer responsibility schemes across Chile, Mexico, Peru, and Colombia could unlock cross-border scale economies for certified recycled content suppliers.
- Preform-to-Bottle Integration Models:Blow-molding automation convergence with in-house preform production compresses design-to-delivery timelines for carbonated soft drink bottlers.
Industry Challenges
- Recycled Feedstock Quality Variability:Post-consumer rPET flake consistency problems force converters to maintain dual sourcing protocols and redundant quality testing protocols.
- Blow-Molding Technician Shortage:Specialized mold maintenance and process optimization skills remain scarce in Colombia's technical education pipeline, constraining line speed improvements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Rigid Plastic Packaging Market |
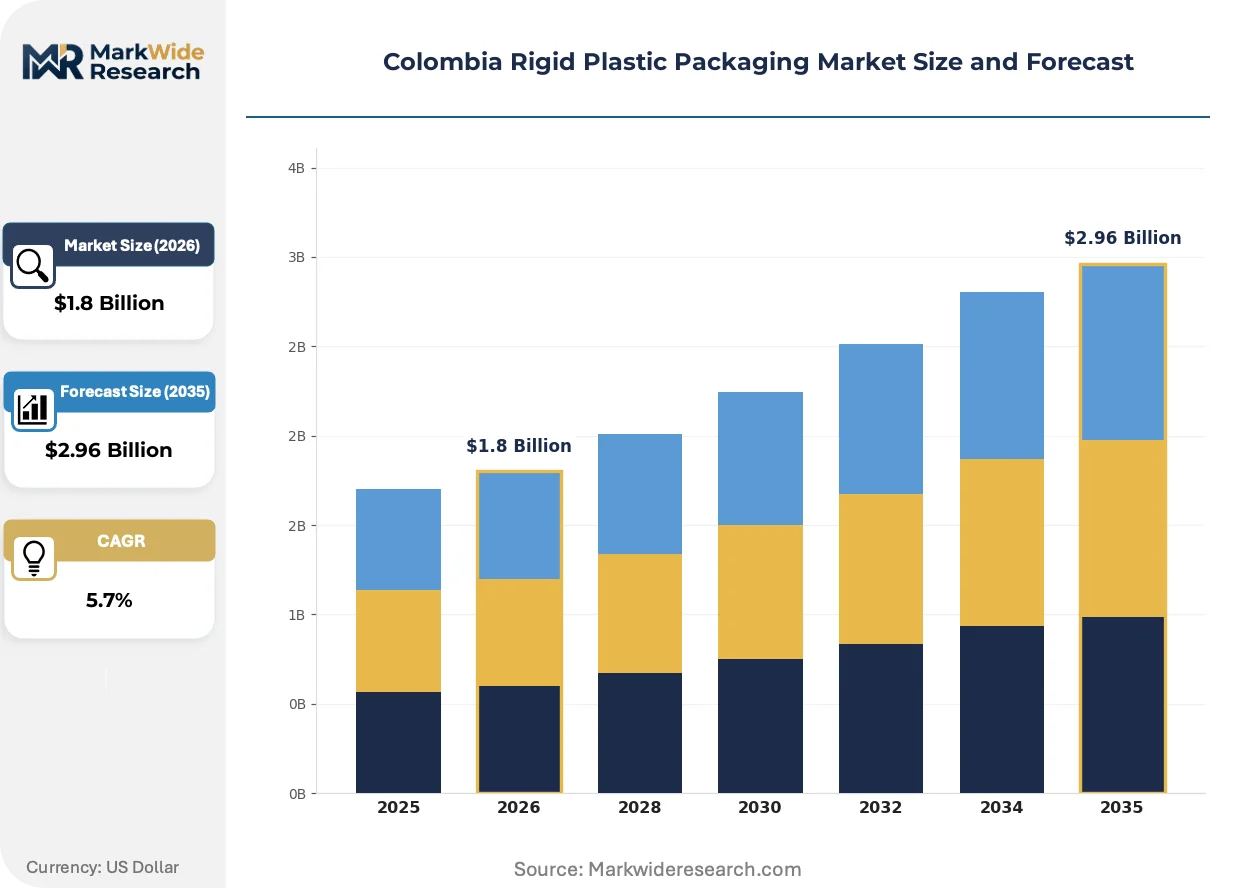
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Containers, Jars, Trays Application: Food, Beverages, Personal Care, Pharmaceuticals Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Consumer Goods, Healthcare, Foodservice, Retail |
| Companies Covered | Berry Global Inc., Amcor Group GmbH, Amfora Packaging SAS, RPM Colombia SAS, Sonoco Products Company, ALPLA Werke Alwin Lehner GmbH & Co KG, Greif Inc, Weener Plastics Group BV, Aptar Group Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Rigid Plastic Packaging Market Trends and Innovations
Lightweighting automation and regulatory compliance technologies are rewriting operational benchmarks across Colombia's converter base. Three distinct vectors are restructuring competitive capabilities and buyer-supplier relationships.
Digital preform inspection systems are rewriting quality assurance protocols in blow-molding operations. Beverage bottlers deploying vision-based defect detection are reducing downstream leaker rates and compressed customer complaint resolution cycles. This technology is enabling just-in-time production scheduling previously impossible with manual sampling methods.
Law 2232 of 2022 compliance reporting through blockchain-tracked recycled content certificates is restructuring supplier qualification requirements. Converters must now document chain-of-custody from post-consumer collection through reprocessing to final article production. Dairy and juice processors face the tightest audit timelines as retail buyers demand real-time verification dashboards.
Direct converter relationships with retail chains are displacing traditional distributor intermediaries in procurement channels. Large-format supermarket operators in Bogotá and Cali now negotiate packaging specifications, sustainability certifications, and volume commitments directly with ALPLA, Berry Global, and Amcor production facilities. This disintermediation concentrates technical negotiation leverage with buyers possessing dedicated packaging engineering staff.
Colombia Rigid Plastic Packaging Market Segmentation
Segmentation reveals how Law 2232 compliance costs and resin sourcing patterns concentrate value across distinct converter specializations. Each dimension exposes different vulnerability points to currency volatility, mechanical recycling limits, and ICONTEC certification friction.
Packaging Type:
Blow-molding and thermoforming capacity concentrates disproportionately around Bogotá's beverage bottling corridor, shaping procurement leverage.
- Bottles:PET blow-molding lines dominate resin throughput, serving carbonated soft drink and bottled water accounts with high-speed automation. Bogotá bottlers command volume discounts through multi-year procurement contracts with preform-integrated suppliers.
- Containers:Injection-molded tubs and pails protect dairy, spreads, and industrial chemicals through stackable geometries and tamper-evident closures. Dairy processors in Cundinamarca specify PP homopolymer for microwave reheating compatibility.
- Jars:Wide-mouth PET and PVC formats preserve moisture-sensitive condiments and personal care creams; neck finish standardization reduces capping equipment changeover costs.
- Trays:Thermoformed PET and PS structures display fresh produce and prepared meals; retail chains now mandate minimum recycled content thresholds for shelf placement.
Bottles absorb the bulk of installed capacity; trays are expanding most quickly as fresh-format retail penetration deepens.
Application:
End-use profitability stratifies sharply based on shelf-life requirements and regulatory scrutiny intensity.
- Food:Barrier trays and retort pouches demand multi-layer coextrusion capability; prepared food processors pay premiums for oxygen scavenger integration.
- Beverages:Carbonated and non-carbonated liquid containment drives the highest volume resin consumption; lightweighting programs target sub-10 gram PET bottle weights.
- Personal Care:Cosmetic jars and dispensing closures require aesthetic-grade resin with low haze and color consistency; fragrance compatibility testing extends qualification timelines.
- Pharmaceuticals:Child-resistant and senior-friendly closure compliance absorbs disproportionate quality assurance labor; blister packs face strict migration limit enforcement.
Beverages command the greatest absolute tonnage; pharmaceuticals sustain the steepest margin premiums.
Material:
Resin selection trade-offs hinge on recyclability certification pathways and import tariff exposure.
- Polyethylene:HDPE and LDPE grades serve blow-molded milk jugs and squeeze tubes; domestic recycling streams achieve higher flake purity for HDPE versus LDPE.
- Polypropylene:Random and impact copolymers displace polystyrene in dairy trays as EPR schemes penalize non-recyclable formats; Medellín converters are expanding PP thermoforming capacity.
- Polyvinyl Chloride:Clarity and chemical resistance sustain pharmaceutical blister and blood bag demand; environmental NGO pressure constrains brand owner adoption.
- Polystyrene:Foamed and crystal grades retreat to low-cost disposable applications; major supermarket chains have announced phase-out timelines.
Polyethylene retains the largest installed processing base; polypropylene is gaining share fastest through dairy and prepared food conversion.
End User:
Customer concentration patterns determine converter pricing power and technical service intensity.
- Consumer Goods:Multinational FMCG accounts negotiate global framework agreements with regional production commitments; sustainability scorecards weight recycled content and carbon footprint.
- Healthcare:Hospital and pharmacy distribution demands lot traceability and sterile barrier validation; converter margins compensate for extended qualification protocols.
- Foodservice:Disposable cutlery, cups, and clamshells face the steepest Law 2232 restrictions; biodegradable alternatives capture institutional catering procurement.
- Retail:Private-label packaging specifications flow directly from supermarket chains to converter engineering teams, bypassing traditional distributor intermediaries.
Consumer goods anchor converter revenue stability; retail direct procurement is restructuring channel economics fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethylene and polypropylene resin imports through Cartagena and Barranquilla ports anchor Colombia's rigid plastic packaging geography. Bogotá's industrial corridor concentrates conversion capacity near beverage bottling and dairy processing clusters. Regional disparities in recycling infrastructure and regulatory enforcement create divergent operating conditions across Colombian territory.
Andean Region
Dairy processors in Cundinamarca and Boyacá specify polypropylene trays for microwave reheating compatibility. Colombia's Ministry of Environment enforces Law 2232 of 2022 recycled content thresholds most stringently here. Bogotá's Fontibón and Soacha industrial zones host blow-molding and thermoforming facilities serving carbonated soft drink bottlers.
Caribbean Coast
Resin import terminals at Cartagena and Barranquilla reduce logistics costs for converters serving export-oriented food processors. The national customs authority administers duty drawback programs for packaging materials incorporated into exported goods. Free trade zone status in Barranquilla attracts thermoforming investments targeting Central American markets.
Antioquia
Medellín's manufacturing hinterland remains underpenetrated for rigid plastic packaging relative to its food processing base. The regional government promotes industrial park development through tax incentive programs. Rionegro and La Ceja host emerging converter operations supplying dairy and prepared food accounts.
Valle del Cauca
Cali's foodservice and retail distribution hub generates demand for disposable containers and display trays. Sugar refineries and processed food exporters in Palmira and Yumbo specify barrier packaging for humidity-sensitive exports. The Pacific port of Buenaventura enables direct resin importation bypassing Caribbean transshipment.
Santander
Bucaramanga's petrochemical proximity through Ecopetrol's Barrancabermeja refinery complex offers potential feedstock integration advantages. Regional beverage bottlers currently source preforms from Bogotá-based suppliers. The national petroleum company evaluates polypropylene production expansion that would alter resin sourcing economics.
Colombia Rigid Plastic Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as converters position for Law 2232 compliance deadlines and recycled content procurement requirements. The vendor base stratifies between multinational integrated packaging groups with preform-to-bottle capabilities and regional specialists in dairy tray and industrial pail fabrication. Three archetypes occupy distinct competitive positions: resin-integrated global suppliers, automation-focused regional converters, and niche specialists in pharmaceutical barrier formats. Geographic expansion through greenfield thermoforming investments and backward integration into preform production represent the dominant competitive vectors reshaping procurement relationships.
Within the integrated multinational tier, ALPLA Werke Alwin Lehner GmbH & Co KG anchors blow-molding capacity through regional production network positioning. Berry Global Inc. exemplifies lightweighting automation specialization across dairy and juice account segments. Amcor Group GmbH occupies a position emphasizing preform-to-bottle integration for carbonated soft drink bottler relationships. These three entities represent contrasting strategic postures: geographic density, material efficiency programs, and design-to-delivery timeline control respectively.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Amcor Group GmbH |
| Amfora Packaging SAS |
| RPM Colombia SAS |
| Sonoco Products Company |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Greif Inc |
| Weener Plastics Group BV |
| Aptar Group Inc |
| Others |
Pricing and Supply Chain Analysis
Polyethylene and polypropylene resin indices on the Gulf Coast and Rotterdam benchmarks cascade through Colombian converter pricing tiers, compressing margins for non-integrated suppliers while rewarding preform-to-bottle operators with captive resin hedging. Law 2232 compliance costs layer atop raw material volatility, forcing a three-tier pricing structure across premium certified-recycled, standard virgin-content, and economy spot-purchase contract levels.
Pricing Analysis
Warranty and technical service bundling separates premium converter relationships from transactional spot purchases, with ALPLA and Amcor embedding mold maintenance and line optimization into multi-year beverage contracts while regional specialists price equipment support separately. Price differentiation hinges on ICONTEC certification tier and volume scale, with dairy processors commanding steepest discounts through consolidated tray procurement. Cost compression in the standard tier is intensifying because resin import exposure and currency hedging costs erode converter margins. Foodservice distributors exhibit highest price sensitivity due to Law 2232 disposable restrictions, while pharmaceutical accounts absorb premium pricing for barrier validation and lot traceability.
Supply Chain Analysis
Post-consumer collection and mechanical reprocessing flows remain underdeveloped, forcing converters to source rPET flake through informal recycler networks with inconsistent quality documentation. Resin supply concentrates in the United States, Saudi Arabia, and South Korea for polyethylene and polypropylene feedstock, with domestic converters drawing from Cartagena and Barranquilla import terminals. Raw material sourcing rests on naphtha-derived polymer pellets, masterbatch colorants, and barrier additive packages. Single-source vulnerability runs through Gulf Coast petrochemical complexes exposed to hurricane disruption. Distribution runs through Bogotá-based converter direct sales to beverage bottlers and dairy processors, bypassing traditional distributor layers for large-format accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's rigid plastic packaging sector is consolidating around Law 2232 compliance capabilities, with recycled content certification investments forcing sub-scale converters toward exit or acquisition. Technical audit requirements and preform-to-bottle capital intensity favor integrated multinational operators.
For Market Incumbents: Anticipate margin compression from resin price volatility by securing backward integration into preform production or long-term offtake agreements with Gulf Coast suppliers. Defensive positioning requires accelerating Medellín corridor capacity to capture underpenetrated dairy and prepared food accounts before regional specialists consolidate. Channel control through direct retail chain relationships offers pricing power against distributor-dependent competitors. For New Entrants and Emerging Players: Law 2232 of 2022 in Colombia opens a window for specialized mechanical recycling operators capable of certifying rPET flake consistency for beverage bottler procurement. White-space targets concentrate in Antioquia thermoforming capacity for dairy tray conversion and pharmaceutical barrier formats for hospital distribution. Go-to-market positioning should emphasize blockchain-tracked chain-of-custody documentation for retail buyer sustainability scorecards. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap converters with ICONTEC certification infrastructure and established dairy processor relationships in Cundinamarca and Boyacá. Long-term viability centers on regulatory compliance capability rather than scale alone, with Pacific Alliance harmonization creating cross-border platform potential. The signal to watch is Ecopetrol's Barrancabermeja polypropylene production expansion timeline, which would reshape domestic resin sourcing economics and incumbent positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Production | Captive supply of PET preforms compresses design-to-delivery timelines for carbonated soft drink bottlers. |
| Mechanical Recycling Certification Investment | Law 2232 compliance enables access to retail buyer procurement mandates with recycled content thresholds. |
| Antioquia Corridor Greenfield Expansion | Medellín manufacturing hinterland offers first-mover positioning for dairy and prepared food tray supply. |
| Direct Retail Chain Relationship Development | Bypassing distributor intermediaries concentrates technical negotiation leverage with supermarket packaging engineering staff. |
| Pacific Alliance Regulatory Harmonization Alignment | Cross-border scale economies emerge for certified recycled content suppliers across Chile, Mexico, Peru, and Colombia. |
Research Methodology
Trade publications, resin price reporting services, and ICONTEC technical standards formed the secondary backbone for market sizing and regulatory mapping. Primary interviews with blow-molding plant managers, dairy processor procurement leads, beverage bottler supply chain directors, and retail category buyers validated converter capacity estimates and pricing dynamics. Bottom-up and top-down triangulation reconciled resin import volumes through Cartagena and Barranquilla customs data against end-use consumption patterns.
Bottom-up modeling anchored volume projections to installed blow-molding and thermoforming capacity across Bogotá, Medellín, and Cali industrial zones, cross-referenced against beverage bottler and dairy processor expansion announcements. Segmentation dimensions included packaging type, material grade, application shelf-life requirements, and end-user concentration patterns. CAGRs were derived from polymer demand elasticity estimates and regulatory compliance cost pass-through assumptions across the projection horizon. Forecast inputs incorporated Law 2232 implementation timelines and Pacific Alliance harmonization scenarios.
Caveats apply where resin price volatility, currency depreciation, or mechanical recycling infrastructure delays could materially shift the outlook. Practitioners should monitor Ecopetrol petrochemical expansion announcements and ICONTEC certification backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Rigid Sleeve Boxes Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market