
 Vietnam Rigid Plastic Packaging Market | 2026-2036
Vietnam Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Rigid Plastic Packaging Market Insights
Food and beverage processing is restructuring Vietnam's rigid plastic packaging procurement patterns. Duy Tan Plastics Corporation leverages its southern manufacturing footprint to anchor supply for domestic beverage bottlers. Indorama Ventures Vietnam sustains PET resin integration that feeds downstream bottle production. ALPLA Werke Alwin Lehner GmbH & Co KG competes through specialized preform and closure systems for multinational brand owners.
Vietnam rigid plastic packaging encompasses molded or thermoformed containers—typically 0.3–5.0 mm wall thickness—fabricated from polyethylene, polypropylene, polystyrene, or PVC to protect goods during distribution and shelf display. Injection molding and extrusion blow molding dominate production, with polyethylene bottles capturing volume leadership due to cost efficiency in beverage and household chemical applications. Polypropylene containers are expanding fastest in food service and ready-meal segments where heat resistance and microwave compatibility command margin premiums. The jars category remains mature in personal care, while trays face structural pressure from fiber-based alternatives in fresh produce.
Vietnam's Ministry of Natural Resources and Environment enforces plastic waste management decrees that mandate recycled content thresholds and extended producer responsibility schemes. The General Department of Vietnam Customs coordinates import controls on virgin resin flows, shaping raw material access for domestic converters. BIS-equivalent national standards on food-contact materials constrain formulation choices for healthcare and food end users. Stakeholders must monitor how circular economy enforcement timelines and recycling infrastructure investments reshape material specifications and supplier qualification requirements.
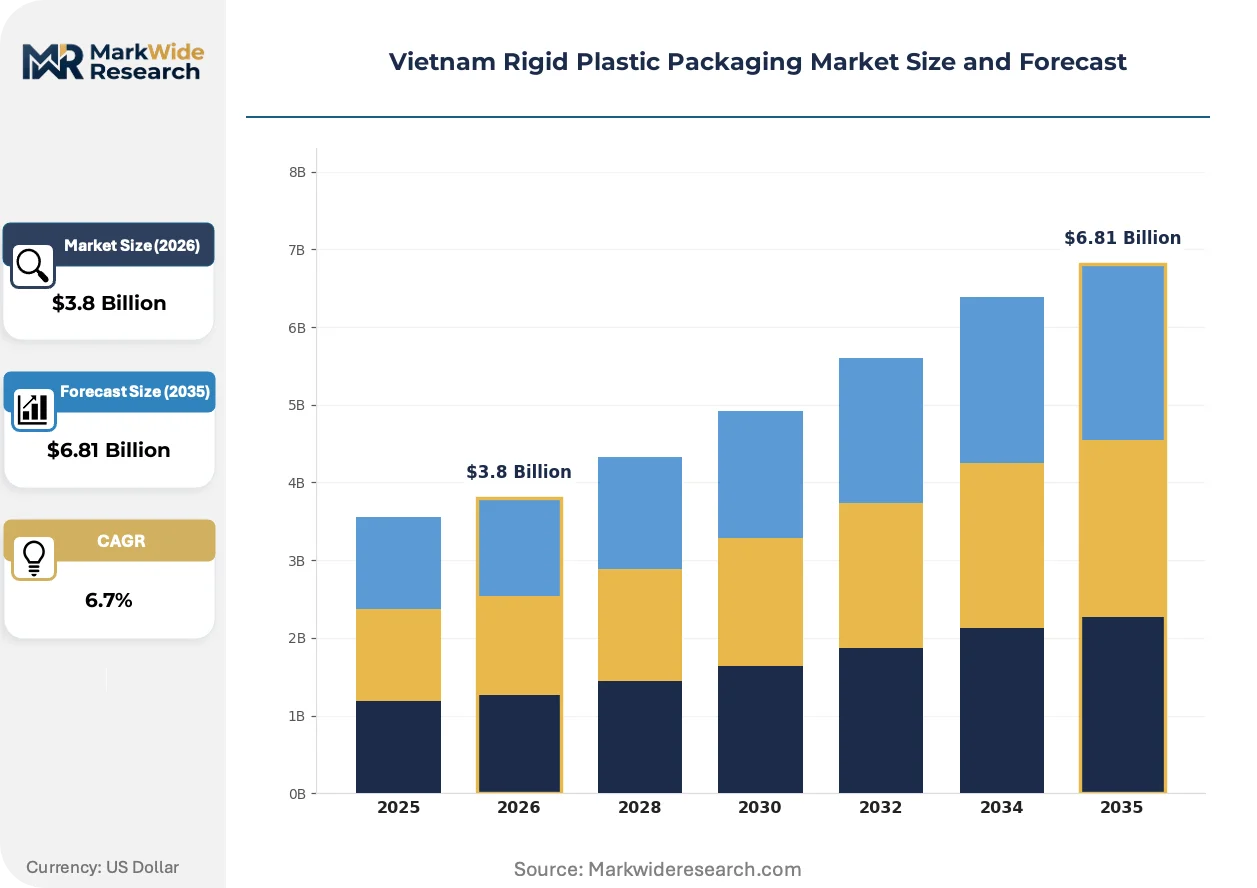
Market Dynamics
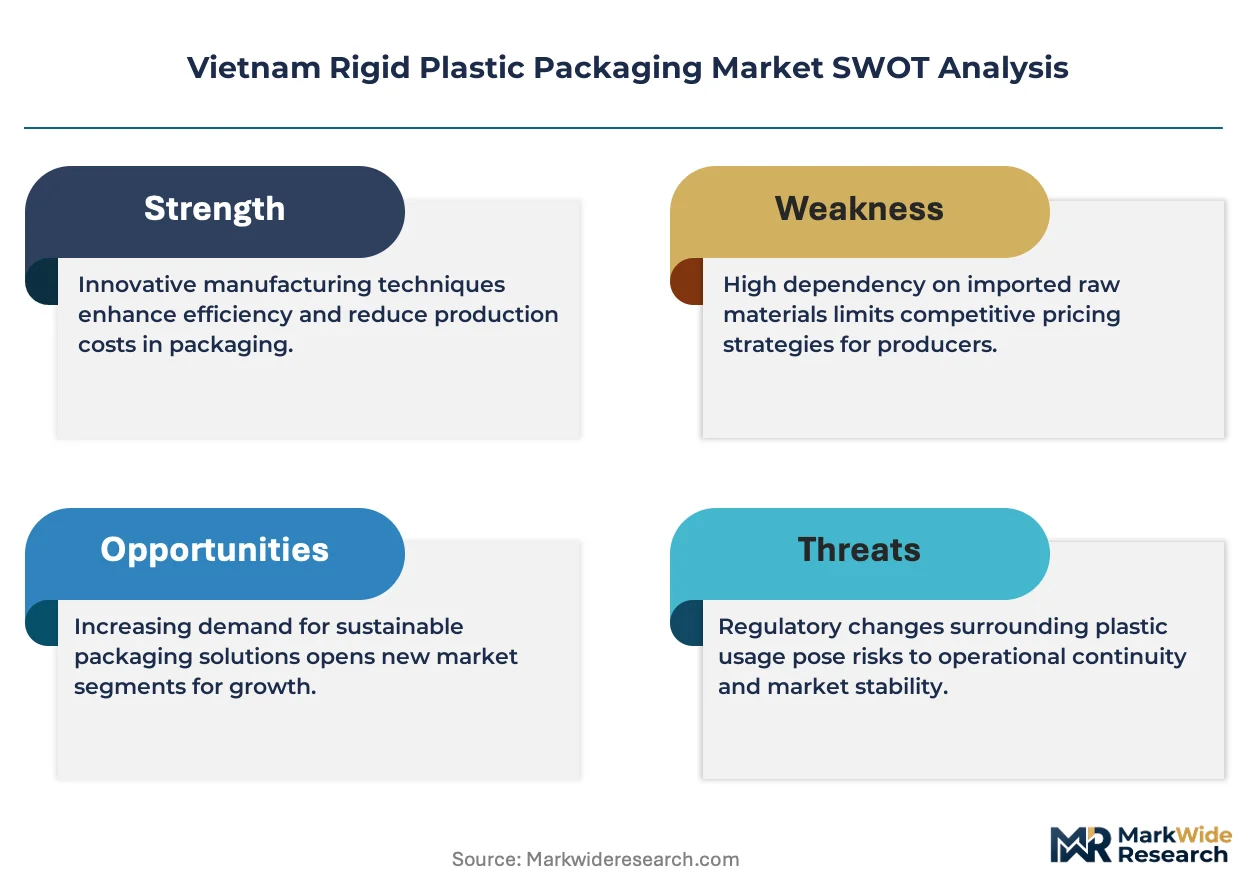
Circular economy mandates from Vietnam's Ministry of Natural Resources and Environment are forcing converters to reengineer resin specifications and recycling infrastructure simultaneously. This regulatory pressure intersects with raw material cost volatility and multinational brand owner sustainability targets to compress margins across the value chain.
Growth Catalysts
- Extended Producer Responsibility Decrees:Vietnam's plastic waste management framework mandates recycled content thresholds that pull investment into domestic recycling capacity and qualified resin supply.
- Food Service Heat-Resistance Demand:Polypropylene containers with microwave compatibility are capturing premium positioning in ready-meal and food service segments as convenience formats expand.
- Southern Industrial Corridor Concentration:Manufacturing gravity around Ho Chi Minh City and Binh Duong province creates density economies for converter operations and logistics.
Market Restraints
- Virgin Resin Import Dependency:General Department of Vietnam Customs controls on polyethylene and polypropylene flows expose converters to currency fluctuation and supply interruption.
- Fiber-Based Substitution Pressure:Molded fiber trays and paperboard alternatives are displacing polystyrene and PET in fresh produce applications where wet strength has improved.
- Recycling Infrastructure Gaps:Collection system fragmentation and sorting capacity shortfalls limit feedstock availability for food-grade recycled resin production.
Strategic Opportunities
- Mekong Delta Underpenetration:Agricultural processing and aquaculture packaging demand in Can Tho and surrounding provinces remains underserved by rigid plastic converters.
- Chemical Recycling Scale-Up:Pyrolysis and depolymerization investments can unlock food-contact approved recycled content beyond mechanical recycling limitations.
- Central Highlands Distribution Expansion:Da Lat vegetable and coffee processing clusters present untapped demand for modified atmosphere rigid containers.
Industry Challenges
- Food-Contact Certification Timelines:BIS-equivalent national standards for healthcare and food applications impose extended testing protocols that delay new product launches.
- Skilled Blow Molding Technician Scarcity:Extrusion and injection blow molding process engineering expertise concentrates with legacy operators, constraining new entrant scale-up.
- Legacy Equipment Retrofit Costs:Existing injection molding assets require substantial modification to process high percentages of recycled resin without quality degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Rigid Plastic Packaging Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays Material: Polyethylene, Polypropylene, Polystyrene, PVC End User: Food & Beverage, Healthcare, Personal Care, Household Packaging Type: Plastic Boxes, Rigid Clamshells, Blister Packs, Tubs |
| Companies Covered | Taiwan Hon Chaun Group, ALPLA Werke Alwin Lehner GmbH & Co KG, Bericap Holding GmbH, Duy Tan Plastics Corporation, Indorama Ventures Vietnam, IML Containers (Groupe Lacroix), Inplas Vietnam JSC, Greif Inc, VisyPak, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Rigid Plastic Packaging Market Trends and Innovations
Material science advances and regulatory compliance requirements are converging to reshape converter technology roadmaps and customer qualification protocols across Vietnam's rigid plastic packaging sector.
Mono-material PET bottle designs with integrated handle features and full-body shrink sleeve compatibility are electrifying lightweighting roadmaps for beverage brand owners. Domestic bottlers are adopting these formats at pilot scale ahead of multinational parent company mandates. The technology is compressing multi-component closure and label supply chains into streamlined single-resin recovery streams.
Vietnam's Ministry of Natural Resources and Environment is tightening enforcement timelines for circular economy regulations that mandate post-consumer recycled content in rigid containers. Industrial consequence includes accelerated converter investment in domestic recycling partnerships and imported pellet qualification. Food and beverage end-use segments are most affected, with brand owners demanding supplier documentation on recycled resin chain of custody.
Direct procurement relationships between multinational brand owners and certified converters are displacing traditional distributor-mediated supply arrangements in high-volume beverage and personal care segments. Tier-one converters with integrated preform production and laboratory testing capabilities are capturing preferred supplier status. This pattern concentrates most visibly in the southern industrial corridor where multinational manufacturing joint ventures anchor demand.
Vietnam Rigid Plastic Packaging Market Segmentation
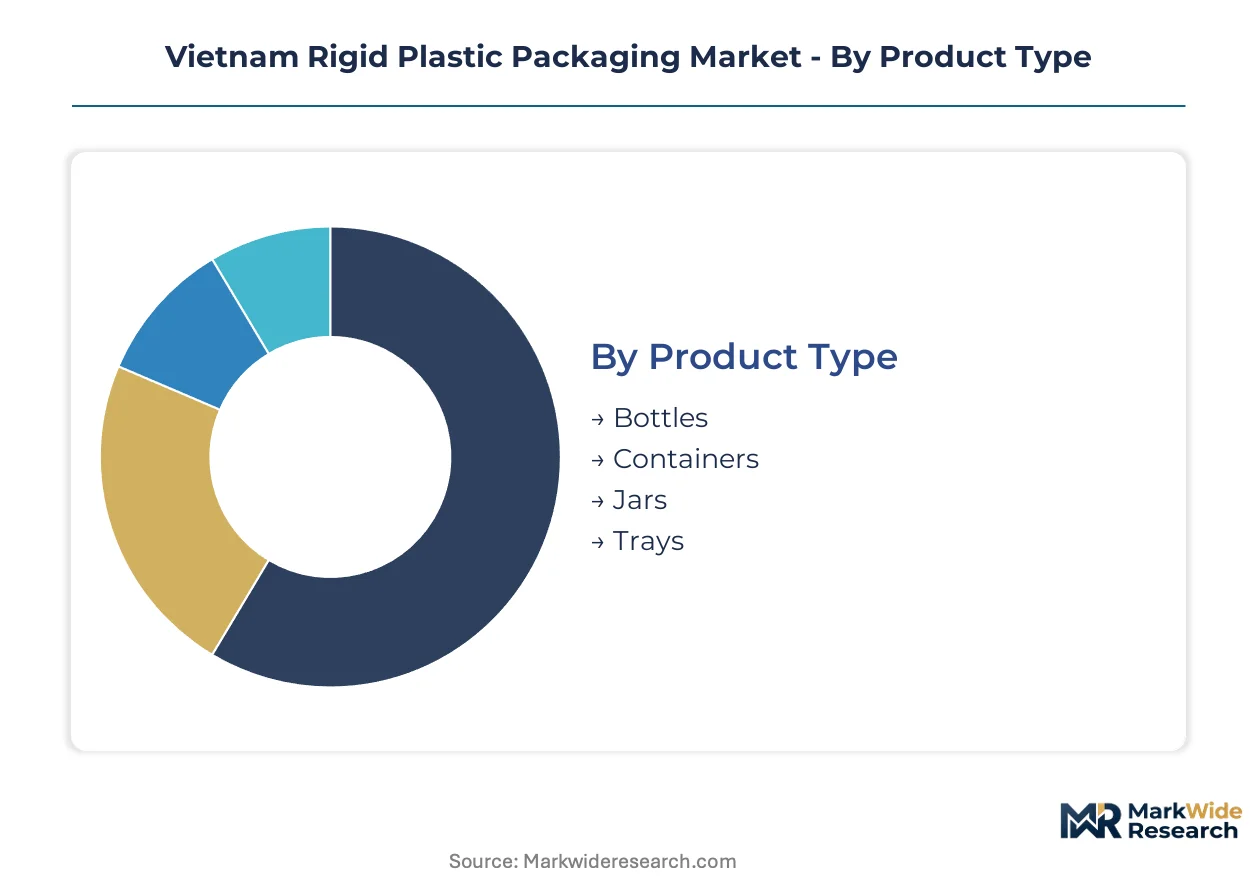
Vietnam's rigid plastic packaging market fragments across four distinct dimensions that shape converter investment priorities and procurement patterns. Product type and material composition drive manufacturing technology choices, while end-user specifications and packaging formats determine margin structures and regulatory compliance requirements.
Product Type:
Volume leadership sits with beverage bottles, while premium positioning concentrates in specialized containers for food service and healthcare applications.
- Bottles:Polyethylene and PET bottles dominate beverage and household chemical applications through extrusion and injection blow molding. Ho Chi Minh City bottlers anchor procurement for carbonated soft drinks and bottled water, though lightweighting mandates are compressing resin throughput per unit.
- Containers:Polypropylene containers with heat-resistant properties command margin premiums in ready-meal and food service segments. Binh Duong province converters are expanding microwave-compatible formats as convenience food processors deepen southern manufacturing footprints.
- Jars:Wide-mouth polystyrene and PET jars serve personal care and condiment applications with established toolsets and shorter qualification timelines.
- Trays:Thermoformed PET and polystyrene trays face substitution pressure from molded fiber in fresh produce, though modified atmosphere specifications retain rigid plastic demand in premium protein packaging.
Mature deployment sits with bottles. Newer deployment is concentrated in containers.
Material:
Cost tier stratification separates commodity polyethylene from performance-grade polypropylene, with regulatory pressure reshaping recycled content specifications across all resin categories.
- Polyethylene:HDPE and LDPE grades capture volume leadership through cost efficiency in beverage bottles and household chemical containers. The Ministry of Natural Resources and Environment's recycled content mandates are forcing reformulation of virgin-heavy legacy specifications.
- Polypropylene:Homopolymer and copolymer grades are expanding most quickly in food service applications where heat resistance and microwave compatibility justify price premiums. Da Nang and Can Tho food processors are emerging as demand anchors beyond the southern corridor.
- Polystyrene:General purpose and high-impact grades retain position in personal care jars and disposable food service, though environmental scrutiny is narrowing application scope.
- PVC:Rigid PVC compounds serve specialized pharmaceutical blister and chemical-resistant applications with constrained growth due to formulation complexity and disposal regulations.
Commodity deployment concentrates in polyethylene. Performance deployment is accelerating in polypropylene.
End User:
Customer-type concentration separates multinational brand owners with sustainability mandates from domestic processors prioritizing unit economics.
- Food & Beverage:Beverage bottlers and processed food manufacturers generate the largest procurement volumes, with multinational joint ventures in Binh Duong and Dong Nai provinces driving specifications for recycled content and lightweight designs.
- Healthcare:Pharmaceutical and medical device packaging demands BIS-equivalent national standards compliance for food-contact and sterilization compatibility, extending supplier qualification timelines.
- Personal Care:Cosmetics and toiletries brand owners prioritize aesthetic surface finish and decoration compatibility in jars and bottles, with Ho Chi Minh City converters capturing design-intensive contracts.
- Household:Detergent and cleaning chemical processors favor HDPE bottles with chemical resistance and cost-optimized closure systems, representing stable but lower-margin demand.
Established procurement patterns sit with food and beverage. Emerging specification complexity is concentrated in healthcare.
Packaging Type:
Manufacturing process differentiation separates injection-molded boxes from thermoformed clamshells, with equipment specialization creating supplier segmentation.
- Plastic Boxes:Injection-molded PP and HDPE boxes serve industrial and food storage applications with stackability and durability specifications. Central Highlands agriculture processors are expanding demand for harvest and distribution containers.
- Rigid Clamshells:Thermoformed PET clamshells dominate fresh produce and electronics retail display, though fiber-based alternatives are capturing share in wet-strength-sensitive applications.
- Blister Packs:PVC and PET blister formats serve pharmaceutical unit-dose and consumer goods visibility packaging with exacting barrier and child-resistance requirements.
- Tubs:Injection-molded PP tubs capture dairy, spreads, and ready-meal segments where resealability and refrigeration compatibility matter.
Process-standardized deployment sits with plastic boxes. Technology-intensive deployment is expanding in blister packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production concentrates in the southern industrial corridor, while northern and central provinces remain consumption zones dependent on long-haul logistics. The Ministry of Natural Resources and Environment's circular economy mandates are accelerating regional capacity imbalances as converters cluster near Ho Chi Minh City to access recycling infrastructure and brand owner manufacturing joint ventures.
Southern Industrial Corridor
Beverage bottlers and food processors in Ho Chi Minh City and Binh Duong province generate the densest packaging procurement volumes. The General Department of Vietnam Customs operates port-of-entry resin inspection facilities at Cat Lai and Cai Mep-Thi Vai, streamlining polyethylene and polypropylene flows for southern converters. Duy Tan Plastics Corporation and Indorama Ventures Vietnam anchor manufacturing footprints in this zone, feeding downstream bottle production for multinational brand owners.
Mekong Delta
Agricultural processing and aquaculture packaging demand in Can Tho and surrounding provinces outpaces local rigid plastic supply. The Ministry of Agriculture and Rural Development promotes post-harvest infrastructure investment, yet converter presence remains thin. Traders bridge the gap with trucked-in containers from Ho Chi Minh City, inflating landed costs for rice millers and seafood exporters.
Central Highlands
Da Lat vegetable and coffee processing clusters present untapped demand for modified atmosphere rigid containers. The Lam Dong provincial government incentivizes cold chain investment, but blow molding and thermoforming capacity is absent. Processors rely on imported packaging from the southern corridor or inferior fiber-based alternatives that compromise shelf life.
Central Coast
Da Nang food processors are emerging as demand anchors beyond the southern corridor, particularly for polypropylene containers with heat-resistant specifications. The Da Nang Hi-Tech Park administration courts packaging converters to colocate with expanding convenience food manufacturing. Logistics connectivity via Hai Van Pass tunnel reduces transit times from Ho Chi Minh City, though local production remains minimal.
Northern Key Economic Zone
Hanoi and Hai Phong beverage bottlers source rigid plastic packaging through distributor networks rather than direct converter relationships. The Ministry of Industry and Trade designates northern provinces for industrial relocation, yet resin access depends on overland transport from central coast ports. Northern procurement patterns favor cost-optimized HDPE bottles over premium polypropylene formats prevalent in the south.
Vietnam Rigid Plastic Packaging Market Competitive Landscape
Top-tier vendors anchor multinational supply relationships, while mid-scale domestic converters compete on logistics proximity and qualification speed. The vendor base stratifies across three tiers: integrated resin-to-preform operators, standalone blow molding specialists, and trading houses with tolling arrangements. Two strategic archetypes dominate: southern corridor incumbents leveraging density economies, and foreign-owned specialists capturing premium specifications. Competitive intensity centers on recycled content certification timelines and laboratory testing capabilities rather than unit pricing alone.
Among foreign-owned specialists, ALPLA Werke Alwin Lehner GmbH & Co KG and Bericap Holding GmbH exemplify the premium-tier archetype through specialized preform and closure systems. Duy Tan Plastics Corporation occupies a position as the dominant domestic converter with southern manufacturing density. Indorama Ventures Vietnam represents backward-integrated resin supply that feeds downstream bottle production for beverage brand owners. These three anchors illustrate how competitive positioning separates integrated operators from standalone converters in qualification-intensive segments.
| Leading Market Players |
|---|
| Taiwan Hon Chaun Group |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Bericap Holding GmbH |
| Duy Tan Plastics Corporation |
| Indorama Ventures Vietnam |
| IML Containers (Groupe Lacroix) |
| Inplas Vietnam JSC |
| Greif Inc |
| VisyPak |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between food-contact approved converters and general-purpose molders manifests in both pricing premiums and supply chain tiering. Vietnam's Ministry of Natural Resources and Environment recycled content mandates compress margins for non-compliant operators while concentrating procurement power with southern corridor incumbents who have secured BIS-equivalent laboratory certifications.
Pricing Analysis
Lead-time premiums for certified recycled resin batches command 15-20% markups over virgin polyethylene spot pricing. Three-tier pricing structure across premium, standard, and economy levels separates multinational brand owner contracts from domestic processor spot purchases. Pricing pressure stems from General Department of Vietnam Customs resin import controls and currency fluctuation exposure. Domestic beverage bottlers exhibit highest price sensitivity, while pharmaceutical and healthcare end users absorb premiums for compliance documentation.
Supply Chain Analysis
Dual-sourcing requirements from multinational brand owners mandate multi-supplier qualification across at least two certified converters per resin category. Geographic supply concentration centers on Thailand, South Korea, and Singapore for virgin polyethylene and polypropylene resin flows. Raw material dependencies include naphtha-derived ethylene, propylene monomer, and imported food-grade recycled pellets. Single-source vulnerability concentrates around Cat Lai port resin inspection bottlenecks. Distribution runs through converter-direct relationships with beverage bottlers and distributor-mediated channels for northern provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's rigid plastic packaging market operates as a supply-constrained environment where domestic recycling infrastructure gaps prop pricing premiums for certified recycled content. Qualified converter capacity limits outpace demand expansion, sustaining margin structures for compliant operators.
For Market Incumbents: Hedge against fiber-based substitution pressure by accelerating chemical recycling partnerships that unlock food-contact approved feedstock beyond mechanical recycling limitations. Expand captive preform production capacity in Binh Duong province to defend share against ALPLA Werke Alwin Lehner GmbH & Co KG and Bericap Holding GmbH closure system specialists. Prioritize laboratory certification investment as the priority lever for multinational brand owner retention. For New Entrants and Emerging Players: The mid-tier pricing gap between premium multinational-serving converters and economy domestic processors creates entry space for specialized operators. Target Mekong Delta agricultural packaging demand in Can Tho and surrounding provinces where converter presence remains thin and logistics costs inflate landed pricing. Pursue tolling arrangements with established southern molders as the go-to-market angle to bypass capital-intensive equipment acquisition. For Investors and Strategic Acquirers: Re-rating potential sits with backward-integrated resin-to-preform operators given Ministry of Natural Resources and Environment enforcement timeline acceleration. Long-term viability favors converters with captive recycling partnerships and laboratory testing capabilities over standalone blow molding specialists. Watch for General Department of Vietnam Customs import quota adjustments as the inflection signal for raw material cost volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis investments unlock food-contact recycled content beyond mechanical recycling constraints. |
| Backward Integration into Preform Production | Captive preform supply secures margin control against specialized closure system competitors. |
| Central Highlands Distribution Expansion | Da Lat vegetable processing clusters present untapped demand for modified atmosphere containers. |
| BIS-Equivalent Laboratory Certification | Food-contact compliance documentation captures multinational brand owner procurement preference. |
| Mekong Delta Converter Facility | Can Tho colocation reduces logistics inflation for rice miller and seafood exporter demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at southern corridor converters, procurement leads at beverage bottlers, distribution channel partners, and technical R&D directors at resin suppliers combined with secondary validation from General Department of Vietnam Customs import statistics, Ministry of Natural Resources and Environment decree documentation, and industry association production surveys. Bottom-up capacity modeling and top-down demand estimation triangulated volume outputs.
Data-stream reconciliation across converter production surveys, resin import manifests, and end-user procurement patterns informed the analytical framework. Segmentation dimensions modeled include product type, material composition, end-user industry, and packaging format across the projection horizon. CAGRs derived from weighted average growth rates across segment-level demand drivers and capacity expansion timelines. Industry-specific forecast inputs incorporated recycled content mandate compliance schedules and multinational brand owner sustainability target adoption curves.
Underlying measurement precision varies by segment; beverage bottles and food containers carry tighter precision than pharmaceutical blister packs and industrial boxes. Forecasts reflect assumptions on regulatory enforcement timelines, resin import quota stability, and recycling infrastructure investment flows. Deviation in Ministry of Natural Resources and Environment decree implementation schedules or General Department of Vietnam Customs inspection protocols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
United Kingdom Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
Rigid Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Middle East and Africa Rigid Bulk Packaging Market
Rigid Packaging
Rigid Industrial Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market