
 GCC Rigid Plastic Packaging Market | 2026-2036
GCC Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Rigid Plastic Packaging Market Foresight
Saudi Arabia's Eastern Province is fragmenting as new resin-to-package production complexes come online. Sabic Packaging Solutions leverages backward integration into polyethylene feedstock to control raw material costs. Takween Advanced Industries anchors its position through specialized pharmaceutical-grade blow molding capabilities. Zamil Plastic Industries Co. competes across the full container spectrum from dairy bottles to industrial pails.
GCC rigid plastic packaging comprises thermoformed and injection-molded containers with wall thickness exceeding 0.25 millimeters, engineered to protect goods from moisture, oxidation, and mechanical damage during distribution. Polyethylene Terephthalate bottles lead volume due to carbonated soft drink and bottled water demand across the Gulf states. Polypropylene containers represent the fastest-expanding material category, driven by hot-fill dairy and ready-meal applications requiring thermal resistance above 120 degrees Celsius. Food and Beverage applications command the largest share of value, while Pharmaceuticals packaging captures premium margins due to Saudi Food and Drug Authority child-resistance mandates.
Saudi Food and Drug Authority regulations on pharmaceutical serialization and traceability reshape primary packaging specifications across the Kingdom. UAE's Ministry of Industry and Advanced Technology enforces Gulf Standardization Organization conformity marks for food-contact plastics, creating compliance barriers for non-certified imports. Stakeholders must monitor how extended producer responsibility frameworks under development in Bahrain and Oman alter cost structures for single-use containers.
Market Dynamics
Saudi Vision 2030 industrial localization mandates are forcing resin-to-package integration across the Eastern Province petrochemical corridor, compressing import dependency while fragmenting incumbent supply positions.
Growth Catalysts
- Hot-fill dairy proliferation:Polypropylene containers rated above 120 degrees Celsius capture ready-meal and UHT dairy expansion across Saudi Arabia and the UAE. Food-contact compliance under Gulf Standardization Organization marks accelerates domestic substitution.
- Pharmaceutical serialization mandates:Saudi Food and Drug Authority traceability rules reshape primary packaging specifications, forcing child-resistant closure adoption and premium-grade polymer sourcing.
- Jebel Ali logistics clustering:Dubai's free zone concentration enables just-in-time container supply to African and South Asian export markets, reducing working capital cycles for regional converters.
Market Restraints
- Ethylene feedstock concentration:Sabic's dominance in Saudi polyethylene supply creates single-source vulnerability for non-integrated packaging converters during turnarounds.
- Import certification friction:Gulf Standardization Organization conformity mark requirements extend lead times for European and Asian resin suppliers unfamiliar with regional testing protocols.
- Aluminum can substitution:Carbonated soft drink brands in the UAE trial metal packaging for premium positioning, compressing PET bottle volume in beverage segments.
Strategic Opportunities
- Oman and Bahrain EPR white space:Extended producer responsibility frameworks under development create first-mover advantage for integrated collection-recycling infrastructure.
- Pharmaceutical blow molding specialization:High-barrier multilayer containers for biologics storage represent underpenetrated premium tier with SFDA compliance as entry barrier.
- Digital printing convergence:Direct-to-object inkjet on rigid containers enables lot-size-one customization for promotional beverage campaigns.
Industry Challenges
- Multilayer delamination expertise gap:EVOH barrier layer adhesion control requires polymer science specialists scarce in Gulf technical institutes.
- Hot-runner mold capex intensity:Thin-wall injection systems for food containers demand capital commitments exceeding mid-converter balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Rigid Plastic Packaging Market |
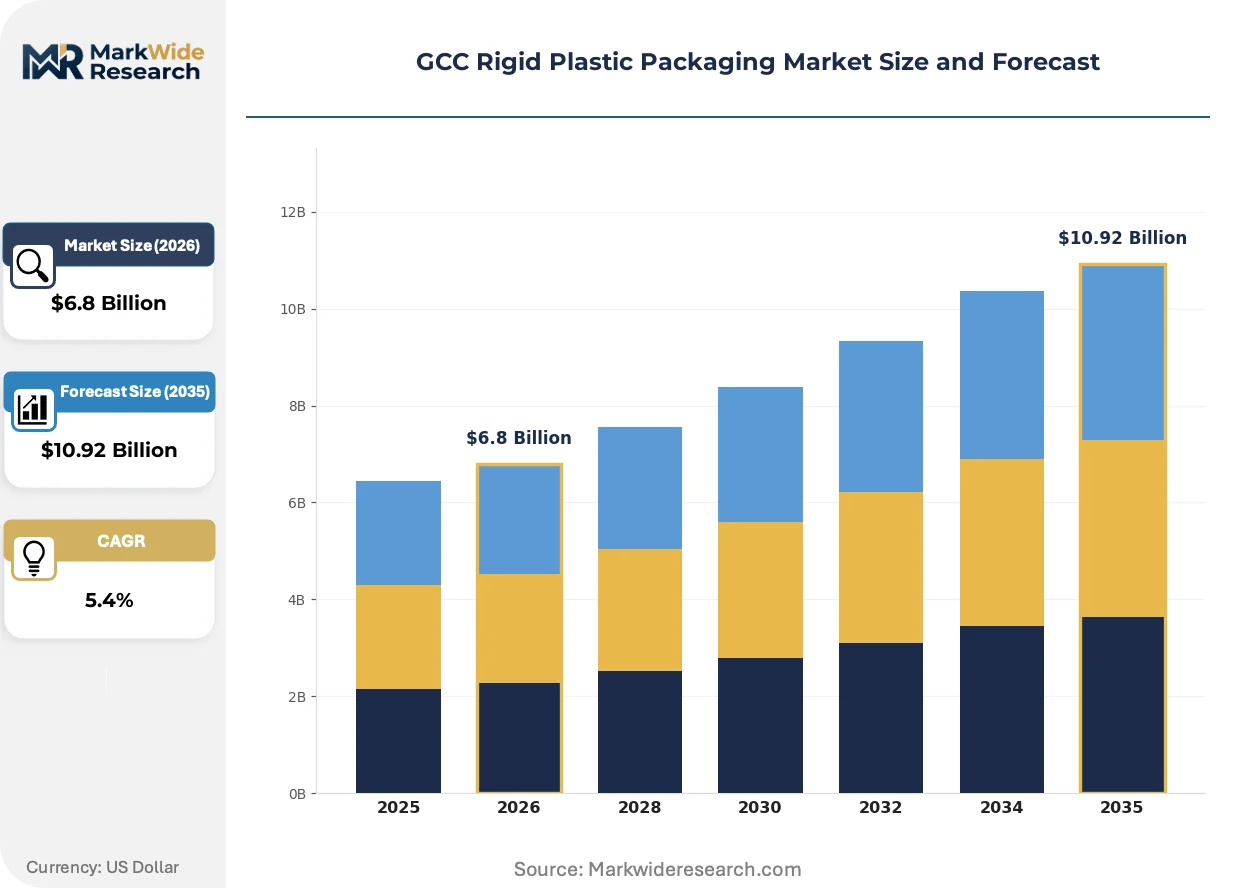
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Bottles, Jars, Containers, Trays Material Type: Polyethylene Terephthalate, High-Density Polyethylene, Polypropylene, Polystyrene, Acrylonitrile Butadiene Styrene Application: Pharmaceuticals, Food & Beverage, Cosmetics, Electronics, Chemicals End User: Manufacturers, Distributors, Retailers, Packaging OEMs, Exporters |
| Companies Covered | Al Rashid Boxes and Plastic Co., Al Bayader International, Zamil Plastic Industries Co., Al Watania Plastics, Precision Plastic Products LLC, Takween Advanced Industries, Saudi Arabian Packaging Industry WLL, Sabic Packaging Solutions, Packaging Products Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Rigid Plastic Packaging Market Shifts & Advancements
Digital manufacturing and regulatory traceability are compressing production cycles while elevating compliance technology investment across GCC converter operations.
Lightweighting simulation software is virtualizing structural design workflows for dairy and beverage containers. Tier-one converters deploy finite element analysis to optimize wall thickness before mold cutting, reducing prototype cycles from weeks to days. This capability is virtualizing competitive advantage toward engineering-intensive suppliers with captive simulation teams.
Gulf Standardization Organization food-contact plastics regulations are tightening migration testing protocols for recycled content incorporation. Converters must now document compliance across resin batches with chain-of-custody certification. Saudi Arabia's packaged food exporters face the steepest adaptation curve as European retail buyers demand GSO-plus-EU dual compliance.
Consolidated procurement by Saudi dairy cooperatives is compressing supplier rosters and extending contract durations. Long-term resin pass-through agreements now displace spot purchasing for volume tiers above ten million units annually. This concentration is most visible in the Eastern Province, where Almarai and Nadec coordinate packaging tendering through shared technical specifications.
GCC Rigid Plastic Packaging Market Segmentation
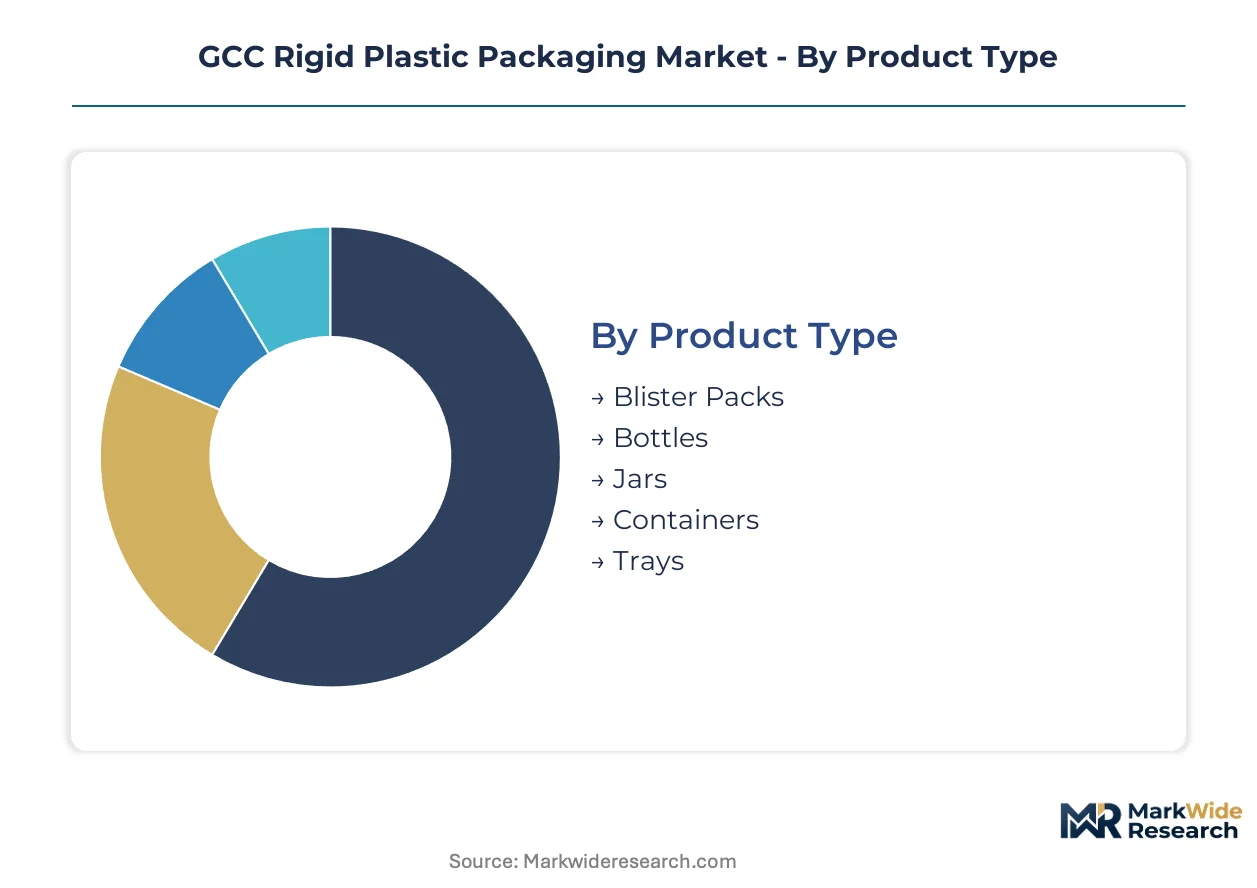
Rigid plastic packaging in the GCC fragments across four structural dimensions that determine procurement patterns and margin capture. Material chemistry and application requirements dominate converter technology choices, while end-user channel concentration shapes contract structures across Saudi Arabia and the UAE.
Product Type:
Mature formats anchor volume throughput while emerging configurations capture premium positioning in regulated applications.
- Bottles:Polyethylene Terephthalate dominates carbonated soft drink and bottled water applications across the Gulf states. Saudi Arabia's Eastern Province petrochemical corridor hosts the densest blow molding capacity, with hot-fill dairy expansion driving polypropylene substitution in certain formats.
- Containers:Injection-molded pails and drums serve industrial chemical distribution through Dubai's Jebel Ali logistics hub. Wall thickness exceeding 0.25 millimeters protects against mechanical damage during regional distribution to African and South Asian export markets.
- Blister Packs:Thermoformed pharmaceutical units face SFDA child-resistance mandate compliance requirements.
- Jars:Wide-mouth polypropylene formats capture ready-meal and UHT dairy segments requiring thermal resistance above 120 degrees Celsius.
- Trays:Thermoformed food service applications concentrate in UAE hospitality procurement channels.
Bottles handle the majority of throughput; containers are expanding most quickly on share through industrial chemical demand.
Material Type:
Cost tier positioning separates commodity resins from specialty polymers commanding formulation premiums.
- Polyethylene Terephthalate:Clear, lightweight barrier properties dominate beverage volume across carbonated soft drink and bottled water categories. Sabic's polyethylene feedstock integration creates cost advantages for Eastern Province converters serving Saudi retail channels.
- Polypropylene:Thermal resistance above 120 degrees Celsius enables hot-fill dairy and ready-meal applications where polyethylene terephthalate fails. Gulf Standardization Organization food-contact compliance accelerates domestic substitution for imported European containers.
- High-Density Polyethylene:Chemical resistance drives industrial pail and drum specifications.
- Polystyrene:Thermoformed trays and clamshells serve cost-sensitive food service segments.
- Acrylonitrile Butadiene Styrene:High-gloss cosmetic jar applications command premium positioning.
Polyethylene Terephthalate holds the largest installed base; Polypropylene is gaining share fastest through hot-fill dairy proliferation.
Application:
Regulatory intensity creates margin stratification across end-use categories.
- Food & Beverage:Bottles and containers dominate volume with Gulf Standardization Organization conformity mark requirements creating compliance barriers for non-certified imports. Saudi dairy cooperatives consolidate procurement through shared technical specifications extending contract durations.
- Pharmaceuticals:SFDA serialization and traceability mandates reshape primary packaging specifications, forcing child-resistant closure adoption and premium-grade polymer sourcing. High-barrier multilayer containers for biologics represent underpenetrated premium tier.
- Cosmetics:Acrylonitrile butadiene styrene and polyethylene terephthalate jars serve premium positioning requirements.
- Electronics:Antistatic formulations protect sensitive components during Gulf distribution.
- Chemicals:High-density polyethylene pails and drums serve industrial lubricant and solvent segments.
Food & Beverage commands the volume base; Pharmaceuticals captures the steepest margin expansion trajectory through regulatory premiumization.
End User:
Channel concentration determines contract structure and working capital requirements.
- Manufacturers:Brand-owning food and pharmaceutical companies specify resin grades and barrier properties directly. Long-term resin pass-through agreements displace spot purchasing for volume tiers above ten million units annually.
- Retailers:Saudi dairy cooperatives coordinate packaging tendering through consolidated procurement, compressing supplier rosters. Private label programs demand direct-to-object digital printing capabilities for promotional customization.
- Distributors:Jebel Ali free zone clustering enables just-in-time supply to African and South Asian export markets.
- Packaging OEMs:Equipment-integrated converters capture value through mold-design collaboration.
- Exporters:Dual Gulf Standardization Organization-plus-EU compliance requirements face steepest adaptation curve for Saudi packaged food exporters.
Manufacturers drive the largest contract values; Retailers are restructuring procurement fastest through cooperative consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Resin-to-package integration concentrates in Saudi Arabia's Eastern Province petrochemical corridor, fragmenting incumbent supply positions across the Gulf Cooperation Council states. Domestic manufacturing capacity accelerates under Saudi Vision 2030 localization mandates, compressing import dependency while elevating compliance requirements under Gulf Standardization Organization protocols.
Saudi Arabia
Hot-fill dairy proliferation and pharmaceutical serialization mandates drive packaging specification upgrades across the Kingdom. Saudi Food and Drug Authority traceability rules reshape primary packaging for child-resistant closures and premium-grade polymers. The Eastern Province petrochemical corridor hosts Sabic Packaging Solutions and Takween Advanced Industries in dense blow molding and injection molding clusters.
United Arab Emirates
Carbonated soft drink and bottled water demand sustains polyethylene terephthalate bottle throughput across Dubai and Abu Dhabi retail channels. Ministry of Industry and Advanced Technology enforces Gulf Standardization Organization conformity marks for food-contact plastics, creating compliance barriers for non-certified imports. Jebel Ali free zone logistics clustering enables just-in-time container supply to African and South Asian export markets.
Kuwait
Food service and hospitality procurement channels concentrate thermoformed tray demand in Kuwait City metropolitan distribution networks. National quality infrastructure aligns with Gulf Standardization Organization harmonized standards for polymer migration testing. Shuwaikh Industrial Area converters serve domestic dairy and ready-meal segments with polypropylene thermal resistance specifications.
Oman
Extended producer responsibility frameworks under development create first-mover positioning for integrated collection-recycling infrastructure investments. Ministry of Commerce, Industry and Investment Promotion evaluates circular economy regulations for single-use container cost structures. Sohar Port and Freezone petrochemical downstream zones attract rigid packaging converters seeking proximity to polyethylene feedstock.
Qatar
Event-driven hospitality procurement and premium retail positioning elevate acrylonitrile butadiene styrene cosmetic jar specifications in Doha metropolitan supply chains. Qatar General Organization for Standardization implements Gulf Standardization Organization food-contact compliance protocols for imported resin batches. Ras Laffan Industrial City polymer derivatives cluster supports localized container manufacturing for domestic dairy and beverage brands.
GCC Rigid Plastic Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and mold supply. The vendor base compresses around resin-integrated conglomerates and specialized pharmaceutical-grade converters, with mid-scale independents facing procurement consolidation from Saudi dairy cooperatives. Three archetypes dominate: backward-integrated petrochemical players controlling polyethylene feedstock, pharmaceutical blow molding specialists capturing SFDA compliance premiums, and diversified container fabricators spanning dairy bottles to industrial pails. Competitive moves concentrate on capacity expansion in Eastern Province resin-to-package complexes and strategic partnerships for Gulf Standardization Organization certification acquisition.
Within the backward-integrated tier, Sabic Packaging Solutions exemplifies feedstock-controlled cost positioning through Eastern Province polyethylene supply. Zamil Plastic Industries Co. and Takween Advanced Industries occupy differentiated specialization vectors, with the former representing diversified container spectrum coverage and the latter anchoring pharmaceutical-grade blow molding capabilities. Al Bayader International and Al Watania Plastics sit among mid-scale regional fabricators navigating cooperative procurement consolidation and extended producer responsibility adaptation across Bahrain and Oman regulatory white space.
| Leading Market Players |
|---|
| Al Rashid Boxes and Plastic Co. |
| Al Bayader International |
| Zamil Plastic Industries Co. |
| Al Watania Plastics |
| Precision Plastic Products LLC |
| Takween Advanced Industries |
| Saudi Arabian Packaging Industry WLL |
| Sabic Packaging Solutions |
| Packaging Products Company |
| Others |
Supply & Pricing Matrix
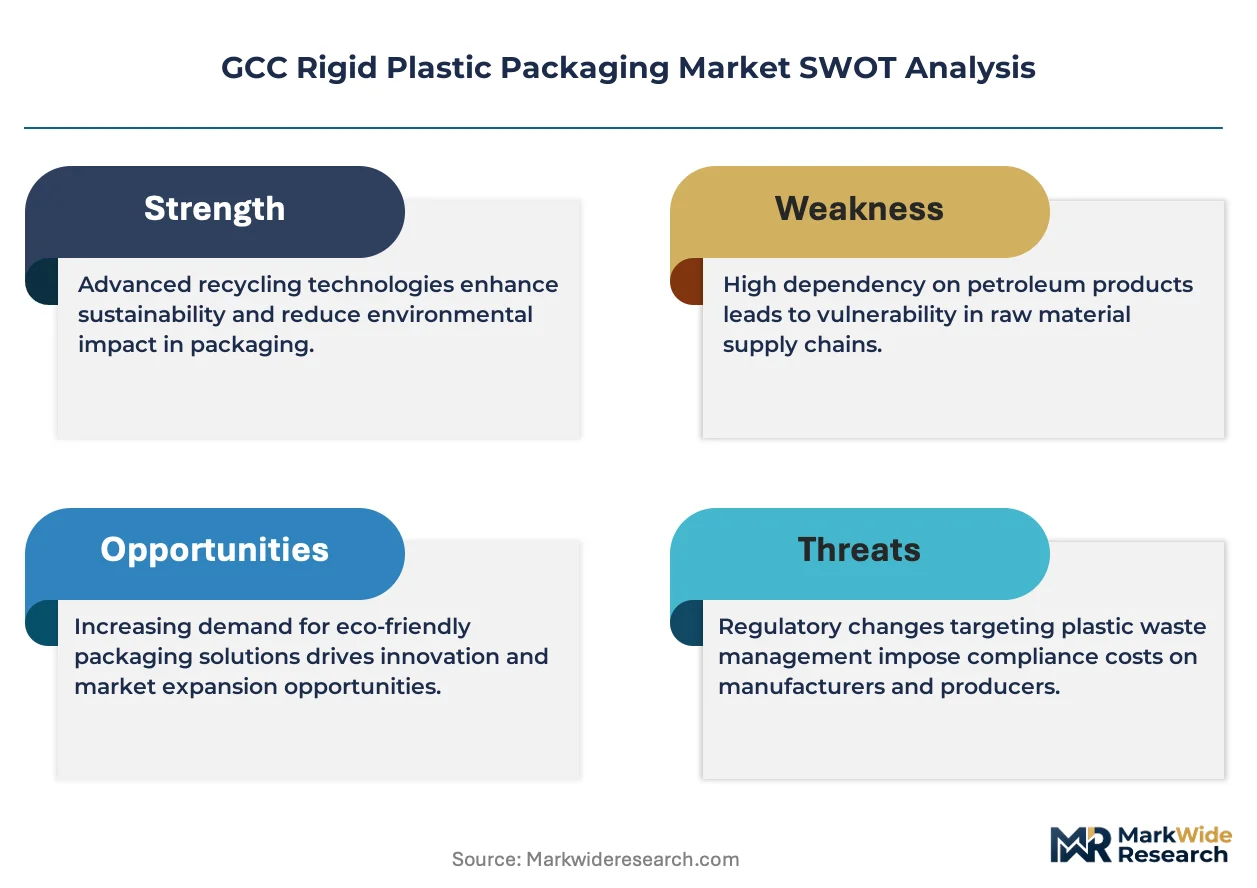
Eastern Province blow molding overcapacity compresses converter margins while fragmenting pricing power across Saudi Arabia's petrochemical corridor. Sabic Packaging Solutions leverages captive polyethylene feedstock to undercut non-integrated rivals, forcing mid-scale independents toward spot resin vulnerability or long-term pass-through contracts with dairy cooperatives.
Pricing Analysis
Gulf Standardization Organization conformity mark requirements dictate the pricing tier structure across food-contact applications, separating certified domestic converters from import-dependent competitors facing extended testing lead times. Three-tier pricing structure across premium, standard, and economy levels reflects resin grade differentiation, with pharmaceutical-grade multilayer containers commanding formulation premiums above commodity dairy bottles. Pricing pressure stems from consolidated procurement by Saudi dairy cooperatives extending contract durations and compressing supplier rosters. Small-scale converters serving hospitality channels exhibit highest price sensitivity, while pharmaceutical blow molding specialists capture lowest sensitivity due to SFDA compliance barriers limiting substitution.
Supply Chain Analysis
Extended payment terms from Saudi dairy cooperatives strain working capital for non-integrated converters, accelerating consolidation toward resin-backed balance sheets. Geographic supply concentrates in Saudi Arabia, the United Arab Emirates, and Kuwait, with Eastern Province petrochemical complexes feeding downstream blow molding clusters. Raw material dependencies center on polyethylene terephthalate resin, polypropylene homopolymer, and high-density polyethylene blow molding grades. Single-source vulnerability to Sabic turnaround schedules represents the dominant structural risk. Distribution runs through Dubai's Jebel Ali free zone for African and South Asian export markets, with domestic Saudi retail served directly from Eastern Province converter sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum can substitution in UAE carbonated beverages threatens PET bottle volume, forcing rigid plastic incumbents to defend position through barrier innovation and hot-fill format expansion.
For Market Incumbents: Harden resin-to-package integration across Eastern Province complexes to neutralize feedstock cost volatility from Sabic supply concentration. Pursue Gulf Standardization Organization certification acquisition as a compliance moat against European and Asian import competitors unfamiliar with regional testing protocols. Defend pharmaceutical blow molding share through multilayer EVOH barrier expertise, addressing the polymer science specialist scarcity that limits rival technical capability.
For New Entrants and Emerging Players: Pursue Oman and Bahrain extended producer responsibility white space before regulatory frameworks mature, capturing first-mover positioning in integrated collection-recycling infrastructure. Target pharmaceutical serialization compliance services as the most penetrable segment, with SFDA traceability mandates forcing incumbent retooling that creates service gaps. Enter through digital printing convergence partnerships with beverage brands seeking lot-size-one promotional customization.
For Investors and Strategic Acquirers: Capital is best deployed toward pharmaceutical-grade blow molding specialists with captive SFDA compliance capabilities, as regulatory premiumization sustains margin expansion over the medium-term horizon. Monitor aluminum can trial outcomes in UAE premium beverage positioning as the critical inflection signal for PET bottle demand trajectory. Avoid mid-scale diversified converters lacking resin integration or specialized regulatory tier access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyethylene Feedstock | Sabic Packaging Solutions controls raw material costs through Eastern Province petrochemical corridor proximity. |
| Pharmaceutical-Grade Blow Molding Specialization | Takween Advanced Industries captures SFDA compliance premiums through high-barrier multilayer container expertise. |
| Extended Producer Responsibility Infrastructure | First-mover investments in Oman and Bahrain circular economy frameworks alter single-use container cost structures. |
| Digital Printing Convergence | Direct-to-object inkjet capabilities enable promotional beverage customization for Saudi dairy cooperative private label programs. |
| Hot-Fill Dairy Format Expansion | Polypropylene thermal resistance above 120 degrees Celsius captures ready-meal and UHT dairy growth across Saudi Arabia and UAE. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, Saudi Food and Drug Authority regulatory filings, Gulf Standardization Organization technical standards, and petrochemical industry association reports. Primary interviews engaged blow molding plant managers, dairy cooperative procurement directors, pharmaceutical packaging engineers, and resin distribution channel partners across Saudi Arabia's Eastern Province and Dubai's Jebel Ali logistics hub. Bottom-up volume modeling from converter capacity utilization triangulates against top-down demand estimates from end-use consumption patterns.
Forecast inputs incorporate material chemistry substitution rates, regulatory compliance cost trajectories, and resin price pass-through elasticity across the projection horizon. Segmentation dimensions span product type, material chemistry, application regulatory intensity, and end-user channel concentration. CAGRs derive from structural demand drivers including hot-fill dairy proliferation, pharmaceutical serialization mandates, and industrial localization policy implementation. Specific forecast inputs include Sabic polyethylene supply turnaround schedules and Saudi dairy cooperative procurement consolidation velocity.
Sensitivities concentrate around SFDA regulatory amendment timing, extended producer responsibility framework adoption rates in Bahrain and Oman, and aluminum can substitution velocity in UAE beverage markets. Forecasts reflect documented assumptions regarding resin supply continuity and dairy cooperative procurement behavior. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Rigid Sleeve Boxes Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market