
 Global Powered Agriculture Equipment Market | 2026-2036
Global Powered Agriculture Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Powered Agriculture Equipment Market Intelligence
Consolidation among specialized drivetrain and hydraulic system suppliers is recalibrating the original equipment manufacturer (OEM) supply chain. John Deere leverages its extensive R&D in autonomous operation to maintain technology leadership. CNH Industrial competes through its multi-brand strategy, targeting distinct customer segments across geographies. Meanwhile, Kubota Corporation specializes in compact and mid-size tractors, dominating that specific niche.
Powered agriculture equipment encompasses self-propelled or towed machinery designed for farming tasks, from soil preparation to harvesting. These machines integrate mechanical, hydraulic, and electronic systems, often featuring engine power ratings from 20 to over 600 horsepower. While tractors and combine harvesters constitute the largest product type segments by value, sprayers are seeing rapid adoption. Within technology, GPS guidance has become standard, while autonomous operation represents the next frontier for large farms and agricultural cooperatives.
Engine emission standards set by the US EPA and equivalent European regulations dictate powertrain design and after-treatment technology. The EU Green Deal and ISO 11783, the standard for agricultural electronics, influence the development of sustainable and interoperable farming technologies. OEMs and farmers must navigate the decision between investing in capital-intensive autonomous systems versus upgrading existing fleets with precision farming retrofits.
Market Dynamics
The convergence of precision agriculture technologies with stringent engine emission mandates from regulators like the US EPA defines the market's trajectory. This pressure compels manufacturers to innovate on both operational efficiency and environmental compliance for new equipment designs.
Growth Catalysts
- Government Support:National policies in economies like India and Brazil are providing subsidies and credit facilities for farm mechanization, accelerating the replacement of manual labor with powered equipment for small and medium-sized farms.
- Precision Farming Integration:The widespread integration of IoT sensors and telematics across equipment fleets allows large-scale farms to optimize inputs like fertilizer and water, directly boosting crop yields and operational profitability.
- Farm Consolidation:The trend toward larger commercial farms and agricultural cooperatives, particularly in North America, creates demand for high-horsepower tractors and combines capable of covering extensive acreage efficiently.
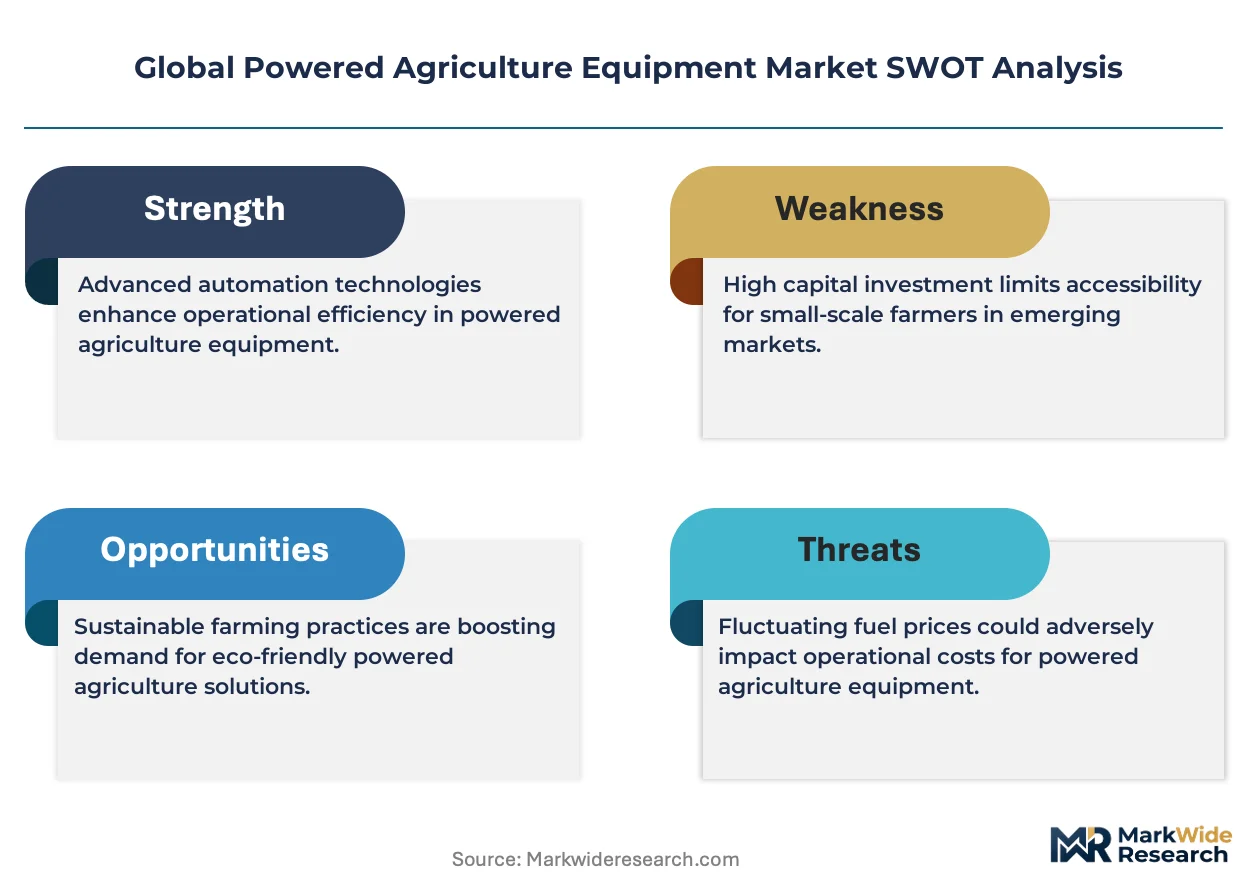
Market Restraints
- High Capital Outlay:The significant initial investment required for autonomous tractors and advanced harvesters acts as a barrier for small to mid-sized farms, limiting adoption to large agricultural corporations with substantial capital budgets.
- Regulatory Fragmentation:Divergent engine emission standards, such as the US EPA's Tier 4 Final and the EU's Stage V, create design and manufacturing complexities for OEMs, increasing R&D costs for global product lines.
- Supplier Consolidation:Increasing concentration among suppliers of critical components like hydraulic systems and specialized drivetrains gives these vendors greater pricing power, squeezing OEM margins and creating potential supply chain vulnerabilities.
Strategic Opportunities
- Equipment Electrification:The development of battery-electric compact tractors and utility vehicles presents an opportunity to serve niche applications like vineyards and organic farms, aligning with sustainability goals and lower operational noise requirements.
- Aftermarket Retrofits:Offering precision farming retrofit kits, including GPS guidance and variable rate control systems, for existing equipment fleets provides a revenue stream from farmers not ready to purchase new capital-intensive machinery.
- Data-as-a-Service Models:OEMs can create new service-based revenue by offering agronomic data analysis platforms that interpret telematics information, helping farmers make data-driven decisions on planting, spraying, and harvesting.
Industry Challenges
- Technician Skill Gap:A shortage of technicians trained to service and repair the complex electronic, hydraulic, and software systems in modern precision agriculture equipment creates maintenance bottlenecks for farmers and dealers.
- Data Interoperability:Ensuring seamless data exchange between multi-brand equipment fleets and various farm management software platforms, despite the ISO 11783 standard, remains a persistent operational hurdle for large, diversified farms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Powered Agriculture Equipment Market |
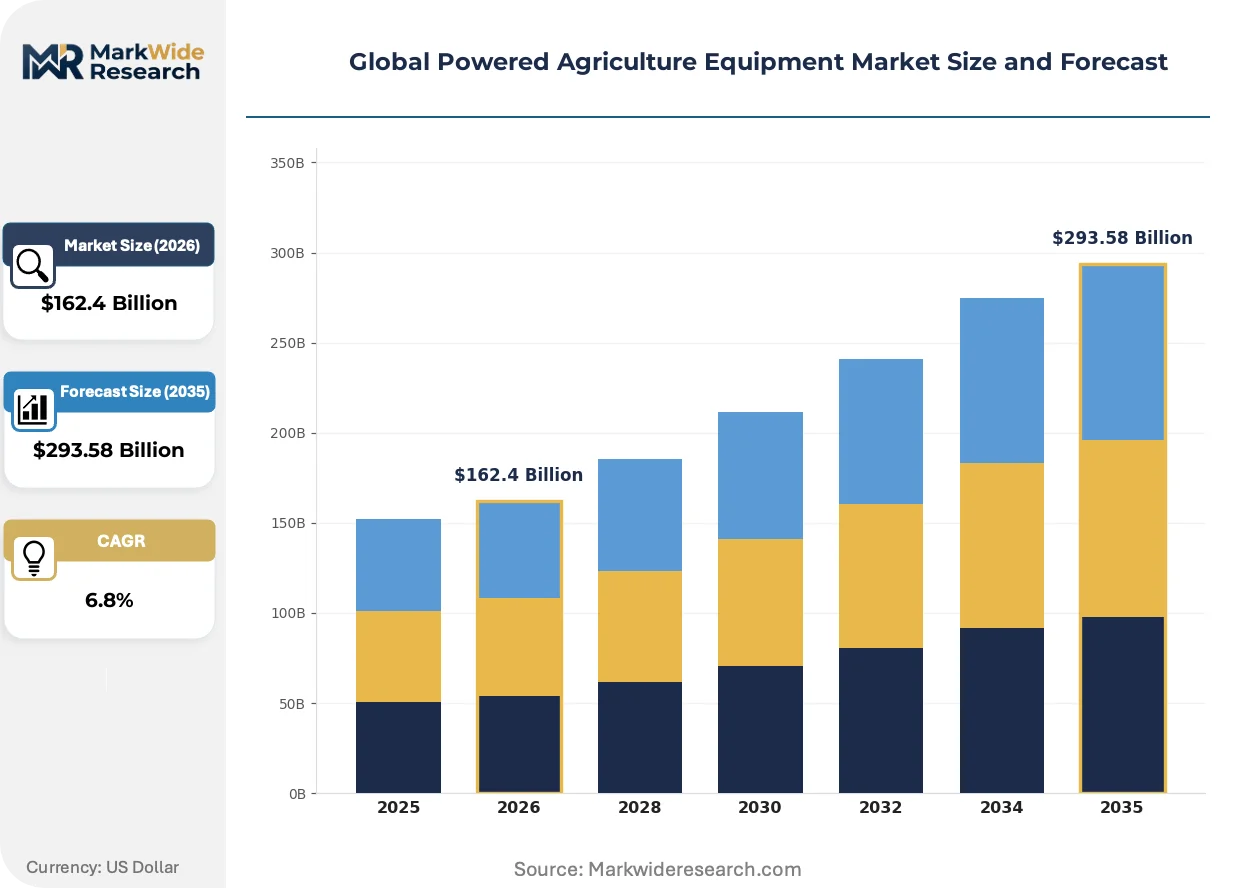
| Market Size in 2026 | $162.4 Billion |
| Market Size in 2035 | $293.58 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Combine Harvesters, Ploughs, Seed Drills, Sprayers, Tillers Technology: GPS Guidance, Autonomous Operation, Precision Farming, Telematics, IoT Sensors, Variable Rate Technology Application: Crop Cultivation, Livestock Management, Soil Preparation, Harvesting, Irrigation Management, Pest Control End User: Large Farms, Smallholder Farmers, Agricultural Cooperatives, Government Agencies, Contract Farmers |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra & Mahindra, Claas Group, SDF Group, Kinze Manufacturing, Caterpillar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Powered Agriculture Equipment Market Strategic Shifts & Innovations
A fundamental shift from pure mechanical horsepower to data-driven operational intelligence is redefining equipment value. This transition places a premium on software, connectivity, and autonomous capabilities over traditional metrics of engine size and raw power alone.
Autonomous operation technology integrates LiDAR, GPS, and machine learning to enable driverless tractors and harvesters. Large-scale agricultural cooperatives and corporate farms are the primary adopters, seeking to reduce labor costs and extend operational hours. This technology is automating critical, time-sensitive tasks like planting and harvesting, decoupling farm productivity from operator availability.
The EU Green Deal, with its Farm to Fork strategy, pressures OEMs to develop more sustainable farming technologies, including equipment that supports reduced pesticide and fertilizer use. This directly influences R&D priorities, favoring precision sprayers and nutrient management systems. Farmers in the European Union are consequently prioritizing equipment that can document and verify sustainable practices.
Farmers are increasingly exploring usage-based leasing and equipment-as-a-service models instead of outright capital purchases. This shift disrupts the traditional dealer-led sales channel, favoring flexible rental fleets managed by OEMs or large dealerships. This trend is most prominent in North America and Europe for high-value, seasonal equipment like combine harvesters.
Global Powered Agriculture Equipment Market Segmentation
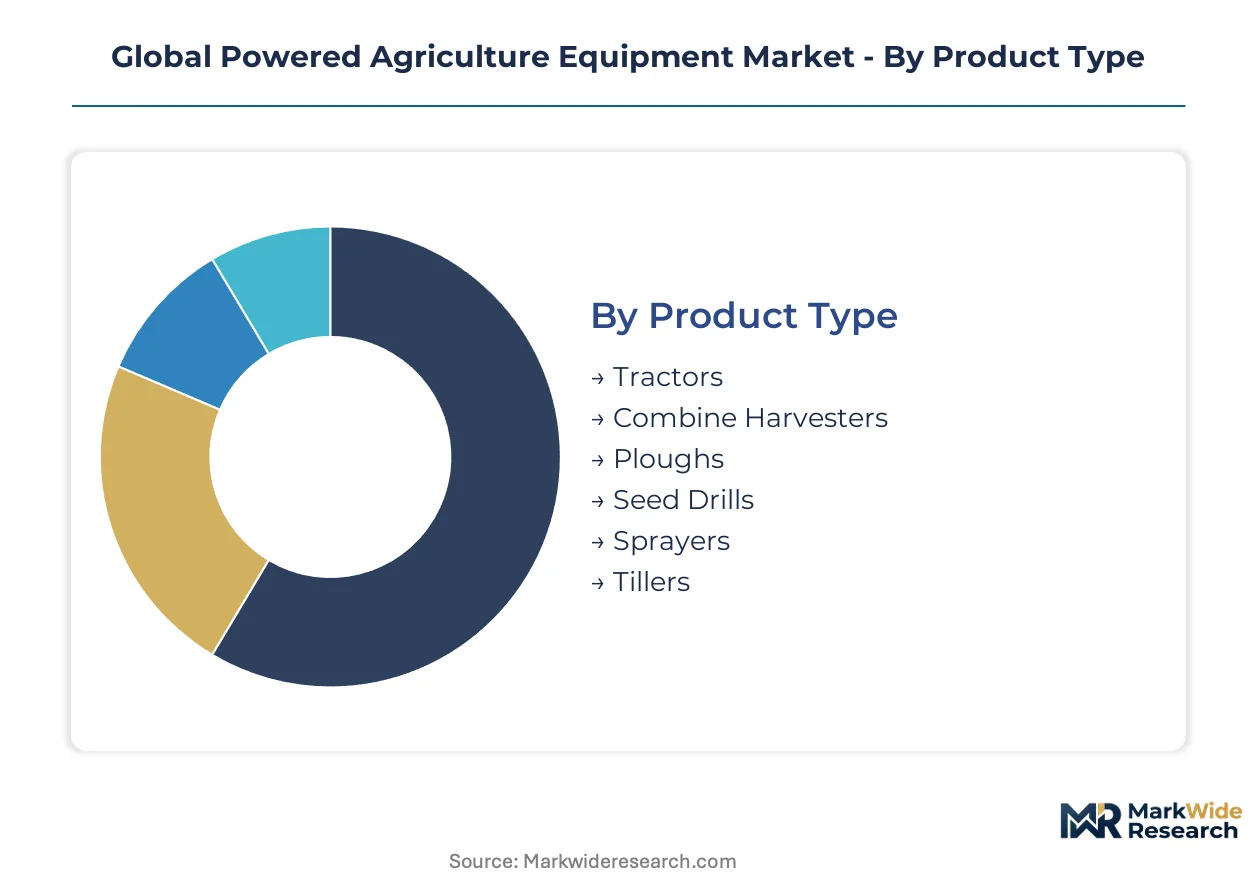
The segmentation analysis for the Global Powered Agriculture Equipment Market reveals distinct categories influencing purchasing decisions and technological adoption across diverse farming landscapes. Understanding these segments is crucial for manufacturers to tailor product offerings and for stakeholders to identify growth opportunities within specific niches.
Product Type:
The product type segmentation highlights how different equipment types integrate into farming operations, from standalone machinery to components within larger systems.
- Tractors:These self-propelled vehicles serve as the primary power source for diverse farm implements, featuring engine power ratings ranging from 20 to over 600 horsepower. Demand is particularly robust in North America and Brazil, driven by requirements for high-horsepower units on large-scale commercial farms.
- Combine Harvesters:These complex machines integrate reaping, threshing, and winnowing functions into a single unit for grain crops, optimizing labor and time efficiency during harvest season. European agricultural cooperatives increasingly invest in these systems to manage extensive acreage and reduce post-harvest losses.
- Ploughs:These implements prepare soil for planting by turning and aerating the earth, essential for initial land preparation in diverse terrains.
- Seed Drills:Precision seed drills distribute seeds uniformly across fields, crucial for optimal crop establishment and maximizing yield potential.
- Sprayers:Agricultural sprayers apply liquids like pesticides and fertilizers, experiencing rapid adoption driven by precision farming needs in India.
- Tillers:Tillers are used for secondary soil preparation, breaking up soil clods and leveling the seedbed, particularly in smaller farm operations.
Volume placements concentrate in Tractors; the faster expansion belongs to Sprayers.
Technology:
The technology segmentation outlines the advanced systems enhancing operational intelligence and efficiency across farming tasks.
- Autonomous Operation:This advanced technology integrates LiDAR, GPS, and machine learning to enable driverless machinery for critical tasks like planting and harvesting. Large agricultural cooperatives in the United States increasingly adopt these systems to mitigate labor shortages and extend operational hours.
- Precision Farming:This holistic approach uses data-driven insights to optimize resource application and maximize crop yields, leveraging various sensors and software platforms. Farmers in Germany prioritize these solutions to meet EU Green Deal sustainability objectives and improve input efficiency.
- GPS Guidance:Global Positioning System technology provides highly accurate navigation for agricultural machinery, now a standard feature enhancing field efficiency.
- Telematics:Telematics systems transmit real-time machine data, enabling remote monitoring and predictive maintenance for modern equipment fleets.
- IoT Sensors:Internet of Things sensors collect environmental and machine data, feeding into precision farming platforms for informed agricultural decisions.
- Variable Rate Technology:This technology allows for precise, localized application of inputs based on field data, significantly improving resource utilization and reducing waste.
Innovation in Autonomous Operation drives value, while GPS Guidance forms the foundational layer.
Application:
The application segmentation delineates the specific agricultural processes where powered equipment delivers critical functionality.
- Crop Cultivation:This broad application involves all activities from planting to crop maintenance, directly impacting yield and quality through optimized machinery use. Significant investment in equipment for this area is observed in India, supporting national food security goals.
- Harvesting:This critical application focuses on collecting mature crops efficiently, often involving specialized high-capacity machinery like combine harvesters. Agricultural operations in Canada rely on advanced harvesting equipment to manage vast grain fields within narrow weather windows.
- Livestock Management:Equipment here supports feeding, cleaning, and waste management for animal husbandry operations, enhancing farm productivity.
- Soil Preparation:This involves tilling, ploughing, and harrowing machinery to create optimal seedbed conditions for various crop types.
- Irrigation Management:Automated systems and pumps manage water delivery to crops, crucial for water-stressed regions like parts of Australia and Brazil.
- Pest Control:Sprayers and other specialized equipment apply treatments to protect crops from pests and diseases, minimizing crop loss.
Efficiency gains are most pronounced in Harvesting, with Pest Control offering significant cost reduction potential.
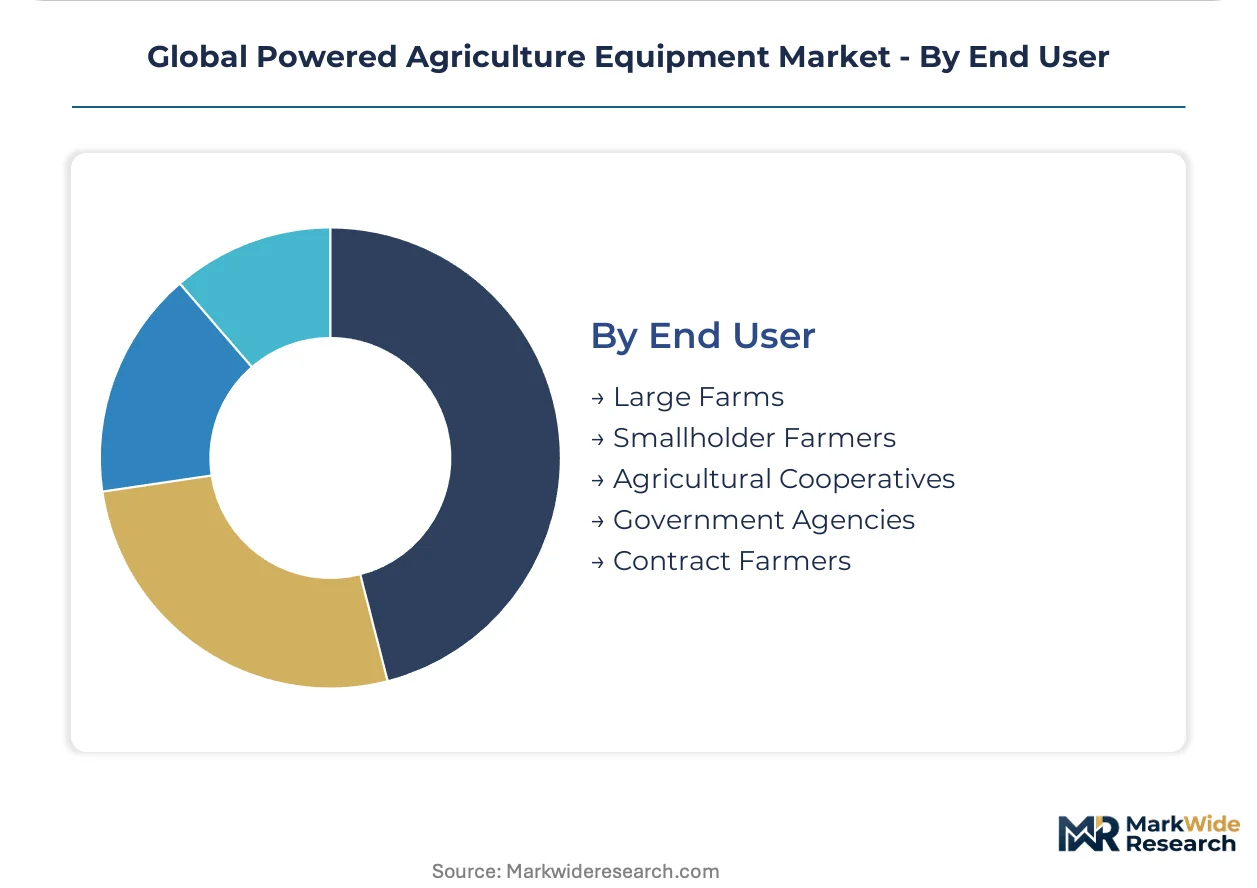
End User:
The end-user segmentation differentiates customer groups based on their operational scale and specific equipment acquisition patterns.
- Large Farms:These commercial operations typically cover extensive acreage and demand high-horsepower, technologically advanced, and often autonomous equipment. North American large-scale farms are primary adopters of capital-intensive autonomous systems to maximize output and reduce labor dependency.
- Agricultural Cooperatives:These groups of farmers pool resources to purchase and share expensive machinery, enabling access to advanced technology for members. European cooperatives frequently invest in shared combine harvesters and precision sprayers to optimize member farm operations.
- Smallholder Farmers:These farmers operate smaller plots and typically seek compact, affordable, and versatile equipment or precision farming retrofit solutions.
- Government Agencies:Public entities use agricultural equipment for research, demonstration farms, and disaster relief efforts in many countries.
- Contract Farmers:These individuals or firms provide specialized farming services using their own equipment to multiple clients, optimizing asset utilization.
Demand from Large Farms drives high-value sales, while Smallholder Farmers represents a substantial volume opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil, as a major agricultural producer, anchors significant demand for powered agriculture equipment across Latin America. The global market trajectory is shaped by diverse regional needs, ranging from large-scale commercial farming in North America to precision farming adoption in Europe and mechanization efforts in Asia. Government policies and environmental regulations significantly influence equipment design and purchasing decisions in these key geographies.
United States
Large commercial farms in the United States drive demand for high-horsepower tractors and autonomous harvesting systems. The US EPA's Tier 4 Final emission standards dictate engine design and after-treatment technologies for new equipment. The Midwest agricultural belt, particularly states like Iowa and Illinois, serves as a hub for advanced farm machinery deployment and innovation.
Brazil
National policies in Brazil, including subsidies and credit facilities for farm mechanization, accelerate equipment adoption by small and medium-sized farms. The country's vast agricultural lands, especially in the Mato Grosso region, require robust equipment for large-scale soybean and corn cultivation. Environmental regulations, while evolving, increasingly influence sustainable farming practices and equipment choices.
India
Government support for farm mechanization in India is accelerating the replacement of manual labor with powered equipment. The widespread adoption of sprayers is driven by precision farming needs to optimize input usage. States like Punjab and Haryana, known for intensive crop cultivation, show robust demand for compact tractors and seed drills.
Germany
Farmers in Germany prioritize equipment aligning with EU Green Deal sustainability objectives and improved input efficiency. The EU's Stage V emission standards significantly impact powertrain development for agricultural machinery. Bavaria, with its strong engineering base, is a key center for specialized and high-precision farming equipment manufacturing.
Canada
Vast grain fields across Canada, particularly in Saskatchewan and Alberta, create consistent demand for high-capacity combine harvesters and seeding equipment. Federal incentives support the adoption of advanced agricultural technologies to enhance productivity and reduce environmental impact. Agricultural cooperatives often pool resources to invest in shared, high-value machinery.
Global Powered Agriculture Equipment Market Key Industry Players
Established producers occupy the standard tier, while emerging entrants pursue specialized compact equipment and electrification technologies. The market structure exhibits a tiered consolidation, with a few global leaders dominating the high-horsepower segment. Strategic archetypes include full-line manufacturers, niche specialists, and technology integrators. Competitive moves often involve strategic partnerships for technology development and geographic expansion into emerging agricultural economies.
Within the full-line manufacturer archetype, John Deere (Inc.) and CNH Industrial (N.V.) represent entities with extensive product portfolios spanning various equipment types. Kubota Corporation (Ltd.) occupies a position as a specialist in compact and mid-size tractors, anchoring its presence in that specific niche. These companies leverage their global distribution networks to serve diverse customer segments.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra |
| Claas Group |
| SDF Group |
| Kinze Manufacturing |
| Caterpillar |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and large agricultural cooperatives influence equipment supply behavior and pricing discipline across the powered agriculture equipment market. Supply concentration among specialized component manufacturers dictates pricing power for original equipment manufacturers.
Pricing Analysis
Comprehensive warranty and service packages often bundle with high-value equipment, influencing overall acquisition costs for farmers. Pricing stratifies across premium, standard, and economy tiers, driven by after-sales service quality and customization level. Cost compression from consolidated component suppliers intensifies pricing pressure for OEMs in the mid-range segment. Smallholder farmers exhibit the highest price sensitivity, while large commercial farms prioritize advanced features and are less sensitive to initial capital outlay.
Supply Chain Analysis
Robust reverse-logistics channels for component refurbishment and remanufacturing are gaining importance for sustainability goals and cost control. Geographic supply concentration for specialized components like hydraulic systems and drivetrains centers in Germany, Japan, and the United States. Single-source vulnerability from supplier consolidation represents a structural risk for OEMs across the industry. Distribution relies on established dealer-led networks, which provide sales, service, and parts support to end-users globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The powered agriculture equipment market is becoming a vertical-integration race, with OEMs seeking to control software and data platforms downstream.
For Market Incumbents: Anchor R&D investments in autonomous operation and electrification technologies to maintain technology leadership. Form strategic partnerships with AI and software specialists to accelerate data platform development. Expand data-as-a-service offerings to generate new revenue streams and deepen customer relationships. This mitigates threats from emerging specialized compact equipment and strengthens market position against niche players.
For New Entrants and Emerging Players: Smallholder farmers in emerging economies represent a significant underserved buyer archetype for affordable solutions. Target niche applications like vineyards and organic farms with battery-electric compact tractors and utility vehicles. Offer precision farming retrofit kits for existing equipment fleets as a cost-effective entry point. Usage-based leasing models provide a compelling go-to-market angle for capital-constrained farmers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor technology integrators in the European market for specialized components, offering long-term viability. The market remains viable over the next decade, driven by mechanization trends and precision farming adoption. Target suppliers of advanced sensors, AI software, or specialized electric drivetrains for strategic acquisitions. Practitioners should monitor consolidation among agricultural software providers as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Autonomous R&D | John Deere advances technology leadership for large farms. |
| Expand Electrified Product Lines | Kubota Corporation targets niche vineyards and organic farms. |
| Develop Data-as-a-Service Platforms | OEMs generate new revenue from agronomic insights for agricultural cooperatives. |
| Offer Precision Farming Retrofits | Farmers in India upgrade existing equipment for input optimization. |
| Form Strategic Partnerships | CNH Industrial strengthens supply chains for hydraulic systems. |
Research Approach
Multi-period observation of equipment sales volumes, technology adoption rates, and regulatory changes anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with OEM product managers, large farm operators, dealership owners, and agricultural cooperative leaders. This primary intelligence was triangulated with secondary data from government agricultural censuses, company annual reports, patent filings for autonomous technology, and industry association publications, ensuring both bottom-up and top-down validation.
Segment-weighting models integrated volume and value projections across product types, technologies, applications, and end-user categories. The analytical framework considered regional economic growth and specific farm mechanization policies throughout the forecast period. Compound annual growth rates were derived from historical growth patterns and anticipated technological shifts. Key industry-specific forecast inputs included farm mechanization subsidies and precision farming integration rates across various geographies.
Revisions become necessary when significant shifts in government agricultural policies or global commodity prices materialize. Forecasts reflect assumptions regarding engine emission standard evolution and the stability of critical component supply chains. Practitioners should monitor regulatory updates and raw material cost fluctuations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
Global Lawn Mowers Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Tillage Equipment Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market