
 Europe Haying and Forage Machinery Market | 2026-2036
Europe Haying and Forage Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Haying and Forage Machinery Market Foresight
Equipment leasing and cooperative financing models are reshaping competitive access across Europe, enabling mid-sized dairy cooperatives to deploy high-capacity balers and self-propelled forage harvesters without capital-intensive purchases. CLAAS leverages its vertically integrated manufacturing footprint in Germany to sustain premium positioning in self-propelled harvester categories. Krone anchors its competitiveness through specialized expertise in large square balers and mower conditioners. John Deere extends its distribution control through dealer networks that dominate the mixed-farm segment across France and Benelux.
Europe haying and forage machinery encompasses mechanical systems designed to cut, condition, dry, rake, bale, and transport grass, legume, and cereal crops for animal feed preservation, with operating widths ranging from 2.5 meters to 15 meters and throughput capacities calibrated to daily dry-matter tonnage targets. These systems serve dairy and beef operations by minimizing field-to-bunker nutrient loss and enabling year-round feed security. Balers command the largest installed base among product types due to universal applicability across farm scales, while precision technology segments are gaining traction fastest as variable-rate application and GPS-guided swath alignment reduce overlap waste. Conventional technology still dominates replacement cycles in price-sensitive southern European markets where smaller landholdings limit automation returns.
CE marking requirements under the EU Machinery Directive establish mandatory safety and electromagnetic compatibility standards for all equipment sold within the region, while the F-Gas Regulation constrains refrigerant choices in conditioning systems. The EU Green Deal's carbon-border adjustment mechanisms and national farm sustainability audits in Germany and France are redirecting procurement toward equipment with documented fuel-efficiency performance. Stakeholders must monitor evolving national subsidy frameworks under the Common Agricultural Policy that increasingly tie direct payments to climate-friendly machinery investments.
Market Dynamics
The EU Green Deal's carbon-border adjustment mechanisms and farm sustainability audits are forcing dairy cooperatives to retire fuel-intensive legacy equipment ahead of normal replacement cycles. This regulatory compression is accelerating capital redeployment toward precision haying systems that document emissions reductions.
Growth Catalysts
- EU Green Deal agricultural targets:National sustainability audits in Germany and France tie direct payments to climate-friendly machinery investments, redirecting procurement toward fuel-efficient balers and conditioners.
- Dairy cooperative expansion:Large-scale farming structures across Denmark and northern Germany are deploying high-capacity self-propelled forage harvesters to meet rising milk production quotas.
- Precision technology penetration:GPS-guided swath alignment and variable-rate application systems are reducing overlap waste in mechanized forage operations, compressing per-hectare input costs.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings for high-grade alloys and precision hydraulics compress manufacturing margins and destabilize equipment pricing.
- CE marking compliance burden:The EU Machinery Directive's mandatory safety and electromagnetic compatibility standards extend certification timelines and raise fixed compliance costs for specialized manufacturers.
- Used equipment substitution:Refurbished balers and mowers from retiring northern European dairy operations are displacing new-unit demand in price-sensitive southern markets.
Strategic Opportunities
- Equipment-as-a-service models:Cooperative financing and leasing structures are enabling mid-sized French and Benelux dairy operations to access premium harvester technology without capital-intensive purchases.
- F-Gas Regulation retrofit demand:The phase-down of high-global-warming-potential refrigerants in conditioning systems is creating replacement cycles for compliant cooling equipment.
- Silage additive integration:Convergence of precision application machinery with biological inoculant systems is opening bundled service revenue streams for harvester OEMs.
Industry Challenges
- Precision agriculture technician scarcity:Dairy cooperatives lack personnel trained to calibrate GPS-guided equipment and interpret yield-mapping data, limiting realized efficiency gains from new machinery.
- Legacy fleet interoperability:Mixed-farm operations in France struggle to integrate telemetry-enabled harvesters with existing tractor fleets and bunker management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Haying and Forage Machinery Market |
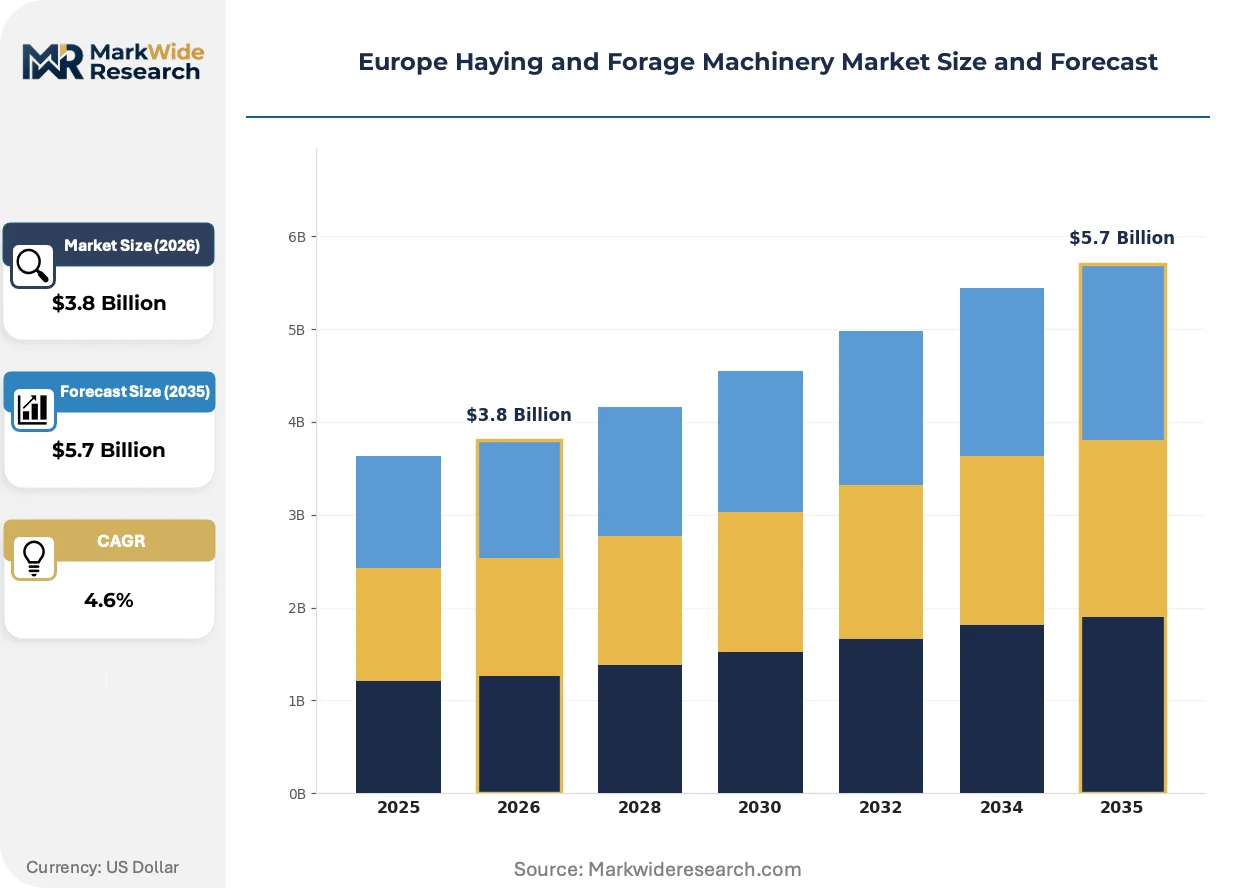
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balers, Mowers, Rakes, Tedders End User: Dairy Farms, Beef Farms, Mixed Farms, Crop Producers Technology: Conventional, High-Density, Autonomous, Precision Installation: Fixed, Portable, Semi-Portable, Tracked |
| Companies Covered | CLAAS, Krone, John Deere, AGCO Corporation, KUHN SAS, PÖTTINGER Landtechnik GmbH, Kverneland Group, SDF Group, Maschio Gaspardo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Haying and Forage Machinery Market Shifts & Advancements
Digital twin technology and connected fleet management are virtualizing equipment performance optimization across European dairy operations. These innovations compress downtime and enable predictive maintenance contracts that reshape traditional ownership economics.
Telematics-enabled baler control systems are virtualizing real-time density monitoring and automatic twine adjustment. Large-scale cooperatives in the Netherlands are deploying these systems fastest, with adoption concentrated among operations exceeding 500 hectares of forage land. The technology is virtualizing traditional field-to-bunker quality variance, compressing nutrient loss and enabling outcome-based service pricing from equipment providers.
The F-Gas Regulation's refrigerant phase-down mandates are forcing conditioner manufacturers to redesign thermal management systems around lower-global-warming-potential alternatives. This regulatory pressure compresses product development cycles and raises R&D allocation requirements. German and Danish harvester OEMs are responding fastest, leveraging in-house thermal engineering capabilities to secure first-mover certification advantages.
Cooperative procurement consortia are consolidating equipment purchasing power across multi-farm structures in northern Germany and Denmark. These buying groups displace traditional dealer-direct relationships, compressing margin structures for distribution networks. The shift is most visible in self-propelled forage harvester categories, where volume commitments enable customized financing terms and dedicated technical support contracts.
Europe Haying and Forage Machinery Market Segmentation
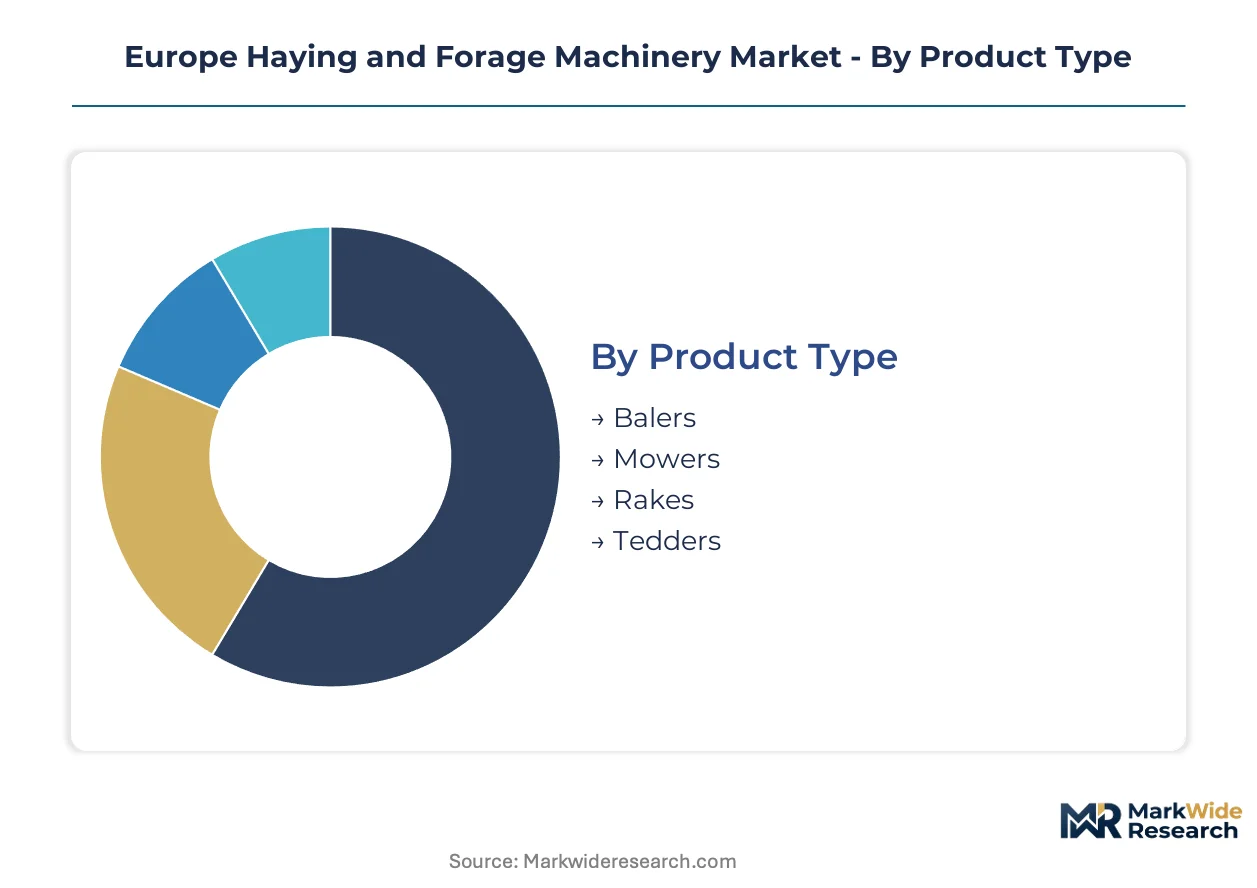
Segmentation in European haying and forage machinery reveals distinct equipment lifecycles and investment patterns across dairy cooperatives and mixed-farm operations. Understanding these divisions exposes where capital redeploys fastest under regulatory pressure from the EU Green Deal.
Product Type:
Replacement cycles vary dramatically across equipment categories, with balers turning over slowest due to mechanical simplicity while precision harvesters refresh fastest under emissions compliance deadlines.
- Balers:Mechanical compression systems binding cut forage into round or square bales using twine or net wrap, with throughput ranging from 40 to 120 bales hourly. Demand concentrates across Denmark and northern Germany where cooperative dairy structures require uniform bale density for bunker storage efficiency, though southern European price sensitivity delays precision upgrades.
- Mowers:Cutting systems with operating widths from 2.5 to 15 meters severing crop stems at optimal heights for drying. French mixed-farm operations drive replacement fastest here, as disc mower-conditioners integrate with existing tractor fleets and CE marking compliance forces retirement of pre-directive mounted units.
- Rakes:Rotary or wheel-type mechanisms gathering dried swaths into windrows for baler pickup.
- Tedders:Rotating tine systems spreading and turning cut forage to accelerate moisture evaporation before baling.
Balers anchor the volume base while precision-enabled mower-conditioners gain share at the steepest rate.
End User:
Customer scale determines technology tier access, with large cooperatives capturing precision equipment economies unavailable to fragmented holdings.
- Dairy Farms:Operations prioritizing silage and haylage quality for milk yield optimization, typically managing 200+ hectares of forage land. German and Dutch dairy cooperatives concentrate demand for self-propelled forage harvesters with GPS-guided swath alignment, driven by sustainability audit requirements tying direct payments to documented fuel-efficiency performance.
- Beef Farms:Grazing operations requiring lower-density hay for winter supplementation, often with smaller acreage and less mechanized infrastructure.
- Mixed Farms:Diversified operations across France and Benelux combining crop and livestock production, where equipment must flex between grain and forage duties.
- Crop Producers:Specialist growers supplying forage as a cash crop to livestock operations, particularly in intensive grassland regions of Ireland and the UK.
Dairy farms dominate capital deployment while mixed-farm operations expand most quickly as crop-livestock integration spreads.
Technology:
Technology tiers stratify by regulatory compliance horizon and labor availability, with premium segments capturing cooperative procurement consortia volume.
- Conventional:Mechanically controlled systems without telemetry or automated adjustment, dominating replacement cycles in price-sensitive southern European markets where smaller landholdings limit automation returns and technician scarcity constrains precision equipment operation.
- High-Density:Compression systems achieving 20-30% greater bale weight through reinforced chamber designs and extended plunger strokes.
- Autonomous:Self-navigating harvesters and swathers operating without continuous operator presence, currently field-testing in Dutch cooperative structures with 500+ hectare forage blocks.
- Precision:GPS-guided swath alignment, variable-rate application, and real-time yield mapping systems reducing overlap waste.
Conventional technology holds the installed base while precision systems climb the fastest as F-Gas Regulation and carbon-border mechanisms accelerate fleet renewal.
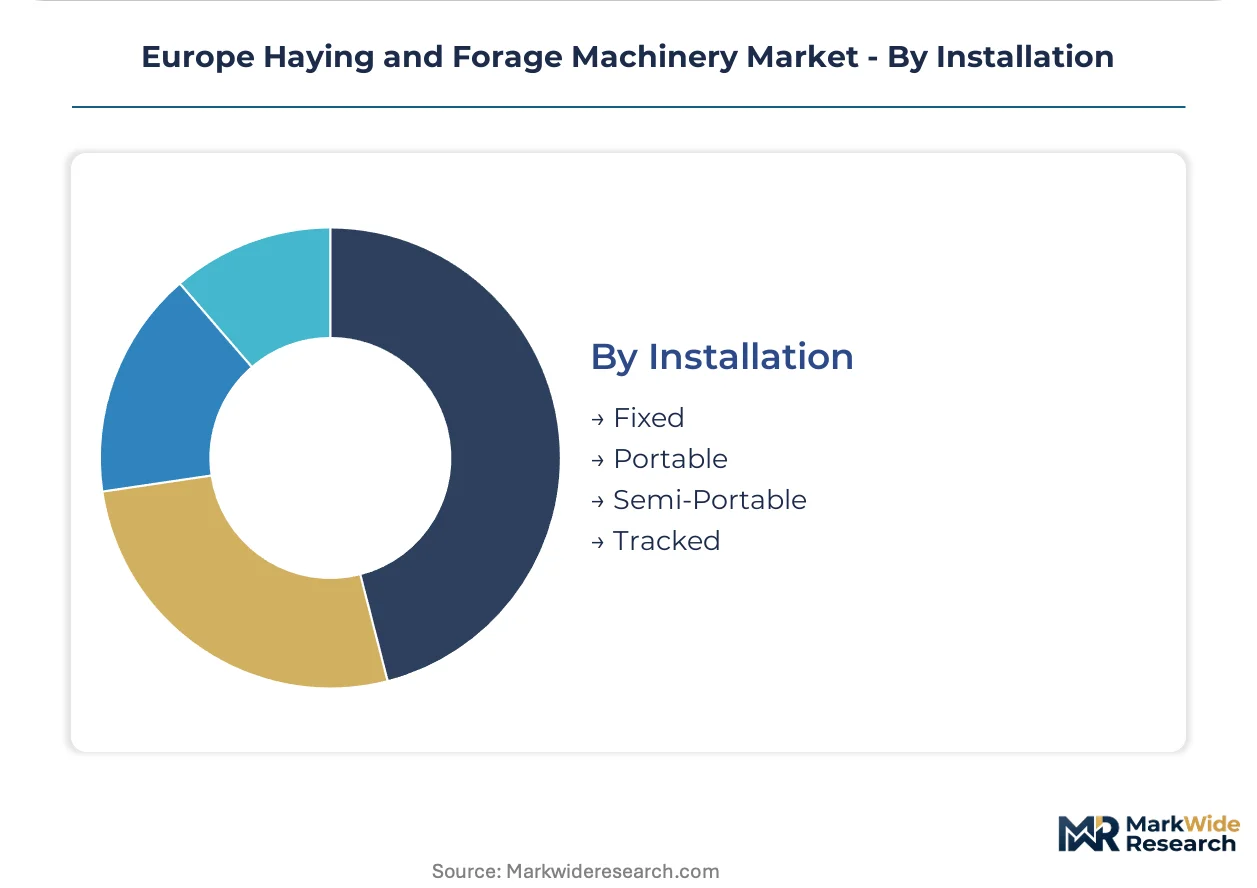
Installation:
Mobility configurations align with farm scale and terrain, determining how equipment transfers between owned and leased land parcels.
- Fixed:Stationary processing equipment including stationary balers and forage choppers requiring crop delivery to a central location.
- Portable:Trailed implements hitched to tractor three-point linkages or drawbars, dominating mid-scale French and Benelux mixed-farm operations where equipment serves multiple fields across dispersed landholdings.
- Semi-Portable:Modular systems with detachable headers or subassemblies enabling road transport between distant parcels.
- Tracked:Self-propelled harvesters with crawler undercarriages distributing weight across soft ground, essential for early-season cutting in high-moisture conditions across northern German peatland dairy regions.
Portable equipment captures the broadest deployment while tracked self-propelled units expand most quickly in waterlogged northern catchments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium harvester pricing in Denmark and northern Germany runs 15-20% above comparable equipment in southern France and Spain, reflecting cooperative purchasing power concentration versus fragmented mixed-farm price sensitivity. This asymmetry compresses margin structures for distribution networks serving price-tiered geographies.
Germany
Large-scale dairy cooperatives across Lower Saxony and Schleswig-Holstein deploy high-capacity self-propelled forage harvesters to meet rising milk production quotas. The EU Green Deal's carbon-border adjustment mechanisms and national farm sustainability audits tie direct payments to documented fuel-efficiency performance, redirecting procurement toward precision haying systems. CLAAS leverages its captive manufacturing footprint in Harsewinkel to sustain premium positioning in harvester categories serving these cooperative structures.
France
Mixed-farm operations across Île-de-France and Auvergne-Rhône-Alpes drive replacement demand for disc mower-conditioners integrating with existing tractor fleets. CE marking compliance under the EU Machinery Directive forces retirement of pre-directive mounted units, compressing replacement cycles. John Deere extends distribution control through dealer networks dominating this segment, while cooperative procurement consortia in Normandy consolidate purchasing power across multi-farm structures.
Netherlands
Intensive dairy operations exceeding 500 hectares of forage land in Gelderland and Friesland deploy telematics-enabled baler control systems fastest, virtualizing real-time density monitoring. The F-Gas Regulation's refrigerant phase-down mandates redesign of thermal management systems in conditioning equipment, raising R&D allocation requirements. Dutch cooperatives field-test autonomous self-navigating harvesters on consolidated land blocks, compressing labor dependency.
Denmark
Cooperative farming structures dominate forage harvesting across Jutland, deploying tracked self-propelled units essential for early-season cutting in high-moisture peatland conditions. National sustainability audits accelerate capital redeployment toward precision haying systems that document emissions reductions. Equipment leasing and cooperative financing models enable mid-sized operations to access premium harvester technology without capital-intensive purchases.
Italy
Price-sensitive southern European markets in Lombardy and Emilia-Romagna delay precision upgrades due to smaller landholdings limiting automation returns. Refurbished balers and mowers from retiring northern European dairy operations displace new-unit demand, compressing manufacturer volume in this tier. Conventional technology dominates replacement cycles where technician scarcity constrains precision equipment operation.
Europe Haying and Forage Machinery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in attachments and conditioning subassemblies. The vendor base stratifies across three tiers: full-line harvester OEMs with vertically integrated manufacturing, specialized baler and mower-conditioner houses with focused R&D allocation, and regional fabricators serving price-sensitive replacement demand. Consolidation pressure concentrates in the mid-tier as cooperative procurement consortia displace traditional dealer-direct relationships. Strategic moves center on equipment-as-a-service financing structures and predictive maintenance contract bundling.
Among Germany-based full-line manufacturers, CLAAS and Krone occupy positions at opposite ends of the specialization spectrum. CLAAS exemplifies the integrated platform archetype with captive production of self-propelled harvester systems. Krone represents the focused specialist model, anchoring competitiveness through concentrated expertise in large square baler categories. John Deere sits within the multinational agricultural equipment tier, leveraging distribution density across mixed-farm segments. These three patterns—integrated platform, focused specialist, and multinational scale—define competitive positioning vectors across European procurement channels.
| Leading Market Players |
|---|
| CLAAS |
| Krone |
| John Deere |
| AGCO Corporation |
| KUHN SAS |
| PÖTTINGER Landtechnik GmbH |
| Kverneland Group |
| SDF Group |
| Maschio Gaspardo |
| Others |
Supply & Pricing Matrix
Harsewinkel's captive manufacturing cluster for self-propelled harvesters concentrates capacity dynamics that translate directly into downstream pricing power for German OEMs serving cooperative procurement consortia across northern Europe.
Pricing Analysis
Configured-to-order pricing for GPS-enabled self-propelled forage harvesters commands a 15-20% premium over standard-specification units in the Danish and northern German dairy belt. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by CE marking certification grade and after-sales service bundling. Pricing pressure stems from cooperative procurement consortia consolidating volume commitments to extract customized financing terms. Beef farms and mixed-farm operations in southern France and Italy exhibit the highest price sensitivity, while large-scale Dutch and Danish dairy cooperatives show the least.
Supply Chain Analysis
Tariff exposure between Chinese steel suppliers and European fabricators dominates supply chain risk assessment for high-grade alloy components in precision hydraulic systems. Manufacturing concentration rests on Germany, Denmark, and the Netherlands for final assembly, while raw material dependencies center on Swedish specialty steel, Italian precision hydraulics, and Chinese rare-earth magnets for electric drive systems. Single-source vulnerability in conditioning system refrigerants under the F-Gas Regulation compresses component availability timelines. Distribution runs through dealer networks in France and Benelux, with cooperative procurement consortia displacing traditional channels in northern Germany and Denmark.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles are compressing as EU Green Deal carbon-border mechanisms force premature retirement of fuel-intensive legacy fleets, positioning this market for cyclical recovery driven by regulatory-mandated capital redeployment.
For Market Incumbents: Insulate premium positioning in self-propelled harvester categories by deepening backward integration into precision hydraulic component manufacturing and securing dedicated technical support contracts with cooperative procurement consortia. Threats from refurbished equipment substitution in southern European markets demand countermeasures through certified remanufacturing programs that capture secondary market value. For New Entrants and Emerging Players: Pursue white-space opportunities in telematics-enabled baler control systems for mid-scale French and Benelux mixed-farm operations, where incumbent coverage remains thin and precision agriculture technician scarcity creates service gaps. The most penetrable entry point sits in outcome-based service pricing models that bundle equipment access with predictive maintenance contracts, bypassing capital-intensive ownership barriers. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative procurement consortia are systematically displacing fragmented dealer networks, concentrating purchasing power among fewer buyer entities and favoring scaled platforms with captive manufacturing and dedicated technical service capabilities. Acquisition targets should display vertical integration depth in thermal management systems for F-Gas Regulation compliance. The signal to watch is accelerating cooperative financing model adoption rates across Normandy and northern Germany as an inflection indicator for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Launch | Cooperative financing structures in Denmark bypass capital barriers for mid-sized dairy operations. |
| Precision Technology Integration | GPS-guided swath alignment systems reduce overlap waste for Dutch operations exceeding 500 hectares. |
| F-Gas Regulation Compliance Pathway | Thermal management redesign secures first-mover certification for German and Danish OEMs. |
| Predictive Maintenance Contract Bundling | Telemetry-enabled harvesters enable outcome-based service pricing from equipment providers. |
| Cooperative Procurement Consortium Partnership | Volume commitments in northern Germany compress margin structures for traditional distribution networks. |
Research Methodology
Operator-level perspectives from dairy cooperative managers, precision agriculture technicians, dealer network principals, and aftermarket service heads anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from EU Machinery Directive compliance filings, national farm sustainability audit records, and cooperative procurement consortium disclosures. Customs data on steel and hydraulic component trade flows, CE marking certification databases, and Common Agricultural Policy subsidy framework documents provided quantitative anchors. Bottom-up equipment shipment tracking and top-down macroeconomic overlay triangulated market sizing across the analysis window.
Scenario-bracketing framed the projection methodology, with analytical outputs reflecting segmented modeling across product type, end user scale, technology tier, and installation configuration. CAGRs derived from equipment replacement cycle compression rates under EU Green Deal compliance deadlines and cooperative expansion trajectories in the northern European dairy belt. Industry-specific forecast inputs included F-Gas Regulation phase-down timelines and carbon-border adjustment mechanism implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in steel price volatility, agricultural commodity returns, or Common Agricultural Policy subsidy restructuring would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and cooperative financing model penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market