
 Australia Seed Treatment Market | 2026-2036
Australia Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Seed Treatment Market Outlook
Biological active ingredient development is reconfiguring margin pools away from conventional chemistry toward microbial and botanical formulations. BASF Australia Limited leverages its global R&D pipeline to anchor biological seed treatment portfolios locally. Bayer CropScience Pty Limited sustains dominance in fungicide seed treatment through channel control with major grain handlers. Nufarm Limited competes on manufacturing scale, producing formulations cost-competitively for the domestic broadacre market.
Seed treatment encompasses the application of protective chemical or biological agents directly onto seeds prior to planting, typically involving film coatings at application rates of milliliters per kilogram of seed to establish localized defense zones around the germinating embryo. The primary purpose centers on reducing early-season pest and pathogen damage during the vulnerable establishment phase when plant defenses remain undeveloped. Fungicide treatments occupy the largest share of product value, driven by relentless pressure from bunts, smuts, and seedling blights across Australia's Mediterranean and temperate cropping zones. Biopesticide formulations represent the fastest-expanding category, propelled by APVMA streamlining of low-toxicity biological registrations and grower demand for residue-compliant export grain. Liquid formulations lead volume due to ease of on-farm application through precision treaters, though powder variants retain share in smaller-scale horticultural and pulse segments.
APVMA registration requirements govern all seed treatment chemistry entering the Australian market, with re-evaluation protocols periodically restricting legacy actives and redirecting formulation investment toward compliant alternatives. TGA residue standards for grain destined for food and feed channels shape maximum residue limits that treatment chemistries must not exceed at harvest. The EU Green Deal's carbon border adjustment mechanism and associated sustainability standards are pressuring Australian grain exporters to document lower-carbon input profiles, indirectly favoring biological seed treatments with favorable lifecycle assessments. Stakeholders must monitor APVMA review timelines for neonicotinoid seed treatments and position biological alternatives ahead of potential regulatory discontinuities.
Market Dynamics
APVMA's neonicotinoid re-registration review is compressing the window for conventional chemistry while accelerating biological formulation pipelines. Western Australian broadacre operators now face immediate input substitution decisions as regulatory discontinuity looms.
Growth Catalysts
- EU Green Deal carbon border adjustments:Australian grain exporters must document lower-carbon input profiles, creating pull-through demand for biological seed treatments with favorable lifecycle assessments.
- Fungicide resistance management protocols:Seedling blight pressure across New South Wales cropping zones drives rotation toward novel mode-of-action treatments.
- Precision treater technology diffusion:On-film coating equipment enables variable-rate application, improving treatment economics for medium-scale broadacre operators.
Market Restraints
- Active ingredient supply concentration:Three overseas manufacturers control 80% of fungicide technical supply, exposing Australian formulators to freight and currency volatility.
- APVMA registration timeline friction:Biological product approvals average 18-24 months, delaying market entry for microbial candidates.
- Grain handler treatment infrastructure lock-in:Major bulk handlers operate captive coating facilities optimized for liquid chemistry, creating switching costs for biological alternatives.
Strategic Opportunities
- Queensland pulse expansion:Chickpea and mungbean acreage growth creates demand for rhizobia-compatible seed treatments absent from current cereal-focused portfolios.
- Integrated pest management mandates:Graincorp and CBH sustainability procurement criteria favor suppliers offering biocide-free establishment protocols.
- Drone-based spot re-treatment convergence:UAV application platforms enable post-planting biological top-ups, extending the addressable treatment window beyond sowing.
Industry Challenges
- Microbial formulation stability expertise gap:Few Australian agronomists possess training in biological product storage, handling, and tank-mix compatibility.
- Multi-jurisdiction residue compliance:Export grain must simultaneously satisfy TGA domestic standards, EU MRLs, and buyer-specific contract limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Seed Treatment Market |
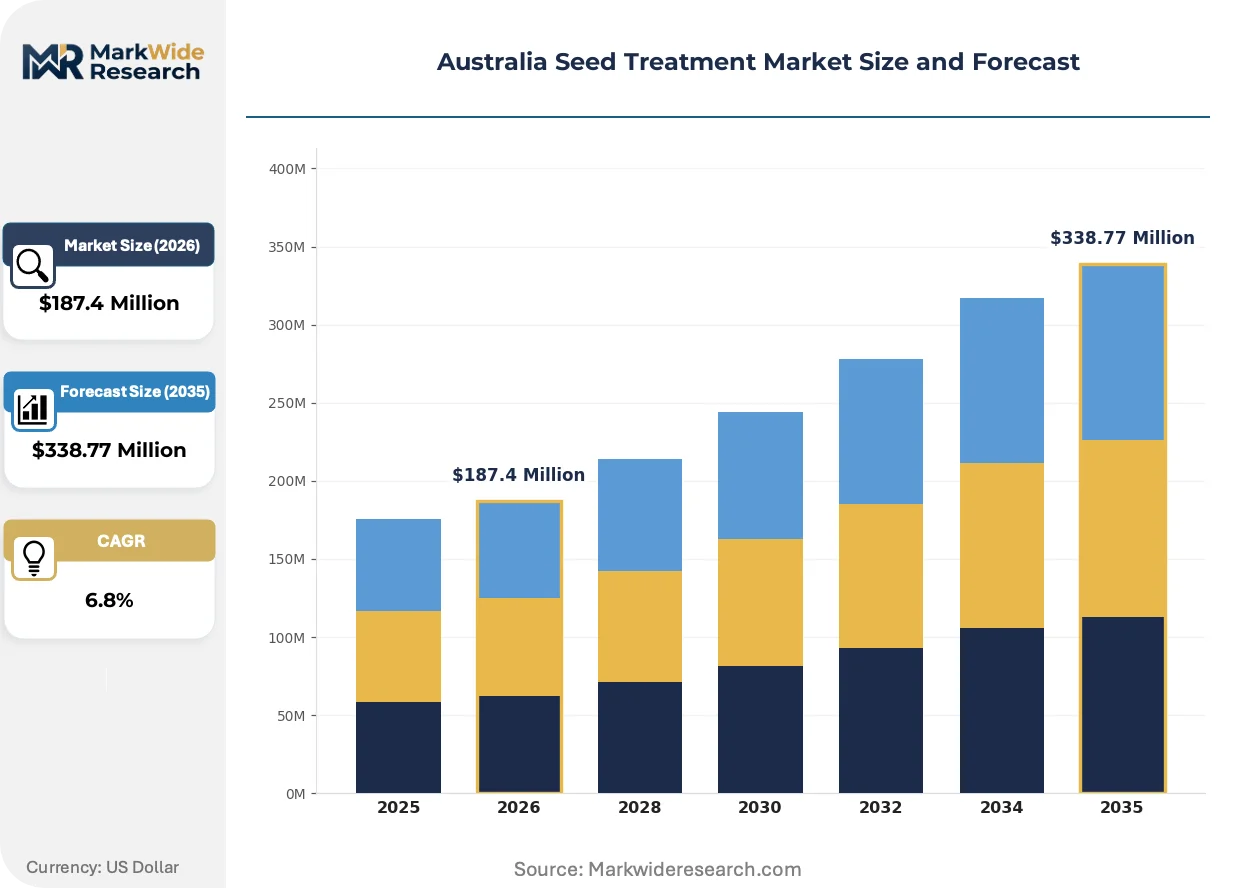
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Fungicides, Herbicides, Biopesticides Application: Cereals, Oilseeds, Pulses, Vegetables End Use Industry: Agriculture, Horticulture, Commercial Gardening, Forestry Formulation Type: Liquid, Powder, Granule, Other |
| Companies Covered | BASF Australia Limited, Bayer CropScience Pty Limited, Syngenta Australia Pty Ltd, Nufarm Limited, Corteva Agriscience, FMC Corporation, ADAMA Australia Limited, Sumitomo Chemical Australia, INCOTEC Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Seed Treatment Market Strategic Shifts
Seed treatment chemistry is pivoting from prophylactic broad-spectrum coverage toward targeted establishment-phase protection. Formulation science, regulatory compliance architecture, and procurement contracting are all undergoing concurrent recalibration.
Biological active ingredient platforms are migrating from horticultural niche applications toward broadacre cereal adoption. Trichoderma and Bacillus-based formulations now target root rot complexes in wheat and barley. BASF and local biological specialists are field-testing microbial consistency across variable Western Australian soil temperatures. The technology is migrating from greenhouse-protected environments to open-field broadacre systems, compressing the price premium versus synthetic chemistry.
APVMA's streamlined low-toxicity biological registration pathway is reshaping product development timelines. The 2023 administrative reforms reduced data requirements for microbial seed treatments with established overseas safety profiles. Australian formulators now parallel-track domestic submissions with EU BPR and US EPA registrations. Pulse crop segments are responding fastest, where residue constraints for human consumption markets already favor biological alternatives.
Grain handler procurement contracts are unbundling seed treatment from grain marketing services. CBH and Graincorp historically bundled coating fees into receival charges, obscuring true input costs. Large broadacre operators now negotiate direct supply agreements with formulators, bypassing handler markups. This pattern is most visible in Western Australia's wheatbelt, where 5,000+ hectare farms possess scale to justify on-farm precision treater investment.
Australia Seed Treatment Market Segmentation
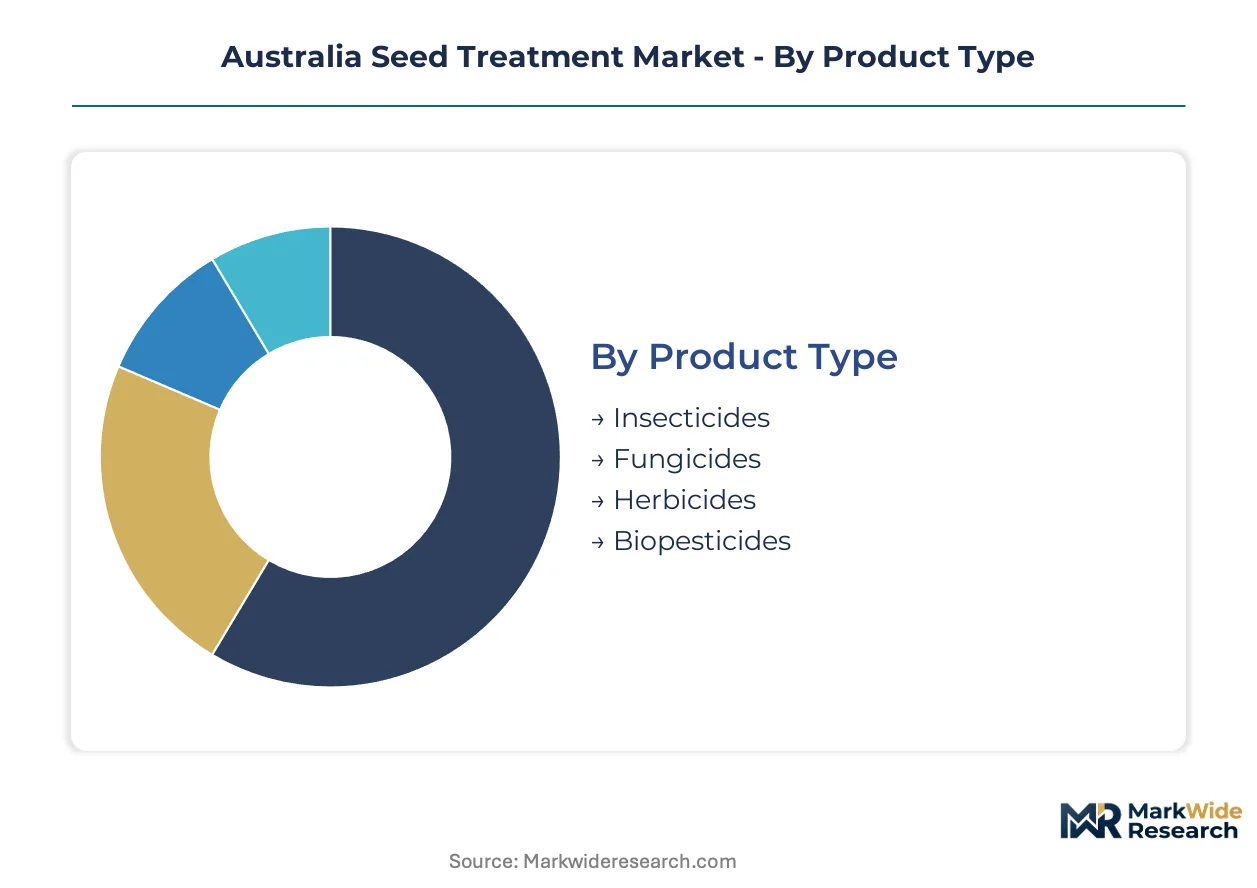
Segmentation reveals how treatment chemistry, crop targets, and application formats intersect with distinct farmer economics across Australian broadacre and intensive cropping systems. Each dimension carries regulatory and operational implications that reshape procurement patterns.
Product Type:
Cost tier stratification separates legacy chemistry from emerging biological platforms, with farmer willingness-to-pay varying sharply by crop value and export market access.
- Fungicides:Azole and strobilurin-based film coatings dominate wheat and barley protection against bunts, smuts, and seedling blights. Western Australian grain handlers specify these formulations in receival contracts due to established residue compliance pathways for Asian export markets.
- Biopesticides:Trichoderma and Bacillus microbial formulations target root rot complexes with APVMA-streamlined registration timelines. Queensland pulse growers adopt these fastest where EU and Middle Eastern buyers mandate residue-free establishment protocols.
- Insecticides:Neonicotinoid seed treatments face re-registration uncertainty; APVMA review timelines compress effective commercial windows for clothianidin and imidacloprid products.
- Herbicides:Pre-emergent herbicide seed coatings address early weed competition in no-till systems, particularly for glyphosate-resistant ryegrass management in South Australia.
Fungicides command the established base. The steepest expansion runs through biopesticides.
Application:
Volume concentration tracks the geographic distribution of Australia's cropping belt, with Mediterranean climate zones driving distinct treatment intensity patterns.
- Cereals:Wheat and barley seed treatment absorbs the majority of formulation volume, with Western Australia's wheatbelt and New South Wales Riverina representing the densest demand clusters. Yield protection economics justify premium fungicide expenditure where farm-gate prices exceed $300 per tonne.
- Pulses:Chickpea, lentil, and mungbean acreage expansion in Queensland and northern New South Wales creates demand for rhizobia-compatible treatments. Residue constraints for human consumption markets accelerate biological adoption faster than in cereals.
- Oilseeds:Canola seed treatment focuses on blackleg suppression and establishment-phase insect protection, with Victorian Wimmera and South Australian Eyre Peninsula as core demand zones.
- Vegetables:High-value brassica and allium crops in Queensland's Lockyer Valley and Victoria's Gippsland drive precision application of biological nematicides and biofungicides.
Cereals anchor volume throughput. Pulses deliver the fastest value expansion as acreage climbs.
End Use Industry:
Customer type differentiation separates broadacre commodity operations from intensive horticultural and amenity sectors with divergent input cost structures.
- Agriculture:Broadacre grain and oilseed production represents the dominant consumption base, with farm-scale precision treaters enabling direct procurement from formulators rather than through grain handler intermediaries.
- Horticulture:Protected cropping and intensive vegetable systems in Queensland and Western Australia demand specialized biological formulations with documented non-target organism safety profiles.
- Commercial Gardening:Turf and amenity seed markets in metropolitan peripheries favor convenience-oriented powder formulations over liquid systems requiring application infrastructure.
- Forestry:Plantation timber nurseries in Tasmania and Victoria's Central Highlands utilize specific fungicide treatments for eucalyptus and radiata pine establishment, though volume remains marginal.
Agriculture holds the volume concentration. Horticulture generates the highest margin per treated hectare.
Formulation Type:
Application technology maturity determines format preference, with on-farm equipment diffusion favoring liquid systems while legacy infrastructure sustains solid alternatives.
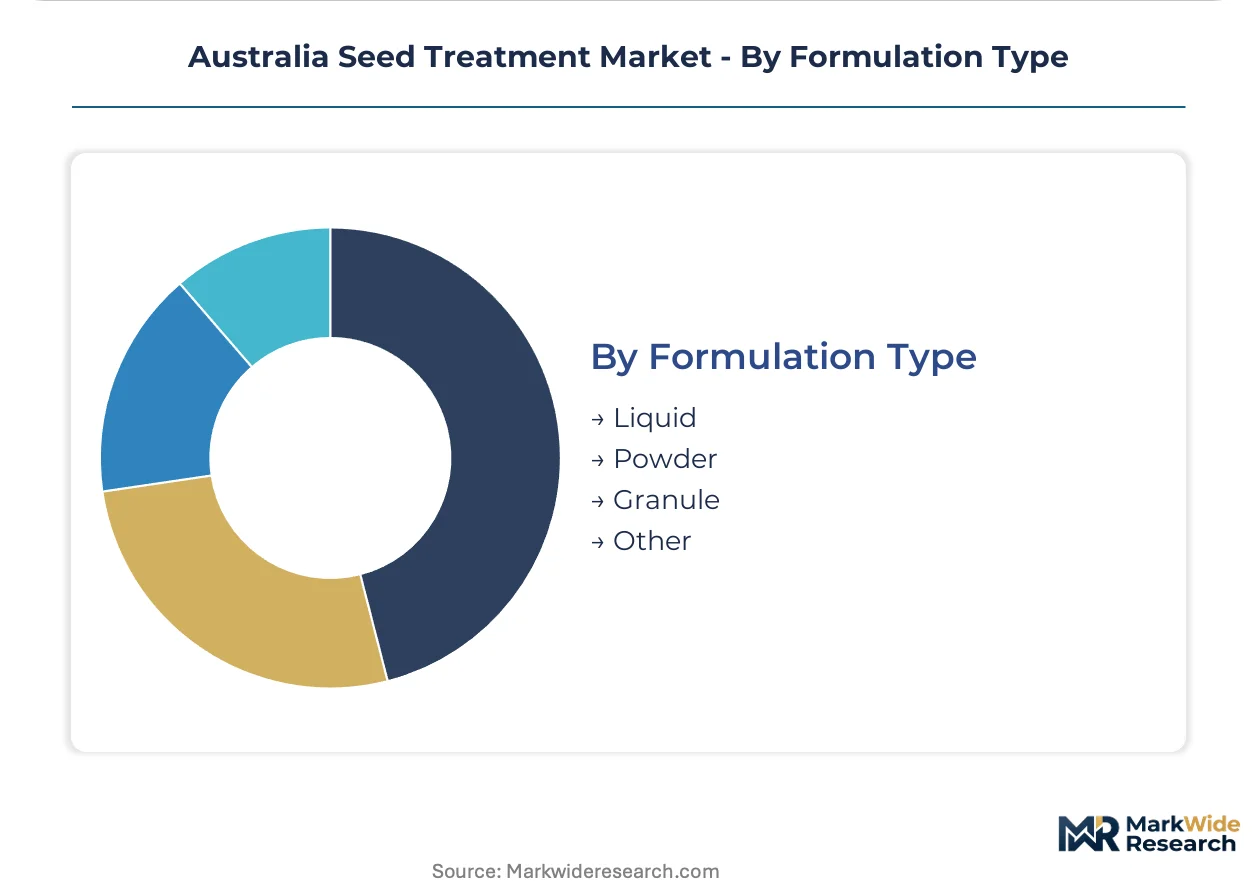
- Liquid:Film-coating suspensions and emulsifiable concentrates integrate with precision treater technology at grain receival sites and on-farm installations. Major bulk handlers operate captive liquid coating facilities optimized for high-throughput cereal treatment.
- Powder:Dust and wettable powder formulations retain relevance in smaller-scale pulse and vegetable segments where batch sizes and equipment capital constraints favor simpler application methods.
- Granule:Controlled-release granule systems target specific soil-borne pathogen suppression in high-value horticultural crops, with limited adoption in broadacre contexts due to cost and application incompatibility.
- Other:Emerging microencapsulation and seed pelleting technologies address specific crop establishment challenges, including saline soil tolerance and nutrient co-delivery.
Liquid formulations dominate throughput volume. Granule systems are climbing fastest from a small horticultural base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australian broadacre operators exhibit the highest price elasticity, treating seed as a discretionary input when grain prices dip below break-even thresholds. Victorian and South Australian farmers show lower elasticity, accepting premium formulations as fixed costs due to established export quality premiums. Queensland pulse growers occupy the middle ground, responding to residue compliance mandates rather than pure price signals.
Western Australia
Mediterreanean climate cropping zones drive fungicide seed treatment intensity across the wheatbelt region. APVMA registration timelines for neonicotinoid alternatives compress decision windows for the 2025-2026 planting season. Geraldton and Albany port corridors concentrate grain handler infrastructure, with CBH receival sites operating captive liquid coating facilities optimized for high-throughput cereal flows.
New South Wales
Riverina and central west cropping districts absorb substantial formulation volume for wheat and barley establishment protection. TGA residue standards for export grain shape maximum residue limits that treatment chemistries must satisfy at harvest. Wagga Wagga and Griffith serve as distribution nodes where precision treater technology diffuses to medium-scale broadacre operators seeking direct formulator relationships.
Victoria
Wimmera and Mallee districts generate concentrated demand for canola seed treatment targeting blackleg suppression. EU Green Deal carbon border adjustment mechanisms pressure grain exporters to document lower-carbon input profiles, indirectly favoring biological alternatives. Horsham functions as the regional agronomy hub where farmer education on microbial formulation handling occurs through extension networks.
Queensland
Chickpea and mungbean acreage expansion in the Darling Downs and central highlands creates demand for rhizobia-compatible seed treatments absent from cereal-focused portfolios. APVMA streamlined low-toxicity biological registration pathways accelerate product availability for residue-constrained human consumption markets. Toowoomba anchors the northern distribution infrastructure for biological formulation supply chains.
South Australia
Eyre Peninsula and Yorke Peninsula cropping zones prioritize pre-emergent herbicide seed coatings for glyphosate-resistant ryegrass management in no-till systems. Graincorp sustainability procurement criteria favor suppliers offering biocide-free establishment protocols. Port Lincoln and Wallaroo receival points concentrate handler treatment infrastructure with legacy liquid chemistry optimization.
Australia Seed Treatment Market Competitive Environment
Global agrichemical majors and domestic manufacturing specialists split the market between proprietary formulation development and cost-competitive supply. Three overseas technical manufacturers concentrate upstream fungicide active ingredient supply, exposing Australian formulators to freight and currency volatility. The competitive terrain separates R&D-intensive biological platform builders from scale-driven generic manufacturers. Consolidation pressure manifests through grain handler procurement contract unbundling and direct farm-scale supply agreements.
Among global agrichemical platforms with Australian subsidiaries, BASF Australia Limited and Bayer CropScience Pty Limited anchor the premium formulation tier through biological pipeline access and fungicide seed treatment channel control respectively. Nufarm Limited occupies the domestic manufacturing scale position, producing formulations cost-competitively for the broadacre market. These three entities represent the structural poles around which competitive positioning organizes: proprietary technology leverage, distribution infrastructure capture, and manufacturing cost discipline.
| Leading Market Players |
|---|
| BASF Australia Limited |
| Bayer CropScience Pty Limited |
| Syngenta Australia Pty Ltd |
| Nufarm Limited |
| Corteva Agriscience |
| FMC Corporation |
| ADAMA Australia Limited |
| Sumitomo Chemical Australia |
| INCOTEC Australia |
| Others |
Value Chain & Pricing Dynamics
The Fremantle to Kwinana grain corridor freight economics compress margins for imported active ingredients while amplifying price spreads between liquid fungicide formulations and emerging biological alternatives. Three overseas technical manufacturers control upstream fungicide supply, granting them pricing power over Australian formulators who must absorb currency volatility and shipping cost surges. Downstream, grain handler bundling of coating fees into receival charges historically obscured true input costs, though direct farm-scale procurement now unbundles these relationships and exposes price differentiation.
Pricing Analysis
After-sales technical support and agronomic advisory services drive lifetime value more than initial formulation sales. Three-tier pricing structure across premium, standard, and economy levels separates proprietary biological platforms from generic azole formulations and commodity powder treatments. Price differentiation rests on APVMA registration status and residue compliance certification for EU export markets. Cost compression in the economy tier is intensifying because Nufarm's domestic manufacturing scale anchors low-cost supply. Large broadacre operators in Western Australia exhibit highest price sensitivity, while Victorian canola growers accept premium formulations as fixed costs due to established quality premiums.
Supply Chain Analysis
Contract manufacturing concentration for microbial formulations sits with BASF's Ludwigshafen biological production network and specialty fermentation houses in the Netherlands and Denmark. Geographic supply concentration centers on Germany, China, and India for fungicide technicals, with microbial active ingredient production anchored in Western Europe. Raw material dependencies include azole intermediates, strobilurin precursors, and Trichoderma fermentation substrates. Single-source vulnerability runs through the three overseas fungicide technical suppliers who control eighty percent of feedstock. Distribution runs through grain handler receival sites and direct farm-scale precision treater installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological seed treatment platforms expand addressable service revenue through recurring agronomic advisory and residue compliance documentation, outpacing hardware-only formulation sales. The shift from bundled handler pricing to direct farm procurement creates attach opportunities for monitoring, soil testing, and seasonal re-treatment protocols.
For Market Incumbents: Build switching-cost moats through captive precision treater financing and exclusive biological formulation supply agreements. Defend against Nufarm's manufacturing scale by deepening backward integration into microbial fermentation capacity in Queensland. Anchor channel control with Graincorp and CBH through multi-year sustainability procurement contracts that lock out emerging biological specialists.
For New Entrants and Emerging Players: Build out rhizobia-compatible biological portfolios targeting Queensland pulse expansion where residue constraints favor biocide-free protocols. Penetrate the chickpea and mungbean segments in Darling Downs and central highlands through demonstration partnerships with export-focused aggregators. Lead with APVMA streamlined registration pathway expertise to compress time-to-revenue versus conventional chemistry entrants.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biological platform builders with established overseas safety profiles and parallel EU BPR registration progress. Five-to-ten year viability hinges on neonicotinoid regulatory discontinuity accelerating substitution demand. Target acquisition archetypes include microbial formulation specialists with Queensland distribution infrastructure and Trichoderma strain libraries. The signal to watch is APVMA publication of neonicotinoid re-registration timelines, which would trigger immediate input substitution decisions across Western Australia.
| Strategic Initiative | Industry Significance |
|---|---|
| Biological Portfolio Expansion | Captures margin migration from conventional chemistry toward microbial formulations with favorable EU lifecycle assessments. |
| Precision Treater Channel Control | Locks in farm-scale customers through equipment financing tied to exclusive formulation supply agreements. |
| APVMA Registration Parallel-Tracking | Accelerates market entry by submitting microbial candidates simultaneously under streamlined domestic and EU BPR pathways. |
| Queensland Pulse Segment Focus | Addresses fastest-expanding acreage in chickpea and mungbean with rhizobia-compatible biological treatments. |
| Grain Handler Contract Unbundling | Exposes true input costs to large broadacre operators and enables direct formulator relationships bypassing receival markups. |
Study Parameters
A standing panel of agronomy extension officers, grain handler procurement managers, biological formulation R&D directors, and broadacre farm operations managers provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from APVMA registration databases, CBH and Graincorp receival statistics, TGA residue standard publications, and EU Green Deal carbon border mechanism documentation. Bottom-up treatment volume estimates triangulated against top-down agrichemical import customs data.
Scenario-bracketing framed conservative, baseline, and accelerated biological adoption pathways across the projection horizon. Segmentation dimensions modeled include product type chemistry tier, crop application intensity, end-use industry scale, and formulation technology maturity. CAGRs derived from historical treatment volume trajectories adjusted for regulatory discontinuity risk and precision treater diffusion rates. Industry-specific forecast inputs incorporated APVMA review timeline probabilities and EU carbon border adjustment implementation phasing.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese generic fungicide manufacturers or accelerated EU MRL tightening would shift outcomes. Forecasts assume moderate currency volatility and no catastrophic supply chain disruptions to active ingredient feedstocks. Quarterly review of APVMA registration publication schedules, grain handler sustainability procurement criteria updates, and EU carbon border mechanism granular rules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
Italy Seed Treatment Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
Oilseed Processing Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
North America Seed Treatment Market
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
Brazil Seed Treatment Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
Fenugreek Seed Extract Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
Argentina Seed Treatment Market