
 Germany Haying and Forage Machinery Market | 2026-2036
Germany Haying and Forage Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Haying and Forage Machinery Market Foresight
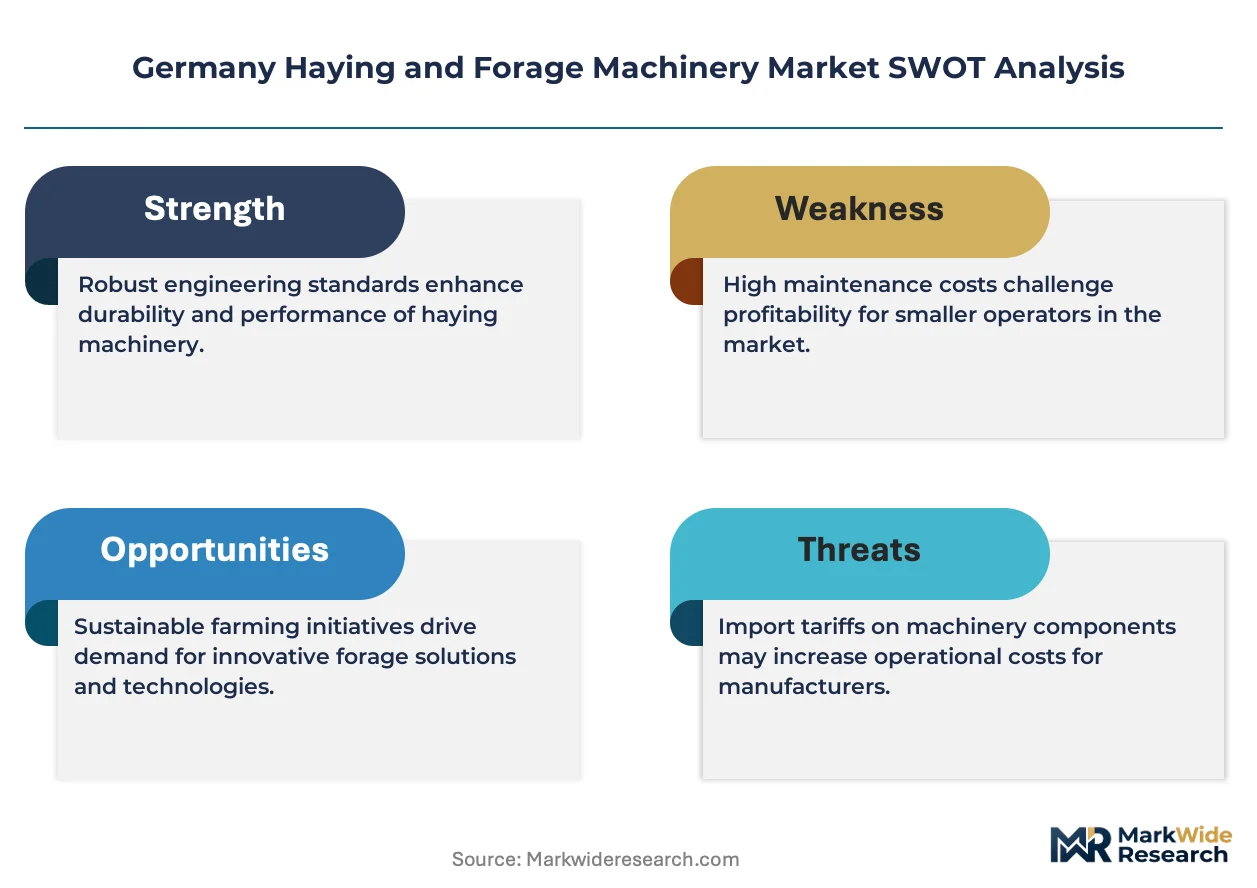
The German haying and forage machinery sector is recalibrating around a widening split between premium precision equipment and commodity-grade implements serving price-sensitive operators. CLAAS anchors the premium tier through its integrated crop flow systems and proprietary CEMOS automation technology. Krone differentiates via its specialized rotor and chopping innovations for high-wet silage. John Deere leverages its precision agriculture ecosystem to control the GPS-guided and sensor-integrated technology layer.
German haying and forage machinery encompasses field equipment designed to cut, condition, dry, rake, bale, chop, and transport grass, legume, and cereal biomass for animal feed and bedding, with working widths ranging from two to twelve meters and power requirements spanning 40 to 800 horsepower depending on implement class. Forage harvesters and balers dominate capital expenditure flows, reflecting their centrality in dairy farm cost structures and the limited substitution options for mechanized silage and hay production. Mower conditioners and tedders occupy mature replacement cycles, while GPS guidance and sensor integration represent the fastest-growing technology layer as operators seek to document field operations for subsidy compliance and variable-rate input management.
The German Agricultural Machinery Manufacturers Association (VDMA) coordinates industry standards with the EU Machinery Directive and CE marking requirements, while the German Federal Motor Transport Authority (KBA) enforces emission compliance under Stage V regulations that constrain engine architecture choices. The EU Green Deal's Farm to Fork strategy pressures machinery specifications toward lower soil compaction and reduced fuel intensity per ton of harvested forage. Stakeholders must monitor how the EU AI Act's risk classification framework applies to autonomous swathing and bale-tracking algorithms, as compliance costs could reshape software development priorities across the sector.
Market Dynamics
EU Stage V emission regulations are compressing engine architecture choices for German manufacturers while simultaneously accelerating electrification R&D investment across the sector.
Growth Catalysts
- Dairy expansion in Lower Saxony:Intensive livestock corridors are mechanizing silage operations to meet milk quota requirements, driving capital expenditure on self-propelled forage harvesters.
- EU Green Deal's Farm to Fork strategy:This framework mandates reduced soil compaction and fuel intensity per ton harvested, creating specification pull for precision equipment with GPS guidance and sensor integration.
- Contracting services consolidation:Professional forage contractors in northern Germany are replacing aging fleets with high-capacity implements that minimize field passes and labor hours per hectare.
Market Restraints
- Stage V engine cost inflation:Exhaust after-treatment systems and selective catalytic reduction hardware have added substantial cost to diesel powertrains above 130 kilowatts.
- Steel and hydraulic component volatility:Input cost swings for high-strength alloys and precision hydraulics compress margin predictability for mid-tier implement manufacturers.
- Used equipment import pressure:Depreciated machinery from Dutch and Danish markets saturates southern German regions, constraining new equipment absorption rates.
Strategic Opportunities
- Autonomous swathing algorithms:The EU AI Act's risk classification framework creates first-mover advantage for developers of bale-tracking and path-planning software that meets compliance thresholds.
- Bavarian biogas feedstock demand:Anaerobic digestion plants require consistent biomass supply, creating dedicated machinery demand for precision-chopped whole-crop cereals.
- Subscription telemetry models:Remote diagnostics and fleet management platforms offer recurring revenue streams beyond equipment sales to large contracting operations.
Industry Challenges
- Electronics-hydraulics integration:CAN bus protocols and ISOBUS compatibility demand specialized skill sets scarce among traditional agricultural machinery technicians.
- CE marking documentation burden:The EU Machinery Directive's conformity assessment timelines delay product launches by six to twelve months for complex self-propelled equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Haying and Forage Machinery Market |
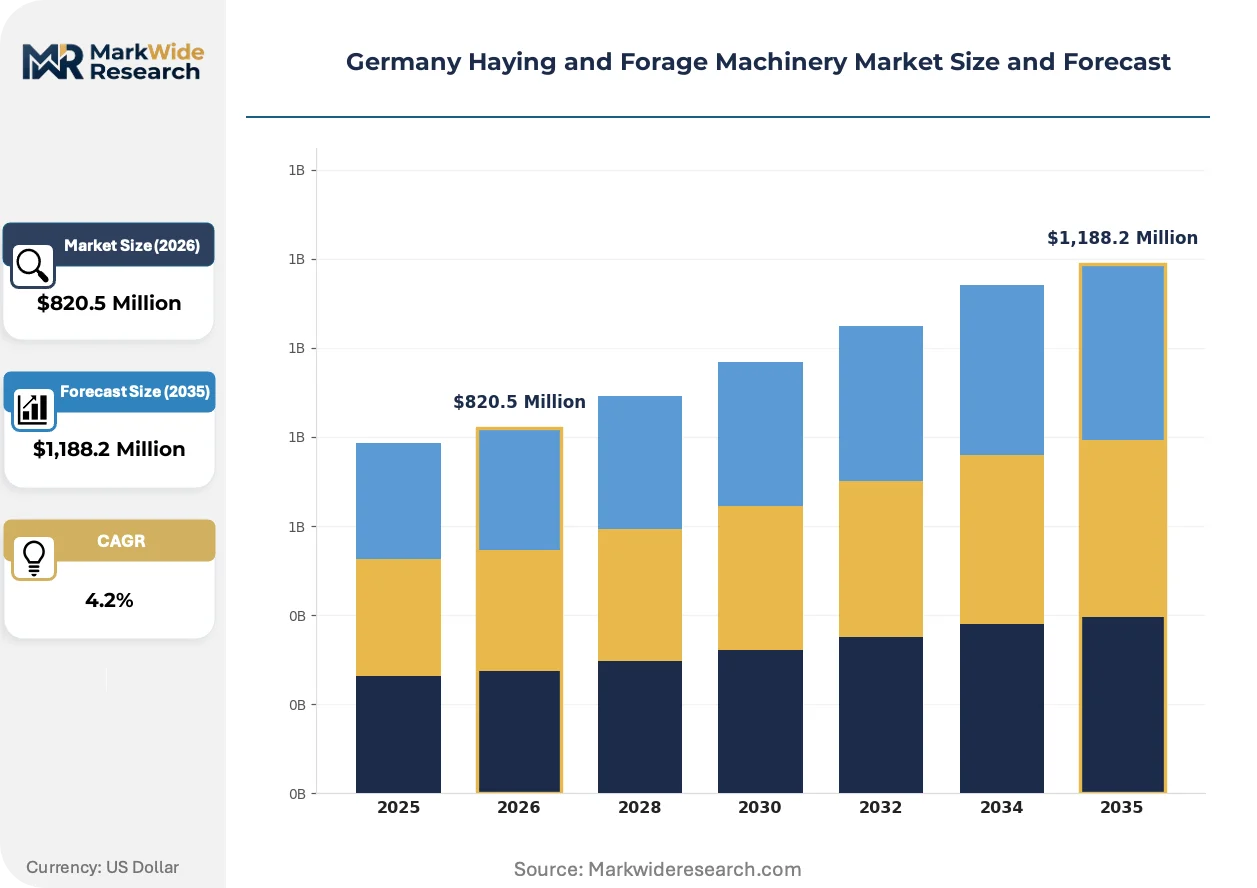
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,188.2 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baler, Mower Conditioner, Tedder, Rake, Forage Harvester, Loader Wagon Technology: Hydraulic Drive, PTO Drive, Electric Drive, Mechanical Drive, GPS Guidance, Sensor Integration Application: Silage Harvesting, Haymaking, Crop Conditioning, Stubble Management, Straw Handling, Bale Wrapping End User: Dairy Farms, Livestock Farms, Contracting Services, Agricultural Cooperatives, Crop Producers |
| Companies Covered | CLAAS, John Deere, Kubota Corporation, Krone, New Holland Agriculture, Case IH, Lemken, Pottinger, Kuhn Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Haying and Forage Machinery Market Shifts & Advancements
Automation layers are penetrating haying and forage machinery faster than electrification, driven by labor scarcity and subsidy documentation requirements rather than energy cost pressures alone.
Sensor fusion technology is consolidating field operation data from moisture detectors, yield monitors, and GPS tracks into unified farm management information systems. Dairy cooperatives in Schleswig-Holstein are mandating this data architecture for supplier compliance. The structural result is that machinery without open API connectivity is consolidating into commodity price tiers.
Germany's Fertilizer Ordinance is restricting nutrient application timing and rates, forcing machinery specifications toward precision cutting heights that preserve soil structure and minimize runoff risk. Equipment manufacturers must now document field compaction metrics to maintain market access. Northern German dealers report specification requests increasingly cite nutrient management compliance as the primary purchase criterion.
Service unbundling is fragmenting traditional distribution relationships as large contractors procure parts directly from VDMA member manufacturers and source maintenance through independent hydraulic specialists. Bavarian machinery rings are negotiating fleet-level service contracts that exclude dealer markups. This pattern concentrates most visibly in regions with established contracting cooperative structures.
Germany Haying and Forage Machinery Market Segmentation
German haying and forage machinery segments reflect divergent capital intensity across dairy operations, contracting services, and crop producers. Equipment specifications vary sharply between standalone implements for smaller holdings and integrated systems for professional operators in Lower Saxony and Bavaria.
Product Type:
Integration depth separates self-propelled systems with embedded automation from tractor-mounted implements requiring operator skill.
- Forage Harvester:Self-propelled units with integrated crop flow systems dominate capital expenditure in intensive livestock corridors. Bavarian dairy cooperatives specify these for high-wet silage operations where throughput per hour determines seasonal capacity.
- Baler:Round and square balers with variable chamber technology serve contracting services across northern Germany. Density sensors and net-wrapping automation reduce field passes, critical for operators covering 2,000+ hectares annually.
- Mower Conditioner:Disc and drum configurations with integrated conditioning rollers occupy mature replacement cycles in grassland regions.
- Tedder:Rotary and finger-wheel designs spread cut biomass for moisture reduction before raking.
- Rake:Single-rotor and twin-rotor configurations consolidate swaths for baler pickup efficiency.
- Loader Wagon:Self-loading trailers with cutting mechanisms transport chopped material from field to storage.
Volume placements concentrate in balers and forage harvesters; the faster expansion belongs to high-capacity self-propelled harvesters with telemetry integration.
Technology:
Cost tier stratification places precision automation in premium equipment while mechanical drives serve price-sensitive operators in southern regions.
- GPS Guidance:RTK-corrected auto-steering systems document field operations for EU subsidy compliance and variable-rate management. Schleswig-Holstein dairy cooperatives mandate this data architecture for supplier qualification.
- Sensor Integration:Moisture detectors, yield monitors, and compaction sensors feed farm management information systems. The EU AI Act's risk classification framework shapes development priorities for bale-tracking algorithms.
- Hydraulic Drive:Proportional valve systems enable variable speed control in mower conditioners and tedders.
- PTO Drive:Tractor power-take-off remains standard for lower-horsepower implements in mixed farming operations.
- Electric Drive:Battery-electric actuators penetrate conveyor and wrapping functions ahead of full powertrain electrification.
- Mechanical Drive:Gearbox and driveline configurations persist in commodity-grade equipment serving machinery rings.
Adoption velocity peaks in GPS guidance and sensor fusion; electric drive expansion lags pending Stage V compliance cost resolution.
Application:
Customer type determines specification intensity, with contracting services demanding multi-function flexibility and dairy farms prioritizing silage quality consistency.
- Silage Harvesting:Precision-chopped whole-crop cereals and grass require specific theoretical length of cut settings. Bavarian biogas plants specify 4-8 mm chop lengths for optimal anaerobic digestion feedstock.
- Haymaking:Drying, tedding, and baling operations for equine and small ruminant feed quality standards.
- Crop Conditioning:Crushing and crimping treatments accelerate moisture release in humid German summers.
- Stubble Management:Post-harvest residue handling for seedbed preparation and pest suppression.
- Straw Handling:Collection and densification of cereal residues for bedding and biogas substrate.
- Bale Wrapping:Film and net wrapping for aerobic stability in outdoor storage conditions.
Equipment utilization rates favor silage harvesting; margin capture concentrates in precision conditioning applications with documented nutrient management compliance.
End User:
Procurement scale separates fleet purchasers with direct manufacturer relationships from single-unit buyers dependent on dealer networks.
- Contracting Services:Professional forage contractors in Lower Saxony and Schleswig-Holstein replace equipment on 3-5 year cycles. These operators negotiate fleet-level telemetry subscriptions and parts direct from VDMA manufacturers.
- Dairy Farms:Herd sizes above 200 cows in Bavaria justify dedicated self-propelled harvesters with CEMOS automation for labor efficiency.
- Livestock Farms:Beef and sheep operations in central Germany utilize smaller balers and mower conditioners on seasonal hire arrangements.
- Agricultural Cooperatives:Machinery rings pool equipment across member farms, favoring robust mechanical designs over precision technology.
- Crop Producers:Arable farmers with marginal grassland purchase used equipment from Dutch import channels.
Revenue concentration sits with contracting services; the steepest technology upgrade trajectory belongs to large dairy farms integrating sensor data into herd management software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lower Saxony's intensive livestock corridor anchors German haying and forage machinery demand, with dairy cooperatives in the Oldenburg Münsterland driving specification intensity for high-capacity self-propelled harvesters.
Bavaria
Biogas feedstock demand from anaerobic digestion plants in the Danube and Main valleys pulls precision-chopped whole-crop cereal equipment. Germany's Fertilizer Ordinance restricts nutrient application windows, forcing machinery specifications toward soil-preserving cutting heights. Munich-based machinery rings negotiate fleet telemetry contracts that bypass traditional dealer networks.
Lower Saxony
Milk quota compliance pressures in the Emsland and Weser-Ems regions accelerate capital expenditure on automated silage systems. EU Stage V emission regulations compress engine choices for equipment servicing the dense dairy operations around Vechta and Cloppenburg. Contracting services here replace harvester fleets on three-year cycles with direct manufacturer relationships.
Schleswig-Holstein
Dairy cooperatives mandate GPS-tracked field documentation for supplier qualification, creating specification pull for sensor-integrated equipment across the Schleswig-Flensburg corridor. The EU Green Deal's Farm to Fork strategy pressures machinery toward documented fuel intensity per ton harvested. Professional contractors in the Dithmarschen bogs operate the highest machine utilization rates nationally.
Baden-Württemberg
Mixed farming operations in the Kraichgau and Swabian Alps favor versatile tractor-mounted implements over dedicated self-propelled systems. KBA emission enforcement shapes equipment replacement timing for the region's smaller herd structures. Stuttgart-area machinery rings pool seasonal demand across fragmented livestock holdings.
North Rhine-Westphalia
Depreciated Dutch import equipment saturates the Münsterland's southern margins, constraining new machinery absorption rates among price-sensitive beef and sheep operations. The VDMA coordinates conformity assessment timelines that delay product launches for regional implement distributors. Cologne-based contracting cooperatives source maintenance through independent hydraulic specialists rather than dealer channels.
Germany Haying and Forage Machinery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across automation integration depth, with integrated crop flow systems commanding pricing separation from mechanical-drive implements. The vendor base stratifies into three tiers: full-line systems houses with proprietary telemetry platforms, specialized rotor and chopping innovators, and regional fabricators serving machinery rings. Consolidation pressure concentrates most visibly in the mid-tier, where electronics-hydraulics integration demands outpace traditional technical capabilities. Dominant competitive moves include backward integration into precision sensor supply and geographic expansion through service unbundling that fragments legacy distribution relationships.
Within the premium automation tier, CLAAS anchors integrated systems positioning through its CEMOS technology layer, while John Deere exemplifies precision agriculture ecosystem control. Krone occupies a specialized position in high-wet silage rotor innovation. These three represent divergent strategic archetypes: proprietary automation platforms, agricultural data ecosystems, and mechanical specialization for specific crop conditions.
| Leading Market Players |
|---|
| CLAAS |
| John Deere |
| Kubota Corporation |
| Krone |
| New Holland Agriculture |
| Case IH |
| Lemken |
| Pottinger |
| Kuhn Group |
| Others |
Supply & Pricing Matrix
Contracting services in Lower Saxony and Schleswig-Holstein anchor pricing power through fleet-level procurement negotiations that bypass traditional dealer markups. Their concentrated buying volume forces manufacturers toward subscription telemetry models and direct parts relationships that reshape margin capture across the sector.
Pricing Analysis
Throughput-per-hour metrics anchor value-based pricing for self-propelled forage harvesters in intensive livestock corridors. Premium-mid-economy pricing differentiation separates CEMOS-enabled automation tiers from mechanical-drive commodity equipment serving machinery rings. Cost compression in mid-tier implements is intensifying because Stage V after-treatment hardware inflates diesel powertrain costs above 130 kilowatts. Machinery rings exhibit highest price sensitivity; large dairy cooperatives with biogas feedstock contracts show lowest sensitivity to capital expenditure.
Supply Chain Analysis
Regional distribution centers in Münsterland and Oldenburg coordinate hub-and-spoke patterns that consolidate final-mile delivery to northern German contracting clusters. Manufacturing draws from German, Italian, and Austrian production hubs for precision hydraulics and high-strength alloy components. Steel and hydraulic component volatility creates margin unpredictability for mid-tier implement manufacturers. Distribution runs through VDMA-coordinated dealer networks that fragment as large contractors source maintenance through independent hydraulic specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's Stage V emission regulations and the EU AI Act's risk classification framework erect compliance moats that favor capitalized incumbents with dedicated regulatory affairs capabilities.
For Market Incumbents: Anticipate electronics-hydraulics integration bottlenecks by captive supply of CAN bus protocol specialists and ISOBUS compatibility engineers. Backward integration into precision sensor supply secures margin control against emerging telemetry platform competitors. Defensive consolidation should target mid-tier manufacturers lacking CE marking documentation expertise. For New Entrants and Emerging Players: The price-point gap between premium automation tiers and economy mechanical drives offers entry space for sensor-agnostic implement designs. Southern German machinery rings and Dutch-import-dependent crop producers in North Rhine-Westphalia represent the most penetrable buyer segments. A go-to-market angle through independent hydraulic service networks bypasses entrenched dealer relationships. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with proprietary rotor or chopping innovations that lack telemetry scale. Long-term viability hinges on software development capabilities that meet EU AI Act compliance thresholds for autonomous path-planning algorithms. Watch for inflection when dairy cooperatives mandate open API connectivity as a supplier qualification standard.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply | CEMOS automation platforms require captive moisture detector and yield monitor production to control telemetry data flows. |
| CE Marking Documentation Investment | Six-to-twelve month conformity assessment timelines for self-propelled equipment demand dedicated regulatory affairs infrastructure. |
| Subscription Telemetry Model Launch | Remote diagnostics platforms generate recurring revenue from Lower Saxony contracting services with three-year replacement cycles. |
| Biogas Feedstock Equipment Specialization | Bavarian anaerobic digestion plants specify 4-8 mm chop lengths that precision-chopped whole-crop cereal systems must deliver. |
| Independent Hydraulic Service Partnership | Bavarian machinery rings and Cologne-based cooperatives source maintenance outside dealer channels, creating alternative distribution pathways. |
Research Methodology
Multi-period observation of VDMA shipment data, KBA emission compliance filings, and dairy cooperative equipment procurement patterns anchored the trend analysis, supplemented by interviews with forage harvester product managers, precision agriculture software engineers, contracting service fleet operators, and VDMA regulatory affairs directors. Secondary validation drew from EU Machinery Directive implementation reports, Stage V engine certification databases, and Schleswig-Holstein dairy cooperative supplier qualification standards. Bottom-up equipment placement modeling and top-down agricultural machinery production statistics were triangulated to constrain estimate variance.
Segment-weighting across product type, technology tier, application intensity, and end-user procurement scale informed the analytical framework across the analysis window. CAGRs were derived from equipment replacement cycle analysis, milk quota compliance pressures, and biogas plant feedstock demand trajectories. Forecast inputs incorporated EU Green Deal Farm to Fork strategy implementation timelines and Fertilizer Ordinance restriction schedules affecting machinery specification requirements.
Inputs from VDMA member manufacturers and northern German dealer networks were available through the study window; gaps in real-time telemetry subscription revenue disclosure introduce uncertainty bands around service revenue projections. Forecasts reflect documented assumptions regarding Stage V compliance cost trajectories and EU AI Act enforcement timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
Global Tillage Equipment Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market