
 GCC Organic Fertilizer Market | 2026-2036
GCC Organic Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Organic Fertilizer Market Foresight
Saudi Vision 2030 is decoupling organic fertilizer eligibility from traditional subsidy frameworks, forcing manufacturers to recertify under stricter sustainability protocols. Al Yahar Organic Fertilizers Factory leverages its proximity to UAE date palm plantations to dominate compost distribution across the northern emirates. Emirates Bio Fertilizer Factory anchors production capacity near Abu Dhabi's food recycling hubs, securing feedstock cost advantages. RNZ Agrotech Industries Ltd. competes through specialized vermicompost lines targeting Oman's expanding greenhouse vegetable sector.
Organic fertilizers are nutrient-rich soil amendments derived from decomposed plant matter, animal manure, or marine biomass, typically containing nitrogen, phosphorus, and potassium in forms requiring microbial mineralization before plant uptake. These products restore soil organic carbon and improve water retention in arid-zone agriculture, where synthetic salt accumulation degrades long-term productivity. Compost and manure formulations lead volume sales across the GCC, reflecting established supply chains from municipal waste and livestock operations. Liquid seaweed extracts and vermicompost represent the fastest-expanding form categories, driven by precision drip-irrigation adoption in Saudi greenhouse complexes and UAE hydroponic facilities. Pelletized products command margin premiums where mechanized spreading equipment predominates.
MOHAP in the UAE and Saudi Arabia's Ministry of Environment, Water and Agriculture enforce fertilizer registration protocols that mandate heavy-metal thresholds and pathogen reduction certification for commercial sale. The Saudi Standards, Metrology and Quality Organization (SASO) and Emirates Authority for Standardization and Metrology (ESMA) govern product labeling and organic content verification, creating compliance barriers for unregistered imports. Stakeholders must monitor how Gulf harmonization of bio-input standards reshapes cross-border trade eligibility and domestic production incentives.
Market Dynamics
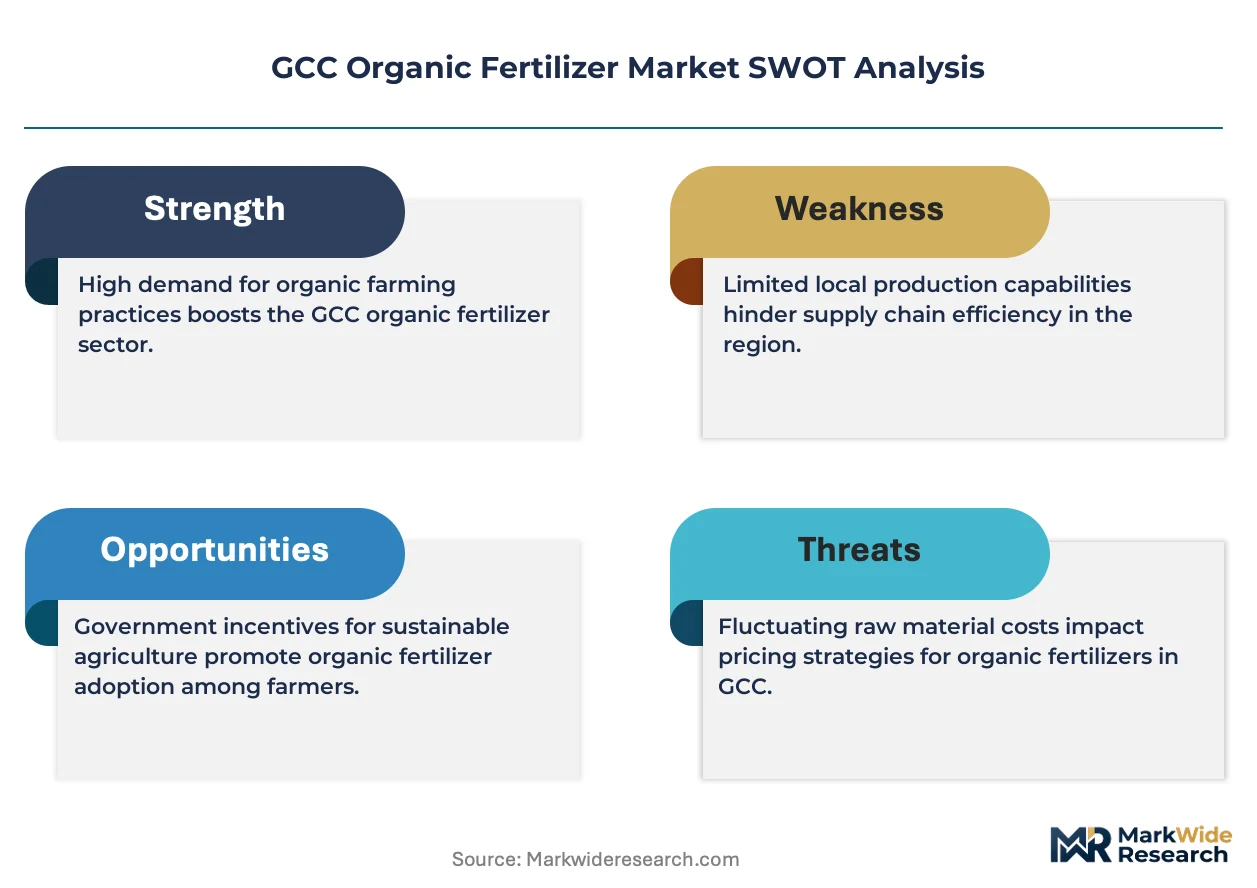
Saudi Vision 2030 subsidy recalibration is forcing manufacturers to abandon synthetic-compatible certification pathways and rebuild compliance infrastructure around microbial mineralization protocols and heavy-metal threshold documentation.
Growth Catalysts
- Al-Qassim Greenhouse Expansion:Large-scale vegetable operations in Saudi Arabia's central region are replacing chemical fertilizer programs with compost-based soil amendments, creating concentrated demand pull for pelletized formulations compatible with mechanized spreading equipment.
- MOHAP Registration Streamlining:The UAE health authority's consolidated fertilizer approval pathway reduces time-to-market for vermicompost products, incentivizing domestic production capacity expansion near Abu Dhabi's food waste recycling hubs.
- Date Palm Residue Valorization:Saudi Arabia's 30 million date palms generate substantial frond and fruit waste streams that composting facilities are capturing as captive feedstock, lowering raw material costs for nitrogen-rich formulations.
Market Restraints
- SASO Heavy-Metal Thresholds:Saudi Arabia's standards body mandates sub-ppm cadmium and lead limits that exclude imported manure from uncontrolled livestock operations, restricting supplier geography to certified feedlot sources.
- Arid-Zone Water Scarcity:Compost production requires moisture levels that evaporate rapidly in Gulf climates, forcing producers to install covered aeration systems that add 15-20% to capital intensity versus open-windrow alternatives.
- Synthetic Fertilizer Price Subsidies:Remaining urea and DAP support mechanisms in Oman and Bahrain create artificial price gaps that slow grower conversion to organic alternatives despite soil degradation risks.
Strategic Opportunities
- Oman Greenhouse Vegetable Sector:RNZ Agrotech's vermicompost specialization targets underpenetrated protected agriculture in Al Batinah and Dhofar, where Dutch-style hydroponic investment is accelerating without established organic input suppliers.
- Liquid Seaweed Extract Convergence:Integration of Red Sea kelp harvesting with precision drip-irrigation systems creates premium product positioning for UAE hydroponic facilities serving Emirates Flight Catering and luxury hotel chains.
- Emirates Bio Fertilizer Feedstock Control:Proximity to Abu Dhabi's source-separated organic waste collection zones enables backward integration into municipal composting contracts, locking in cost advantages against import-dependent competitors.
Industry Challenges
- Pathogen Reduction Certification Timelines:SASO and ESMA thermophilic processing documentation requirements extend product registration cycles to 14-18 months, straining working capital for small-scale composting operations.
- Microbial Mineralization Expertise Gap:Greenhouse operators lack agronomic training to manage nitrogen release timing from organic sources, creating yield risk that slows conversion from synthetic programs despite subsidy eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Organic Fertilizer Market |
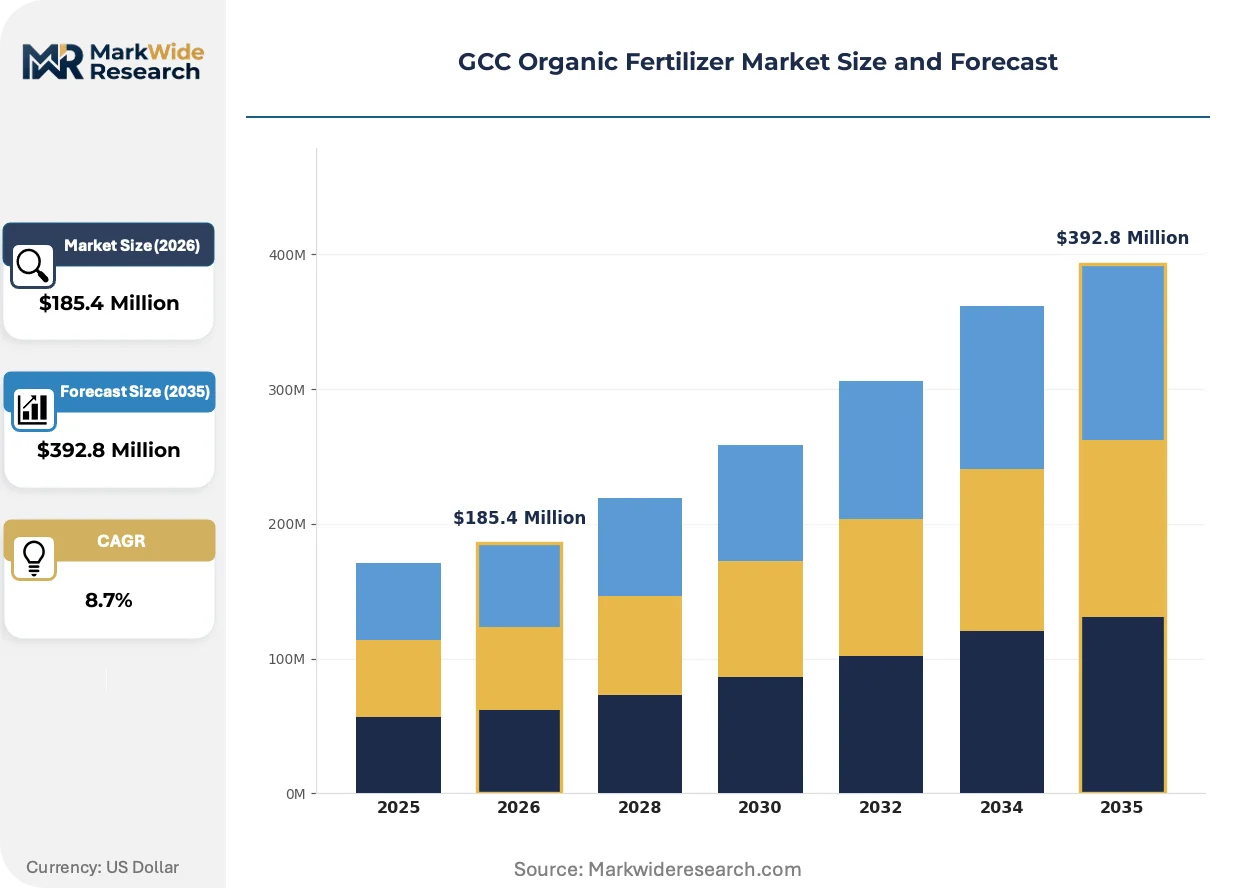
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $392.8 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compost, Manure, Bone Meal, Seaweed Extract, Vermicompost, Guano Application: Cereals & Grains, Fruits & Vegetables, Legumes, Turf & Ornamentals, Plantation Crops, Greenhouse Crops Form: Pelletized, Granular, Liquid, Powdered, Sheet, Briquette End User: Farmers, Agricultural Cooperatives, Horticulturists, Nurseries, Hydroponic Growers, Landscaping Services |
| Companies Covered | Al Yahar Organic Fertilizers Factory, uTerra Middle East Agro Industries LLC (UniPax Investment Group), RNZ Agrotech Industries Ltd. (RNZ Group), Union Chemicals Co. LLC, Desert Oasis Fertilizers Packaging LLC (Desert Group), Emirates Bio Fertilizer Factory (EBFF), Debbane Agri (Debbane Saikali Group), Tadweer Food Recycling Company, Al-Akhawain (Al-Akhawain Holding), Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Organic Fertilizer Market Shifts & Advancements
Precision agriculture infrastructure is reshaping how organic nutrients reach plants, with liquid delivery systems and sensor-controlled dosing displacing broadcast application methods across protected cultivation in the Gulf.
Vermicomposting technology is absorbing capital investment from producers seeking faster throughput than traditional windrow composting. Saudi greenhouse operators in Riyadh's outskirts are adopting continuous-flow worm reactor systems that cut processing time from 90 days to 45 days. This compression is absorbing price pressure from synthetic alternatives while delivering consistent microbial biomass counts that satisfy SASO registration requirements.
ESMA's 2024 harmonization of bio-input labeling standards with Saudi SASO protocols is eliminating dual-certification costs for cross-border suppliers. Manufacturers previously maintaining separate documentation for UAE and Saudi markets now submit unified organic-content verification. Liquid seaweed extract producers with Red Sea harvesting licenses are capturing first-mover advantage under this convergence, as their marine-sourced products face simplified heavy-metal traceability requirements.
Buyer consolidation among UAE hypermarket chains is compressing supplier negotiation cycles for organic produce certification. Lulu Group and Union Coop now mandate farm-level organic input documentation from vegetable suppliers, transferring compliance burden upstream to fertilizer manufacturers. This documentation cascade is most visible in Al Ain's protected agriculture zone, where farms serving Dubai's retail distribution centers are switching to registered compost brands to maintain shelf placement.
GCC Organic Fertilizer Market Segmentation
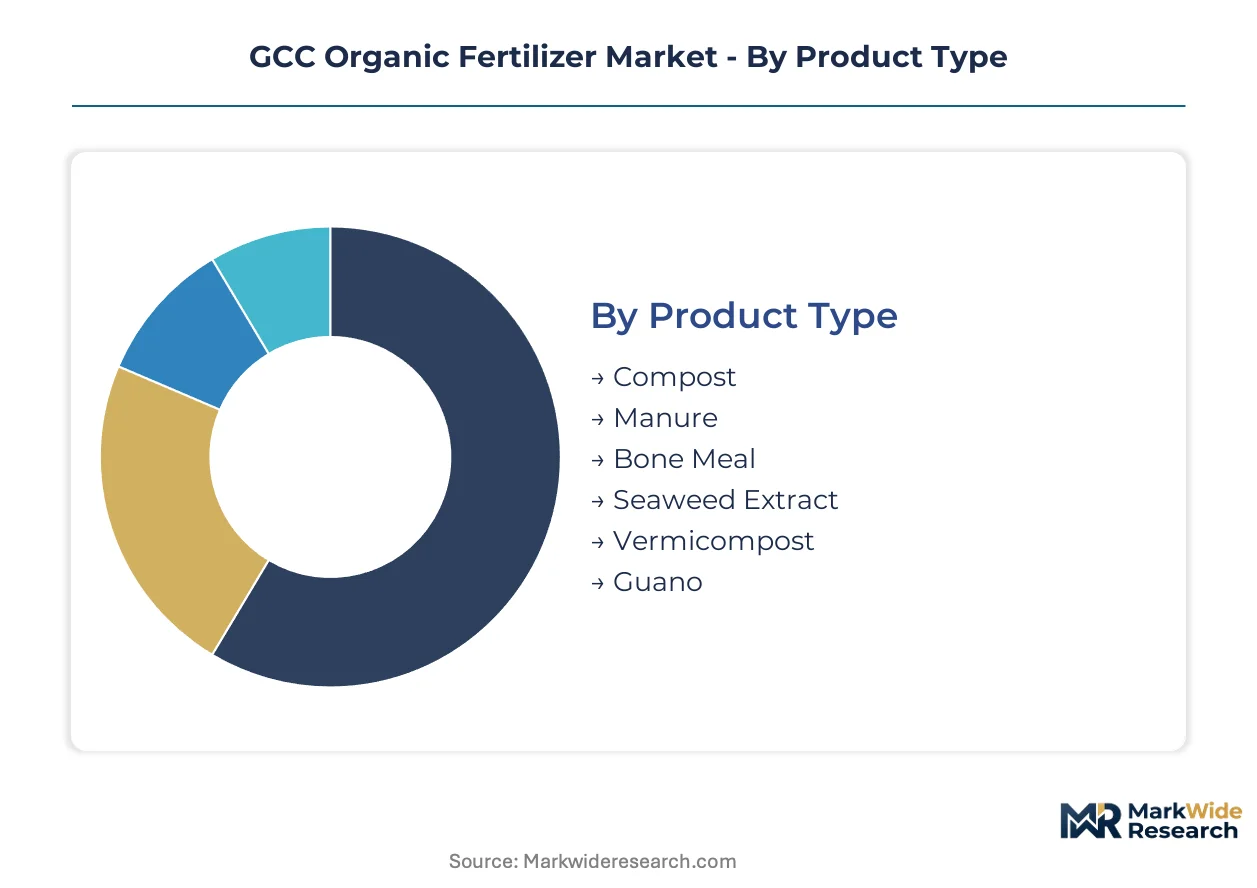
Segmentation in the GCC organic fertilizer market reveals how arid-zone agriculture constraints reshape product formulation priorities. Purchase patterns diverge sharply between protected cultivation operators demanding precision delivery systems and open-field date palm growers prioritizing soil carbon restoration. Understanding these divides exposes where manufacturers must recalibrate specifications to capture subsidy eligibility under Saudi Vision 2030 and UAE MOHAP frameworks.
Product Type:
Upgrade cycles in the GCC organic fertilizer market center on replacing synthetic nitrogen programs with microbial-mineralization alternatives that satisfy SASO heavy-metal thresholds without yield sacrifice.
- Compost:Decomposed organic matter from municipal green waste and agricultural residues, typically containing 1-3% nitrogen and 40-60% organic carbon. Demand concentrates in Saudi Arabia's Al-Qassim region, where greenhouse operators are replacing chemical programs with pelletized compost compatible with mechanized spreaders. SASO registration requirements for pathogen reduction documentation extend production cycles, favoring established facilities with thermophilic processing infrastructure.
- Manure:Livestock-derived amendments from cattle, poultry, and sheep operations, prized for immediate nitrogen availability and phosphorus content. UAE dairy and poultry feedlots near Al Ain supply captive feedstock to Emirates Bio Fertilizer Factory, locking in cost advantages against import-dependent competitors. SASO cadmium and lead thresholds below 1 ppm exclude uncontrolled livestock sources, restricting supplier geography to certified feedlot operations.
- Bone Meal:Steamed animal bones providing slow-release phosphorus and calcium for root development in alkaline Gulf soils.
- Seaweed Extract:Marine-sourced biostimulants harvested from Red Sea kelp beds, concentrated through precision evaporation for drip-irrigation compatibility.
- Vermicompost:Earthworm-processed organic matter with elevated microbial biomass and fine particle structure. RNZ Agrotech Industries Ltd. targets Oman's greenhouse vegetable sector with specialized vermicompost lines.
- Guano:Accumulated seabird or bat excrement with exceptional nitrogen and phosphorus concentration, imported primarily for high-value ornamental and turf applications.
Compost sits at the top of the volume ranking, with vermicompost climbing the fastest as greenhouse operators seek faster nutrient release timing.
Application:
Application segmentation tracks how Saudi Vision 2030 agricultural diversification mandates redirect subsidy structures toward specific crop categories.
- Fruits & Vegetables:Protected cultivation of tomatoes, cucumbers, and leafy greens in Saudi greenhouses and UAE hydroponic facilities. Al-Qassim and Riyadh operators are replacing synthetic fertilizer programs with compost-based amendments, creating concentrated demand pull for registered products. Lulu Group and Union Coop now mandate farm-level organic input documentation from vegetable suppliers.
- Greenhouse Crops:Soilless and substrate-based production systems requiring liquid or fine-grade organic inputs compatible with precision dosing equipment. Emirates Flight Catering contracts drive premium positioning for Red Sea seaweed extract integration in UAE hydroponic facilities.
- Cereals & Grains:Wheat and barley cultivation in Saudi Arabia's central regions, gradually converting from urea-dependent programs.
- Legumes:Nitrogen-fixing crop rotations gaining traction under soil health initiatives in Oman and Bahrain.
- Turf & Ornamentals:Golf course and landscaping maintenance across Dubai and Abu Dhabi, demanding pelletized products for mechanized application.
- Plantation Crops:Date palm cultivation across Saudi Arabia's 30 million palms, generating substantial frond waste streams for captive composting feedstock.
Fruits and vegetables command the largest revenue share, with greenhouse crops expanding most quickly as Dutch-style hydroponic investment accelerates.
Form:
Form selection in Gulf markets reflects the tension between water scarcity constraints and precision agriculture infrastructure deployment.
- Liquid:Concentrated extracts and suspensions designed for drip-irrigation and fertigation systems. UAE hydroponic facilities serving luxury hotel chains prioritize liquid seaweed formulations for sensor-controlled dosing. Red Sea kelp harvesting licenses create first-mover advantages under ESMA-SASO harmonized labeling standards.
- Pelletized:Compressed organic matter in uniform spherical or cylindrical shapes for mechanized spreading. Al-Qassim greenhouse operations demand pelletized compost compatible with broadcast spreaders and precision planters.
- Granular:Irregular particle sizes suitable for soil incorporation in open-field date palm cultivation.
- Powdered:Fine-ground amendments for soil drenching and compost tea preparation in nursery operations.
- Sheet:Compressed fiber mats for erosion control and mulching in landscaping applications.
- Briquette:High-density compressed blocks for slow-release carbon supplementation in sandy desert soils.
Pelletized products dominate mechanized applications, with liquid formulations gaining share fastest as drip-irrigation infrastructure spreads.
End User:
End-user segmentation exposes where compliance documentation burdens concentrate and which buyer categories drive premium pricing.
- Farmers:Individual growers and family operations managing open-field and protected cultivation across Saudi Arabia's agricultural zones. Al-Qassim and Riyadh regions show concentrated conversion from synthetic programs as subsidy eligibility shifts.
- Hydroponic Growers:Soilless cultivation specialists in UAE facilities and Saudi greenhouse complexes. These operators lack agronomic training to manage nitrogen release timing from organic sources, creating yield risk that slows conversion despite subsidy eligibility.
- Agricultural Cooperatives:Consolidated purchasing entities aggregating demand from multiple smallholders.
- Horticulturists:Specialized producers of ornamental and high-value crops for domestic and export markets.
- Nurseries:Plant propagation operations requiring consistent, pathogen-free growing media.
- Landscaping Services:Commercial maintenance contractors for municipal parks, golf courses, and luxury developments.
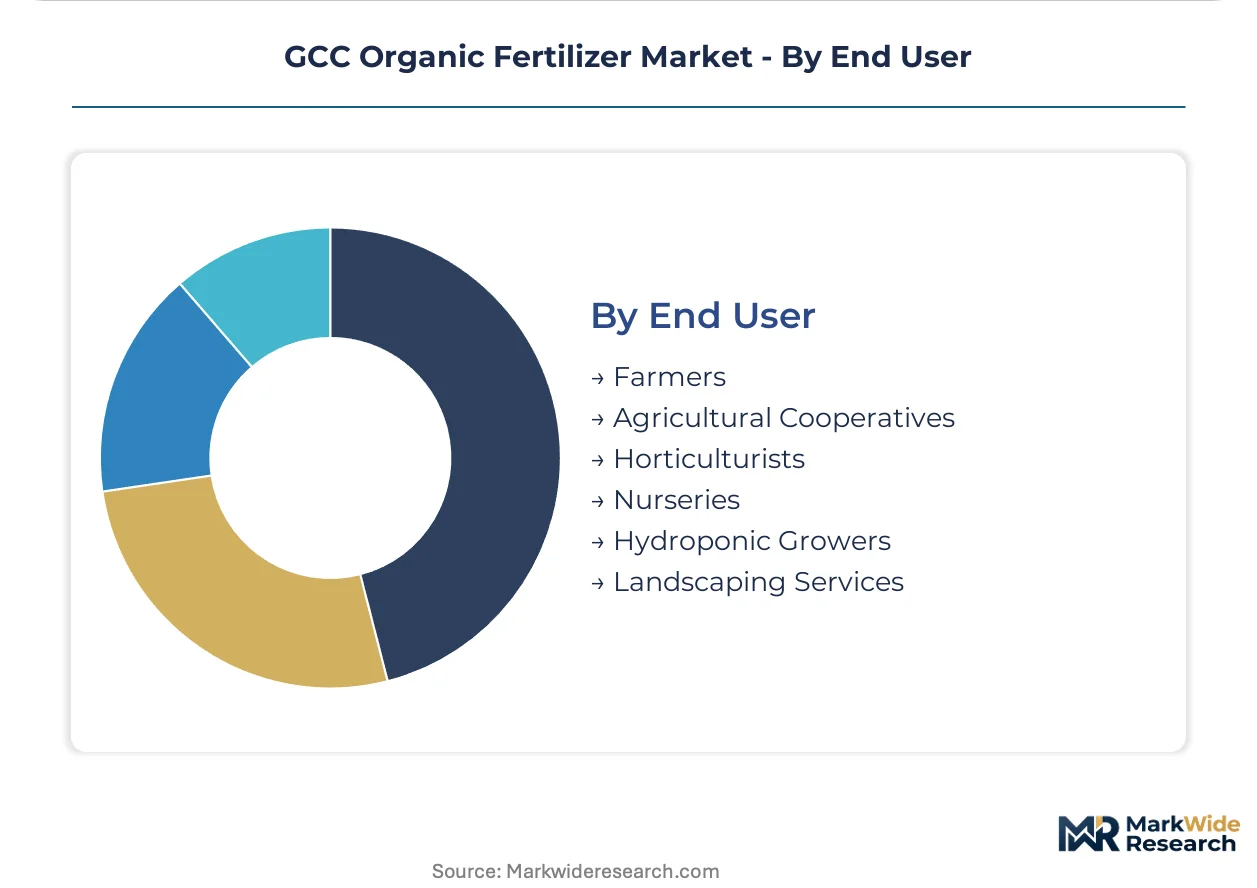
Farmers represent the largest volume base, with hydroponic growers expanding most quickly as protected agriculture investment outpaces input supplier establishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Organic fertilizer production across the Gulf Cooperation Council traces its modern lineage to Saudi Arabia's agricultural investment surge of the 1980s, when state-led wheat self-sufficiency programs first established composting infrastructure around Riyadh's dairy clusters.
Saudi Arabia
Date palm cultivation across 30 million trees generates massive frond and fruit waste streams that Al-Qassim composting facilities now capture as captive feedstock. Saudi Vision 2030 subsidy recalibration is decoupling organic fertilizer eligibility from traditional frameworks, forcing manufacturers to recertify under stricter SASO sustainability protocols. Riyadh's greenhouse belt is replacing synthetic fertilizer programs with pelletized compost formulations compatible with mechanized spreading equipment.
United Arab Emirates
MOHAP's consolidated fertilizer approval pathway reduces time-to-market for vermicompost products, accelerating domestic production capacity expansion. Emirates Bio Fertilizer Factory anchors production near Abu Dhabi's food recycling hubs, securing feedstock cost advantages through municipal waste contracts. Dubai's hydroponic facilities serving luxury hotel chains and Emirates Flight Catering drive premium positioning for liquid seaweed extract integration.
Oman
Dutch-style hydroponic investment is accelerating across Al Batinah and Dhofar without established organic input suppliers, creating white-space opportunity for specialized vermicompost lines. Remaining urea and DAP support mechanisms create artificial price gaps that slow grower conversion despite soil degradation risks. RNZ Agrotech Industries Ltd. targets this underpenetrated protected agriculture sector with technical-grade formulations.
Qatar
Food security mandates under the National Food Security Strategy are redirecting procurement toward domestic composting capacity. Tadweer Food Recycling Company leverages source-separated organic waste collection to supply nitrogen-rich amendments for greenhouse vegetable operations. Doha's controlled-environment agriculture investments concentrate demand for pathogen-free, SASO-compliant growing media.
Bahrain
Synthetic fertilizer price subsidies persist as the dominant restraint on organic conversion among open-field growers. The kingdom's limited domestic production capacity forces reliance on Saudi and UAE imports subject to harmonized ESMA-SASO labeling standards. Northern governorate date farms represent the primary addressable market for soil carbon restoration programs.
GCC Organic Fertilizer Market Competitive Landscape
The competitive structure tilts toward feedstock-integrated domestic producers with municipal waste contracts or captive agricultural residue streams. Manufacturer density concentrates in the UAE and Saudi Arabia, where regulatory registration barriers filter out import-dependent traders. Three archetypes dominate: waste-management spin-offs with backward integration into municipal composting, agribusiness conglomerates leveraging livestock operations for manure supply, and specialized vermicompost operators targeting greenhouse precision agriculture. Capacity expansion and strategic partnerships with food waste collection authorities constitute the primary competitive moves.
Among UAE-based producers, Emirates Bio Fertilizer Factory exemplifies the waste-management integration archetype through its proximity to Abu Dhabi's recycling infrastructure. Al Yahar Organic Fertilizers Factory represents the agricultural residue valorization model, leveraging access to northern emirates date palm plantations. RNZ Agrotech Industries Ltd. occupies the specialist tier, with positioning around technical-grade vermicompost for precision agriculture applications.
| Leading Market Players |
|---|
| Al Yahar Organic Fertilizers Factory |
| uTerra Middle East Agro Industries LLC (UniPax Investment Group) |
| RNZ Agrotech Industries Ltd. (RNZ Group) |
| Union Chemicals Co. LLC |
| Desert Oasis Fertilizers Packaging LLC (Desert Group) |
| Emirates Bio Fertilizer Factory (EBFF) |
| Debbane Agri (Debbane Saikali Group) |
| Tadweer Food Recycling Company |
| Al-Akhawain (Al-Akhawain Holding) |
| Others |
Supply & Pricing Matrix
Specialized thermophilic processing technicians concentrated in Saudi Arabia's Al-Qassim and Riyadh regions command wage premiums that compress pricing-tier spreads between SASO-certified premium formulations and uncertified economy alternatives. Labor-cost differentials in compost production feed directly into margin structures, with covered aeration system operators passing through 15-20% capital intensity premiums while competing against open-windrow imports from Oman and Bahrain.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction dynamics, with SASO registration status and feedstock traceability separating tiers. Premium pelletized compost carrying full pathogen-reduction documentation commands spreads over unregistered granular alternatives from uncontrolled livestock sources. Pricing pressure stems from remaining urea and DAP subsidies in Oman and Bahrain that artificially depress synthetic reference points. Hydroponic growers in UAE facilities show lowest price sensitivity due to Emirates Flight Catering contract premiums, while open-field date farmers in Bahrain's northern governorate exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Saudi Arabia's captive date palm residue streams that Al-Qassim composting facilities have locked through municipal collection contracts. Raw material dependencies center on thermophilic processing infrastructure, earthworm biomass for vermicompost lines, and Red Sea kelp harvesting licenses for liquid extract production. Supply chain risk manifests as regulatory restriction exposure through SASO heavy-metal threshold enforcement that excludes uncontrolled livestock manure. Distribution runs through agricultural cooperative aggregators in Saudi Arabia's central regions and direct-to-farm contracts for UAE hydroponic facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC organic fertilizer market functions as a stable compounder, with Saudi Vision 2030 agricultural diversification mandates providing durable policy tailwinds that redirect subsidy structures regardless of commodity cycle volatility.
For Market Incumbents: Deepen backward integration into municipal organic waste collection contracts to lock in feedstock cost advantages against import-dependent challengers. Incumbents should expand thermophilic processing capacity in Riyadh's greenhouse belt to capture concentrated demand from mechanized spreading operations. SASO registration maintenance and pathogen-reduction documentation infrastructure constitute the primary defensive moat against unregistered import competition. For New Entrants and Emerging Players: Oman's underpenetrated greenhouse vegetable sector in Al Batinah and Dhofar presents the most accessible white-space opportunity, with Dutch-style hydroponic investment accelerating ahead of established organic input suppliers. New entrants should prioritize technical-grade vermicompost specialization targeting precision agriculture applications rather than competing on volume in saturated compost segments. Direct technical agronomy support services addressing the microbial mineralization expertise gap offer differentiated go-to-market positioning. For Investors and Strategic Acquirers: Waste-management conglomerates with existing municipal collection infrastructure are the most active acquirer in this space, seeking backward integration into value-added processing. The five-to-ten year viability window favors feedstock-integrated domestic producers over import-dependent traders. Acquisition targets should demonstrate captive agricultural residue or municipal waste contracts alongside SASO or ESMA registration pathways. The signal to monitor is harmonization progress on Gulf bio-input standards that would reshape cross-border trade eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Municipal Waste Contract Securement | Backward integration into Abu Dhabi's source-separated organic collection zones locks in cost advantages against import competitors. |
| Thermophilic Processing Capacity Addition | Expansion in Al-Qassim satisfies SASO pathogen-reduction timelines that strain working capital for small-scale operations. |
| Vermicompost Specialization Investment | Continuous-flow worm reactor systems cut processing time from 90 days to 45 days for Riyadh greenhouse operators. |
| Red Sea Kelp Harvesting License Acquisition | Marine-sourced products face simplified heavy-metal traceability under ESMA-SASO harmonized labeling standards. |
| Technical Agronomy Service Development | Direct nitrogen-release timing guidance addresses the expertise gap slowing hydroponic grower conversion from synthetic programs. |
Research Methodology
Bottom-up greenhouse and open-field cultivation modeling reconciled against top-down composting facility capacity tracking forms the analytical core. Primary interviews with Saudi Ministry of Environment officials, UAE MOHAP registration specialists, Al-Qassim greenhouse operation managers, and Emirates Bio Fertilizer procurement leads combined with secondary validation from SASO standards documentation, ESMA labeling protocols, customs trade records, and municipal waste collection authority disclosures. Triangulation across these sources calibrated volume estimates against feedstock availability constraints.
Historical trendline analysis of date palm residue generation, dairy cluster manure output, and municipal organic waste collection volumes established baseline supply parameters. Segmentation modeling spanned product type, application crop category, physical form, and end-user archetype across the projection horizon. CAGRs derived from subsidy policy trajectory analysis and protected agriculture investment pipelines, with Saudi Vision 2030 implementation pace and Dutch-style hydroponic capital deployment serving as key forecast inputs.
Underlying measurement precision varies by segment; SASO-registered compost and vermicompost categories carry tighter precision than unregistered economy alternatives due to documentation requirements. Forecasts reflect assumptions around subsidy recalibration timing, municipal contract renewal rates, and harmonization progress on Gulf bio-input standards. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Africa Fertilizers Market
Fertilizers
Organic Fertilizers Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
India Urea Market
Fertilizers
Global Complex Fertilizers Market
Fertilizers
South America Fertilizers Market
Fertilizers
Water Soluble NPK Fertilizers Market
Fertilizers
Enhanced Efficiency Fertilizer Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Brazil Organic Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market