
 Global Insect Growth Regulators Market | 2026-2036
Global Insect Growth Regulators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insect Growth Regulators Market Foresight
Modular tank-mix bundling is shifting buyer choice in the insect growth regulators space, as distributors combine chitin synthesis inhibitors with biological adjuvants into season-specific packages. BASF SE leverages its formulation science footprint to sustain premium positioning in emulsifiable concentrate systems. Bayer AG anchors European ornamental applications through channel partnerships with pest management firms. Syngenta AG competes in cereal crop segments across North American and Australian geographies.
Insect growth regulators are synthetic or naturally derived compounds that disrupt insect metamorphosis through juvenile hormone mimicry, chitin synthesis inhibition, or ecdysone receptor modulation, typically applied at concentrations between 0.01% and 0.1% active ingredient depending on pest species and crop stage. Chitin synthesis inhibitors dominate value pools in stored product protection where residual activity commands pricing premiums, while juvenile hormone analogues represent the fastest-expanding chemistry class in forestry pest management programs. Ecdysone receptor agonists occupy narrower but higher-margin positions in research institution supply chains where precision dosing protocols require specialized formulation types.
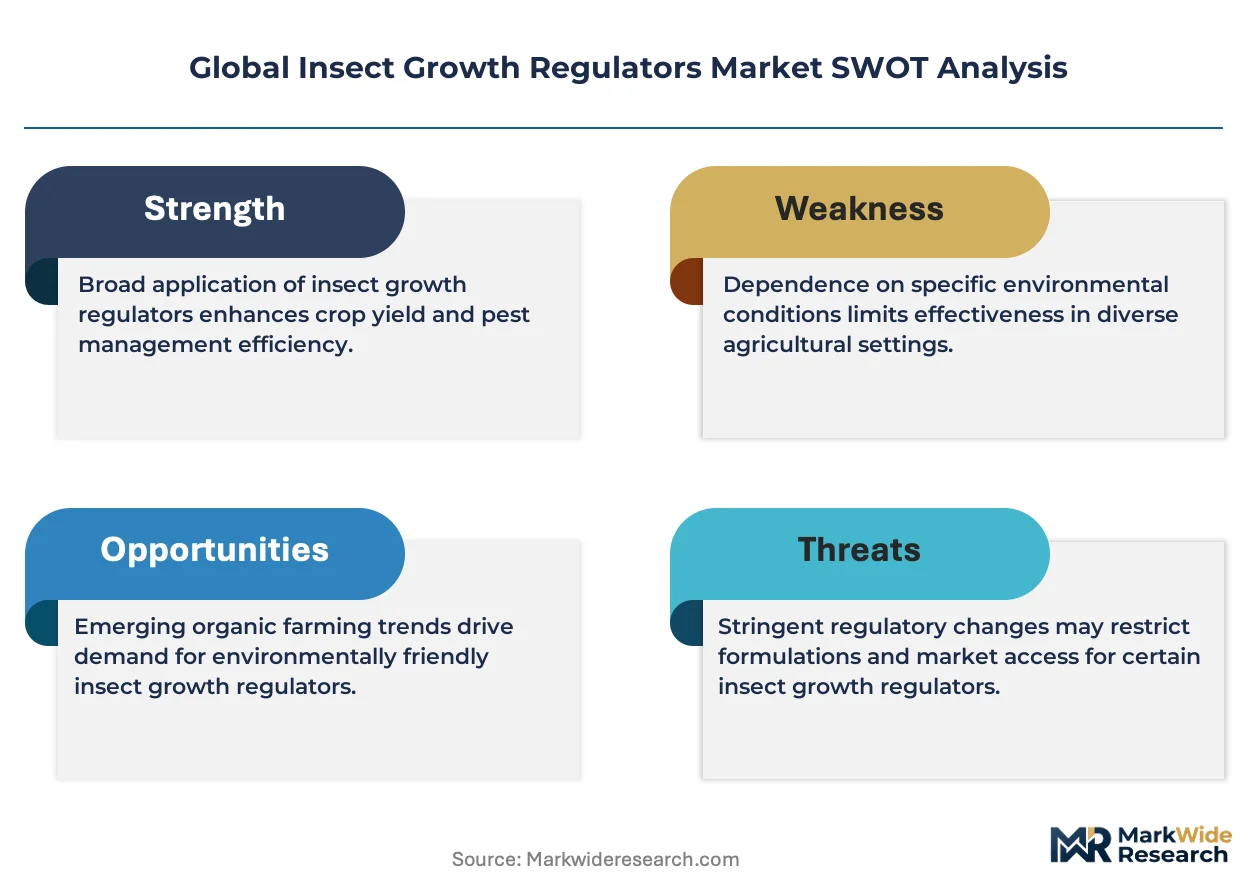
The EPA regulates IGR residue tolerances under the Federal Insecticide, Fungicide, and Rodenticide Act, while the EU Green Deal and REACH frameworks restrict conventional neurotoxic insecticide approvals and redirect formulator investment toward biorational alternatives. India's Central Insecticides Board mandates BIS certification for imported active ingredients, creating compliance barriers that favor established registrants with local toxicology dossiers. Stakeholders must monitor evolving maximum residue limits in export destination markets to avoid shipment rejections and preserve contract farming relationships.
Market Dynamics
Resistance management protocols are forcing cotton and soybean growers to rotate away from pyrethroids toward chitin synthesis inhibitors, restructuring procurement calendars and distributor inventory planning across agricultural input channels.
Growth Catalysts
- EU Green Deal Farm to Fork targets:The pesticide reduction mandates are redirecting formulator R&D budgets toward biorational chemistry platforms, expanding addressable market for juvenile hormone analogues in European cereal protection.
- Pink bollworm resistance in India:Cotton belt farmers are accelerating IGR rotation protocols, creating concentrated demand clusters in Maharashtra and Gujarat where conventional insecticide failure rates exceed economic thresholds.
- Stored product protection:Residual activity premiums for chitin synthesis inhibitors in grain silos and warehousing operations sustain pricing power in post-harvest segments across Brazil and Australia.
Market Restraints
- Active ingredient cost volatility:Fluctuations in benzoylurea intermediate supply from Chinese specialty chemical manufacturers compress margin predictability for emulsifiable concentrate formulators.
- Registration timeline friction:India's Central Insecticides Board mandates BIS certification for imported active ingredients, creating multi-year compliance barriers that favor established registrants with local toxicology dossiers.
- Biological substitution threat:Bacillus thuringiensis formulations and entomopathogenic nematodes are capturing share in forestry pest management programs where application precision requirements are less stringent.
Strategic Opportunities
- Underpenetrated Brazilian soybean belt:Agricultural cooperatives are expanding IGR procurement for pest cycles in Mato Grosso and Rio Grande do Sul, creating channel partnership openings for formulation specialists.
- Modular tank-mix bundling:Distributors are combining chitin synthesis inhibitors with biological adjuvants into season-specific packages, enabling premium positioning through application convenience rather than commodity active ingredient competition.
- EU REACH biorational redirection:Restrictions on conventional neurotoxic insecticide approvals are accelerating investment in ecdysone receptor agonist research platforms for high-value ornamental and research institution segments.
Industry Challenges
- Maximum residue limit compliance:Exporters must monitor evolving MRL standards in destination markets including EU, Japan, and Australia to avoid shipment rejections and preserve contract farming relationships.
- Formulation talent scarcity:Specialized expertise in microencapsulation and controlled-release systems for juvenile hormone analogues concentrates within a limited pool of agricultural chemists, constraining product pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insect Growth Regulators Market |
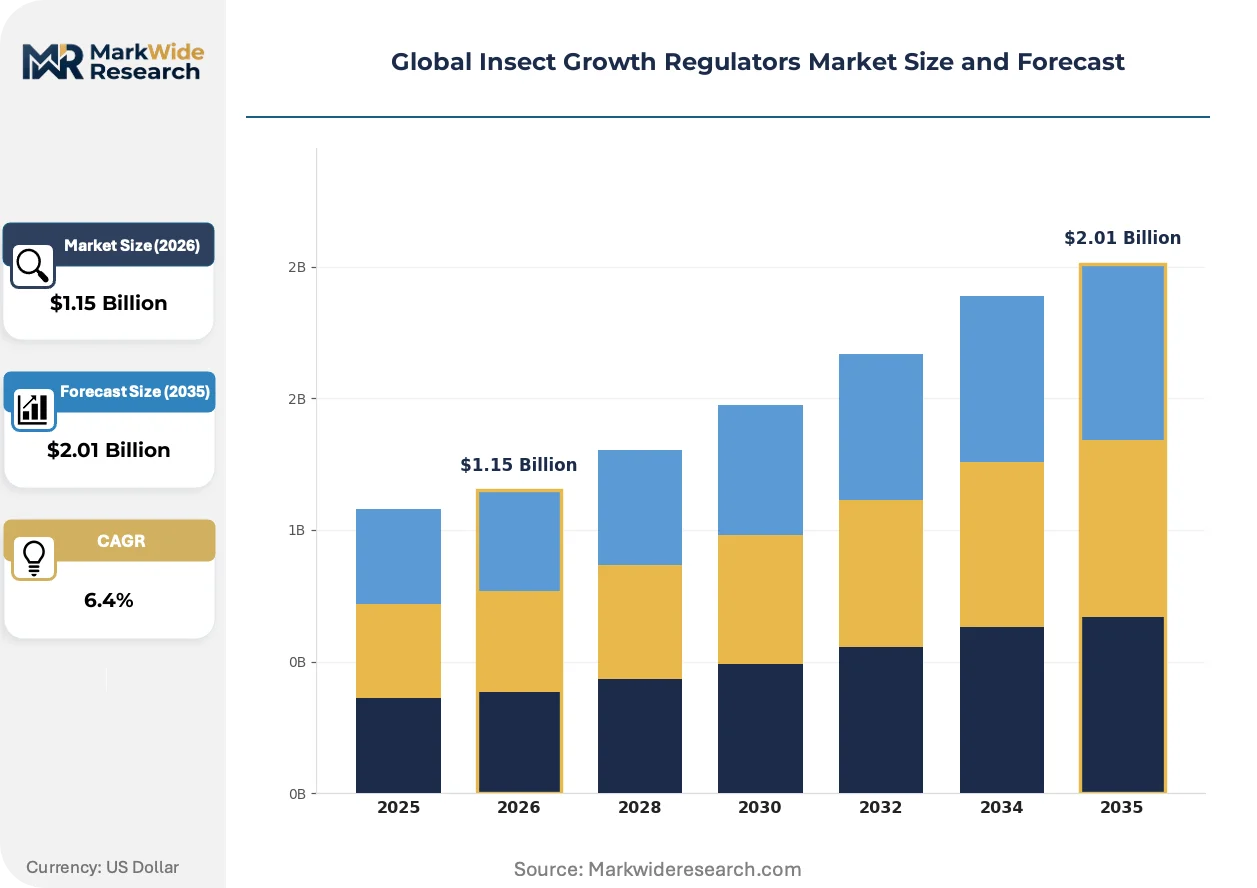
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.01 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Juvenile Hormone Analogues, Chitin Synthesis Inhibitors, Ecdysone Receptor Agonists, Moulting Disruptors Application: Cereal Crops, Vegetables, Ornamentals, Stored Product Protection, Forestry Pest Management End User: Crop Protection Companies, Agricultural Cooperatives, Pest Management Firms, Research Institutions Formulation Type: Emulsifiable Concentrate, Wettable Powder, Granular, Suspension Concentrate, Soluble Concentrate |
| Companies Covered | BASF SE, Bayer AG, Syngenta AG, Corteva Agriscience, Sumitomo Chemical Co. Ltd., FMC Corporation, Nufarm Limited, UPL Limited, Adama Agricultural Solutions Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insect Growth Regulators Market Shifts & Advancements
Formulation science convergence with biological adjuvants is redefining competitive positioning, as application performance becomes the primary purchasing criterion rather than standalone active ingredient specifications.
Microencapsulation technology is unifying residual activity control with environmental stability in chitin synthesis inhibitor delivery systems. Large-scale grain handlers and warehouse operators are adopting these formulations to extend protection windows between applications. The technology is compressing the total cost of ownership for stored product protection programs by reducing reapplication frequency and labor deployment.
REACH framework restrictions on conventional neurotoxic insecticides are redirecting formulator investment toward biorational chemistry platforms. European ornamental and greenhouse segments are experiencing accelerated product substitution as regulatory pressure compounds with buyer sustainability preferences. German and Dutch pest management firms are restructuring supplier relationships to secure juvenile hormone analogue supply commitments ahead of anticipated registration bottlenecks.
Buyer concentration among agricultural cooperatives is consolidating procurement authority and compressing distributor margins. Brazilian soybean growers are negotiating direct supply agreements with formulation houses, bypassing traditional retail channels in Mato Grosso and Paraná. This channel disintermediation is most visible in high-volume commodity crop segments where application scale justifies dedicated logistics investment.
Global Insect Growth Regulators Market Segmentation
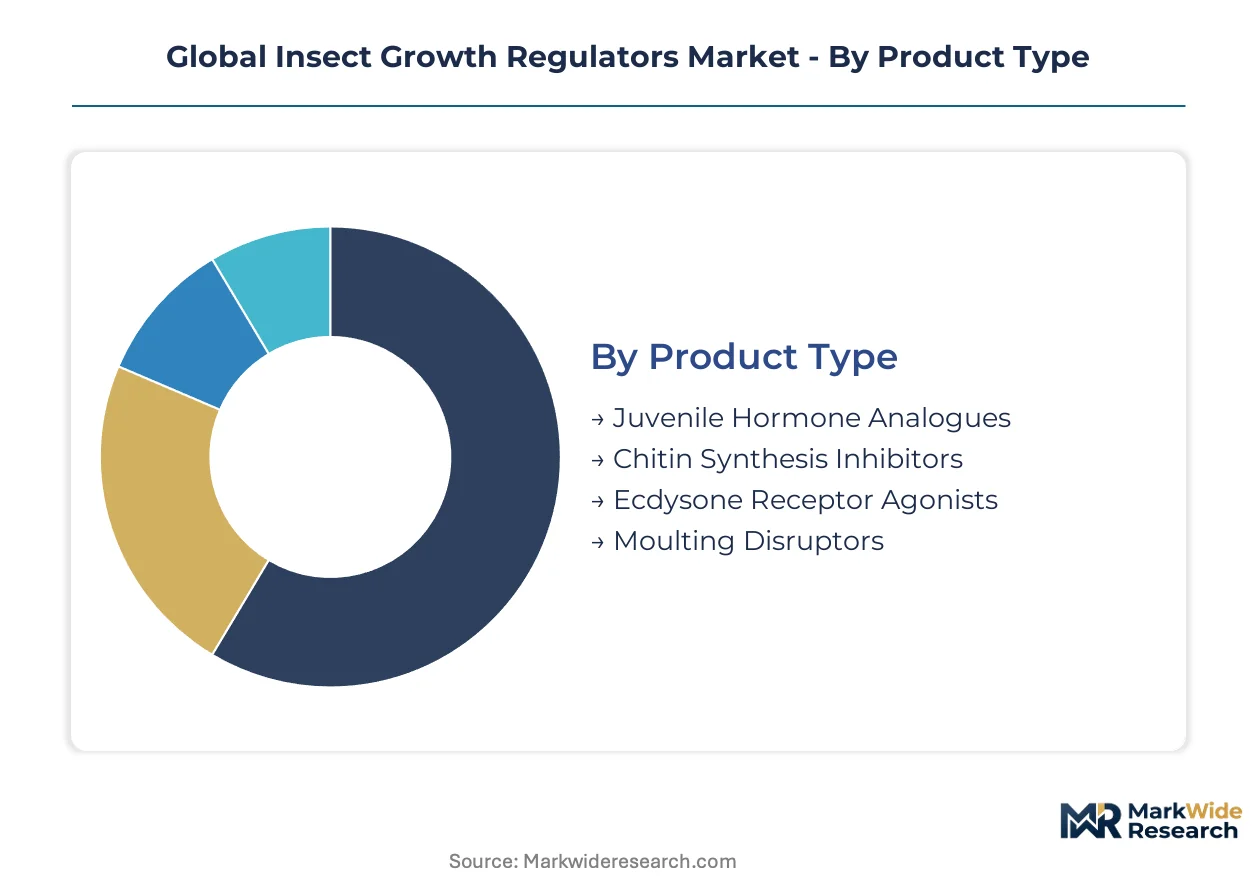
IGR procurement patterns diverge sharply across chemistry classes and application contexts, with stored product protection commanding residual-activity premiums while juvenile hormone analogues capture expansion in forestry programs. Formulation complexity and registration requirements create distinct capital barriers that reshape competitive entry across each segment category.
Product Type:
Capital intensity peaks with ecdysone receptor agonists, where precision-dosing protocols and specialized toxicology dossiers demand sustained R&D commitment before commercialization.
- Juvenile Hormone Analogues:Synthetic compounds that mimic natural insect developmental hormones, disrupting metamorphosis at pupal stages. Demand concentrates in Maharashtra and Gujarat cotton belts where pink bollworm resistance to conventional chemistry accelerates rotation protocols.
- Chitin Synthesis Inhibitors:Benzoylurea-based chemistry that blocks cuticle formation during moulting, requiring precise application timing. Grain silo operators in Brazil and Australia pay residual-activity premiums for extended protection windows between applications.
- Ecdysone Receptor Agonists:High-margin niche chemistry requiring specialized formulation expertise for research institution supply chains.
- Moulting Disruptors:Compounds inducing premature or incomplete ecdysis, deployed selectively in integrated pest management rotations.
Most installed capacity flows through chitin synthesis inhibitors. Expansion is steepest in juvenile hormone analogues.
Application:
Volume concentration varies by residual activity requirements, with post-harvest segments sustaining pricing power through extended protection windows.
- Cereal Crops:Large-scale field applications across North American and Australian geographies where Syngenta AG maintains active market presence.
- Vegetables:High-frequency spraying schedules in intensive horticulture systems with strict maximum residue limit compliance obligations.
- Ornamentals:Greenhouse and nursery protection where Bayer AG anchors European supply through pest management firm partnerships.
- Stored Product Protection:Post-harvest grain warehousing and silo operations where microencapsulation technology compresses total cost of ownership through reduced reapplication frequency.
- Forestry Pest Management:Aerial and ground-based application programs where juvenile hormone analogues displace biological alternatives in precision-demanding contexts.
Revenue concentrates in stored product protection. Gaining share fastest in forestry pest management.
End User:
Procurement authority is consolidating among agricultural cooperatives, compressing traditional distributor margins and enabling direct manufacturer relationships.
- Crop Protection Companies:Formulation houses investing in emulsifiable concentrate science and microencapsulation capabilities for differentiated positioning.
- Agricultural Cooperatives:Brazilian soybean belt organizations in Mato Grosso and Rio Grande do Sul expanding IGR procurement for pest cycle management.
- Pest Management Firms:German and Dutch operators restructuring supplier relationships to secure juvenile hormone analogue commitments ahead of registration bottlenecks.
- Research Institutions:Specialized buyers requiring precision-dosing protocols and ecdysone receptor agonist supply for experimental programs.
Contract volume flows through agricultural cooperatives. Climbing the fastest in research institutions.
Formulation Type:
Technical expertise scarcity concentrates in microencapsulation and controlled-release systems, constraining pipeline velocity for premium delivery formats.
- Emulsifiable Concentrate:Oil-based systems where BASF SE sustains premium positioning through formulation science investment.
- Wettable Powder:Solid concentrate formats requiring dispersion stability for aerial and ground spray equipment compatibility.
- Granular:Soil-applied formulations with extended release characteristics for root-zone pest targeting.
- Suspension Concentrate:Aqueous systems combining particle stability with reduced solvent load for environmental compliance.
- Soluble Concentrate:True solution formulations enabling rapid tank-mix compatibility in modular bundling packages.
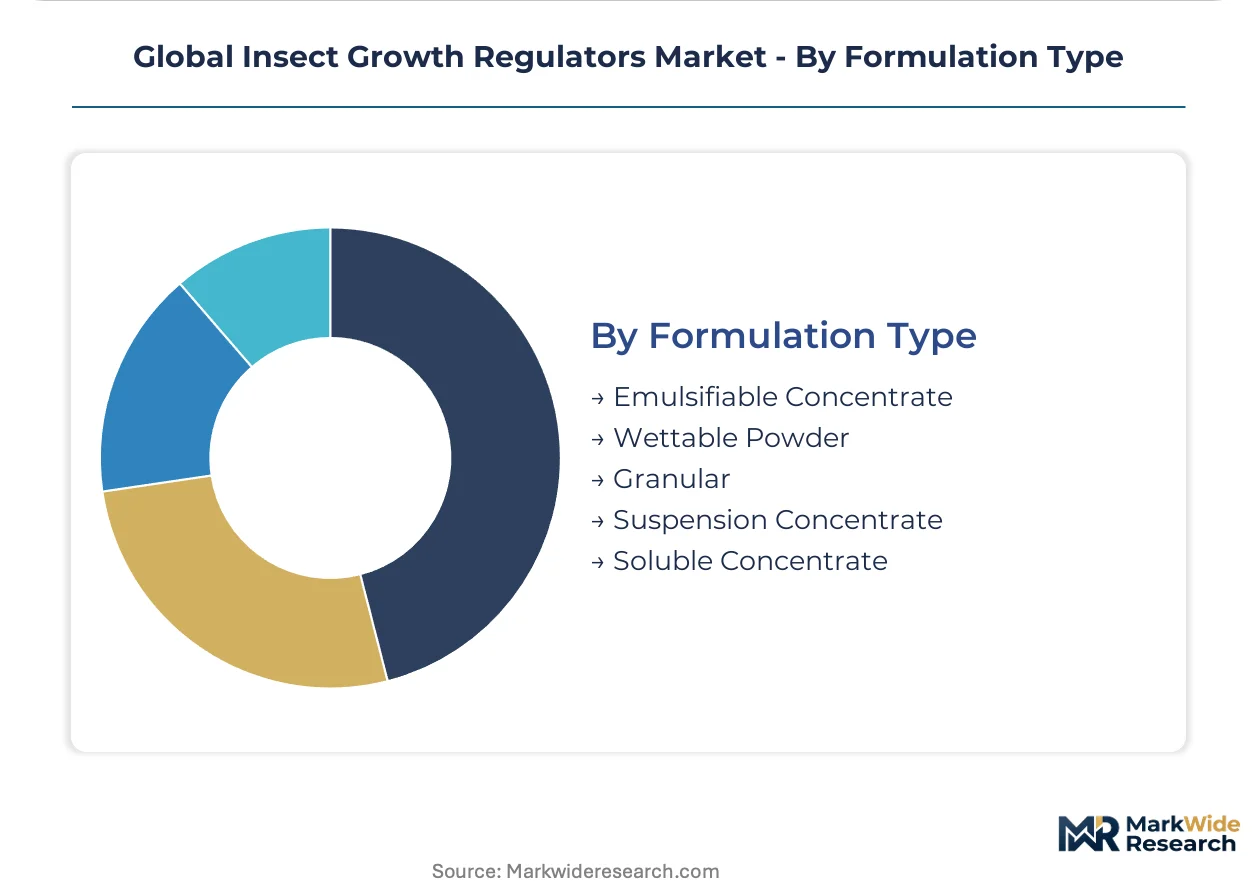
Production capacity centers on emulsifiable concentrate. Expanding most quickly in suspension concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The insect growth regulator industry traces its commercial origins to German and Swiss agrochemical laboratories during the 1970s benzoylurea discovery period, with subsequent scale-up occurring through North American field trials and Brazilian soybean adoption curves.
United States
Cereal crop protection drives IGR consumption across the Corn Belt and Northern Plains, with EPA residue tolerance enforcement under FIFRA shaping formulator compliance investments. The EPA regulates active ingredient approvals through multi-year toxicology review cycles. Iowa and Illinois grain handlers are deploying microencapsulated chitin synthesis inhibitors in elevator networks to extend protection windows between applications.
Brazil
Agricultural cooperatives in Mato Grosso and Rio Grande do Sul are expanding procurement for soybean pest cycles as resistance to pyrethroids accelerates rotation protocols. ANVISA maintains registration oversight for imported active ingredients, creating compliance timelines that favor established dossier holders. São Paulo-based formulation houses are negotiating direct supply agreements with cooperatives, bypassing traditional distribution channels.
India
Pink bollworm resistance in Maharashtra and Gujarat cotton belts is concentrating demand for juvenile hormone analogues as farmers abandon conventional insecticides. The Central Insecticides Board mandates BIS certification for imported active ingredients, erecting multi-year barriers for new entrants. Ahmedabad and Nagpur distribution clusters are restructuring inventory calendars around compressed IGR application windows.
Germany
EU Green Deal Farm to Fork targets are redirecting R&D investment toward biorational chemistry platforms for European cereal and ornamental protection. REACH framework restrictions on neurotoxic insecticides are accelerating product substitution timelines. Leverkusen and Ludwigshafen chemical complexes anchor formulation science development for emulsifiable concentrate systems serving greenhouse and nursery segments.
Australia
Stored product protection in grain export corridors sustains residual-activity premiums for chitin synthesis inhibitors across Queensland and Western Australia silo networks. The TGA and APVMA coordinate residue limit enforcement for export destination compliance. Perth and Brisbane warehouse operators are adopting controlled-release formulations to compress total cost of ownership through reduced reapplication frequency.
Global Insect Growth Regulators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and registration dossier depth, with microencapsulation capabilities and regional toxicology databases serving as the primary tiering mechanism. The vendor base concentrates around three strategic archetypes: diversified agrochemical conglomerates with integrated active ingredient supply, mid-scale formulation specialists leveraging regional registration expertise, and research-driven innovators occupying ecdysone receptor agonist niches. Competitive moves center on backward integration into benzoylurea intermediate supply and channel disintermediation through direct cooperative relationships.
Among diversified agrochemical conglomerates, BASF SE and Bayer AG exemplify the premium-tier archetype through sustained formulation science investment, while Syngenta AG occupies a parallel position in cereal crop segments across North American and Australian geographies. These entities represent the consolidation endpoint where registration scale and manufacturing scope create defensive moats against mid-cap challengers.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta AG |
| Corteva Agriscience |
| Sumitomo Chemical Co. Ltd. |
| FMC Corporation |
| Nufarm Limited |
| UPL Limited |
| Adama Agricultural Solutions Ltd. |
| Others |
Supply & Pricing Matrix
Formulation chemists with microencapsulation expertise cluster in the Rhine-Ruhr and Basel chemical corridors, creating labor-cost differentials that widen pricing spreads between premium controlled-release systems and commodity emulsifiable concentrates. Chinese benzoylurea intermediate manufacturers anchor the cost base for standard-tier chitin synthesis inhibitors, while German and Swiss facilities command 40-60% premiums for juvenile hormone analogue precision formulations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the IGR market, with certification grade under EU REACH and volume scale as the primary differentiation drivers. Cost compression in economy-tier benzoylurea formulations is intensifying because Chinese specialty chemical manufacturers are expanding benzoylurea intermediate capacity. Agricultural cooperatives in Brazil exhibit the highest price sensitivity due to soybean margin pressures, while research institutions show the least sensitivity given precision-dosing protocol requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and São Paulo operate hub-and-spoke patterns for active ingredient flow into formulation houses. Manufacturing concentrates in China, Germany, and India, with benzoylurea intermediates, juvenile hormone precursors, and ecdysone agonist raw materials feeding from these hubs. Single-source vulnerability in Chinese benzoylurea intermediate supply creates structural risk for emulsifiable concentrate formulators. Distribution runs through agricultural cooperative procurement offices and pest management firm supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal Farm to Fork pesticide reduction targets function as a regulatory compounder, redirecting formulator R&D budgets toward biorational chemistry platforms and expanding addressable market for juvenile hormone analogues.
For Market Incumbents: Deepen backward integration into benzoylurea intermediate supply to defend margin position against Chinese specialty chemical volatility. Secure captive production of juvenile hormone precursors in Basel and Ludwigshafen facilities. Biological substitution threats from Bacillus thuringiensis formulations demand accelerated microencapsulation R&D investment. For New Entrants and Emerging Players: Capture the underpenetrated Brazilian soybean belt in Mato Grosso and Rio Grande do Sul through direct cooperative supply agreements. Modular tank-mix bundling with biological adjuvants offers the most penetrable entry angle, bypassing commodity active ingredient competition through application convenience positioning. For Investors and Strategic Acquirers: Diversified agrochemical conglomerates are the most active acquirer in this space, targeting mid-scale formulation specialists with regional registration expertise. Long-term viability hinges on REACH-compliant dossier depth rather than active ingredient novelty. Monitor EU ecdysone receptor agonist registration bottlenecks as the critical inflection signal for biorational platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Benzoylurea Intermediates | Captures margin from Chinese specialty chemical suppliers and reduces formulation cost volatility. |
| Microencapsulation Capacity Expansion | Extends protection windows for grain silo operators in Brazil and Australia. |
| Direct Cooperative Supply Agreements | Bypasses distributor margin compression in Mato Grosso and Paraná soybean belts. |
| REACH-Compliant Dossier Investment | Secures European ornamental and cereal crop segments ahead of registration bottlenecks. |
| Modular Tank-Mix Bundling Development | Combines chitin synthesis inhibitors with biological adjuvants for season-specific packages. |
Research Methodology
Multiple input streams — technical interviews with formulation R&D directors, procurement discussions at agricultural cooperatives, and regulatory affairs consultations with Central Insecticides Board veterans — were reconciled against secondary validation. Primary sources included plant managers at benzoylurea intermediate facilities, channel partners in São Paulo distribution networks, and toxicology dossier specialists. Secondary data drew from EPA FIFRA filings, ECHA REACH registrations, ANVISA approval databases, and customs trade records for benzoylurea active ingredient flows. Bottom-up volume estimates from application rates and crop acreage were triangulated against top-down manufacturer revenue disclosures.
Data-stream reconciliation anchored the forecast framework across the analysis window, with segmentation modeled by chemistry class, application context, formulation complexity, and regional regulatory cluster. CAGRs were derived from growth driver elasticity analysis and substitution curve modeling. Key inputs included pink bollworm resistance progression rates in Maharashtra cotton belts and EU Farm to Fork implementation timelines for neurotoxic insecticide restrictions.
Regulatory approval delays, biological substitution acceleration, and benzoylurea intermediate supply disruptions are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Pre-Emergent Herbicide Market
Crop Protection
Global Acephate Market
Crop Protection
Fosthiazate Market
Crop Protection
Global Dicamba Herbicide Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Larvicides Market
Crop Protection
Miticides Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
Captan Fungicide Market
Crop Protection
Asia-Pacific Nematicides Market
Crop Protection
South America Acaricides Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
Hungary Crop Protection Chemicals Market
Crop Protection
Tebuconazole Epoxide Market