
 Lawn and Garden Equipment Market | 2026-2036
Lawn and Garden Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Lawn and Garden Equipment Market Analysis
Landscaping services is repositioning fleet procurement toward cordless electric platforms, creating volume pull distinct from seasonal residential patterns. Deere & Company dominates commercial-grade autonomous mowing systems through its precision agriculture heritage. Husqvarna Group leverages robotic connectivity to sustain premium positioning in European estates. STIHL specializes in professional-grade battery ecosystems that anchor its transition from two-stroke gasoline dominance.
Lawn and garden equipment encompasses motorized and non-motorized tools for vegetation management, typically spanning cutting widths of 30-72 inches for ride-on mowers and 20-40 volts for cordless handheld units, with primary purpose being turf maintenance, ornamental pruning, and debris clearance across residential, commercial, and public green spaces. Lawn mowers generate the largest revenue pool though cordless power sources represent the fastest structural expansion as lithium-ion energy density improvements displace gasoline in professional handheld categories. Electric power sources concentrate margin capture among battery cell suppliers and motor controller specialists, while gasoline equipment retains installed-base aftermarket parts profitability.
EPA Phase 3 emission standards tighten small spark-ignition engine limits, compelling Briggs & Stratton Corporation and Honda Motor Co., Ltd. to redirect R&D toward electrified architectures or advanced catalytic aftertreatment. California Air Resources Board zero-emission equipment mandates for landscaping fleets reshape commercial demand timing and create compliance-driven replacement cycles. Stakeholders must monitor battery recycling infrastructure development and charger network density as these determine total cost of ownership parity against established gasoline supply chains.
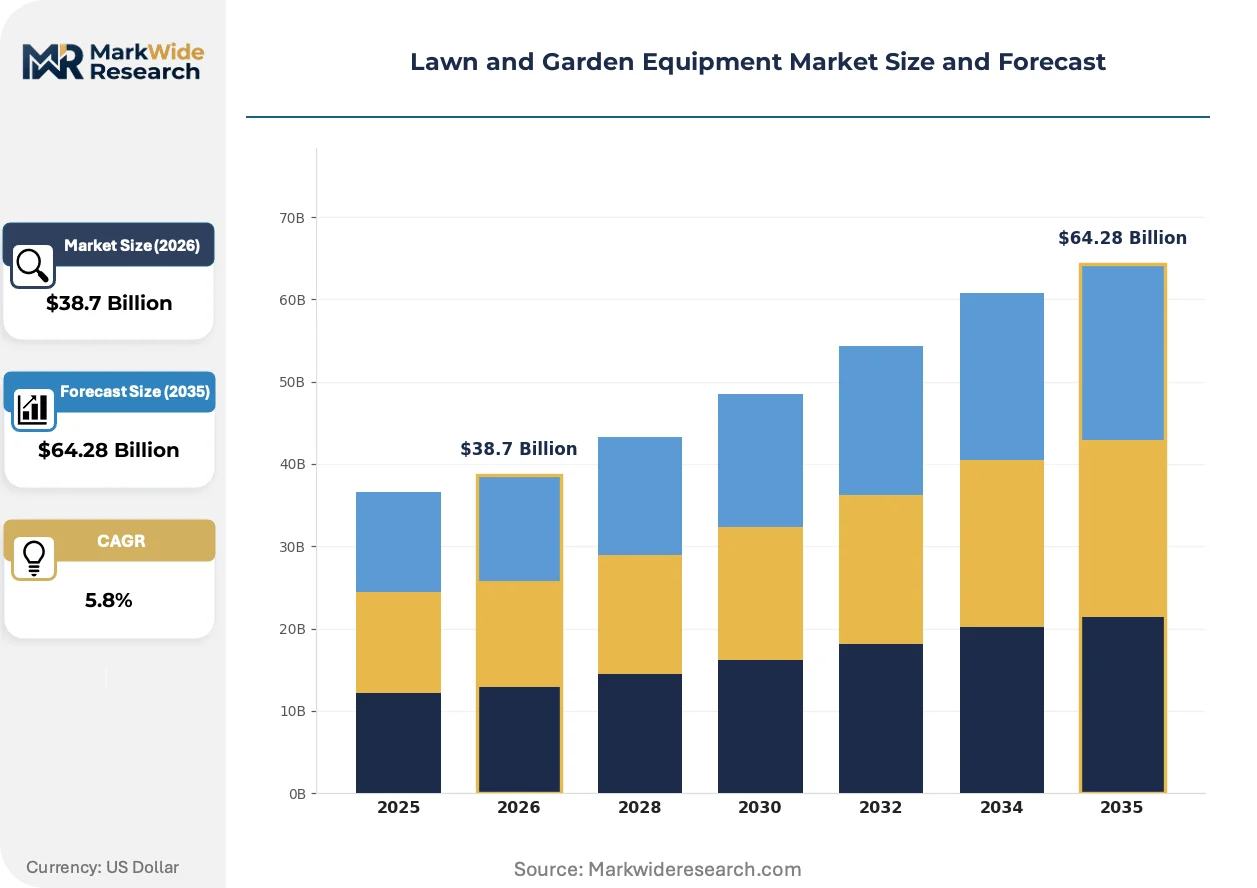
Market Dynamics
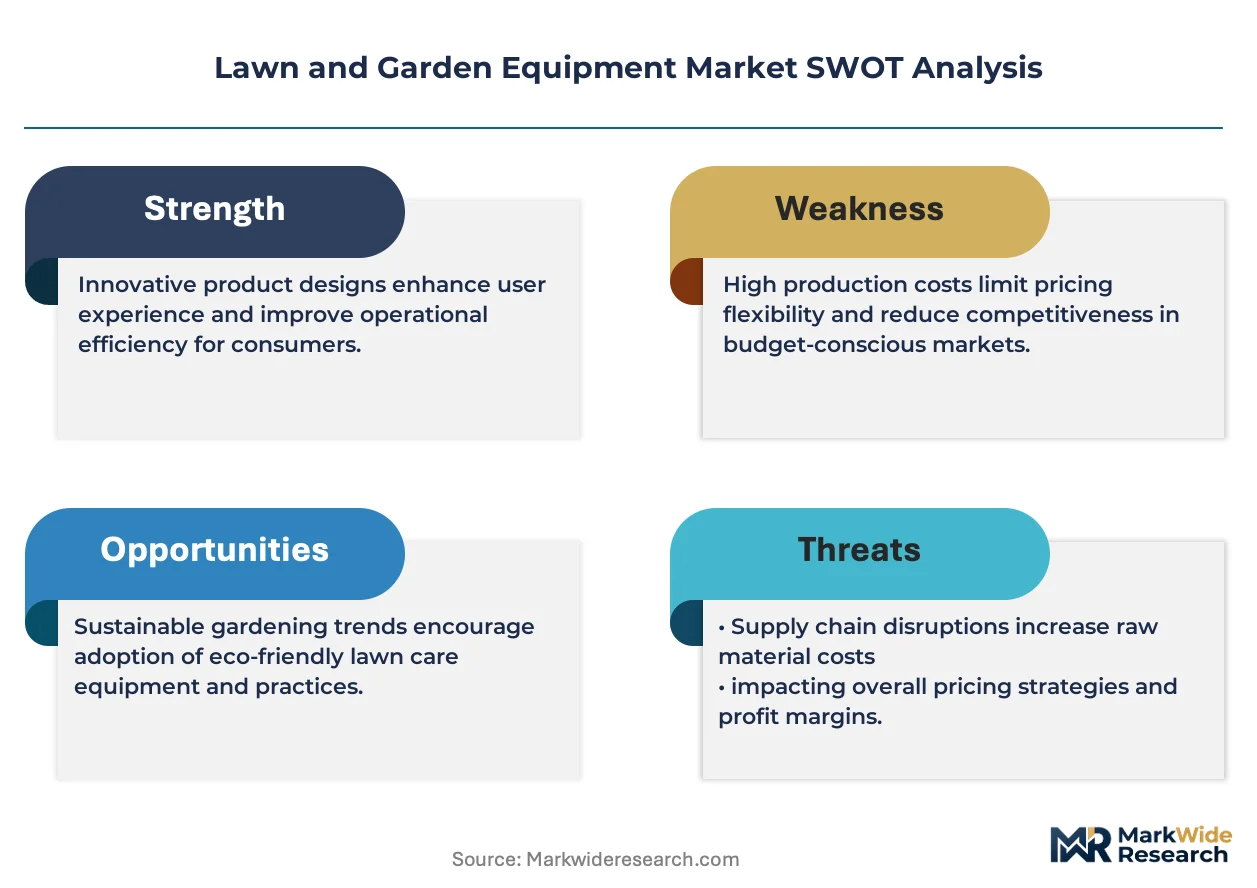
Battery chemistry improvements and EPA Phase 3 emission standards are converging to compress the gasoline equipment replacement cycle while redistributing margin capture toward cell suppliers and motor controller specialists.
Growth Catalysts
- California Air Resources Board zero-emission mandates:Landscaping fleets in the state face compliance-driven replacement cycles that accelerate electric platform procurement ahead of natural wear-out schedules.
- Lithium-ion energy density gains:Professional handheld categories now achieve runtime parity with gasoline equivalents, opening cordless penetration in commercial trimming and blowing applications.
- Urban greening programs:Municipalities in Germany, China, and the United States are expanding park maintenance budgets and specifying low-emission equipment in public tenders.
Market Restraints
- Battery cell supply concentration:Cylindrical and prismatic lithium-ion production clusters in East Asia create input vulnerability for Western equipment assemblers.
- Catalytic aftertreatment cost inflation:Small spark-ignition engine manufacturers face margin compression from precious metal loading requirements under tightened EPA limits.
- Gasoline aftermarket parts profitability:Established dealer networks resist platform transitions that erode high-margin service and replacement component revenue streams.
Strategic Opportunities
- Autonomous mowing connectivity:Robotic systems with fleet management software are expanding into estate maintenance and golf course applications previously served by ride-on units.
- India urban landscaping:Metro rail corridor development and smart city initiatives in Bangalore, Hyderabad, and Pune are creating first-time demand for mechanized turf equipment.
- Battery recycling infrastructure:Closed-loop cell recovery partnerships can secure supply and differentiate positioning as extended producer responsibility frameworks emerge.
Industry Challenges
- Power electronics integration:Motor controller and battery management system design capabilities are scarce among legacy mechanical engineering teams, requiring external recruitment or acquisition.
- Charger network density gaps:Commercial landscaping crews operating across dispersed job sites lack reliable fast-charging infrastructure, constraining daily productivity metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lawn and Garden Equipment Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lawn Mowers, Trimmers, Hedge Cutters, Blowers End User: Residential, Commercial, Landscaping Services, Municipalities Power Source: Gasoline, Electric, Cordless, Solar Distribution Channel: Online Retail, Home Improvement Stores, Specialty Stores, Direct Sales |
| Companies Covered | Deere & Company, Husqvarna Group, The Toro Company, Stanley Black & Decker, Kubota Corporation, MTD Products, Honda Motor Co., Ltd., Briggs & Stratton Corporation, STIHL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lawn and Garden Equipment Market Emerging Trajectories
Electrification architectures are redefining competitive advantage away from engine displacement metrics toward software-defined power management and connected fleet optimization capabilities.
Brushless DC motor systems paired with solid-state battery packs are expanding into professional-grade chainsaws and hedge trimmers previously dominated by two-stroke gasoline engines. Landscaping contractors in the United States and Germany are adopting these platforms for noise-restricted urban contracts. The technology is expanding into premium residential segments as runtime specifications reach 60-minute thresholds.
EPA Phase 3 emission standards are tightening hydrocarbon and nitrogen oxide limits for small spark-ignition engines below 25 horsepower. Equipment manufacturers must redesign combustion architectures or abandon gasoline platforms entirely for affected categories. California's Air Resources Board is advancing complementary zero-emission equipment mandates that compress commercial fleet transition timelines.
Commercial buyers are consolidating vendor relationships around full-platform suppliers capable of delivering interoperable batteries across mowers, handheld tools, and utility vehicles. Independent dealers and rental houses are losing share to direct fleet procurement arrangements with national landscaping services. This concentration is most visible in the United States where ten largest commercial maintenance companies control expanding equipment specification authority.
Lawn and Garden Equipment Market Segmentation
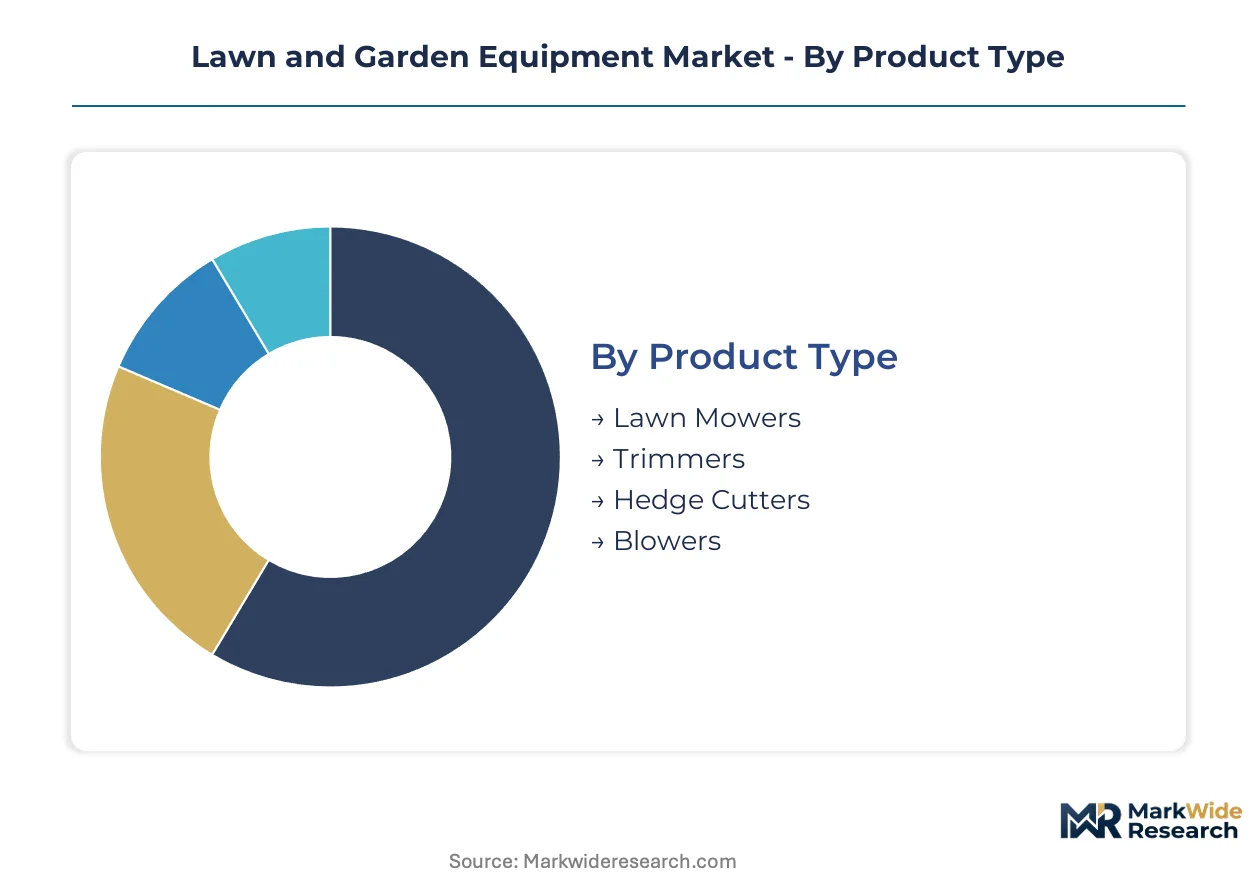
Segmentation in lawn and garden equipment reveals how electrification is fragmenting traditional gasoline-dominated categories while concentrating procurement authority among large commercial operators. Understanding these splits exposes where margin capture is shifting from mechanical engineering toward battery chemistry and power electronics.
Product Type:
Volume concentrates in established cutting platforms while premium growth clusters around precision trimming and debris management systems.
- Lawn Mowers:Ride-on units span 30-72 inch cutting widths for estate and commercial turf maintenance, with demand concentrating in the United States and Germany as urban greening programs expand park maintenance budgets. Gasoline engines retain installed-base profitability though battery platforms are compressing replacement cycles in California compliance zones.
- Trimmers:Professional handheld categories achieving runtime parity with gasoline equivalents through lithium-ion energy density gains, opening cordless penetration in commercial trimming applications previously resistant to electrification. Landscaping contractors in noise-restricted urban contracts drive specification shifts.
- Hedge Cutters:Brushless DC motor systems paired with solid-state battery packs are expanding into professional-grade ornamental pruning equipment.
- Blowers:Cordless platforms displace two-stroke gasoline dominance in debris clearance as runtime specifications reach operational thresholds for commercial crews.
Today's leader: Lawn Mowers. Tomorrow's challenger: Trimmers.
End User:
Procurement authority concentrates with scale operators while residential demand fragments across seasonal replacement patterns.
- Residential:Seasonal replacement cycles dominated by gasoline equipment heritage, though cordless handheld adoption accelerates in premium suburban segments as battery interoperability improves across tool platforms.
- Commercial:Fleet procurement consolidating around full-platform suppliers capable of delivering interoperable batteries across mowers, handheld tools, and utility vehicles.
- Landscaping Services:Repositioning procurement toward battery-powered fleets ahead of natural wear-out schedules, with California zero-emission mandates compressing transition timelines and creating compliance-driven replacement cycles distinct from seasonal residential patterns.
- Municipalities:Public tenders in Germany, China, and the United States specifying low-emission equipment as urban greening programs expand park maintenance budgets and mechanize previously manual turf management.
Landscaping Services is gaining specification authority fastest as ten largest commercial maintenance companies consolidate vendor relationships.
Power Source:
Margin capture is redistributing from engine assemblers toward cell suppliers and motor controller specialists as chemistry improvements displace established fuel systems.
- Gasoline:Small spark-ignition engines face margin compression from precious metal loading requirements under tightened EPA Phase 3 emission standards, with Briggs & Stratton and Honda redirecting R&D toward electrified architectures or advanced catalytic aftertreatment.
- Electric:Corded platforms retain niche positioning in stationary residential applications where runtime certainty outweighs mobility requirements.
- Cordless:Professional handheld categories now achieve runtime parity with gasoline equivalents, representing the steepest expansion trajectory as lithium-ion energy density improvements open commercial trimming and blowing applications.
- Solar:Emerging integration in estate-scale autonomous mowing systems where panel-embedded charging stations extend operational autonomy.
Gasoline retains aftermarket parts profitability. Cordless is climbing the fastest.
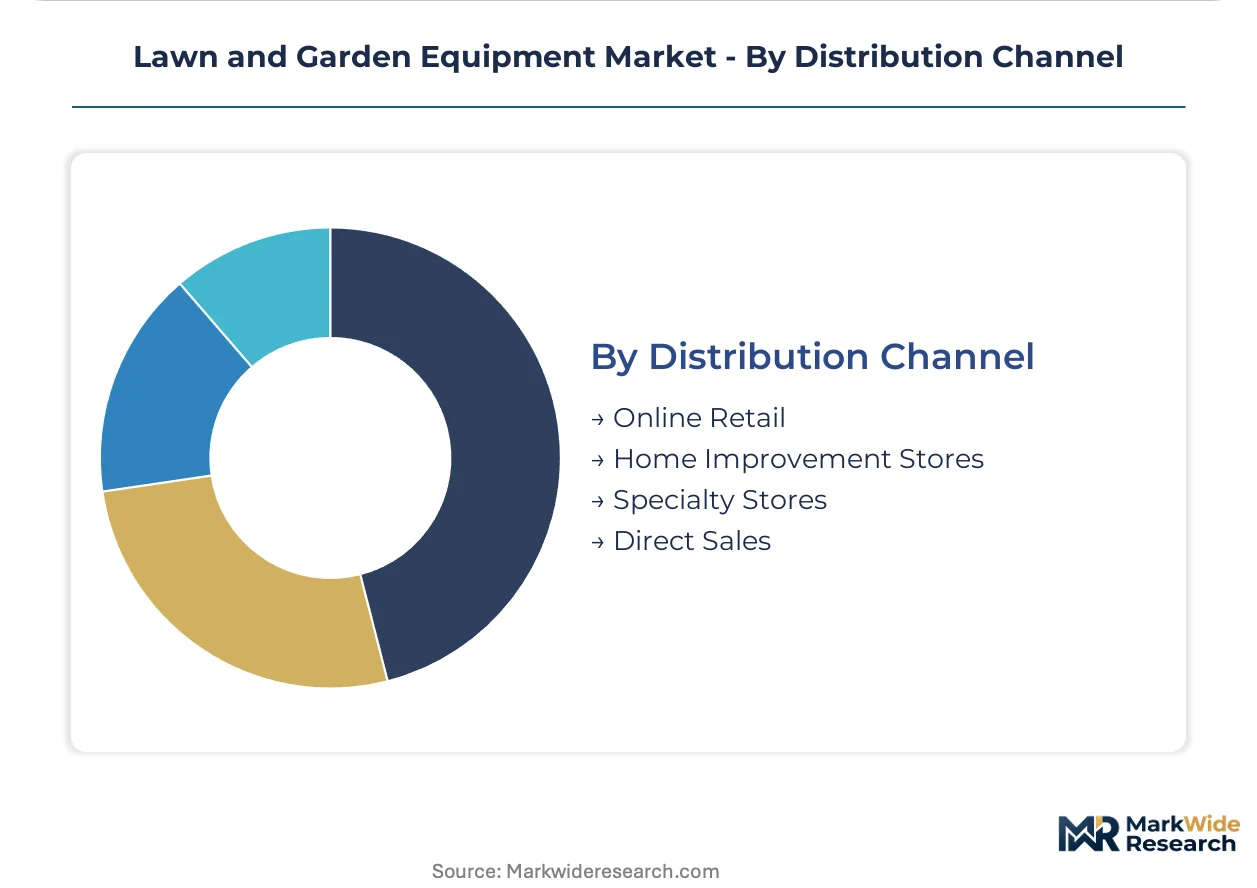
Distribution Channel:
Channel power shifts from independent dealer networks toward direct fleet arrangements as procurement concentrates with national operators.
- Online Retail:Battery platform accessories and replacement cells migrate toward digital channels as interoperability standards reduce specification complexity for residential buyers.
- Home Improvement Stores:Volume concentration for residential replacement cycles, with seasonal merchandising driving cordless handheld attachment rates.
- Specialty Stores:Independent dealers losing share to direct fleet procurement arrangements, resisting platform transitions that erode high-margin service and replacement component revenue streams.
- Direct Sales:National landscaping services consolidating vendor relationships around full-platform suppliers capable of delivering interoperable batteries across equipment categories.
Direct Sales is capturing commercial specification authority. Online Retail is expanding fastest in residential accessories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as emission compliance costs diverge across jurisdictions. Equipment assemblers are relocating production toward regions with battery supply chain density while maintaining distribution proximity to end markets.
United States
Commercial landscaping fleets drive specification authority through consolidated procurement power. EPA Phase 3 emission standards tighten small spark-ignition engine limits while California Air Resources Board zero-emission mandates compress replacement cycles in the largest state market. Equipment demand concentrates in suburban corridors of Texas, Florida, and the Northeast where urban greening programs expand park maintenance budgets.
Germany
Estate maintenance and municipal turf management sustain premium equipment demand across Bavaria and Baden-Württemberg. REACH chemical regulations and EU Green Deal carbon pricing accelerate electric platform adoption in professional handheld categories. Industrial clusters around Stuttgart and Munich host precision motor controller specialists supplying brushless DC systems to equipment assemblers.
China
Urban greening initiatives in megacities like Shanghai and Shenzhen are mechanizing previously manual park maintenance operations. MIIT battery safety standards and dual carbon goals redirect domestic manufacturing toward lithium-ion platforms for export markets. Yangtze River Delta production bases supply cylindrical cells to Western equipment brands seeking supply diversification.
India
Metro rail corridor development in Bangalore, Hyderabad, and Pune creates first-time demand for mechanized turf equipment among municipal contractors. BIS certification requirements for electrical safety and DGFT import tariffs on gasoline engines tilt procurement toward domestic electric platform assembly. Smart city initiatives in Gujarat and Maharashtra specify low-emission maintenance equipment in public tenders.
Japan
Compact precision equipment demand persists in dense urban gardening applications across Kanto and Kansai regions. METI energy efficiency standards and JIS certification requirements favor domestic manufacturers with integrated battery management capabilities. Nagoya-area industrial corridors maintain specialty motor winding capacity for professional-grade handheld tools.
Lawn and Garden Equipment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-platform suppliers capturing commercial fleet consolidation while component specialists dominate battery chemistry and power electronics. Market structure exhibits tiered concentration: a handful of integrated OEMs control autonomous and ride-on categories, numerous regional assemblers compete in gasoline handheld segments, and cell suppliers capture margin in cordless transitions. Three archetypes define positioning: heritage engine manufacturers defending aftermarket parts revenue, battery-native entrants without legacy gasoline exposure, and precision agriculture crossover players leveraging autonomous software stacks. Dominant competitive moves include vertical integration into cell supply partnerships and direct fleet procurement arrangements that bypass traditional dealer networks.
Among heritage equipment manufacturers, Deere & Company, Husqvarna Group, and STIHL occupy positions representing distinct strategic responses to electrification pressure. Deere exemplifies the precision agriculture crossover archetype leveraging autonomous software heritage into commercial mowing applications. Husqvarna represents European estate-focused positioning sustained through robotic connectivity investments. STIHL anchors the professional battery ecosystem transition, shifting from two-stroke gasoline dominance toward cordless handheld platforms. These three illustrate how mechanical engineering heritage translates differently into electrified competitive positioning.
| Leading Market Players |
|---|
| Deere & Company |
| Husqvarna Group |
| The Toro Company |
| Stanley Black & Decker |
| Kubota Corporation |
| MTD Products |
| Honda Motor Co., Ltd. |
| Briggs & Stratton Corporation |
| STIHL |
| Others |
Supply Flow & Price Mechanics
Backward integration into cylindrical lithium-ion cell production anchors pricing power for Western equipment assemblers confronting East Asian supply concentration. This upstream control over battery chemistry insulates margin capture from nickel and cobalt price volatility while compressing procurement timelines for professional-grade cordless platforms.
Pricing Analysis
Distributor margin layers in commercial landscaping channels absorb 15-25 points before fleet procurement, compressing as direct sales arrangements consolidate around full-platform suppliers. Three-tier pricing structure across premium autonomous systems, standard ride-on units, and economy handheld tools reflects runtime specifications and battery interoperability rather than engine displacement. Cost compression in gasoline handheld tiers is intensifying because catalytic aftertreatment requirements under EPA Phase 3 load precious metals into bill-of-materials. Municipal buyers exhibit highest price sensitivity due to public tender transparency, while estate maintenance contractors prioritize runtime certainty over unit economics.
Supply Chain Analysis
Trans-Pacific container rates and inland trucking costs from Yangtze River Delta ports to Midwest distribution centers feed directly into landed cost structures for battery-powered equipment. Cylindrical cell production clusters in China, South Korea, and Japan supply Western assemblers, with brushless DC motor controllers sourcing from Stuttgart and Munich industrial corridors. Single-source vulnerability concentrates in prismatic cell formats for ride-on mower packs. Distribution runs through direct fleet arrangements with national landscaping services, bypassing independent dealer networks that historically captured aftermarket parts revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lawn and garden equipment market reads as a late-cycle quality story where landscaping services procurement is shifting toward premium battery platforms with interoperable ecosystems and fleet management software.
For Market Incumbents: Acquire motor controller design capabilities to address power electronics integration scarcity among legacy mechanical engineering teams. Secure captive lithium-ion cell supply through closed-loop recycling partnerships before extended producer responsibility frameworks mature. Defend against battery-native entrants by embedding software-defined power management into commercial mower platforms. For New Entrants and Emerging Players: Begin with municipal contractors in Indian smart city corridors where BIS certification requirements and DGFT tariffs on gasoline engines tilt procurement toward domestic electric assembly. Target noise-restricted urban contracts in German metropolitan regions where REACH regulations and EU Green Deal carbon pricing accelerate cordless specification. Establish direct rental house partnerships rather than dealer network penetration. For Investors and Strategic Acquirers: Roll-up economics work for precision motor controller specialists because equipment assemblers lack in-house power electronics design capabilities and must source externally. Long-term viability hinges on battery chemistry IP and charger network density rather than mechanical manufacturing scale. Monitor California Air Resources Board mandate expansion into additional states as inflection signal for compliance-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cylindrical cell allocation from Yangtze River Delta producers for cordless platform expansion. |
| Autonomous Mowing Connectivity | Captures estate and golf course applications through fleet management software integration. |
| Closed-Loop Recycling Partnership | Positions for extended producer responsibility frameworks while securing nickel and cobalt supply. |
| Direct Fleet Procurement Arrangement | Bypasses independent dealer resistance to platform transitions eroding aftermarket parts revenue. |
| Power Electronics Acquisition | Addresses motor controller and battery management system design capability gaps. |
Methodological Framework
Multiple input streams — equipment procurement directors at national landscaping services, motor controller specialists in German industrial clusters, battery cell suppliers in East Asian production bases, and regulatory affairs leads at engine manufacturers — were reconciled against customs trade data, EPA emission certification filings, and municipal tender documentation. Primary interviews with aftermarket service heads and rental house operators validated replacement cycle assumptions. Bottom-up unit economics and top-down market sizing approaches were cross-referenced for triangulation.
Historical shipment data was cross-referenced against panel input from commercial fleet operators to build the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, power source architecture, and regional regulatory cluster. CAGRs were derived from replacement cycle compression analysis and electrification penetration curves. Industry-specific forecast inputs incorporated lithium-ion energy density improvement trajectories and California zero-emission mandate compliance timelines.
Several conditions sit outside the modeled scope, including potential relaxation of EPA Phase 3 standards, breakthrough solid-state battery commercialization ahead of chemistry roadmaps, and trade policy shifts affecting cylindrical cell tariffs. Forecasts reflect assumptions about charger network density development and battery recycling infrastructure maturation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
Global Lawn Mowers Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Agriculture Equipment Market