
 China Haying and Forage Machinery Market | 2026-2036
China Haying and Forage Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
China Haying and Forage Machinery Market Outlook
Dairy cooperative expansion across northern China is repositioning equipment procurement toward high-capacity baler and mower systems. Deere & Company leverages its precision agriculture technology to compete in premium segments. Zoomlion anchors its position through domestic manufacturing scale and extensive provincial distribution networks.
Haying and forage machinery encompasses mechanical systems engineered to cut, condition, rake, bale, and handle forage crops with working widths typically spanning 1.5 to 15 meters and throughput rates calibrated to match regional field sizes. These machines serve the primary commercial purpose of converting standing grass, legumes, and cereal residues into storable hay, silage, or feedstock for livestock operations. Mowers and balers currently occupy the largest installed base across Chinese provinces, while integrated technology configurations are gaining traction among agricultural co-operatives seeking labor reduction. Rotary systems differentiate through higher throughput in dense crop conditions, though conventional platforms sustain significant share among price-sensitive farmer segments.
China's Ministry of Industry and Information Technology sets emission and fuel-efficiency benchmarks that constrain engine specifications for domestically sold equipment, while the national GB standards govern structural safety and operational performance testing. The Ministry of Agriculture and Rural Affairs subsidizes mechanization upgrades through provincial implementation programs that steer purchasing decisions toward certified models. Stakeholders must monitor evolving subsidy eligibility criteria and engine tier transitions to align product portfolios with procurement incentives.
Market Dynamics
Inner Mongolia's dairy cooperatives are consolidating landholdings and demanding higher-capacity equipment, compressing procurement timelines and reshaping manufacturer priorities toward integrated haying systems.
Growth Catalysts
- MIIT Fuel-Efficiency Standards:Tightening engine benchmarks under China's Ministry of Industry and Information Technology are accelerating Tier 4 engine adoption, forcing domestic manufacturers to upgrade powertrain portfolios.
- Shandong Manufacturing Cluster:Concentrated component supply and assembly infrastructure in Shandong Province reduce logistics costs and enable rapid model iteration for regional equipment variants.
- Dairy Cooperative Mechanization:Northern China's livestock operations are expanding silage and hay production, pulling demand toward automated mower-conditioner-baler combinations.
Market Restraints
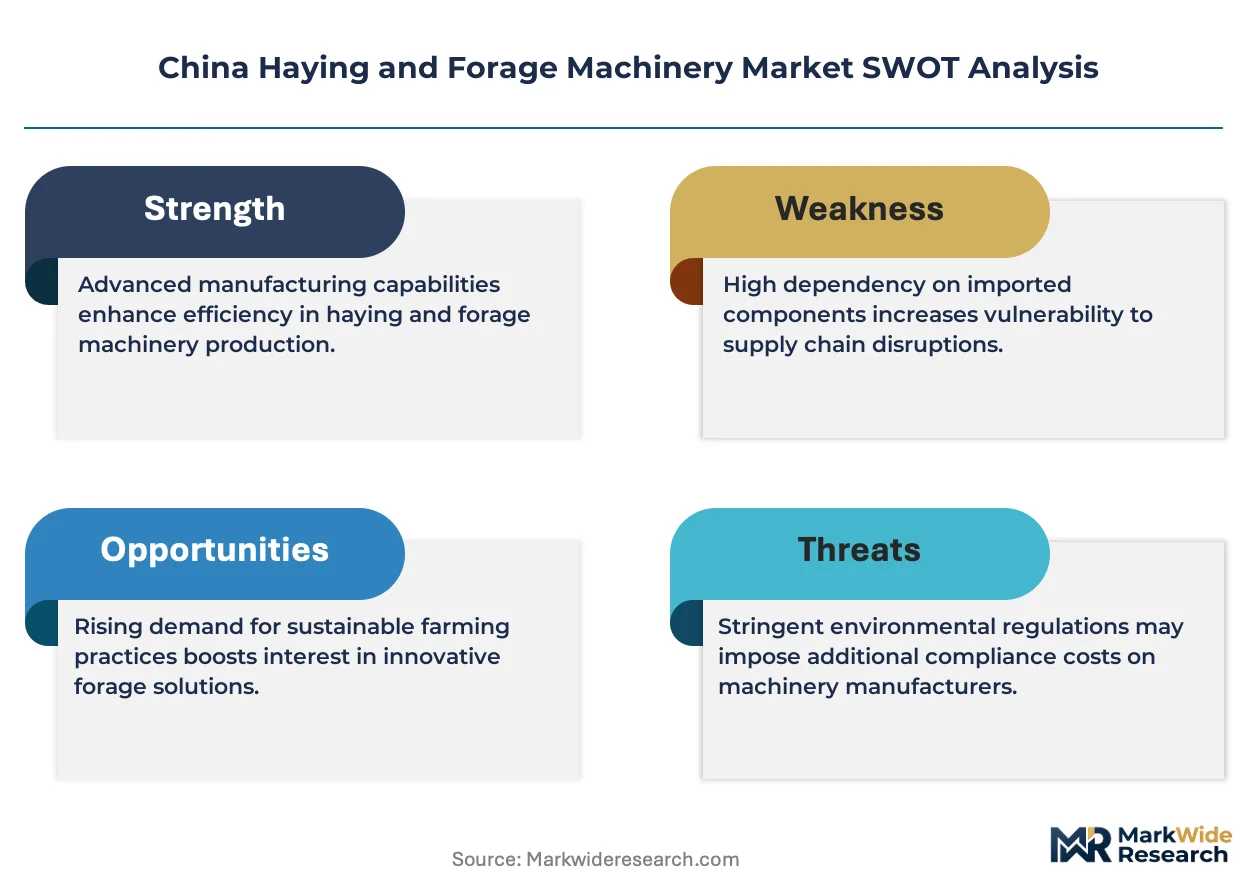
- Steel Price Volatility:Frame and cutting-component costs fluctuate with domestic steel input prices, compressing margin visibility for equipment assemblers.
- Import Dependency for Precision Hydraulics:High-pressure hydraulic systems for large balers concentrate supply among German and Japanese component suppliers, exposing procurement to currency and shipping risk.
- Smallholder Land Fragmentation:Average field sizes below 2 hectares in southern provinces limit payback periods for equipment above 2-meter working width.
Strategic Opportunities
- Xinjiang Pasture Expansion:State-funded grassland rehabilitation programs in western provinces are opening greenfield demand for self-propelled windrowers and high-density balers.
- Telematics-Equipment Convergence:Integration of yield mapping and fuel monitoring into baler control systems creates service-revenue streams beyond hardware sales.
- Rural Revitalization Subsidies:Ministry of Agriculture and Rural Affairs mechanization grants steer purchasing toward certified domestic models, favoring localized production footprints.
Industry Challenges
- Skilled Technician Scarcity:Hydraulic diagnostics and precision calibration expertise lag equipment complexity in county-level service networks.
- GB Certification Timelines:Structural safety and emissions testing under national GB standards extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Haying and Forage Machinery Market |
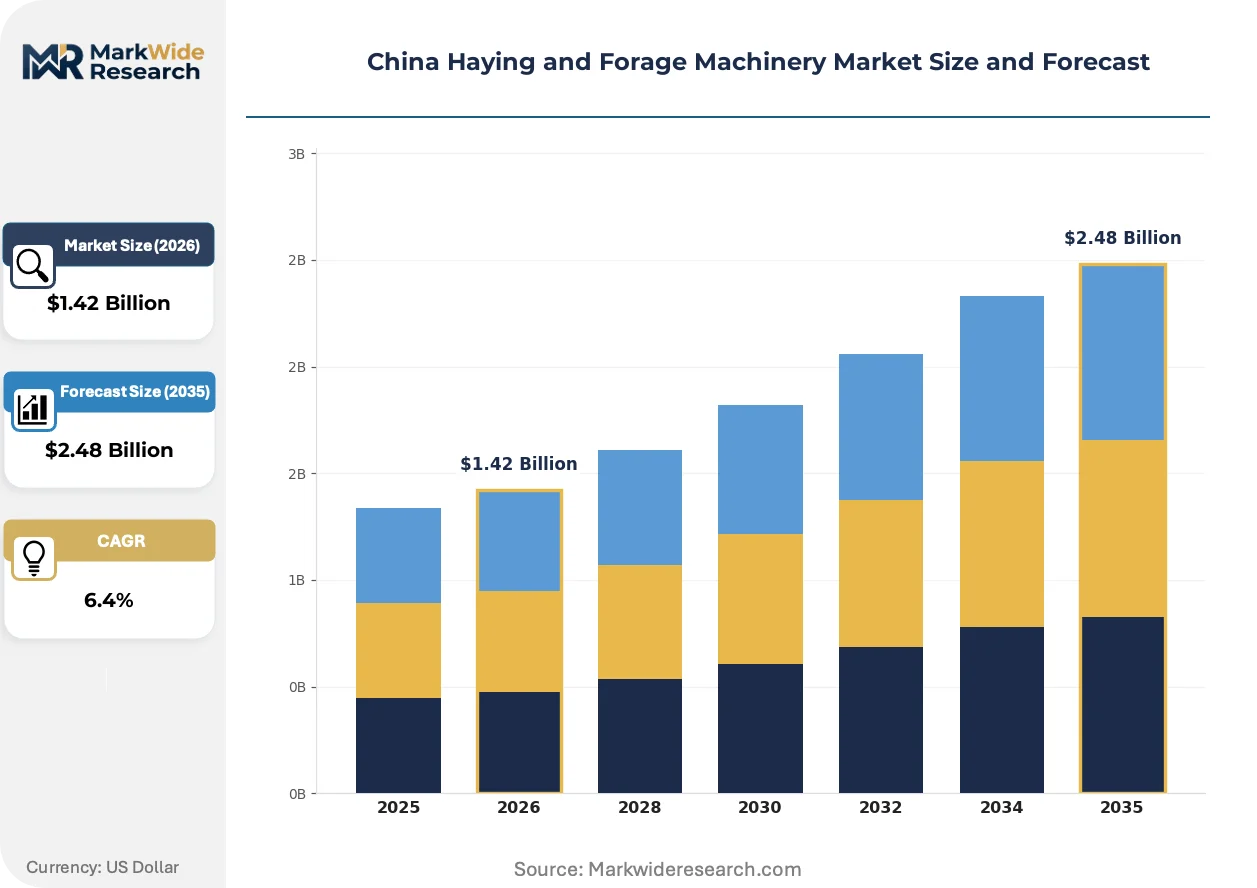
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mowers, Tedders, Rakes, Balers Technology: Conventional, Rotary, Disc, Integrated End User: Farmers, Agricultural Co-operatives, Contractors, Research Institutions Application: Grass Cutting, Haymaking, Silage Production, Crop Management |
| Companies Covered | AGCO Corporation, Foton Lovol, Deere & Company, Zoomlion, YTO Group, CNH Industrial, PÖTTINGER Landtechnik GmbH, Henan Wisely Machinery Equipment Co., Ltd, CLAAS KGaA mbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Haying and Forage Machinery Market Strategic Shifts
Automation density is climbing across haying workflows as labor costs rise and cooperative buyers consolidate purchasing power. Three developments are restructuring competitive requirements.
Variable-chamber balers with real-time density sensors are rewriting harvest logistics for Inner Mongolia's 10,000-head dairy operations. These systems enable consistent bale weights for transport optimization. Large cooperatives are specifying sensor-equipped models in procurement tenders. The technology is compressing seasonal labor windows and favoring manufacturers with integrated control-system expertise.
China's GB standards for agricultural machinery safety and MIIT emission benchmarks are tightening in parallel, creating dual-compliance pressure on engine and frame design. Domestic manufacturers must synchronize powertrain upgrades with structural testing protocols. Premium baler and self-propelled mower segments face the steepest certification burden, pushing some regional assemblers toward simpler, lower-horsepower configurations.
Cooperative procurement committees are consolidating equipment decisions across multiple member farms, replacing individual farmer purchases with volume tenders specifying service packages and parts availability. This buyer concentration is squeezing traditional county-level dealers and favoring manufacturers with direct provincial sales teams. Shandong and Hebei provinces exhibit the most advanced tender-based purchasing structures.
China Haying and Forage Machinery Market Segmentation
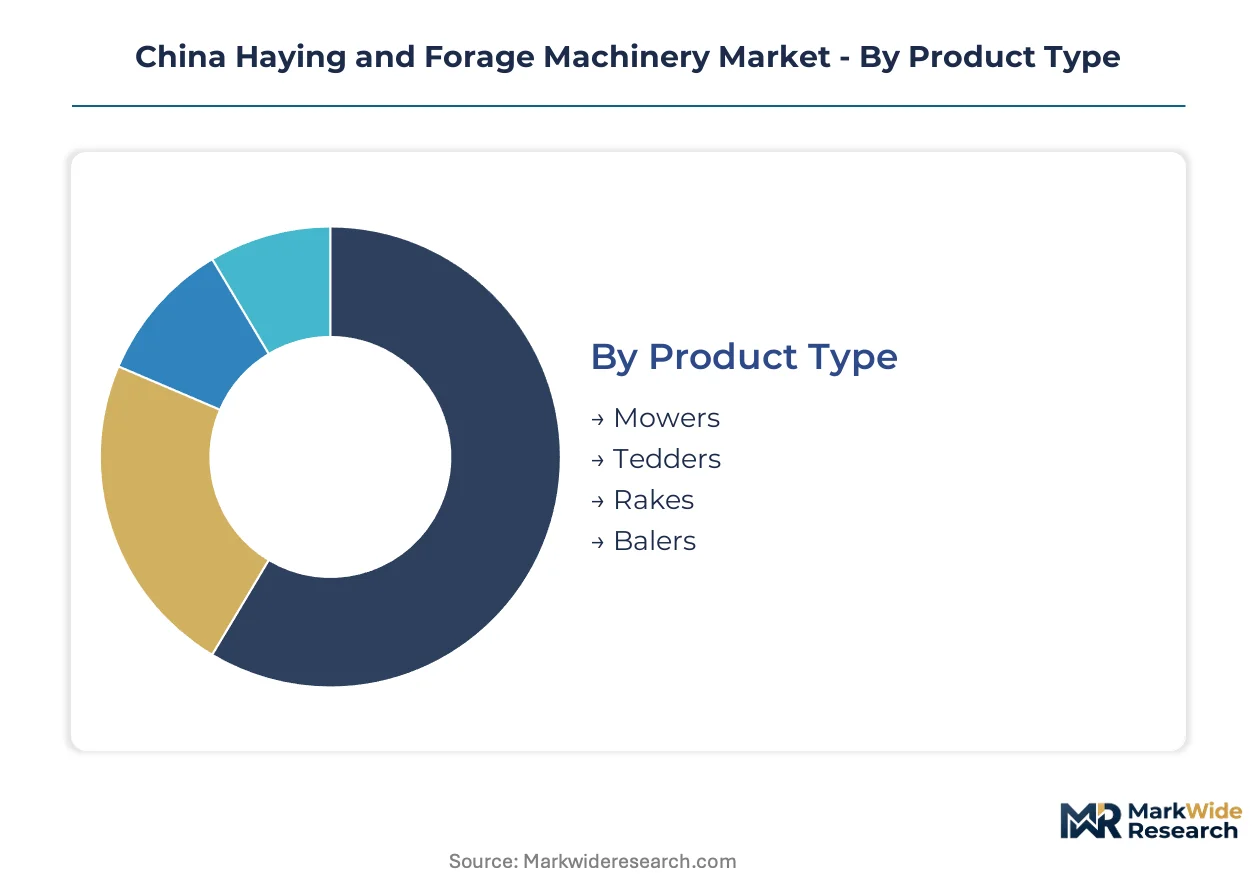
Equipment buyers across China's haying and forage machinery market exhibit sharply divergent procurement patterns based on operational scale, subsidy eligibility, and regional field conditions. Understanding these divides enables manufacturers to align product portfolios with specific buyer economics rather than treating demand as uniform.
Product Type:
Procurement scale separates buyers in this category, with cooperatives favoring integrated systems while individual farmers prioritize standalone units.
- Mowers:Rotary and disc configurations dominate northern pasture operations, with working widths from 1.5 to 4.5 meters calibrated to Inner Mongolia's consolidated dairy holdings. Demand concentrates in Shandong's manufacturing cluster where component density enables rapid model iteration for regional crop conditions.
- Balers:Variable-chamber designs with real-time density sensors are displacing fixed-chamber units across 10,000-head dairy cooperatives, enabling consistent bale weights for transport optimization. Inner Mongolia's procurement committees specify sensor-equipped models in volume tenders, compressing seasonal labor windows.
- Tedders:Rotary tedders with six-rotor configurations serve haymaking operations in Hebei and Shandong provinces, accelerating moisture reduction in humid summer conditions.
- Rakes:Side-delivery and rotary rakes complete windrow formation sequences, with twin-rotor designs gaining traction among contractors serving multiple smallholder clients per season.
Volume sits with balers; growth tilts toward integrated mower-conditioner-baler combinations specified in cooperative tenders.
Technology:
Cost tier and certification burden differentiate technology adoption, with premium segments absorbing compliance costs while price-sensitive buyers remain on simpler platforms.
- Rotary:High-throughput rotary systems utilize flail or drum mechanisms for dense crop conditions, commanding premium pricing in Xinjiang's expanding pasture rehabilitation zones. State-funded grassland programs in western provinces pull demand toward self-propelled rotary windrowers with elevated horsepower ratings.
- Conventional:Sickle-bar and drum mowers sustain significant share among southern smallholders where average field sizes below 2 hectares limit payback periods for advanced equipment. Hebei and Henan provinces exhibit continued reliance on these platforms for cereal residue collection.
- Disc:Disc mowers with hydraulic suspension systems reduce ground pressure in uneven terrain, finding application across northeastern China's rolling pasturelands.
- Integrated:Mower-conditioner-baler combinations with unified control systems are climbing fastest as labor costs rise and cooperative buyers consolidate purchasing power across member farms.
Conventional platforms anchor installed base; integrated configurations are expanding most quickly among procurement committees replacing individual farmer purchases.
End User:
Customer type determines service expectations and financing structures, with cooperatives demanding packaged maintenance while contractors prioritize equipment mobility.
- Agricultural Co-operatives:Northern China's dairy cooperatives are consolidating landholdings and compressing procurement timelines toward integrated haying systems with multi-year service contracts. These buyers specify parts availability and technician response times in tender documentation.
- Farmers:Individual operators in southern provinces purchase through county-level dealers with subsidy guidance, favoring lower-horsepower configurations eligible for Ministry of Agriculture and Rural Affairs mechanization grants.
- Contractors:Mobile service providers cross county lines during peak harvest windows, requiring equipment with rapid field-to-field transport configurations and standardized hydraulic interfaces.
- Research Institutions:Agricultural universities and breeding stations in Beijing and Shandong acquire specialized equipment for forage variety trials and mechanization demonstration projects.
Farmer purchases dominate unit volume; cooperative procurement is gaining share fastest as buyer concentration squeezes traditional dealer networks.
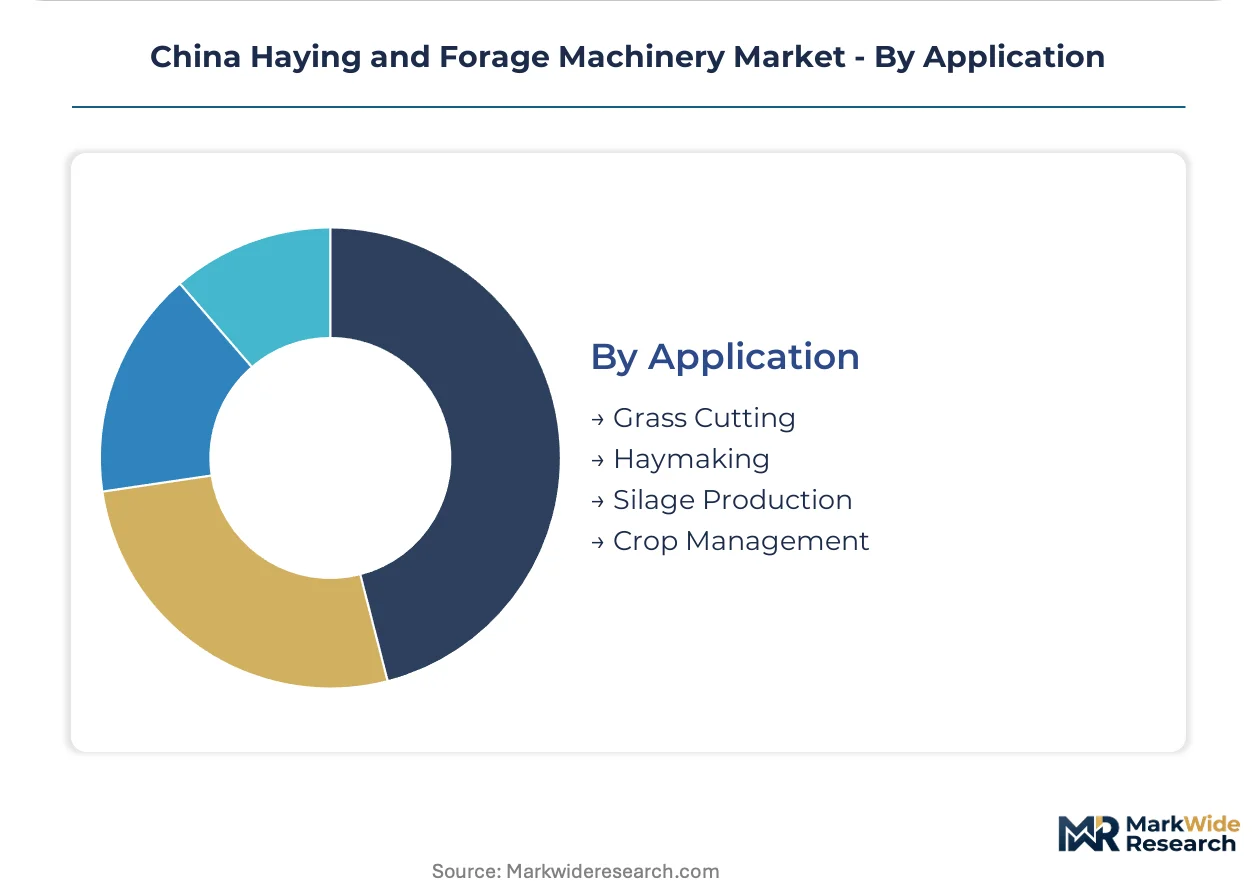
Application:
Seasonal timing and crop value per hectare shape equipment specification, with silage operations justifying higher capital intensity than haymaking.
- Silage Production:Whole-crop cereal and corn silage systems require precision chopping and rapid transport to anaerobic storage, driving specification of self-propelled forage harvesters with kernel processors. Northern dairy cooperatives are expanding silage acreage to secure year-round feed supply.
- Haymaking:Dried forage operations for export and premium domestic markets utilize mower-tedder-rake-baler sequences, with quality-sensitive buyers specifying conditioning rolls for accelerated curing.
- Grass Cutting:Pasture maintenance and seed production operations utilize specialized mowing heights and residue management configurations across Inner Mongolia's state-funded rehabilitation zones.
- Crop Management:Cover crop termination and residue incorporation applications extend machinery utilization beyond traditional forage harvest windows in double-cropping regions.
Haymaking commands current installed base; silage production is climbing the fastest as dairy herd expansion outpaces domestic hay supply growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shandong Free Trade Zone concentrates haying and forage machinery manufacturing through tariff exemptions on imported precision components and streamlined customs processing for exported equipment.
Inner Mongolia
Dairy cooperatives across Hohhot and Hulunbuir are consolidating 10,000-head operations and demanding integrated mower-baler systems. The Ministry of Agriculture and Rural Affairs subsidizes mechanization upgrades through provincial implementation programs. Manufacturing activity clusters in Baotou for steel-frame cutting platforms serving northern pasture zones.
Shandong Province
Rotary mower and variable-chamber baler production scales rapidly to match cooperative procurement timelines. MIIT fuel-efficiency standards tighten engine specifications for domestically sold equipment. Weifang and Jinan anchor component supply chains with rapid model iteration for regional crop conditions.
Xinjiang Uygur Autonomous Region
State-funded grassland rehabilitation programs in Ili and Altay prefectures generate greenfield demand for self-propelled windrowers. The national GB standards govern structural safety testing for high-altitude operating conditions. Urumqi serves as distribution hub for western province equipment deployment.
Hebei Province
Haymaking contractors cross county lines during peak harvest windows with twin-rotor rake configurations. Ministry of Agriculture and Rural Affairs mechanization grants steer purchasing toward certified domestic models. Zhangjiakou and Baoding exhibit the most advanced tender-based purchasing structures among procurement committees.
Henan Province
Cereal residue collection operations sustain demand for conventional sickle-bar mowers among smallholders. Average field sizes below 2 hectares limit payback periods for equipment above 2-meter working width. Zhengzhou machinery dealers coordinate subsidy guidance for individual farmer purchases.
China Haying and Forage Machinery Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium integrated systems concentrating among international technology providers while domestic assemblers capture subsidy-eligible volume tiers. The competitive structure exhibits moderate consolidation at the top and fragmentation among regional fabricators serving county-level dealer networks. Three archetypes dominate: multinational precision-agriculture platforms, state-affiliated manufacturing conglomerates with provincial distribution scale, and specialized component suppliers integrating into complete systems. Capacity expansion and strategic partnerships with dairy cooperatives constitute the dominant competitive moves reshaping procurement relationships.
Among multinational platforms, Deere & Company and CNH Industrial occupy positions emphasizing precision control systems and integrated harvest logistics. Zoomlion anchors the state-affiliated tier through domestic manufacturing scale and extensive provincial distribution networks. PÖTTINGER Landtechnik GmbH exemplifies the European specialist archetype focused on high-density baler technology for large cooperative operations. These three represent contrasting strategic positions without implying specific market share figures or financial performance.
| Leading Market Players |
|---|
| AGCO Corporation |
| Foton Lovol |
| Deere & Company |
| Zoomlion |
| YTO Group |
| CNH Industrial |
| PÖTTINGER Landtechnik GmbH |
| Henan Wisely Machinery Equipment Co., Ltd |
| CLAAS KGaA mbH |
| Others |
Value Chain & Pricing Dynamics
Variable-chamber baler density sensors are compressing seasonal labor windows and simultaneously concentrating procurement power among cooperative buyers, reshaping both manufacturing cost structures and supplier consolidation dynamics across Shandong's component clusters.
Pricing Analysis
Lead-time premiums for MIIT-certified Tier 4 engines command pricing advantages over spot inventory of legacy powertrains awaiting compliance upgrades. Three-tier pricing structure across premium sensor-integrated, standard mechanical, and economy fixed-chamber configurations stratifies by certification grade and after-sales bundling. Price erosion runs through economy tiers as domestic assemblers absorb steel volatility to maintain subsidy eligibility. Individual farmers in Henan exhibit highest price sensitivity; Inner Mongolia cooperatives prioritize service response over unit cost.
Supply Chain Analysis
Dual-sourcing mandates for precision hydraulic systems from German and Japanese suppliers expose assemblers to currency and shipping risk while preventing single-source lock-in. Component supply concentrates in China, Germany, and Japan for high-pressure hydraulics, cutting platforms, and control electronics. Frame fabrication draws from domestic steel mills; engine supply rests on MIIT-licensed domestic and joint-venture manufacturers. Tariff exposure on imported precision components compresses margin visibility. Distribution runs through provincial sales teams serving tender-based procurement committees, displacing traditional county-level dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision hydraulic component scarcity props equipment pricing, constraining volume expansion until domestic alternatives achieve MIIT certification benchmarks.
For Market Incumbents: Lock in cooperative procurement relationships through multi-year service contracts specifying technician response times and parts availability guarantees. Deepen backward integration into cutting-platform steel fabrication to offset volatility in Shandong's component clusters. Threat of emerging domestic sensor-integrated specialists demands accelerated R&D in unified control systems. For New Entrants and Emerging Players: MIIT fuel-efficiency standards in China open a window for Tier 4 engine retrofit specialists serving legacy equipment fleets. Target silage production systems for northern dairy cooperatives where automated mower-conditioner-baler combinations face supply constraints. Go-to-market through direct provincial sales teams bypassing squeezed county dealer networks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by state-affiliated manufacturing conglomerates seeking integrated technology portfolios. Long-term viability hinges on certification compliance capabilities across tightening GB structural safety and MIIT emission benchmarks. Watch for inflection in cooperative tender specifications mandating real-time density sensors as standard equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Component Manufacturing | Reduces import dependency on German and Japanese precision suppliers exposed to currency risk. |
| MIIT Tier 4 Engine Certification Investment | Unlocks subsidy eligibility and cooperative procurement access across northern dairy operations. |
| Telematics Platform Integration | Creates service-revenue streams beyond hardware sales through yield mapping and fuel monitoring. |
| Xinjiang Distribution Hub Establishment | Captures state-funded grassland rehabilitation demand for self-propelled windrowers in western provinces. |
| Cooperative Procurement Committee Partnership | Secures volume tender positioning as buyer concentration squeezes traditional dealer networks. |
Study Parameters
Independent corroboration across equipment procurement directors at dairy cooperatives, MIIT certification engineers, and Shandong component suppliers underwrites the qualitative findings. Primary interviews with haying machinery plant managers, aftermarket service heads, and provincial distribution partners combined secondary validation through MIIT equipment registration databases, Ministry of Agriculture subsidy disbursement records, and GB standards testing protocols. Bottom-up unit shipment estimates triangulated against top-down value projections.
Rate-of-change decomposition across the analysis window separates volume growth from pricing dynamics and mix-shift effects. Segmentation dimensions modeled include product type, technology tier, end-user archetype, and application intensity. CAGRs derived from logistic adoption curves for sensor-integrated equipment and linear extrapolation for conventional platforms. Forecast inputs incorporate MIIT engine tier transition timelines and cooperative land consolidation trajectories.
The model assumes a particular technology adoption path; alternative pathways for variable-chamber sensor integration would alter the outlook if cooperative procurement committees delay specification mandates. Forecasts reflect documented assumptions on subsidy continuation and steel price stabilization. Deviation in MIIT certification timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
India Combine Harvester Market