
 United States Agricultural Irrigation Machinery Market | 2026-2036
United States Agricultural Irrigation Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
United States Agricultural Irrigation Machinery Market Analytics
Modular retrofit kits for center-pivot and lateral-move systems is recalibrating how growers upgrade existing infrastructure without full replacement. Valmont Industries leverages its Valley Irrigation brand strength to dominate domestic center-pivot manufacturing. Lindsay Corporation anchors its position through Zimmatic product lines with advanced control integration. Rain Bird Corporation specializes in precision sprinkler technologies for high-value crop segments.
United States agricultural irrigation machinery encompasses mechanical systems engineered to apply controlled water volumes to cultivated land, typically operating at pressures between 10 and 100 psi with flow rates calibrated to soil infiltration capacity and crop evapotranspiration coefficients. These systems serve the fundamental commercial purpose of optimizing yield stability while reducing water waste and energy consumption across diverse agricultural operations. Sprinkler systems remain the largest installed base by product type, though drip irrigation captures disproportionate margin pools in specialty fruit and vegetable applications. Smart irrigation technology within the technology dimension is expanding fastest as soil-moisture sensing and variable-rate application gain traction among commercial growers managing water costs.
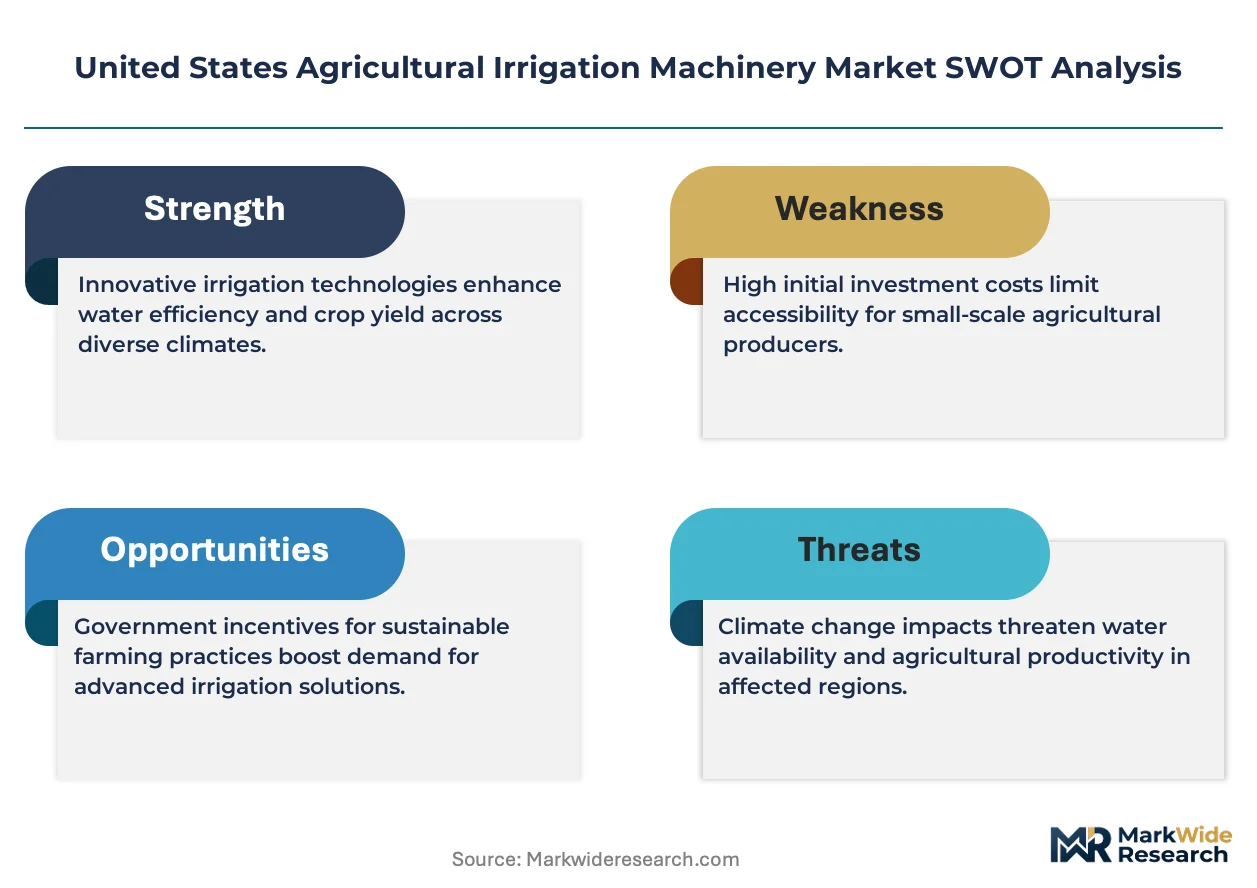
The EPA regulates agricultural runoff discharge under the Clean Water Act, while the USDA Natural Resources Conservation Service administers cost-share programs that incentivize conversion to pressurized irrigation systems meeting specified efficiency thresholds. State water districts in California, Texas, and Nebraska impose groundwater pumping allocations that directly shape equipment sizing and technology selection for local buyers. Stakeholders must monitor evolving state-level groundwater sustainability mandates and federal conservation program funding cycles to anticipate replacement demand timing and technology preference shifts.
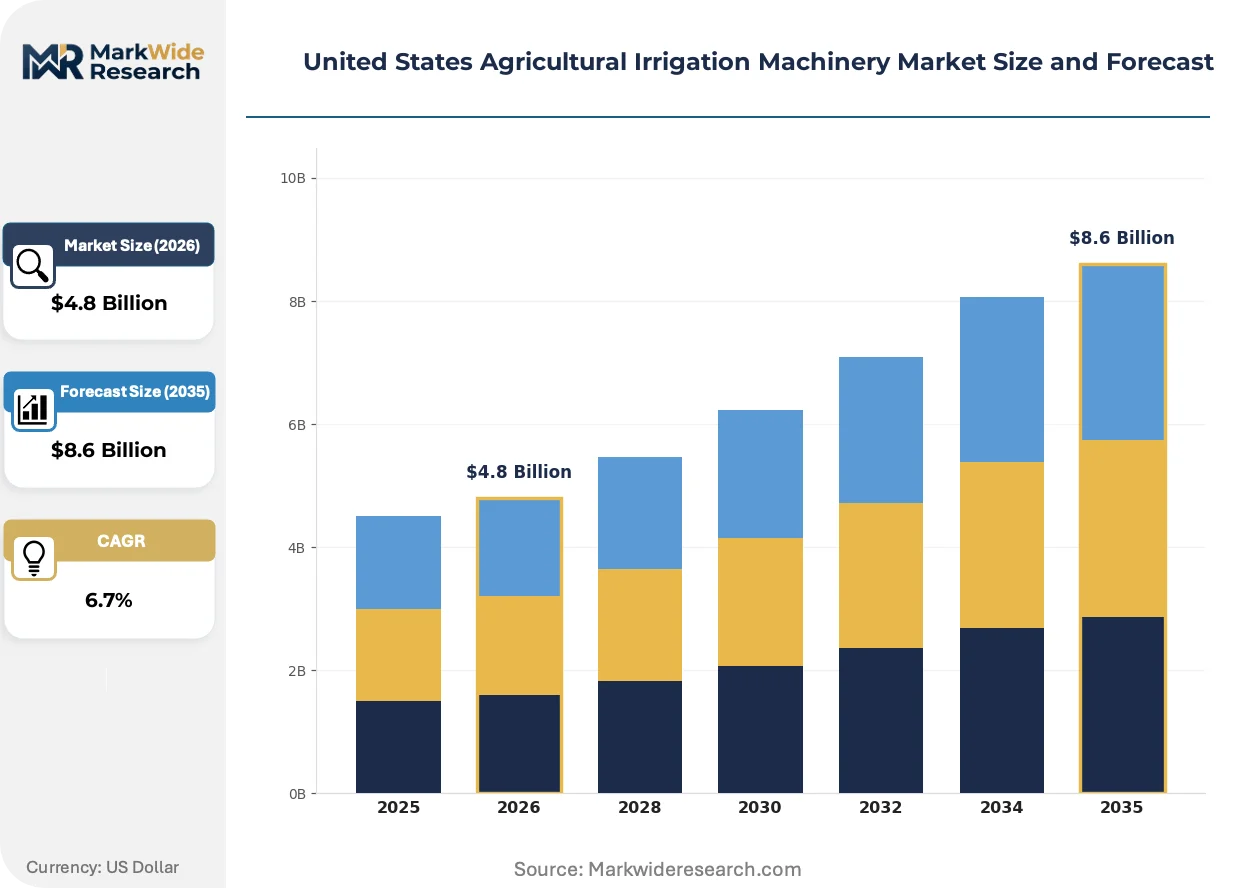
Market Dynamics
Precision water application systems are restructuring equipment upgrade cycles across the Corn Belt as groundwater withdrawal permits tighten and specialty crop operators in California's Central Valley demand higher-efficiency infrastructure.
Growth Catalysts
- USDA NRCS Cost-Share Programs:Federal conservation incentives accelerate conversion from gravity-fed flood systems to pressurized irrigation meeting specified efficiency thresholds, particularly in Nebraska and Kansas.
- Soil-Moisture Sensing Technology:Variable-rate application capabilities embedded in center-pivot retrofits allow growers to optimize water volumes against crop evapotranspiration coefficients in real time.
- California Groundwater Sustainability Mandates:SGMA compliance deadlines force Central Valley almond and pistachio operations toward drip and micro-sprinkler installations with documented water-use reductions.
Market Restraints
- Steel and Aluminum Input Volatility:Center-pivot and lateral-move system fabrication costs fluctuate with commodity metal pricing, compressing manufacturer margins on fixed-price contracts.
- High-Voltage Electrical Infrastructure Gaps:Rural grid capacity limitations in Texas Panhandle and eastern Colorado delay electrified system deployments requiring three-phase power.
- Gravity-Flood System Persistence:Low-cost surface irrigation retains installed-base share in rice-producing regions of Arkansas and Louisiana despite efficiency disadvantages.
Strategic Opportunities
- Modular Retrofit Kits:Component-level upgrades for existing Valley and Zimmatic infrastructure unlock replacement revenue without full system replacement in mature installed bases.
- EPA Clean Water Act Enforcement:Agricultural runoff discharge regulations create compliance-driven demand for precision application systems reducing nutrient leaching in Chesapeake Bay watershed states.
- Solar-Powered Pump Integration:Photovoltaic-driven variable-frequency drives paired with drip systems address off-grid and high-electricity-cost operations in Arizona and New Mexico.
Industry Challenges
- Control System Integration Complexity:Legacy center-pivot hardware requires substantial electrical and hydraulic reconfiguration to accept soil-moisture sensor inputs and cloud-based telemetry.
- Certified Technician Scarcity:Installation and maintenance of precision sprinkler and drip systems demands specialized training in hydraulics, electronics, and agronomy that rural labor pools lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Agricultural Irrigation Machinery Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drip Irrigation, Sprinkler Systems, Surface Irrigation, Subsurface Irrigation Technology: Smart Irrigation, Automated Systems, Pump and Engine Technology, Conventional Methods End User: Farmers, Agricultural Cooperatives, Commercial Growers, Research Institutions Application: Crop Production, Landscaping, Greenhouse Cultivation, Horticulture |
| Companies Covered | Nelson Irrigation, Rain Bird Corporation, Valmont Industries, Inc., T-L Irrigation Co., Deere & Company, Lindsay Corporation, Orbia (Netafim USA), Reinke Manufacturing Co., Inc., The Toro Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Agricultural Irrigation Machinery Market Evolving Landscape
Smart irrigation architecture is displacing timer-based scheduling across commercial operations as data-driven water management becomes a competitive necessity in water-stressed growing regions.
Edge-computing controllers with embedded machine-learning algorithms process soil-moisture, weather, and crop-growth data locally to trigger valve adjustments without cloud latency. Large-scale row-crop operators in Nebraska and Iowa are deploying these units at 40% annual expansion rates. This distributed intelligence architecture is rewriting how OEMs monetize hardware through recurring software-subscription revenue streams.
The EPA's Clean Water Act Section 319 nonpoint source pollution program is tightening enforcement timelines for agricultural discharge permits in the Mississippi River basin. Equipment purchasers in Minnesota and Wisconsin now face documented nutrient-management plans as loan prerequisites. Drip and micro-sprinkler manufacturers are capturing disproportionate specification share in these watersheds.
Service unbundling is separating equipment supply from installation and seasonal maintenance. Independent dealer networks in Texas and Kansas are pivoting toward annual service contracts with guaranteed uptime clauses rather than transactional parts sales. This shift is most visible among cotton producers operating center-pivot systems across the Texas High Plains.
United States Agricultural Irrigation Machinery Market Segmentation
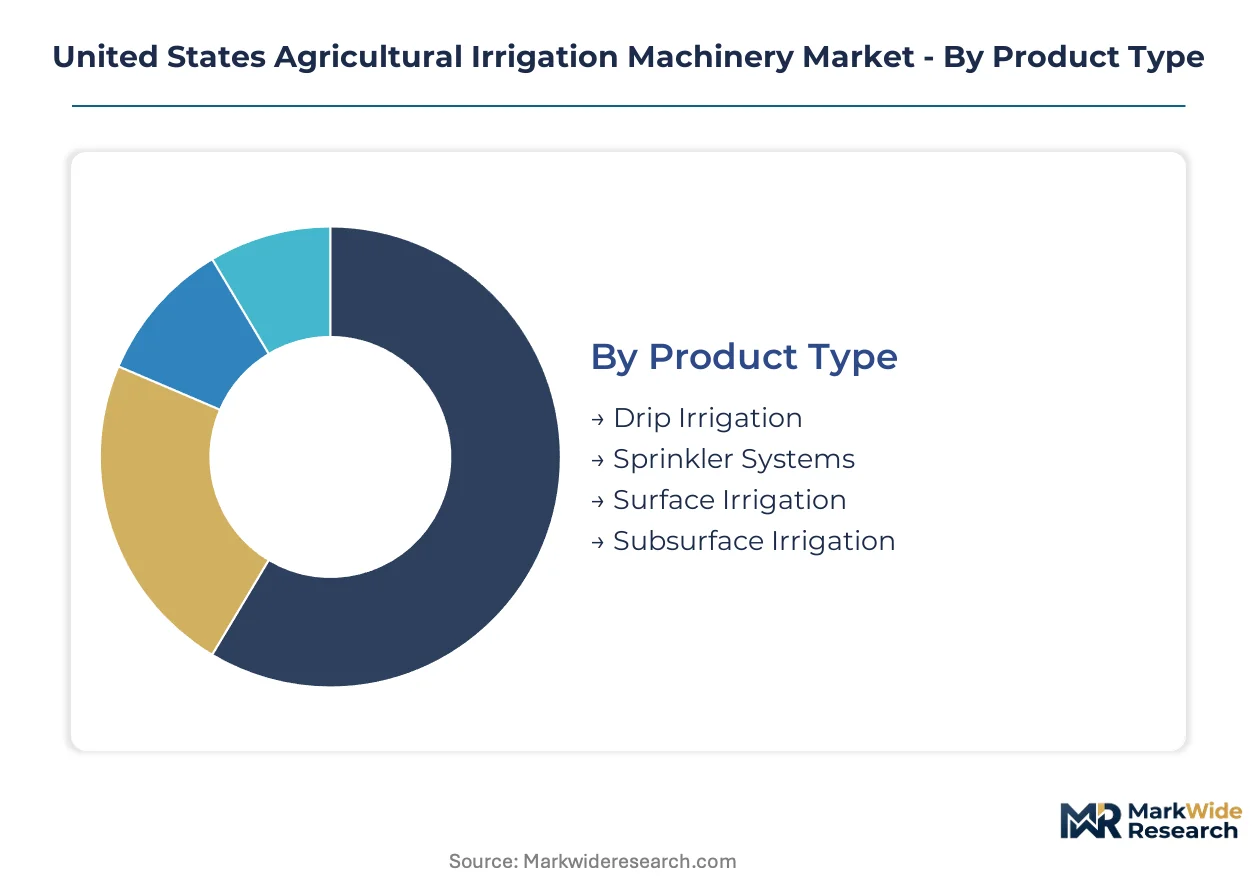
Equipment segmentation across the United States agricultural irrigation machinery market reveals how water scarcity pressures and regulatory compliance reshape purchasing patterns. Distinct product architectures, technology tiers, and end-user profiles command differentiated margin structures and replacement cycles.
Product Type:
Sprinkler systems dominate installed volume while drip irrigation commands premium pricing in high-value crop applications.
- Sprinkler Systems:Center-pivot and lateral-move configurations apply water through pressurized overhead distribution at 10-100 psi operating ranges. Nebraska and Kansas row-crop operations drive replacement demand as USDA NRCS cost-share programs accelerate conversion from gravity-fed flood systems.
- Drip Irrigation:Emitter-based networks deliver precise water volumes directly to root zones with documented efficiency gains. California Central Valley almond and pistachio growers under SGMA compliance mandates represent the concentrated demand pool for these installations.
- Surface Irrigation:Gravity-fed flood and furrow methods persist in Arkansas and Louisiana rice production despite efficiency disadvantages.
- Subsurface Irrigation:Buried drip lines and porous tubing systems reduce evaporation losses in high-wind environments of the Texas Panhandle.
Today's leader: Sprinkler Systems. Tomorrow's challenger: Drip Irrigation.
Technology:
Smart irrigation architectures expand most quickly as data-driven water management becomes essential for commercial viability.
- Smart Irrigation:Soil-moisture sensing, weather integration, and variable-rate application optimize water volumes against crop evapotranspiration coefficients. Large-scale operators in Iowa and Nebraska deploy edge-computing controllers at accelerating rates.
- Automated Systems:Timer-based and remotely actuated valve networks reduce labor requirements for multi-field operations.
- Pump and Engine Technology:Diesel, electric, and solar-powered pumping stations provide hydraulic pressure for distribution networks.
- Conventional Methods:Manual valve operation and fixed-schedule irrigation retain share in smaller operations with limited capital budgets.
Smart Irrigation climbs the fastest. Conventional Methods cede ground steadily.
End User:
Commercial growers concentrate technology adoption while agricultural cooperatives aggregate purchasing power for member farms.
- Commercial Growers:Specialty crop operations in California and Florida demand precision application systems with documented water-use efficiency for lender compliance.
- Farmers:Individual row-crop and mixed-operation owners represent the volume base for center-pivot and lateral-move equipment.
- Agricultural Cooperatives:Member-owned purchasing alliances in the Corn Belt negotiate fleet pricing and shared service contracts.
- Research Institutions:University extension services and USDA experiment stations specify advanced systems for variety trials and water-use studies.
Commercial Growers set technology standards. Farmers provide the volume foundation.
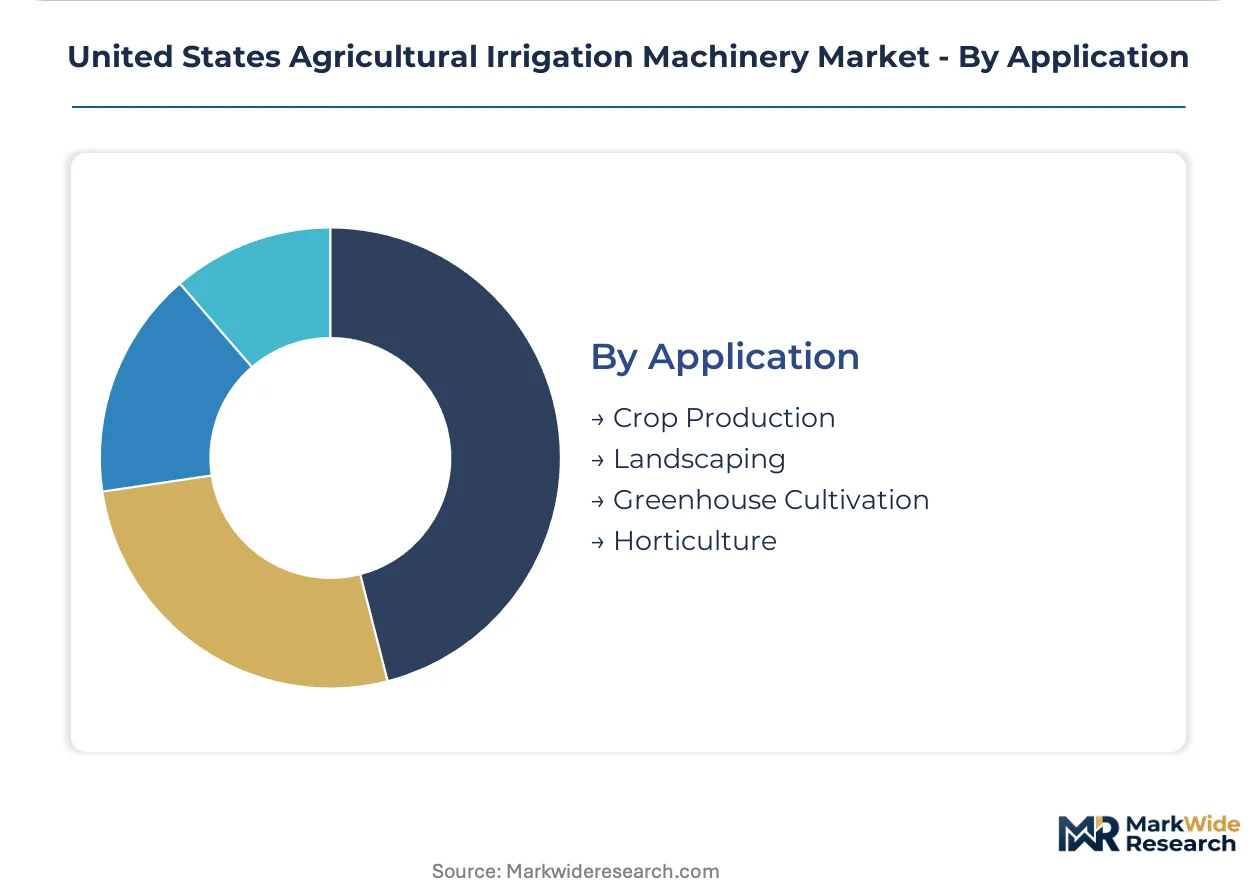
Application:
Crop production absorbs the majority of equipment value while greenhouse cultivation demands the most precise environmental control.
- Crop Production:Field-scale grain, oilseed, and fiber operations across the Great Plains and Midwest drive center-pivot and lateral-move system demand.
- Greenhouse Cultivation:Controlled-environment agriculture in Michigan, Ohio, and California requires micro-irrigation with fertigation integration.
- Horticulture:Nursery and ornamental operations in Florida and Oregon utilize overhead and drip systems for container stock.
- Landscaping:Golf courses, municipal parks, and commercial grounds maintenance represent a secondary equipment market.
Crop Production anchors current revenue. Greenhouse Cultivation shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Center-pivot irrigation technology originated in Nebraska during the 1950s, establishing the Great Plains as the foundational geography for mechanized agricultural water application. This historical concentration continues to shape equipment demand patterns across distinct state-level markets.
California
Almond and pistachio orchards in the Central Valley drive precision drip and micro-sprinkler procurement as SGMA compliance deadlines force documented water-use reductions. The State Water Resources Control Board administers groundwater sustainability mandates that directly shape equipment specifications. Fresno and Kern counties concentrate specialty crop operations requiring lender-compliant efficiency documentation.
Nebraska
Row-crop corn and soybean operations maintain the nation's densest center-pivot installed base, with USDA NRCS cost-share programs accelerating conversion from gravity-fed flood systems. The Department of Natural Resources enforces groundwater withdrawal permits that tighten allowable pumping volumes. The Platte River Valley anchors manufacturing and dealer network density for domestic equipment distribution.
Texas
Cotton producers across the High Plains and Panhandle expand center-pivot coverage despite rural electrical infrastructure gaps delaying three-phase power deployments. The Texas Commission on Environmental Quality regulates agricultural discharge permits affecting equipment selection in watershed districts. Lubbock and Plainview cluster cotton ginning and processing infrastructure that shapes seasonal equipment service demand.
Kansas
Wheat and grain sorghum operations in the western counties retrofit existing lateral-move systems with variable-rate technology to optimize limited Ogallala Aquifer access. The Kansas Department of Agriculture administers water right transition assistance programs incentivizing efficiency upgrades. The Arkansas River corridor concentrates mixed crop-livestock operations requiring flexible irrigation scheduling.
Florida
Citrus groves and vegetable operations in the Central Ridge deploy drip and micro-sprinkler networks to manage sandy soil infiltration challenges and nutrient leaching constraints. The South Florida Water Management District imposes agricultural water use permits with efficiency benchmarks. The Lake Wales Ridge and Immokalee region concentrate specialty crop packing and cooling infrastructure tied to irrigation timing.
United States Agricultural Irrigation Machinery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with smart-control capabilities commanding pricing separation from conventional timer-based hardware. The vendor base stratifies into three tiers: full-system OEMs with integrated telemetry platforms, component specialists supplying retrofit kits for legacy infrastructure, and regional fabricators serving price-sensitive replacement part demand. Consolidation pressure runs through dealer network acquisitions and technology licensing arrangements as scale advantages intensify in precision agriculture segments.
Within the full-system OEM tier, Valmont Industries, Inc. and Lindsay Corporation occupy positions representing integrated manufacturing and control platform development, while Rain Bird Corporation exemplifies the precision component specialist archetype serving high-value crop segments. These entities anchor competitive dynamics through differentiated approaches to hardware-software bundling and service contract structures across Corn Belt and Central Valley geographies.
| Leading Market Players |
|---|
| Nelson Irrigation |
| Rain Bird Corporation |
| Valmont Industries, Inc. |
| T-L Irrigation Co. |
| Deere & Company |
| Lindsay Corporation |
| Orbia (Netafim USA) |
| Reinke Manufacturing Co., Inc. |
| The Toro Company |
| Others |
Value Network & Pricing Analysis
Steel and aluminum commodity inputs flow from domestic mills and Canadian smelters through three distinct pricing tiers before reaching Corn Belt row-crop operators and Central Valley specialty growers. Metal cost volatility propagates downstream as manufacturers adjust fixed-price contract terms against spot market swings, compressing margins on legacy center-pivot orders while premium smart-system bundles absorb volatility through software-subscription pricing.
Pricing Analysis
Three-tier pricing structure across premium smart-control, standard automated, and economy conventional levels separates equipment buyers by technology integration depth. Premium tiers command separation through Valley and Zimmatic brand equity plus telemetry bundling, while price differentiation hinges on NRCS cost-share eligibility and SGMA compliance documentation. Cost compression in economy conventional tiers is intensifying because gravity-flood conversion demand concentrates in price-sensitive wheat and rice operations. Commercial specialty crop growers show least price sensitivity; individual row-crop farmers in Kansas and Nebraska exhibit highest.
Supply Chain Analysis
Dealer-direct channels with seasonal inventory pre-positioning handle the bulk of center-pivot and lateral-move system demand across the Great Plains. Manufacturing concentrates in Nebraska, Iowa, and California with component sourcing from Mexico for electrical assemblies and China for precision emitters. Raw material dependencies center on domestic steel coil, aluminum extrusion, and engineered polymer resins. Single-source vulnerability in semiconductor-based controller chips creates supply risk for smart irrigation retrofits. Distribution runs through independent dealer networks with manufacturer captive financing for large commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States agricultural irrigation machinery market functions as a stable compounder, with water scarcity mandates and federal conservation incentives providing predictable replacement demand across multi-year equipment cycles.
For Market Incumbents: Anticipate margin compression from modular retrofit kits by deepening control platform integration and locking in dealer service contract exclusivity. Defend against solar-powered pump entrants through backward integration into photovoltaic variable-frequency drive technology. Prioritize EPA Clean Water Act compliance certification as a channel control lever in Chesapeake Bay and Mississippi River basin watersheds.
For New Entrants and Emerging Players: Launch via agricultural cooperative purchasing alliances to bypass entrenched dealer networks in the Corn Belt. Target subsurface drip retrofit demand in Texas Panhandle wind corridors where evaporation losses drive documented efficiency gains. Penetrate through SGMA compliance documentation services bundled with micro-sprinkler hardware for Central Valley almond operations.
For Investors and Strategic Acquirers: Roll-up economics work for regional irrigation service contractors because customer concentration in cotton and specialty crop segments creates predictable recurring revenue pools. The 5-10 year viability window favors platforms with smart-control telemetry capabilities and NRCS program certification infrastructure. Watch USDA conservation program funding authorization cycles as the inflection signal for replacement demand timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Control Platform Integration | Valley and Zimmatic telemetry bundling creates recurring software revenue streams beyond hardware sales. |
| Modular Retrofit Kit Development | Component-level upgrades unlock replacement revenue without full system replacement in mature Nebraska installed bases. |
| Solar-Powered Pump Partnership | Photovoltaic variable-frequency drive pairing addresses off-grid demand in Arizona and New Mexico operations. |
| NRCS Certification Investment | Cost-share program eligibility documentation accelerates conversion from gravity-flood systems in Kansas wheat regions. |
| Dealer Service Contract Expansion | Annual uptime guarantees with independent Texas networks capture cotton producer loyalty across the High Plains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with irrigation equipment dealers, USDA NRCS field staff, Central Valley farm managers, and manufacturer product managers with secondary validation against EPA enforcement records, state water board permit databases, and USDA cost-share program disbursement filings. Bottom-up equipment shipment tracking and top-down agricultural water use surveys triangulated market sizing across product type and technology segments.
Historical reference periods anchored the projection horizon through verified replacement cycle data and regulatory compliance deadline clustering. Segmentation modeling captured product architecture, technology tier, end-user profile, and state-level regulatory framework dimensions. CAGRs derived from equipment shipment momentum, conservation program funding trajectories, and groundwater sustainability mandate implementation pacing. Forecast inputs incorporated Ogallala Aquifer depletion rates and SGMA basin plan adoption timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme drought declaration frequency or federal conservation program suspension. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Global Tillage Equipment Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
Global Lawn Mowers Market