
 Global Lawn Mowers Market | 2026-2036
Global Lawn Mowers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lawn Mowers Market Outlook
Lithium-ion battery packs is rebalancing cost structures across electric and robotic lawn mower portfolios. Husqvarna Group leverages its automation software stack to dominate connected robotic systems for estate maintenance. Deere & Company anchors its position through precision turf technology sold into golf and sports venue contracts. Kubota Corporation specializes in compact diesel-to-electric transitions for Japanese municipal buyers.
Lawn mowers are motorized or human-powered machines with rotary or reel cutting decks, typically spanning 16 to 72 inches in cutting width, designed to maintain grass height for aesthetic, recreational, or agricultural purposes. Gasoline engines historically dominated commercial-grade units for their torque density and runtime, though battery chemistry improvements now enable cordless platforms to match output for sub-acre applications. Robotic mowers represent the fastest-expanding product type as autonomous navigation and boundary-wire-free GPS mapping reduce labor input for residential and commercial groundskeeping. The residential end user segment still occupies the largest volume share, but commercial landscaping contracts generate superior margin pools due to equipment durability requirements and fleet replacement schedules.
The EPA regulates exhaust emissions from gasoline-powered outdoor equipment under Phase 3 standards, pushing manufacturers toward catalytic after-treatment or electrification. The EU F-Gas Regulation and REACH framework restrict hydrocarbon refrigerants and chemical substances in battery thermal management systems, reshaping supplier qualification requirements. California Air Resources Board enforcement of small off-road engine rules creates a de facto North American compliance benchmark. Stakeholders must monitor how municipal noise ordinances and zero-emission equipment mandates in German cities and Tokyo prefectures redirect procurement specifications before their next product platform cycles.
Market Dynamics
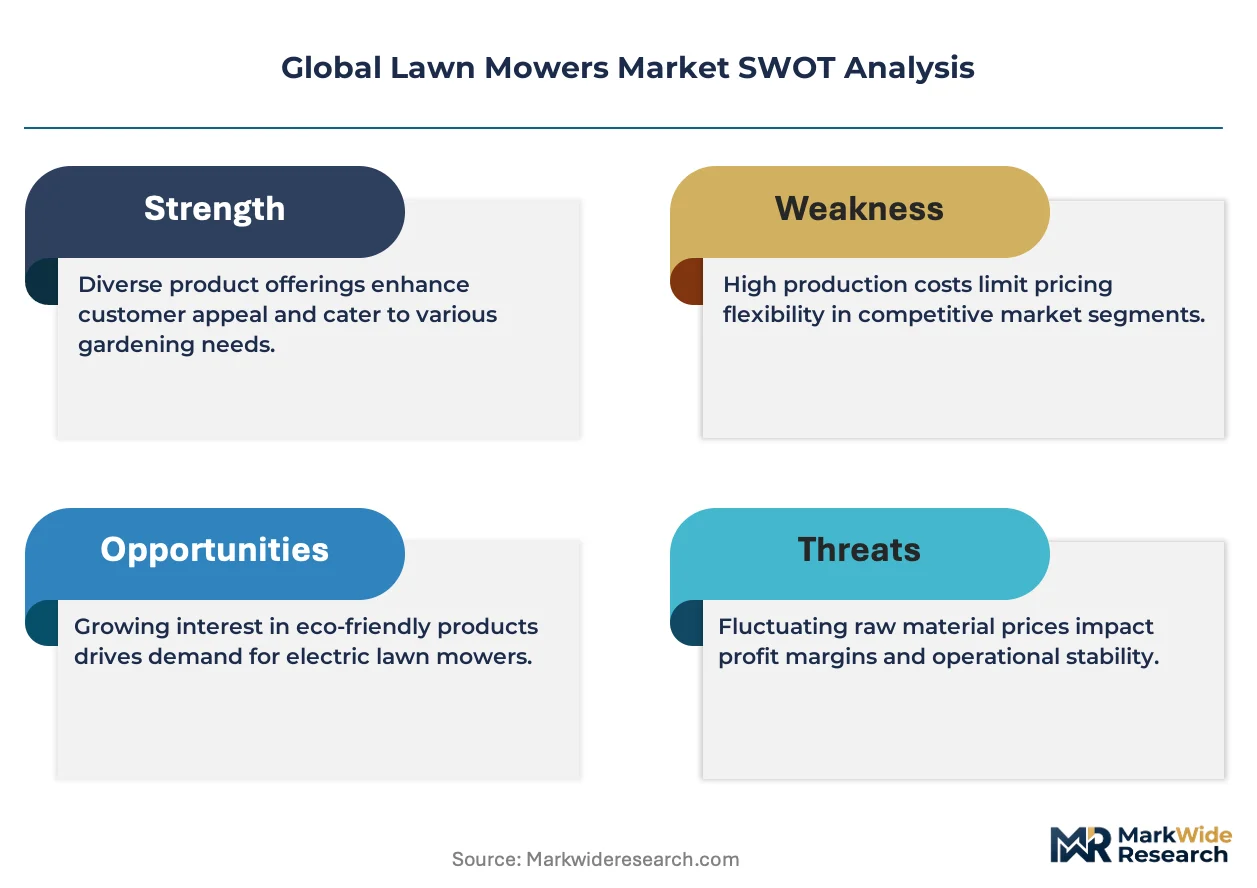
The transition from gasoline to battery-electric powertrains is compressing replacement cycles and rewiring supplier relationships across the lawn mower value chain. Lithium-ion cell chemistry improvements and EPA Phase 3 emissions enforcement are forcing simultaneous platform redesigns.
Growth Catalysts
- EU F-Gas Regulation:Hydrocarbon refrigerant restrictions in battery thermal management are accelerating electric mower certification programs for European commercial fleets.
- Golf course maintenance contracts:Precision turf requirements in Germany, the United States, and Japan are driving demand for GPS-guided cutting decks and autonomous navigation systems.
- Silicon carbide inverters:Power electronics miniaturization is enabling cordless platforms to match gasoline torque density for sub-acre residential applications.
Market Restraints
- Lithium carbonate price volatility:Battery pack cost structures remain exposed to upstream mining concentration in Chile and Australia, squeezing margin on entry-level electric units.
- Small off-road engine compliance:California Air Resources Board enforcement creates fragmented certification requirements that increase R&D overhead for multi-market manufacturers.
- Manual reel mowers:Zero-emission landscaping mandates in some German cities are reviving human-powered alternatives for noise-sensitive zones, capping electric premium pricing power.
Strategic Opportunities
- Brazilian municipal procurement:ANVISA-equivalent environmental standards are tightening, creating first-mover advantage for battery-electric fleet suppliers in South America's largest greenspace maintenance market.
- Subscription-based robotic mowing:Boundary-wire-free GPS mapping enables hardware-as-a-service models for estate management firms seeking to convert capex to opex.
- EU Green Deal public procurement rules:Carbon footprint disclosure requirements for outdoor power equipment are tilting municipal tenders toward verified low-emission suppliers.
Industry Challenges
- Autonomous navigation engineering talent:Simultaneous localization and mapping expertise concentrates in automotive and drone sectors, forcing outdoor power equipment firms to compete for scarce robotics software capabilities.
- REACH substance compliance:Chemical restrictions in battery housing materials and lubricants are extending product validation timelines by 8-14 months for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lawn Mowers Market |
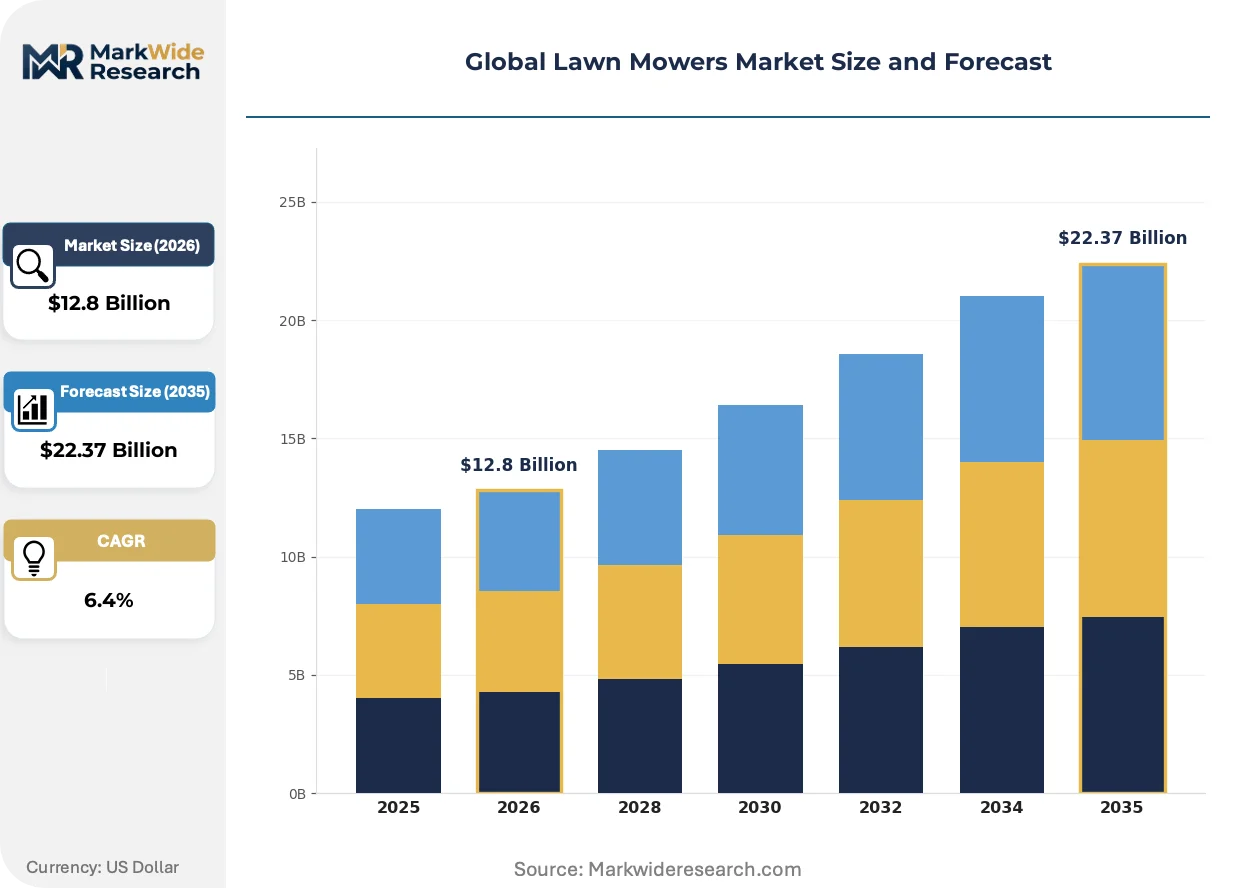
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Powered, Electric, Manual, Robotic End User: Residential, Commercial, Agricultural, Municipal Blade Type: Rotary, Reel, Mulching, Dual-Blade Power Source: Battery, Gasoline, Electric Corded, Electric Cordless |
| Companies Covered | Husqvarna Group, Deere & Company, The Toro Company, American Honda Motor Co., Inc., Stanley Black & Decker, MTD Products, Briggs & Stratton, Ariens Company, Kubota Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lawn Mowers Market Strategic Shifts
Battery-electric architectures are collapsing the historical performance gap with gasoline systems while autonomous software stacks are unbundling labor from groundskeeping operations. These shifts are redrawing competitive boundaries between equipment manufacturers and robotics platforms.
Brushless DC motor controllers with integrated battery management systems are unifying power conversion and cell monitoring into single-chip architectures. Japanese municipal buyers are specifying these consolidated electronics packages for their compact electric tractor fleets. This integration is unifying what were separate supplier tiers, compressing procurement channels and squeezing standalone BMS vendors out of tier-one contracts.
EPA Phase 3 exhaust standards for small off-road engines are tightening hydrocarbon and NOx limits beyond catalytic after-treatment cost-effectiveness. Equipment manufacturers are abandoning gasoline platform refreshes in favor of full electrification for sub-25 horsepower categories. California's enforcement posture is transmitting compliance costs nationwide, as manufacturers decline to maintain separate product lines for a single state.
Landscaping contractors are consolidating equipment procurement through national rental chains rather than dealer networks. Sunbelt Rentals and United Rentals are building captive electric mower fleets with telematics integration, displacing traditional distributor relationships. This concentration is most visible in the United States, where facility management outsourcing has compressed vendor lists to three national lessors.
Global Lawn Mowers Market Segmentation
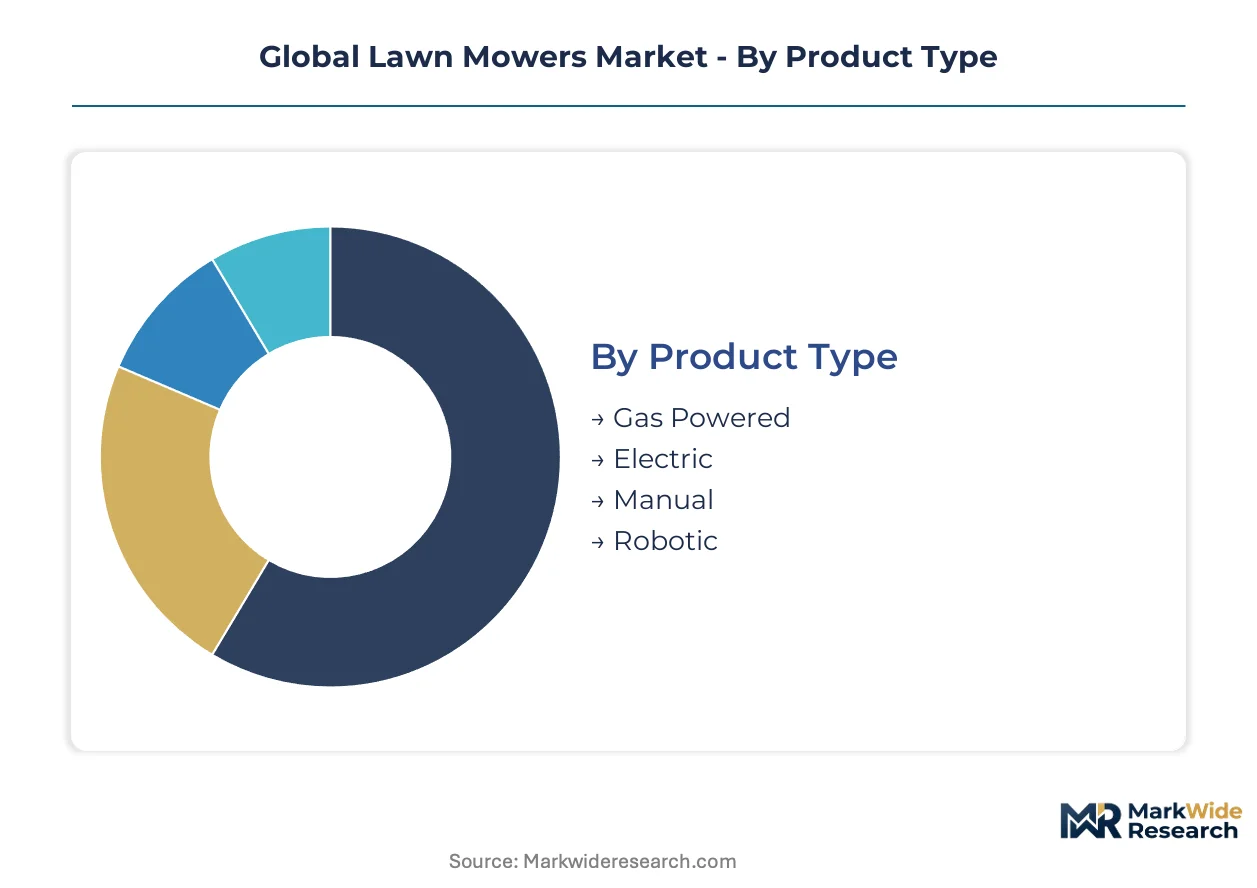
Segmentation in lawn mowers reveals divergent margin pools across powertrain technologies and procurement channels. Equipment specifications vary sharply between residential convenience buyers and commercial fleet operators with uptime requirements.
Product Type:
Volume concentrates in legacy gasoline platforms, while premium capture shifts toward autonomous systems.
- Gas Powered:Internal combustion engines deliver sustained torque for dense turf and extended runtime. Demand persists among commercial landscaping fleets in the United States where refueling infrastructure dominates job site logistics.
- Robotic:Autonomous navigation systems with GPS boundary mapping eliminate perimeter wire installation. German estate management firms and Japanese municipal golf courses are deploying these for labor cost reduction across large maintained areas.
- Electric:Corded and cordless platforms serve sub-acre residential properties with reduced noise signatures.
- Manual:Human-powered reel mechanisms address zero-emission mandates in noise-restricted zones.
Today's leader: Gas Powered. Tomorrow's challenger: Robotic.
End User:
Procurement patterns split between price-sensitive homeowners and durability-focused institutional buyers.
- Residential:Individual homeowners purchase through retail channels with replacement cycles tied to equipment failure rather than technology refresh. Battery-electric platforms are gaining share fastest in suburban United States markets with noise ordinance adoption.
- Commercial:Landscaping contractors operate equipment 800-1,200 hours annually, demanding reinforced decks and serviceable drivetrains. Fleet procurement in Germany and Japan concentrates through rental chains with telematics integration requirements.
- Municipal:City parks departments specify emission compliance and operator safety certifications above unit economics.
- Agricultural:Pasture maintenance and estate groundskeeping require higher cutting widths and terrain adaptability.
Commercial contracts command the steepest expansion trajectory in value terms despite lower unit volumes.
Blade Type:
Cutting mechanism selection tracks turf quality requirements and debris management preferences.
- Rotary:Horizontal spinning blades handle thick grass and irregular terrain. United States residential installations favor these for speed and mulching compatibility.
- Reel:Cylindrical scissor-action blades deliver precision cuts for golf greens and sports turf. Japanese municipal buyers specify these for baseball field maintenance with height tolerances below 5mm.
- Mulching:Enclosed decks with specialized blade geometry recirculate clippings for nutrient return.
- Dual-Blade:Tandem cutting systems reduce pass count on dense growth for commercial productivity.
Rotary dominates unit shipments. Reel commands the highest replacement part revenue per installed base.
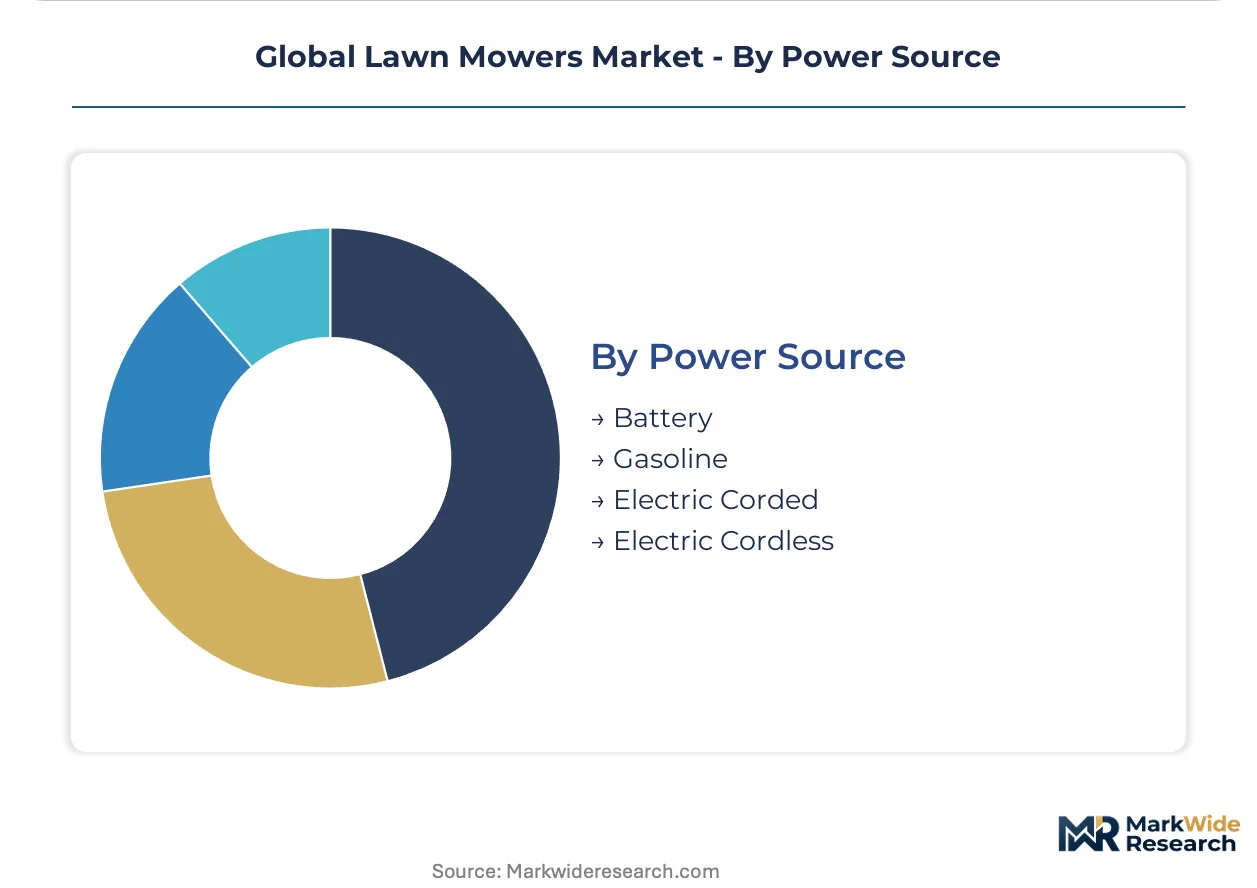
Power Source:
Energy architecture determines weight distribution, runtime architecture, and regulatory compliance exposure.
- Battery:Lithium-ion packs with integrated battery management systems enable cordless operation. EPA Phase 3 enforcement and EU F-Gas Regulation are accelerating certification programs for battery-electric fleets in California and German cities.
- Gasoline:Liquid fuel systems with catalytic after-treatment maintain dominance in commercial horsepower categories above 25hp where runtime exceeds battery economics.
- Electric Corded:Tethered power delivery suits small residential lots with guaranteed electricity access.
- Electric Cordless:Battery platforms with removable packs address range anxiety through hot-swap workflows.
Battery architectures are displacing gasoline in sub-25hp categories where runtime requirements permit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peoria, Illinois anchors global production of outdoor power equipment through Caterpillar's industrial cluster and Deere & Company's precision agriculture hub. German engineering centers in Stuttgart and Munich drive battery-electric platform development for municipal fleets. Japanese manufacturers in Osaka and Tokyo prefectures specialize in compact electric drivetrains for golf course maintenance.
United States
Commercial landscaping contractors operate equipment 800-1,200 hours annually, demanding reinforced cutting decks and telematics integration. California Air Resources Board enforcement of small off-road engine rules creates a de facto national compliance benchmark. Equipment procurement concentrates through Sunbelt Rentals and United Rentals in Texas and Florida, displacing traditional dealer networks with captive electric mower fleets.
Germany
Municipal green-space mandates in Berlin, Munich, and Hamburg drive replacement cycles for zero-emission equipment. EU F-Gas Regulation and EU Green Deal public procurement rules restrict hydrocarbon refrigerants and mandate carbon footprint disclosure for outdoor power equipment. Stuttgart-based engineering clusters specialize in GPS-guided cutting decks for precision turf applications in estate maintenance.
Japan
Tokyo prefecture noise ordinances and municipal golf course maintenance contracts accelerate demand for autonomous navigation systems. METI efficiency standards and local zero-emission equipment mandates redirect procurement specifications toward battery-electric platforms. Osaka manufacturers supply compact diesel-to-electric transitions for municipal buyers specifying height tolerances below 5mm on baseball field turf.
China
Yangtze River Delta manufacturing bases produce lithium-ion battery packs and brushless DC motor controllers for export markets. MIIT industrial standards and dual carbon goals reshape supplier qualification requirements for battery thermal management systems. Shenzhen and Shanghai clusters specialize in integrated battery management systems that unify power conversion and cell monitoring into single-chip architectures.
Brazil
ANVISA-equivalent environmental standards are tightening for greenspace maintenance equipment in São Paulo and Rio de Janeiro municipal fleets. Municipal procurement rules increasingly favor verified low-emission suppliers for public park maintenance contracts. Equipment distributors in the Southeast region build service networks for battery-electric fleet transitions ahead of anticipated federal mandate expansion.
Global Lawn Mowers Market Competitive Environment
Platform electrification dominates the current landscape as manufacturers abandon gasoline refreshes for sub-25 horsepower categories. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with precision agriculture portfolios, specialized outdoor power equipment firms with automation software stacks, and compact equipment specialists serving municipal procurement channels. M&A activity concentrates on battery technology and autonomous navigation capabilities, while capacity expansion targets lithium-ion cell integration and robotic assembly lines.
Among diversified industrial conglomerates, Deere & Company and Kubota Corporation exemplify scale-driven positioning through precision turf technology and compact electric transitions respectively. Husqvarna Group anchors the specialized automation tier with connected robotic systems for estate maintenance. These three entities represent distinct competitive vectors: agricultural equipment cross-over, municipal fleet specialization, and residential robotics platform development.
| Leading Market Players |
|---|
| Husqvarna Group |
| Deere & Company |
| The Toro Company |
| American Honda Motor Co., Inc. |
| Stanley Black & Decker |
| MTD Products |
| Briggs & Stratton |
| Ariens Company |
| Kubota Corporation |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate extraction costs in Chile and Australia cascade through battery pack pricing tiers, compressing margins on entry-level electric mowers while premium robotic platforms absorb volatility through software subscription bundling. Municipal procurement channels in Germany and Japan impose carbon disclosure requirements that widen price spreads between certified low-emission suppliers and conventional gasoline alternatives.
Pricing Analysis
Input-cost pass-through from lithium-ion cell suppliers stratifies pricing across premium, standard, and economy tiers. Price differentiation rests on battery management system certification grade and geographic delivery cost to municipal fleet depots. Cost compression in the entry-level cordless segment is intensifying because lithium carbonate volatility feeds directly into pack economics. Residential homeowners exhibit the highest price sensitivity, while commercial landscaping contractors prioritize total cost of ownership over unit acquisition price.
Supply Chain Analysis
Reverse-logistics networks for battery pack refurbishment and motor controller remanufacturing are emerging in Yangtze River Delta clusters and Stuttgart engineering hubs. Manufacturing concentration centers on China for lithium-ion cells, Japan for brushless DC motor controllers, and Germany for precision cutting deck fabrication. Raw material dependencies span lithium carbonate from Chile, rare earth elements for permanent magnet motors, and specialty steel alloys for blade assemblies. Single-source vulnerability in battery thermal management components creates exposure to EU F-Gas Regulation compliance delays. Distribution runs through national rental chains in the United States and specialized municipal procurement channels in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Lawn Mowers Market functions as a stable compounder anchored by municipal green-space mandates that institutionalize replacement cycles regardless of economic cyclicality.
For Market Incumbents: Extend automation software capabilities into boundary-wire-free GPS mapping systems before robotics engineering talent concentrates further in automotive and drone sectors. Deepen backward integration into lithium-ion cell qualification programs to secure supply priority under EU F-Gas Regulation timelines. Reinforce dealer network relationships in Japan where municipal golf course maintenance contracts demand localized service infrastructure.
For New Entrants and Emerging Players: Brazilian municipal buyers seeking verified low-emission fleet suppliers represent the most penetrable white-space target as ANVISA-equivalent standards tighten ahead of federal mandate expansion. Subscription-based robotic mowing hardware-as-a-service models convert capital expenditure to operating expenditure for estate management firms in Germany. Direct procurement relationships with Sunbelt Rentals and United Rentals bypass entrenched distributor networks in the United States commercial segment.
For Investors and Strategic Acquirers: Consolidation pressure builds where autonomous navigation engineering capabilities concentrate in automotive and drone sectors rather than outdoor power equipment. The five-to-ten year viability window favors acquisition targets with integrated battery management system software stacks and existing municipal certification in German or Japanese markets. Monitor EPA Phase 3 enforcement posture and California Air Resources Board rulemaking as inflection indicators for gasoline platform abandonment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation ahead of EU F-Gas Regulation compliance deadlines. |
| Autonomous Navigation Acquisition | Addresses simultaneous localization and mapping talent scarcity concentrated in automotive sectors. |
| Municipal Certification Investment | Unlocks carbon-disclosure-compliant tender participation in Berlin, Munich, and Hamburg. |
| Remanufacturing Network Buildout | Captures reverse-logistics value from battery pack refurbishment in Yangtze River Delta clusters. |
| Subscription Platform Launch | Converts estate management firm procurement from capital expenditure to recurring revenue. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with equipment procurement managers at municipal parks departments, commercial landscaping fleet operators, and golf course maintenance directors alongside secondary validation from EPA enforcement documentation, EU F-Gas Regulation filings, and METI efficiency standard publications. Bottom-up unit shipment modeling triangulates against top-down value estimates derived from lithium-ion cell production data and cutting deck manufacturing capacity.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include powertrain architecture, end-user procurement channel, blade mechanism type, and regional regulatory cluster. CAGRs were derived from trend extrapolation of replacement cycle compression and electrification penetration curves. Industry-specific forecast inputs incorporate golf course maintenance contract renewal patterns and municipal zero-emission equipment mandate adoption timelines.
Inputs from national rental chain procurement databases and municipal tender documentation were available through the study window; gaps in autonomous navigation system deployment data introduce uncertainty bands around robotic mower penetration assumptions. Forecasts reflect documented assumptions regarding EPA Phase 3 enforcement consistency and lithium carbonate price normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Commercial Oil Extraction Machine Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Agriculture Equipment Market