
 Argentina Seed Treatment Market | 2026-2036
Argentina Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Seed Treatment Market Outlook
Modular service bundling is rebalancing how Argentine growers purchase seed treatment, shifting from standalone chemical applications to integrated packages combining biologicals, coatings, and monitoring tools. Syngenta Agro SA leverages its research station network to anchor premium positioning across the Pampas. BASF Argentina S.A. competes through specialized polymer coating technologies that extend product persistence in variable soil conditions.
Argentina seed treatment encompasses chemical and biological formulations applied to seeds before planting to protect against soil-borne pathogens, early-season insects, and abiotic stress, with film coatings typically ranging from one to five percent of seed weight and active ingredient loadings calibrated by crop species and regional pest pressure. Its primary commercial purpose centers on reducing establishment risk and optimizing yield potential for export-oriented commodity production. Fungicide-based treatments dominate volume as soybean and wheat growers prioritize protection against fusarium and rhizoctonia complexes, while biological inoculants represent the fastest-expanding category as farmers seek to comply with tightening residue protocols in European export markets. Application on grains captures the deepest margin pools due to scale economies and repeat purchase frequency among cooperative buyers.
SENASA maintains registration authority over all agricultural chemical seed treatments, with residue limit harmonization increasingly shaped by EU EFSA standards given Argentina's dependence on European oilseed and grain export channels. The country's national agricultural technology institute INTA validates biological product efficacy, creating a dual-track approval system that advantages firms with robust local trial data. Stakeholders must monitor how evolving EU Green Deal import requirements and domestic bioinput certification pathways reshape product development priorities and distribution investments.
Market Dynamics
SENASA's tightening residue protocols under EU EFSA alignment are forcing Argentine seed treatment formulators to abandon legacy chemistries and rebuild product portfolios around biological actives certified for European export channels.
Growth Catalysts
- Biological registration pathways:INTA's expanded field trial protocols for bioinput validation accelerate commercialization timelines for microbial inoculants targeting rhizoctonia suppression in soybean.
- Export market compliance:EU Green Deal import requirements drive replacement of synthetic fungicides with residue-free alternatives among Pampas grain cooperatives supplying European oilseed processors.
- Precision application hardware:On-farm seed treater installations enable just-in-time coating operations that reduce inventory carrying costs for large-scale Buenos Aires province operations.
Market Restraints
- Active ingredient supply concentration:Polymer coating chemistries rely on imported acrylic resins subject to Argentine central bank foreign exchange rationing.
- Registration timeline friction:SENASA's dual-track chemical-biological approval system creates 18-24 month bottlenecks for novel microbial formulations.
- Soil microbiome variability:Biological efficacy inconsistency across Mollisol and Vertisol soil types limits grower confidence in biological-only treatment packages.
Strategic Opportunities
- Córdoba province penetration:Second-tier grain regions outside Buenos Aires exhibit sub-40% biological adoption rates versus 60% in core Pampas districts.
- Drone-based spot retreatment:Aerial application services enable post-planting biological booster doses for farmers seeking season-long root protection.
- Carbon credit stacking:Biological nitrogen fixation enhancements qualify for emerging agricultural offset protocols in EU compliance markets.
Industry Challenges
- Microbial formulation expertise:Local technical service teams lack shelf-life stability assessment capabilities for multi-strain inoculant blends.
- Legacy equipment incompatibility:Existing chemical seed treaters require retrofitting for low-viscosity biological suspensions and temperature-sensitive live cultures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Seed Treatment Market |
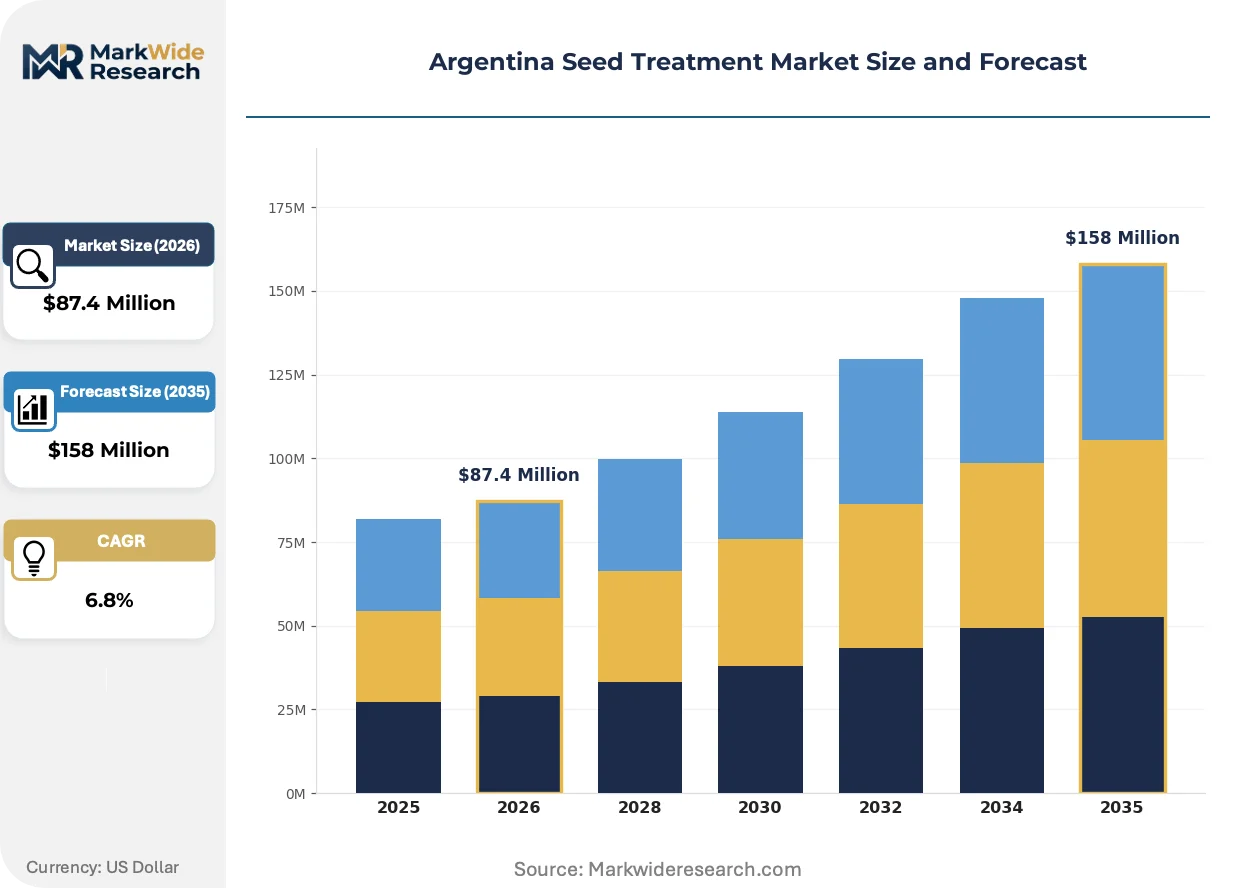
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Fungicides, Insecticides, Herbicides Application: Crops, Vegetables, Fruits, Grains Distribution Channel: Online, Retail, Distributors, Wholesalers End User: Farmers, Agricultural Companies, Cooperatives, Researchers |
| Companies Covered | Syngenta Agro SA, BASF Argentina S.A., ADAMA Agricultural Solutions Ltd, Bayer CropScience Pty Ltd, Corteva Agriscience, INCOTEC Argentina, Nufarm S.A., Sumitomo Chemical Argentina, FMC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Seed Treatment Market Strategic Shifts
Formulation science and application hardware are converging to redefine how Argentine growers evaluate treatment value, shifting from per-kilogram chemistry costs to establishment-rate guarantees and season-long performance accountability.
Microencapsulation of Bacillus subtilis strains with biodegradable polymer shells is rewriting durability standards for biological seed treatments. Large-scale agricultural companies in Santa Fe and Buenos Aires provinces are piloting these formulations at commercial scale. The technology compresses the performance gap between biological and chemical persistence in high-moisture planting conditions.
SENASA's 2024 harmonization with EU EFSA maximum residue limits for azole fungicides is eliminating several legacy active ingredients from the approved list. Formulators must reformulate flagship products or exit the market entirely. Wheat seed treatments face the most immediate compliance pressure given European flour miller procurement specifications.
Cooperative buyers are consolidating procurement through multi-year service agreements that bundle seed, treatment, and establishment monitoring. Independent retailers lose volume to vertically integrated agricultural companies with captive treatment facilities. This concentration is most visible in the northern Pampas where Rosario-based grain handlers anchor supply chain control.
Argentina Seed Treatment Market Segmentation
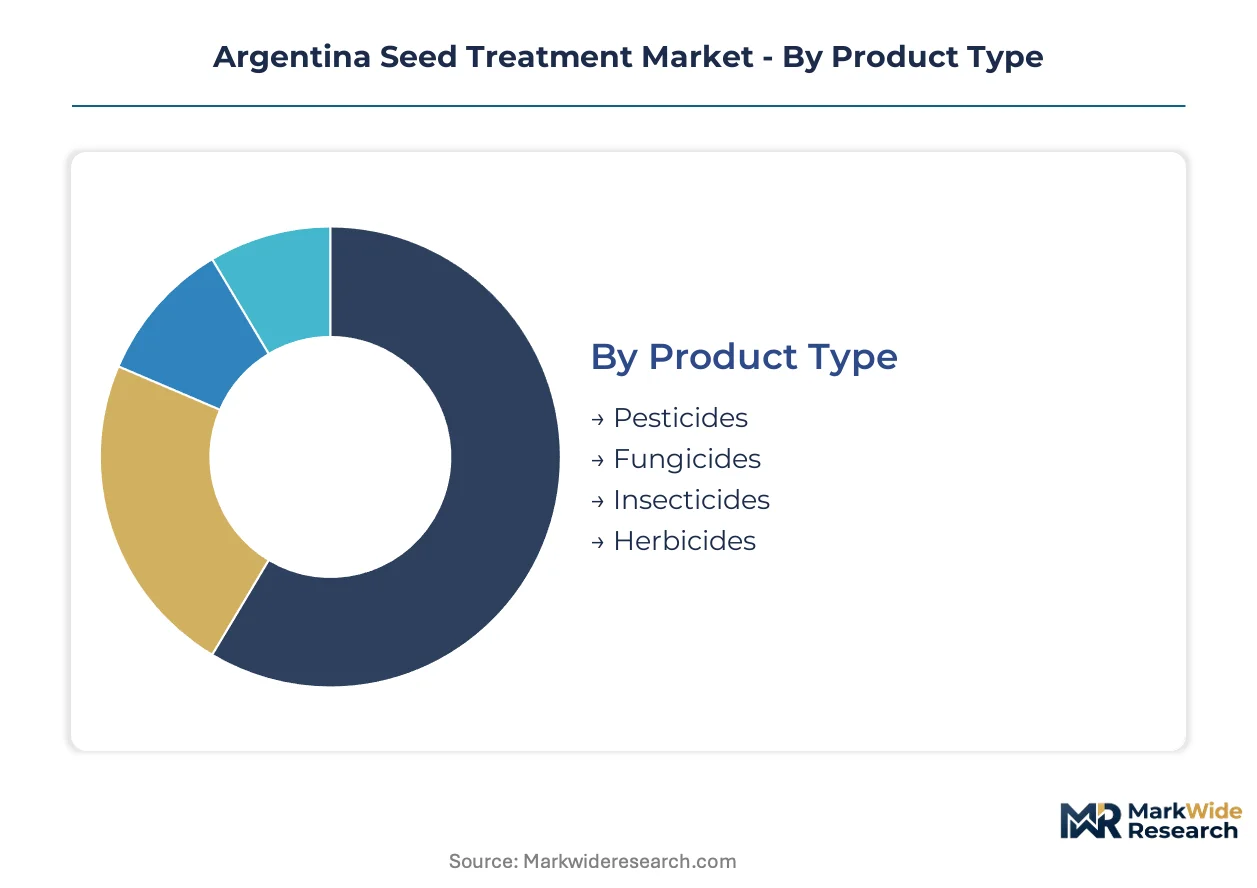
Segmentation in Argentina's seed treatment market reflects divergent regulatory pathways and procurement behaviors across crop systems. SENASA registration requirements and INTA bioinput certification create distinct commercial corridors that suppliers must navigate to capture volume in Buenos Aires province and emerging Cordoba districts.
Product Type:
SENASA maintains separate registration tracks for chemical actives versus biological formulations, with residue limit alignment to EU EFSA standards determining which segments retain market access.
- Pesticides:Broad-spectrum chemical formulations targeting soil-borne nematodes and early-season insect complexes. Demand concentrates among wheat growers in southern Santa Fe province confronting European flour miller procurement specifications that restrict legacy active ingredients.
- Fungicides:Azole and strobilurin-based treatments protecting against fusarium and rhizoctonia in high-moisture planting windows. Large-scale soybean operations in Buenos Aires province drive procurement as export cooperatives seek compliance with tightening EU Green Deal residue protocols.
- Insecticides:Neonicotinoid and biological alternatives targeting seedcorn maggot and wireworm pressure in corn establishment phases.
- Herbicides:Pre-emergence safeners and resistance-management actives bundled with traited seed platforms.
Leading the category by volume: Fungicides. Growing fastest: Pesticides reformulated around biological actives.
Application:
Application segmentation tracks directly to export channel requirements, with European oilseed and grain processors imposing differentiated residue standards across commodity categories.
- Crops:Soybean, corn, and wheat treatments calibrated to crop-specific pathogen pressures and establishment risk profiles. Buenos Aires province agricultural companies consolidate procurement through captive treatment facilities, displacing independent retailer volumes.
- Vegetables:High-value specialty crop coatings requiring precision application and rapid emergence support for domestic fresh market and processed export channels.
- Fruits:Nursery stock and direct-seeded treatments for pome and stone fruit establishment in Mendoza and Rio Negro valley systems.
- Grains:Volume-dominant wheat and barley treatments facing immediate compliance pressure from SENASA's azole fungicide harmonization with EU EFSA maximum residue limits.
Grains command the deepest procurement scale. Vegetables sustain the steepest expansion trajectory through premium pricing for residue-free certification.
Distribution Channel:
Channel structure reflects working capital constraints and foreign exchange rationing that disadvantage import-dependent supply chains.
- Online:Direct-to-farm digital platforms enabling price transparency and technical documentation access for biological product validation. Emerging traction among mid-scale Pampas operations seeking INTA trial data comparisons.
- Retail:Bricks-and-mortar agrochemical depots with on-site seed treater infrastructure and technical service capabilities.
- Distributors:Regional warehousing networks consolidating multi-brand portfolios for cooperative buyers.
- Wholesalers:Volume aggregation points serving northern Pampas grain handlers with Rosario-based supply chain control.
Distributors anchor current volume flows. Online channels are gaining share fastest through cooperative procurement digitization.
End User:
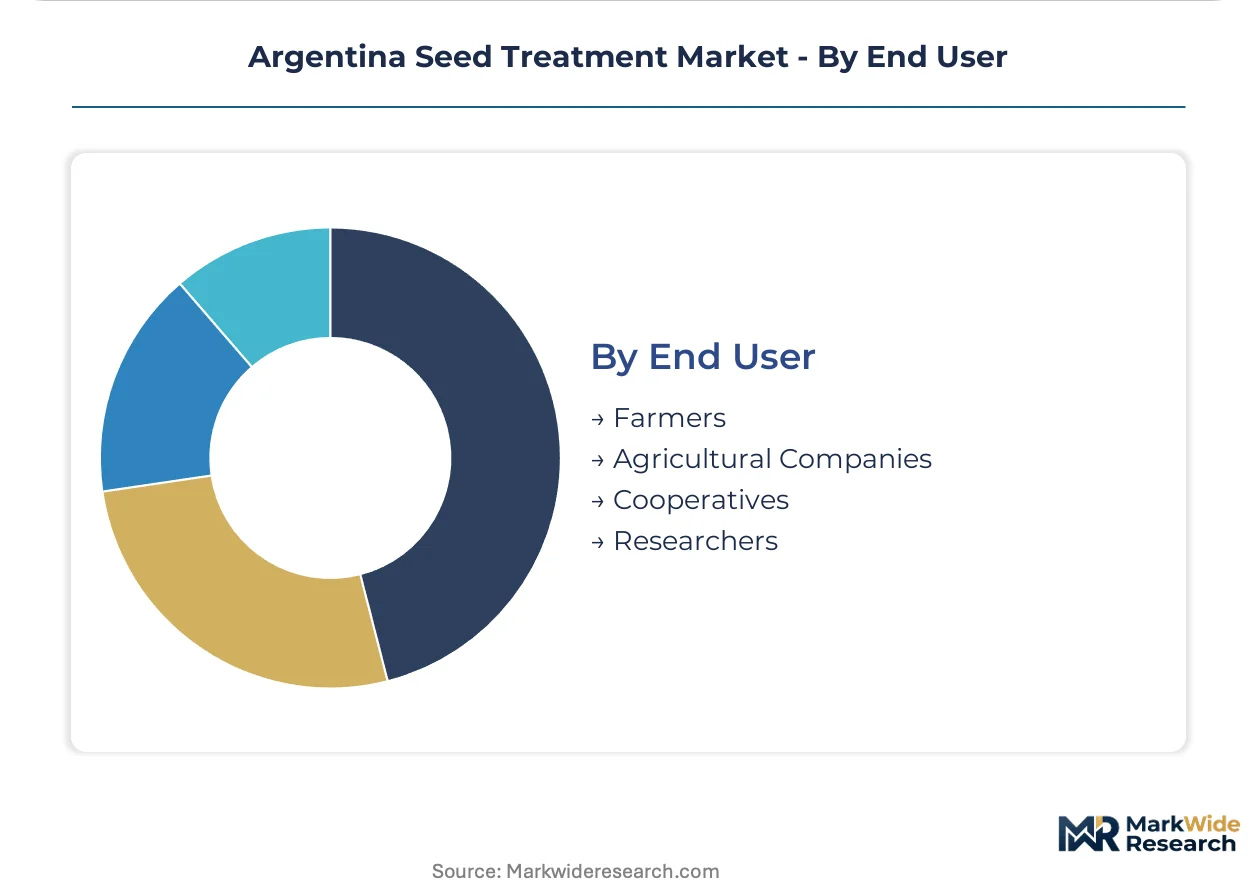
End user segmentation reveals consolidation dynamics as scale advantages reshape treatment procurement from transactional product sales to integrated service agreements.
- Farmers:Individual growers and family operations purchasing through retail channels or cooperative membership structures. Sub-40% biological adoption rates in Cordoba province versus core Pampas districts signal penetration opportunity.
- Agricultural Companies:Vertically integrated operations with captive seed treatment facilities and multi-year service bundling. These entities displace independent retailers through establishment-rate guarantees and season-long performance accountability.
- Cooperatives:Member-owned procurement bodies consolidating volume for price leverage and technical standardization.
- Researchers:INTA stations and private trial operators generating bioinput efficacy data for SENASA registration support.
Agricultural companies lead by volume concentration. Cooperatives represent the fastest-climbing segment through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buenos Aires province anchors Argentina seed treatment demand through its concentration of large-scale agricultural companies operating within the Pampas grain belt. The region's export-oriented soybean and wheat production drives procurement of residue-compliant treatments aligned with SENASA registration requirements.
Buenos Aires Province
Soybean establishment risk and fusarium pressure concentrate demand for azole fungicide alternatives among Pampas grain cooperatives. SENASA's 2024 EU EFSA residue harmonization eliminates legacy chemistries from the approved list. Rosario-based grain handlers consolidate supply chain control through captive seed treatment facilities across the northern Pampas corridor.
Santa Fe Province
Wheat growers confronting European flour miller specifications drive reformulation toward biological actives certified for export channels. INTA field trial protocols validate microbial inoculant efficacy for rhizoctonia suppression in high-moisture planting windows. Large-scale operations in southern districts pilot microencapsulated Bacillus subtilis formulations at commercial scale.
Córdoba Province
Second-tier grain regions exhibit sub-40% biological adoption rates versus core Pampas districts, signaling penetration opportunity for residue-free alternatives. Central bank foreign exchange rationing disrupts polymer coating chemistry imports for local formulators. Agricultural companies in the southeastern grain belt expand on-farm seed treater installations to reduce inventory carrying costs.
Entre Ríos Province
Variable Mollisol and Vertisol soil microbiomes limit grower confidence in biological-only treatment packages across mixed cropping systems. SENASA dual-track approval timelines create 18-24 month bottlenecks for novel microbial formulations seeking commercialization. Cooperative buyers in Paraná district aggregate volume for price leverage against vertically integrated competitors.
La Pampa Province
Extensive wheat and barley production faces immediate compliance pressure from azole fungicide restrictions in European export channels. Precision application hardware adoption enables just-in-time coating operations among mid-scale operations. Santa Rosa agrochemical depots retrofit existing chemical seed treaters for low-viscosity biological suspensions.
Argentina Seed Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Argentina's seed treatment market, creating a tiered structure where global agrochemical majors anchor premium positioning through research infrastructure. The vendor base concentrates around firms with SENASA registration expertise and INTA trial data generation capabilities. Three archetypes dominate: integrated multinational suppliers with captive distribution, regional formulators specializing in biological actives, and equipment-service hybrids bundling application hardware with treatment chemistries. Competitive moves center on multi-year service agreements replacing transactional product sales, and retrofit partnerships enabling biological compatibility in legacy chemical treater installations.
Among multinational suppliers with Argentine subsidiaries, Syngenta Agro SA and BASF Argentina S.A. exemplify the integrated archetype through their research station networks and polymer coating technology portfolios. Nufarm S.A. occupies a position within the regional formulator tier, while ADAMA Agricultural Solutions Ltd represents the specialized active ingredient supplier segment. These entities anchor competitive dynamics through their respective SENASA registration holdings and INTA validation partnerships.
| Leading Market Players |
|---|
| Syngenta Agro SA |
| BASF Argentina S.A. |
| ADAMA Agricultural Solutions Ltd |
| Bayer CropScience Pty Ltd |
| Corteva Agriscience |
| INCOTEC Argentina |
| Nufarm S.A. |
| Sumitomo Chemical Argentina |
| FMC Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EU EFSA-compliant biologicals and legacy chemical treatments splits procurement budgets across Argentine agricultural companies, with premium tiers commanding captive supply arrangements while commodity-grade alternatives flow through distributor networks subject to central bank foreign exchange rationing.
Pricing Analysis
Short lead-time premiums attach to just-in-time biological formulations from Syngenta Agro SA and BASF Argentina S.A. research stations, while spot inventory of conventional azole fungicides trades at discounts amid SENASA registration uncertainty. Three-tier pricing structure across premium, standard, and economy levels reflects INTA bioinput certification status, polymer coating durability, and establishment-rate guarantee terms. Pricing pressure stems from cooperative buyers consolidating procurement through multi-year service agreements that squeeze independent retailer margins. Mid-scale Cordoba province farmers exhibit highest price sensitivity, whereas vertically integrated Buenos Aires province agricultural companies prioritize residue compliance over per-kilogram chemistry costs.
Supply Chain Analysis
Domestic-content mandates under Argentina's bioinput certification pathways reshape sourcing toward INTA-validated microbial strain suppliers, reducing reliance on imported active ingredients. Formulation chemistry draws from China, India, and Germany for polymer coating resins and strobilurin technicals, while biological inoculant mother cultures originate from Brazilian and US research repositories. Single-source vulnerability concentrates in acrylic resin imports subject to Argentine central bank foreign exchange rationing. Distribution runs through Rosario-based grain handlers consolidating captive treatment facilities, with cooperative buyers and independent retailers anchoring downstream tier.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's seed treatment market reads as a consolidation play where SENASA's dual-track approval timelines and residue protocol harmonization force capital-constrained formulators toward exit or acquisition.
For Market Incumbents: Anticipate regulatory bottlenecks by accelerating INTA field trial investments for microbial inoculants before legacy chemical registrations lapse. Secure backward integration into polymer coating chemistry through partnerships with Argentine resin distributors to mitigate central bank foreign exchange exposure. Establishment-rate guarantees and season-long performance accountability anchor defensive positioning against cooperative buyer consolidation. For New Entrants and Emerging Players: Enter via Córdoba province's sub-40% biological adoption gap, where mid-scale grain operations lack access to premium research station networks. Target drone-based spot retreatment services for post-planting biological booster doses as the most penetrable application segment. Carbon credit stacking for biological nitrogen fixation enhancements offers differentiated go-to-market positioning against commodity chemical suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of regional biological formulators with robust INTA trial data libraries and SENASA registration pipelines. Long-term viability hinges on EU Green Deal import requirement alignment across the analysis window. Watch SENASA approval velocity for novel microbial formulations as the critical inflection signal distinguishing scalable platforms from stranded legacy portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| INTA Bioinput Certification Investment | Accelerates SENASA registration timelines for rhizoctonia-targeting microbial inoculants. |
| Polymer Coating Backward Integration | Reduces foreign exchange exposure from imported acrylic resin dependencies. |
| Cooperative Procurement Digitization | Captures volume from Rosario-based grain handlers consolidating supply chain control. |
| Drone-Based Spot Retreatment Launch | Enables post-planting biological booster doses for season-long root protection. |
| Carbon Credit Protocol Alignment | Qualifies biological nitrogen fixation for EU compliance market agricultural offsets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with SENASA registration specialists, INTA field trial directors, cooperative procurement managers, and polymer coating formulators. SENASA chemical-biological approval databases, EU EFSA maximum residue limit harmonization documents, Argentine central bank import licensing records, and grain cooperative annual reports provided validation layers. Bottom-up treatment volume estimates from Buenos Aires and Córdoba province agricultural companies reconciled with top-down market value projections.
Data-stream reconciliation across product type, application crop, distribution channel, and end-user segmentation dimensions generated consistent outputs over the projection horizon. CAGRs derived from exponential growth modeling of biological adoption curves and cooperative procurement consolidation rates. Modeled inputs incorporated SENASA registration pipeline velocity, INTA bioinput certification throughput, and EU Green Deal residue protocol evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU EFSA standard revisions or extended Argentine foreign exchange rationing. Projections reflect assumptions regarding SENASA approval timeline stability and polymer coating import license continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Australia Seed Treatment Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
Italy Seed Treatment Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
North America Seed Treatment Market
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
Alfalfa Seed Extract Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
Brazil Seed Treatment Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
Oilseed Processing Market