
 Global Seed Processing Machinery Market | 2026-2036
Global Seed Processing Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seed Processing Machinery Market Foresight
Market Context
The capital-intensity divergence between integrated European manufacturers and regional assembly specialists is unwinding competitive stability in seed processing equipment. Bühler AG leverages its Swiss engineering heritage and captive foundry network to sustain premium positioning across high-capacity optical sorting lines. Cimbria A/S anchors its Danish operations with deep expertise in air-separation technology for cereal and oilseed applications. PETKUS Technologie GmbH dominates precision coating and seed treatment systems through in-house polymer formulation capabilities.
Technical Definition and Structural Segments
Seed processing machinery encompasses mechanical, pneumatic, and electro-optical systems designed to clean, grade, treat, coat, and package propagative material to certified germination and purity standards, with throughput capacities ranging from laboratory-scale units processing kilograms per hour to industrial lines exceeding twenty metric tons hourly. Seed cleaning machines and seed treatment equipment command the largest installed base, while optical sorting technology captures the fastest expansion as seed companies replace legacy gravity tables with camera-based defect removal. Seed coating machines concentrate margin pools where polymer chemistry and application uniformity determine varietal performance claims.
Regulatory Frame and Outlook
The OECD Seed Schemes, EU Plant Health Regulation, and USDA-APHIS phytosanitary protocols collectively shape equipment specifications, mandating traceable lot handling and contaminant thresholds that drive precision-engineered system demand. EPA and REACH frameworks further constrain chemical treatment formulations, compelling machinery makers to engineer closed-loop application systems that reduce active ingredient loss. Stakeholders must monitor evolving gene-edited seed classification debates, as regulatory rulings on CRISPR-derived varieties will reshape processing protocols for identity preservation and segregation infrastructure.
Market Dynamics
Optical sorting systems are compressing equipment replacement cycles across commercial seed operations, as camera-based defect detection delivers precision thresholds that gravity tables cannot match. This technology shift is redrawing capital allocation patterns among integrated processors and contract seed companies.
Growth Catalysts
- OECD Seed Schemes:Varietal purity mandates in Brazil, Germany, and India compel processors to upgrade cleaning and grading infrastructure. Certified germination standards now require traceable lot handling systems.
- Gene-edited seed protocols:Anticipated regulatory clarity on CRISPR-derived varieties is accelerating investment in identity preservation infrastructure. Segregation-capable processing lines command premium positioning.
- Polymer chemistry advances:Precision coating systems integrate active ingredient delivery with polymer film uniformity. Seed treatment equipment incorporating closed-loop application architectures reduces EPA-monitored chemical loss.
Market Restraints
- Stainless steel and precision optics supply:Foundry capacity constraints in European manufacturing hubs inflate lead times for high-capacity sorting lines. Captive casting operations insulate only vertically integrated producers.
- REACH chemical compliance:Polymer formulation restrictions constrain treatment system configurations. Machinery makers must engineer closed-loop architectures to satisfy active ingredient containment thresholds.
- Legacy gravity table installed base:Depreciated but functional equipment extends replacement timelines. Capital discipline among mid-scale processors defers optical sorting adoption.
Strategic Opportunities
- Indian commercial seed expansion:Domestic processors seek capacity scaling to serve export-oriented hybrid cotton and maize programs. OECD certification infrastructure remains underdeveloped relative to volume growth.
- Near-infrared spectroscopy convergence:Integration with camera-based sorting enables real-time protein and oil content grading. Oilseed processors in the North American Great Plains pilot dual-sensor architectures.
- EU Farm-to-Fork Strategy:Chemical reduction targets incentivize precision application equipment. Closed-loop treatment systems align with pesticide use reduction mandates under the EU Green Deal.
Industry Challenges
- Electro-optical technician scarcity:Camera calibration and AI-driven defect recognition algorithms require specialized skill sets. Regional service networks struggle to field qualified personnel for optical sorting line maintenance.
- Legacy pneumatic system integration:Retrofitting air-separation infrastructure with optical sorting modules demands custom engineering. Downtime costs during hybrid system commissioning compress project margins.
- OECD lot traceability certification:Documentation protocols for varietal purity extend equipment qualification timelines. Processors face audit preparation burdens before certified seed release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seed Processing Machinery Market |
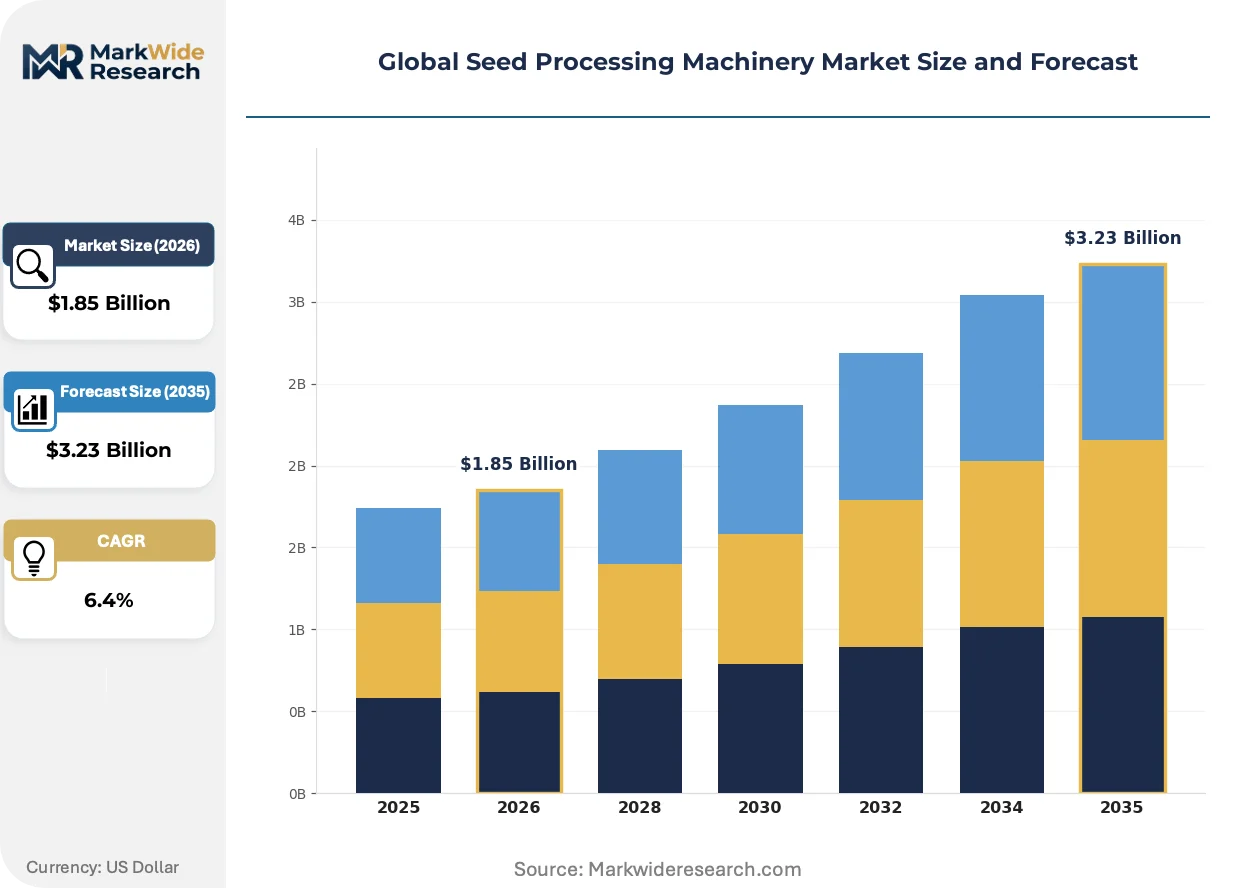
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seed Cleaning Machines, Seed Grading Machines, Seed Treatment Equipment, Seed Coating Machines, Seed Packing Equipment Technology: Optical Sorting, Air Separation, Screening, Magnetic Separation, Coating Application Application: Cereal Crops, Legumes Processing, Oilseed Handling, Vegetable Seed Preparation, Pulse Seed Processing End User: Seed Companies, Agricultural Cooperatives, Contract Processors, Research Institutions |
| Companies Covered | Bühler AG, Cimbria A/S, PETKUS Technologie GmbH, Satake Corporation, Ag Growth International Inc., Bratney Companies, Abel, US Global Resources, Ginhong, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seed Processing Machinery Market Shifts & Advancements
Machine vision and polymer chemistry are converging to redefine seed processing performance benchmarks. Equipment architectures now prioritize traceability integration and chemical containment alongside traditional throughput metrics.
Hyperspectral imaging arrays paired with deep learning defect classification are supplanting monochromatic camera systems in premium optical sorting lines. Large-scale contract processors in Iowa and Saskatchewan deploy these architectures to detect subtle varietal admixtures. The technology is supplanting legacy RGB-camera configurations and compressing differentiation margins among mid-tier equipment suppliers.
REACH chemical authorization procedures are constraining polymer formulation options for seed coating systems. Machinery makers must redesign application nozzles and drying tunnels to accommodate lower-volatility binder chemistries. European seed treatment facilities face the most acute retrofit pressure, as ECHA substance evaluation timelines extend equipment qualification cycles.
Service contracting is unbundling from equipment sales as processors seek performance guarantees on germination uniformity metrics. Major seed companies in Brazil and Germany now specify outcome-based maintenance agreements with uptime penalties. This procurement evolution concentrates aftermarket revenue among suppliers with regional technical service density.
Global Seed Processing Machinery Market Segmentation
Segmentation in seed processing machinery reveals how capital allocation, regulatory mandates, and crop-specific protocols fragment demand across equipment categories. Understanding these divisions exposes where technology substitution accelerates and where legacy infrastructure retains pricing power.
Product Type:
Domestic processors in India and Brazil drive volume demand for entry-level cleaning and grading equipment, while German and North American seed companies anchor export-led demand for precision coating and optical sorting systems.
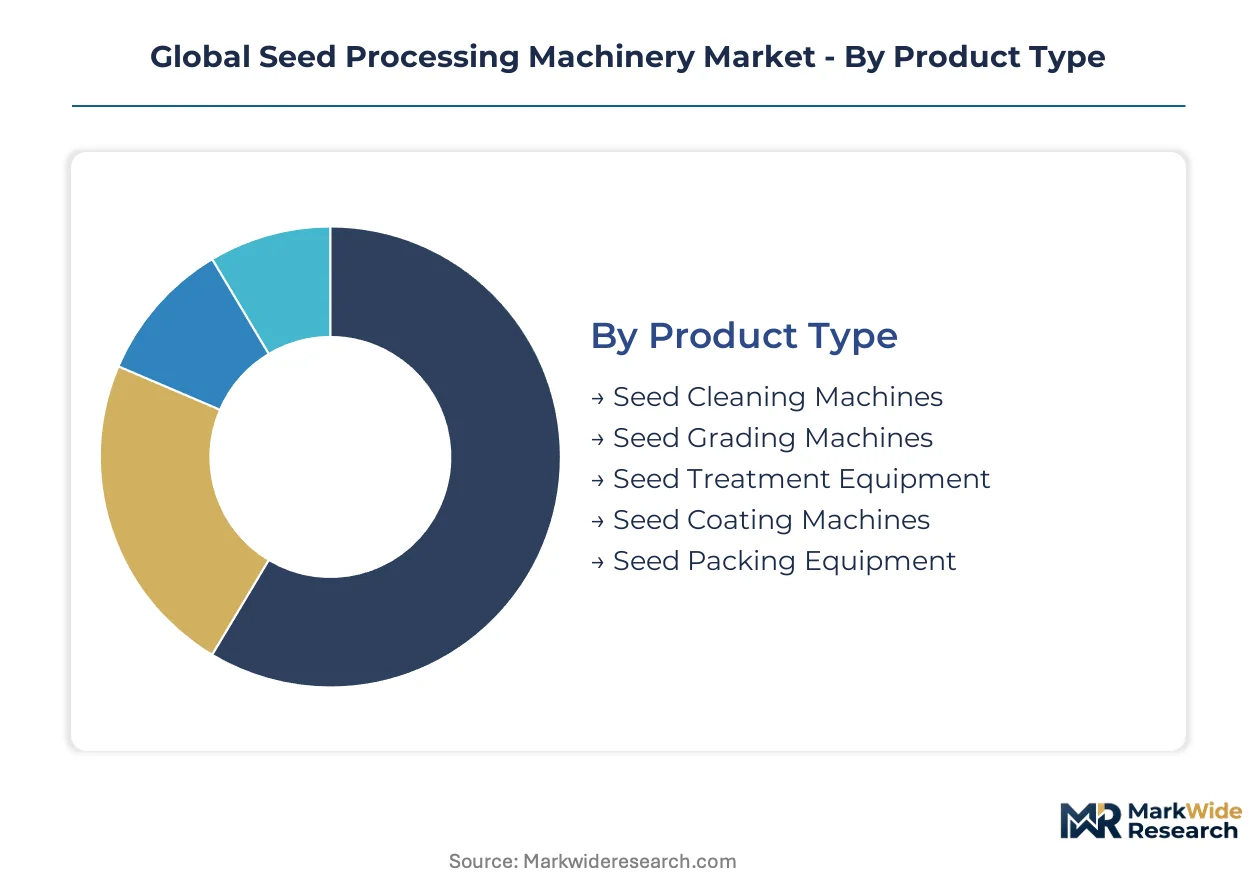
- Seed Cleaning Machines:Mechanical and pneumatic systems remove inert matter, weed seeds, and debris through air separation and screening cascades. Demand concentrates among mid-scale contract processors in Brazil's Mato Grosso region, where OECD varietal purity mandates now require upgraded pre-cleaning infrastructure before certification.
- Seed Treatment Equipment:Closed-loop chemical application systems integrate active ingredient dosing with containment architectures that satisfy EPA and REACH discharge thresholds. German seed companies specify these systems for export-oriented hybrid maize programs, where polymer formulation precision determines germination uniformity claims.
- Seed Grading Machines:Density-based and dimensional sorting units separate seed lots by size and specific gravity.
- Seed Coating Machines:Precision film-coating systems apply polymer binders with active ingredients for pest protection and nutrient delivery.
- Seed Packing Equipment:Automated bagging and containerization lines handle certified seed lot traceability documentation.
Seed cleaning machines command the established base. The steepest expansion runs through seed treatment equipment.
Technology:
Cost tier differentiation separates premium electro-optical systems from mid-range pneumatic equipment, with capital-constrained processors in emerging markets clustering at the standard tier and OECD-certified operations absorbing premium pricing for camera-based architectures.
- Optical Sorting:Hyperspectral imaging arrays paired with deep learning algorithms detect subtle color, texture, and morphological defects invisible to legacy gravity tables. Iowa and Saskatchewan contract processors deploy these systems for identity preservation in gene-edited soybean and canola programs, where varietal admixture detection thresholds now determine certification eligibility.
- Air Separation:Pneumatic density classification remains the workhorse technology for cereal and oilseed pre-cleaning, with Danish engineering heritage sustaining competitive positioning in high-throughput lines.
- Screening:Mechanical aperture separation by seed dimensions serves as the foundational grading stage across all throughput scales.
- Magnetic Separation:Ferrous contaminant removal systems protect downstream coating and packaging equipment from field debris damage.
- Coating Application:Precision nozzle and rotary drum architectures control polymer film thickness uniformity for active ingredient delivery.
Air separation anchors the installed base across volume processing. Optical sorting gains share fastest where varietal purity premiums justify capital intensity.
Application:
Customer type fragmentation splits demand between integrated seed companies seeking full-line automation and agricultural cooperatives prioritizing modular, crop-flexible equipment configurations.
- Cereal Crops:Wheat, rice, and maize processing lines demand high-throughput cleaning and grading infrastructure with moisture-controlled handling. Indian commercial seed expansion for hybrid maize export programs drives capacity investment, though OECD certification infrastructure lags volume growth.
- Oilseed Handling:Soybean, canola, and sunflower processing requires specialized dehulling and separation stages before precision coating. North American Great Plains processors pilot near-infrared spectroscopy integration for real-time oil and protein content grading.
- Legumes Processing:Bean and pea seed handling emphasizes damage minimization through gentle conveying and reduced-impact cleaning.
- Vegetable Seed Preparation:High-value, small-seed crops demand laboratory-scale precision and lot traceability systems.
- Pulse Seed Processing:Lentil and chickpea operations require robust dehulling and splitting recovery stages.
Cereal crop equipment represents the largest revenue pool. Oilseed handling infrastructure expands most quickly on protein and oil content grading premiums.
End User:
Supply concentration among integrated European manufacturers and regional assembly specialists creates tiered procurement patterns, with seed companies absorbing premium Swiss and German engineering and cooperatives sourcing from regional specialists.
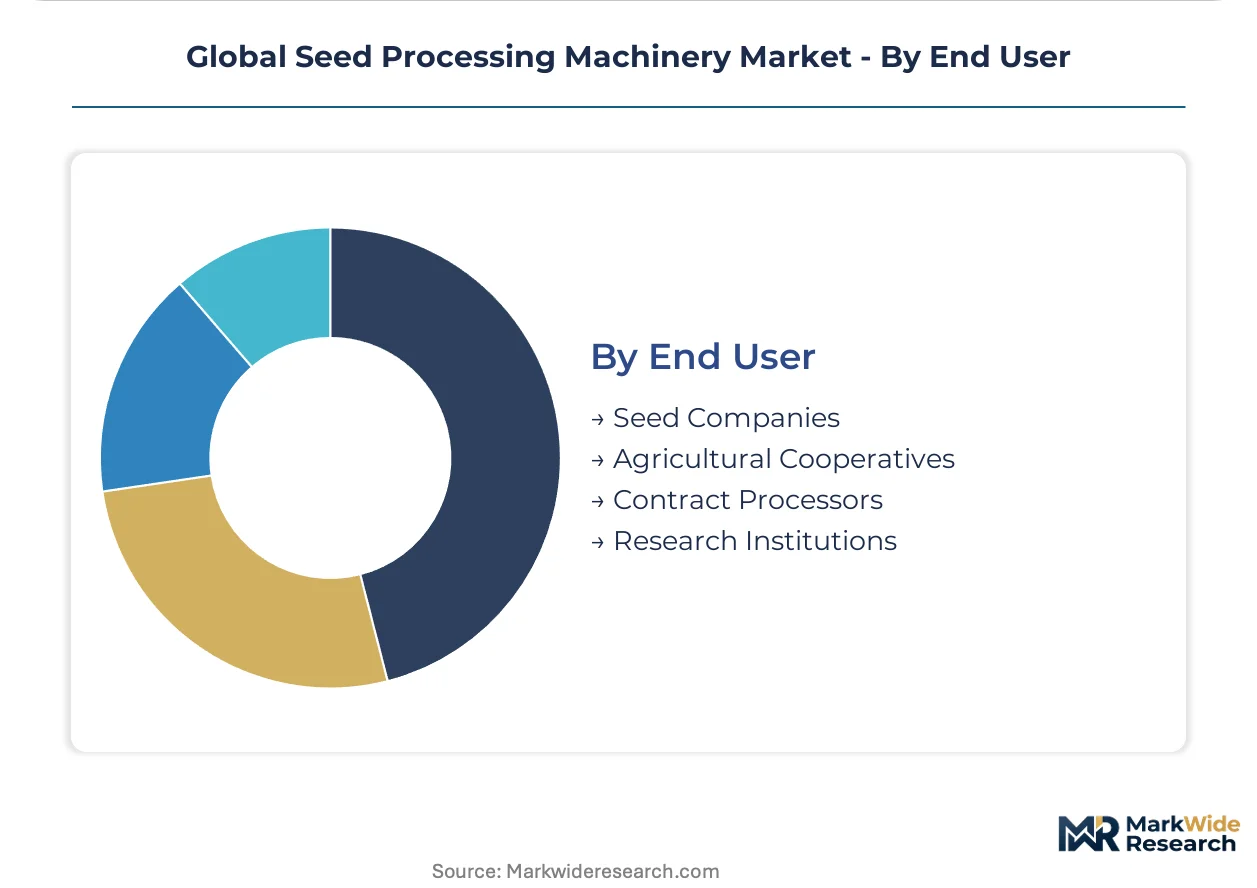
- Seed Companies:Integrated multinationals specify full-line optical sorting, precision coating, and automated packaging with outcome-based service contracts. Brazilian and German majors now demand uptime penalties and germination uniformity guarantees in procurement terms.
- Contract Processors:Third-party seed cleaning and treatment operations in Iowa and Saskatchewan serve integrated supply chains with capacity-flexible equipment configurations.
- Agricultural Cooperatives:Member-owned operations prioritize crop-flexible, mid-scale equipment with lower capital barriers.
- Research Institutions:Breeding programs and gene-edited variety development require laboratory-scale precision and segregation-capable processing for identity preservation protocols.
Seed companies anchor premium equipment demand. Contract processors represent the fastest-climbing customer segment on outsourced processing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across buyer segments. Brazilian and Indian processors prioritize capital efficiency and local service density. German and North American seed companies absorb premium pricing for optical sorting and precision coating systems that satisfy OECD certification protocols.
United States
Iowa and Saskatchewan contract processors deploy hyperspectral imaging arrays for gene-edited soybean and canola identity preservation. USDA-APHIS phytosanitary protocols mandate traceable lot handling systems that compress equipment qualification timelines. The North American Great Plains cluster anchors outsourced processing growth as integrated seed companies divest captive capacity.
Germany
Export-oriented hybrid maize programs drive demand for closed-loop chemical application systems with REACH-compliant containment architectures. ECHA substance evaluation timelines extend polymer formulation qualification cycles for seed coating equipment. Engineering heritage in precision mechanics sustains premium positioning for domestic manufacturers serving OECD-certified operations.
Brazil
Commercial seed companies in Mato Grosso expand pre-cleaning infrastructure to meet varietal purity mandates under OECD Seed Schemes. ANVISA chemical registration procedures constrain treatment system configurations for export-bound hybrid cotton programs. Domestic processors face certification infrastructure gaps relative to volume growth trajectories.
India
Hybrid maize and cotton export programs drive capacity scaling among commercial seed processors. BIS equipment standards and DGFT export protocols shape procurement specifications for cleaning and grading infrastructure. Gujarat and Maharashtra clusters concentrate domestic manufacturing of mid-scale pneumatic systems for regional contract processors.
Canada
Canola processors pilot near-infrared spectroscopy integration with camera-based sorting for real-time oil content grading. Health Canada and PMRA chemical compliance frameworks influence treatment system design for identity preservation infrastructure. Prairie province seed cleaning cooperatives prioritize modular equipment configurations with crop-flexible throughput.
Global Seed Processing Machinery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting the vendor base across integrated European manufacturers and regional assembly specialists. Premium-tier positioning concentrates among Swiss and German engineering houses with captive foundry networks and polymer formulation capabilities. Mid-scale processors in emerging markets source from regional specialists offering standardized pneumatic configurations. Competitive moves center on optical sorting module development and service contracting unbundling with performance guarantees.
Among Swiss and German engineering houses, Bühler AG and PETKUS Technologie GmbH occupy positions within the premium-tier optical sorting and precision coating segments. Cimbria A/S represents the Danish engineering heritage in air-separation technology for high-throughput cereal applications. These three exemplify how geographic concentration of mechanical engineering expertise shapes competitive positioning across equipment categories.
| Leading Market Players |
|---|
| Bühler AG |
| Cimbria A/S |
| PETKUS Technologie GmbH |
| Satake Corporation |
| Ag Growth International Inc. |
| Bratney Companies |
| Abel |
| US Global Resources |
| Ginhong |
| Others |
Supply & Pricing Matrix
Outcome-based service contracts with uptime penalties and germination uniformity guarantees lock in multi-year equipment access and price predictability for Brazilian and German seed companies seeking OECD certification compliance.
Pricing Analysis
After-sales revenue from spare parts, field service, and performance-guarantee contracts drives lifetime value beyond initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates Swiss and German engineering houses with captive foundry networks from regional assembly specialists in Gujarat and Maharashtra. Cost compression in mid-scale pneumatic equipment is intensifying because Indian and Brazilian processors prioritize capital efficiency over optical sorting premiums. Agricultural cooperatives exhibit highest price sensitivity, while integrated multinationals absorb premium positioning for identity preservation infrastructure.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints inflate inbound logistics costs for precision optics and stainless steel components. Manufacturing gravity centers on Switzerland, Germany, and Denmark for premium optical sorting and air-separation systems, while India and China anchor mid-scale pneumatic equipment assembly. Supply chains draw from specialty steel foundries, hyperspectral camera modules, and polymer formulation chemicals. Single-source vulnerability concentrates in European foundry capacity for high-capacity sorting line castings. Distribution runs through direct sales forces for premium tier and regional distributor networks for standard equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of electro-optical technicians capable of camera calibration and AI-driven defect recognition algorithm maintenance constrains optical sorting line deployment and aftermarket service density.
For Market Incumbents: Consolidate regional technical service networks to capture unbundled performance-guarantee contracts from Brazilian and German seed companies. Acquire captive foundry capacity to insulate against stainless steel casting lead time inflation. Vertical integration into polymer formulation capabilities defends margin position against REACH-compliant coating system retrofit demands. For New Entrants and Emerging Players: Remote diagnostics and predictive maintenance platforms represent a service-layer gap where incumbents under-serve mid-scale contract processors in Iowa and Saskatchewan. Target modular optical sorting retrofits for legacy pneumatic infrastructure as the most penetrable segment. Pursue outcome-based contracting with agricultural cooperatives as the primary go-to-market angle. For Investors and Strategic Acquirers: Danish and German engineering houses with deep air-separation expertise and established OECD certification track records present attractive acquisition target archetypes. Long-term viability hinges on gene-edited seed regulatory clarity reshaping identity preservation infrastructure demand. Monitor ECHA substance evaluation timelines for polymer formulation restrictions as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Module Development | Hyperspectral imaging arrays displace gravity tables in Iowa and Saskatchewan contract processing. |
| Regional Service Network Expansion | Brazilian Mato Grosso processors demand local technician density for OECD compliance uptime. |
| Polymer Formulation Capability Acquisition | REACH-compliant closed-loop architectures command premium positioning in German export programs. |
| Modular Retrofit System Launch | Legacy pneumatic integration in North American Great Plains reduces downtime during hybrid commissioning. |
| Near-Infrared Spectroscopy Integration | Real-time oil and protein grading pilots in Canadian canola operations enable content-based premiums. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with seed company operations directors, contract processing facility managers, electro-optical technician supervisors, and polymer formulation chemists. Secondary validation drew from OECD Seed Scheme certification databases, USDA-APHIS phytosanitary protocol filings, ECHA substance evaluation registers, and equipment import customs records. Bottom-up installation base modeling and top-down capital expenditure triangulation anchored market sizing.
Across the analysis window, forecasts incorporate product type segmentation by cleaning, treatment, grading, coating, and packing equipment; technology tier by optical, pneumatic, and mechanical systems; and crop application by cereal, oilseed, legume, vegetable, and pulse categories. CAGRs were derived from equipment replacement cycle compression rates and OECD certification infrastructure buildout trajectories. Near-infrared spectroscopy adoption curves and gene-edited seed regulatory scenario weights informed scenario-based projections.
Underlying assumptions cover stable OECD Seed Scheme varietal purity mandate enforcement, with deviation risk concentrated in CRISPR-derived variety classification rulings and ECHA polymer authorization timeline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Commercial Oil Extraction Machine Market
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
Global Tillage Equipment Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market