
 Hammer Mill Market | 2026-2036
Hammer Mill Market Size, Share, and Industry Trends Forecast 2026-2036
Hammer Mill Market Foresight
Stainless steel is expanding its share in hammer mill chamber construction, displacing carbon steel in food-grade and pharmaceutical applications where sanitation protocols have tightened. Bühler Group leverages its Swiss precision engineering heritage to dominate high-throughput grain milling installations across European food processors. ANDRITZ Group anchors its position through backward integration into pelletizing systems, bundling hammer mills with downstream densification equipment. Williams Patent Crusher & Pulverizer Co., Inc. specializes in heavy-duty mineral processing configurations, sustaining premium pricing in mining and aggregate sectors.
A hammer mill is a size reduction machine employing rotating hammers mounted on a central shaft to shatter feed material through repeated impact against breaker plates or grinding screens, with rotor speeds typically ranging from 1,800 to 3,600 rpm depending on material friability and desired particle distribution. Its primary industrial purpose spans comminution of biomass for biofuel feedstock, grinding of grains for animal nutrition, and pulverization of minerals for chemical processing. Horizontal hammer mills command the largest installed base in agricultural applications due to their throughput efficiency and simpler maintenance access, while laboratory-scale units represent the fastest-growing product category as pharmaceutical quality control labs intensify particle size validation protocols. Wood and biomass material segments concentrate margin pools in Europe and North America where renewable energy subsidies incentivize pellet production infrastructure.
The US Food and Drug Administration enforces Current Good Manufacturing Practice regulations that mandate cleanable surfaces and contamination prevention in pharmaceutical and food-contact hammer mill designs, directly elevating stainless steel specification rates. The European Medicines Agency and EFSA jointly influence equipment validation standards through their harmonized approach to process analytical technology in pharmaceutical manufacturing. China's National Medical Products Administration and Ministry of Ecology and Environment impose dual compliance burdens on imported equipment, requiring both sanitary design certifications and emissions controls for domestic assembly operations. Stakeholders must monitor evolving carbon border adjustment mechanisms and bioenergy subsidy phase-outs as these policy instruments will reconfigure regional equipment demand intensity faster than underlying feedstock growth alone.
Market Dynamics
Stainless steel specification in hammer mill chambers is accelerating as pharmaceutical and food-grade sanitation protocols tighten, forcing equipment replacement cycles in regulated processing environments. This material transition cascades through procurement criteria, maintenance scheduling, and capital allocation decisions across biomass, grain, and mineral processing verticals.
Growth Catalysts
- EU Green Deal renewable mandates:Biomass pellet producers in Germany are scaling hammer mill procurement to meet binding bioenergy targets, concentrating demand in European pelletizing corridors.
- US Inflation Reduction Act tax credits:Domestic renewable energy subsidies are accelerating equipment replacement in Iowa's agricultural processing belt, modernizing grain milling infrastructure.
- Rotor speed optimization technology:Variable frequency drive integration enables real-time adjustment between 1,800 and 3,600 rpm, expanding friable material processing flexibility for multi-feedstock operators.
Market Restraints
- Alloy steel input cost volatility:Hammer and screen replacement part pricing fluctuates with nickel and chromium commodity markets, compressing aftermarket margin pools for service providers.
- European equipment supply concentration:Swiss and Austrian precision engineering houses dominate high-throughput grain milling, limiting price competition in premium food-grade segments.
- Horizontal mill maintenance access limitations:Agricultural installations face extended downtime during rotor bearing replacement compared to vertical configurations, constraining throughput in seasonal harvest windows.
Strategic Opportunities
- India's Punjab agricultural corridor:Grain milling modernization in this high-intensity farming region offers replacement cycle acceleration as state subsidies support equipment upgrades.
- Laboratory-scale pharmaceutical validation:Quality control labs are intensifying particle size distribution protocols, creating demand for small-batch hammer mills with ISO 17025 calibration.
- Pharmaceutical process analytical technology convergence:Real-time particle monitoring integration with hammer mill controls enables continuous manufacturing compliance under EMA guidance.
Industry Challenges
- Stainless steel welding certification scarcity:Food-grade chamber fabrication requires ASME Section IX qualified welders, creating production bottlenecks for sanitary design orders.
- Legacy carbon steel fleet retrofit complexity:Existing agricultural installations face integration friction when upgrading to cleanable surfaces without full line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hammer Mill Market |
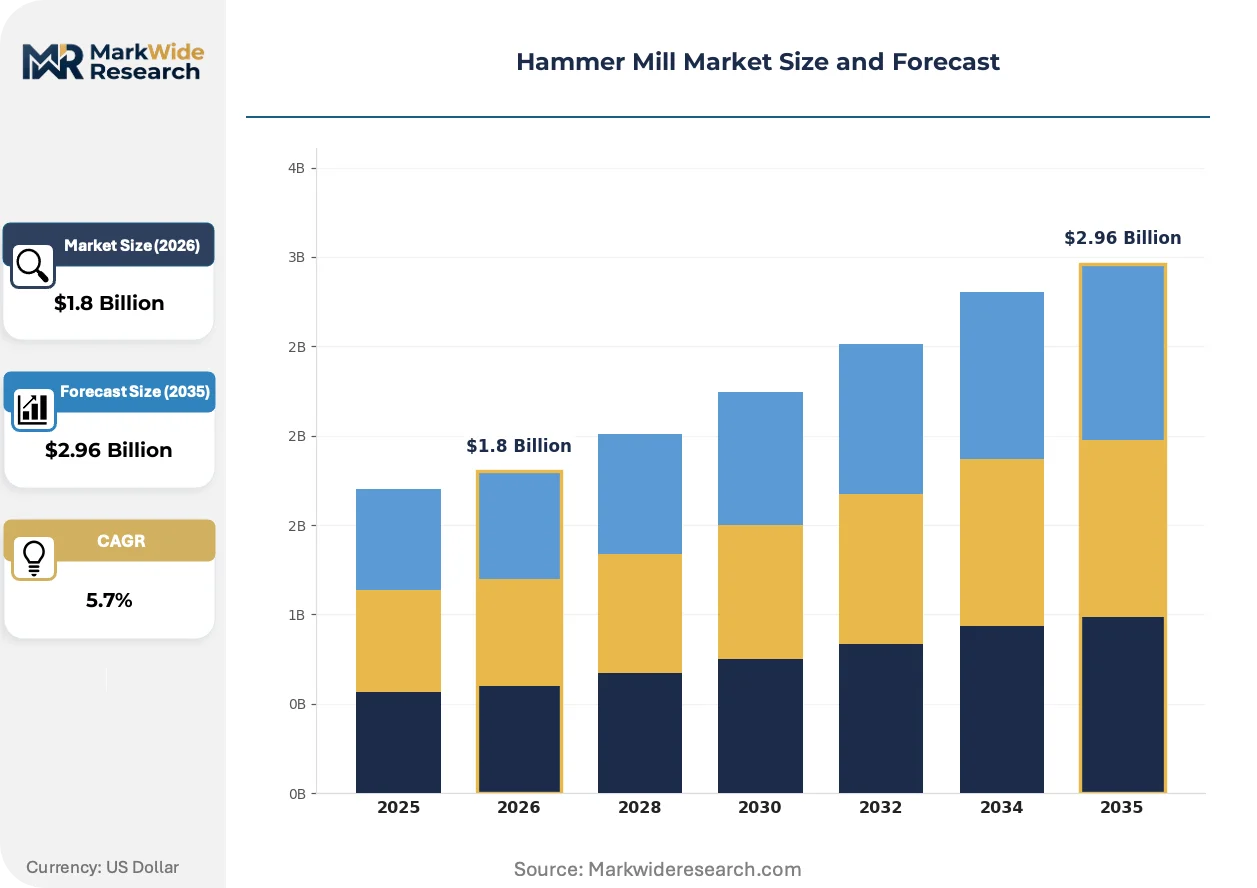
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Industrial, Laboratory Material: Wood, Biomass, Minerals, Grains End User: Agriculture, Food Processing, Pharmaceuticals, Chemicals Functionality: Crushing, Grinding, Shredding, Mixing |
| Companies Covered | Bühler Group, Prater Industries, Williams Patent Crusher & Pulverizer Co., Inc., Hosokawa Micron Powder Systems, Stedman Machine Company, Schutte-Buffalo Hammermill, LLC, CPM (California Pellet Mill), Munson Machinery Company, Inc., ANDRITZ Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hammer Mill Market Shifts & Advancements
Electrification of drive systems and digitalization of particle control are compressing maintenance intervals while expanding process validation capabilities. Equipment manufacturers are embedding sensors and connectivity to shift from mechanical reliability to data-driven uptime guarantees.
Permanent magnet synchronous motors are electrifying hammer mill drive trains, replacing induction motors with variable-speed precision that matches rotor torque to material friability in real time. Pharmaceutical manufacturers in Switzerland and Germany are adopting these systems to reduce energy intensity while maintaining batch-to-batch particle consistency. The technology is electrifying competitive positioning in premium segments where power consumption and validation documentation carry equal weight in procurement scoring.
REACH regulation substance restrictions on lubricants and surface coatings are forcing reformulation of bearing greases and chamber finishes in European-sourced equipment. Hammer mill suppliers serving EMA-regulated pharmaceutical facilities must now certify full material disclosure down to subcomponent level. Laboratory-scale units face the steepest compliance burden, as portable equipment historically relied on non-compliant coating systems for corrosion resistance.
Outcome-based service contracts are displacing transactional parts sales in North American biomass processing, with pellet producers purchasing guaranteed throughput rather than individual hammers and screens. Equipment vendors embed predictive wear monitoring to schedule replacement before failure, capturing lifetime value through uptime commitments. This model concentrates in the US Inflation Reduction Act-subsidized pellet corridor, where production tax credits make downtime costlier than premium service pricing.
Hammer Mill Market Segmentation
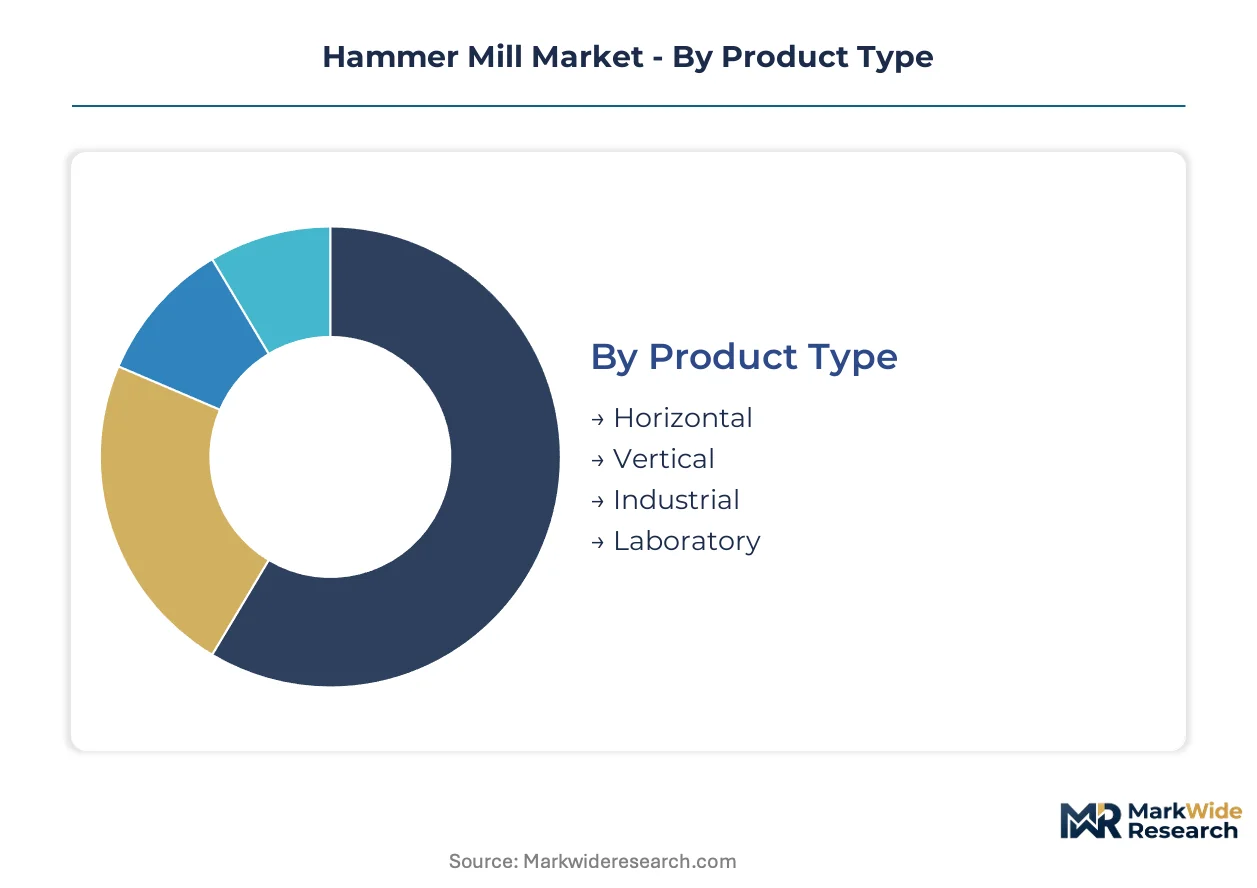
Hammer mill procurement decisions split sharply between throughput-intensive agricultural installations and precision-validated pharmaceutical systems. Equipment specification cascades through material compatibility, rotor configuration, and regulatory compliance requirements.
Product Type:
Horizontal designs dominate volume procurement, while laboratory units command premium pricing through calibration-intensive validation protocols.
- Horizontal:These mills orient the rotor shaft parallel to the ground, enabling gravity-assisted feed flow and simplified screen access for agricultural grain processing. Demand concentrates in Iowa's corn belt and Brazil's Mato Grosso soybean corridor, where seasonal harvest windows demand maximum uptime reliability.
- Laboratory:Bench-scale units feature sealed stainless steel chambers and ISO 17025-traceable particle measurement systems for pharmaceutical quality control. Swiss and German drug manufacturers are intensifying procurement as EMA process analytical technology guidance tightens batch validation requirements.
- Vertical:Rotor shafts mounted perpendicular to the base plate occupy compact footprints in space-constrained European food processing facilities.
- Industrial:Heavy-duty configurations with reinforced housings serve mineral pulverization in mining operations across Australia's Pilbara region.
Mature deployment sits with Horizontal designs. Newer deployment is concentrated in Laboratory units.
Material:
Biomass feedstock processing anchors replacement cycle intensity, while mineral applications sustain aftermarket parts revenue through abrasive wear.
- Biomass:Woody and herbaceous feedstocks for pellet production require hammer mills with hardened alloy hammers and variable frequency drives to manage moisture-induced friability variation. EU Green Deal renewable mandates in Germany and Poland are accelerating equipment procurement in Baltic Sea pelletizing corridors.
- Grains:Corn, wheat, and rice milling for animal nutrition and flour production demands sanitary designs with quick-clean chamber access. India's Punjab region is modernizing state-subsidized grain processing infrastructure, forcing replacement of legacy carbon steel installations.
- Wood:Forestry residue and sawdust comminution for biofuel feedstock concentrates margin pools in North American Pacific Northwest logging regions.
- Minerals:Limestone, gypsum, and phosphate rock pulverization for cement and fertilizer production drives demand for abrasion-resistant chamber liners in Saudi Arabia's mining sector.
Volume concentration remains with Grains. Steepest expansion trajectory belongs to Biomass.
End User:
Regulatory stringency separates pharmaceutical procurement scoring from agricultural price sensitivity.
- Agriculture:Feed mills and grain elevators prioritize throughput per kilowatt-hour and hammer replacement interval predictability. Brazil's integrated poultry and pork producers are consolidating milling operations, favoring larger-capacity units with automated screen change systems.
- Pharmaceuticals:Active ingredient micronization and excipient processing require FDA-validated clean-in-place designs with full material traceability. US generic drug manufacturers face heightened FDA Current Good Manufacturing Practice enforcement, elevating stainless steel specification rates.
- Food Processing:Spice grinding and cereal production in European facilities must comply with EFSA hygiene standards for food-contact surfaces.
- Chemicals:Specialty chemical and pigment manufacturers in China's Jiangsu province require explosion-proof configurations for combustible dust environments.
Procurement sophistication peaks in Pharmaceuticals. Volume scale dominates in Agriculture.
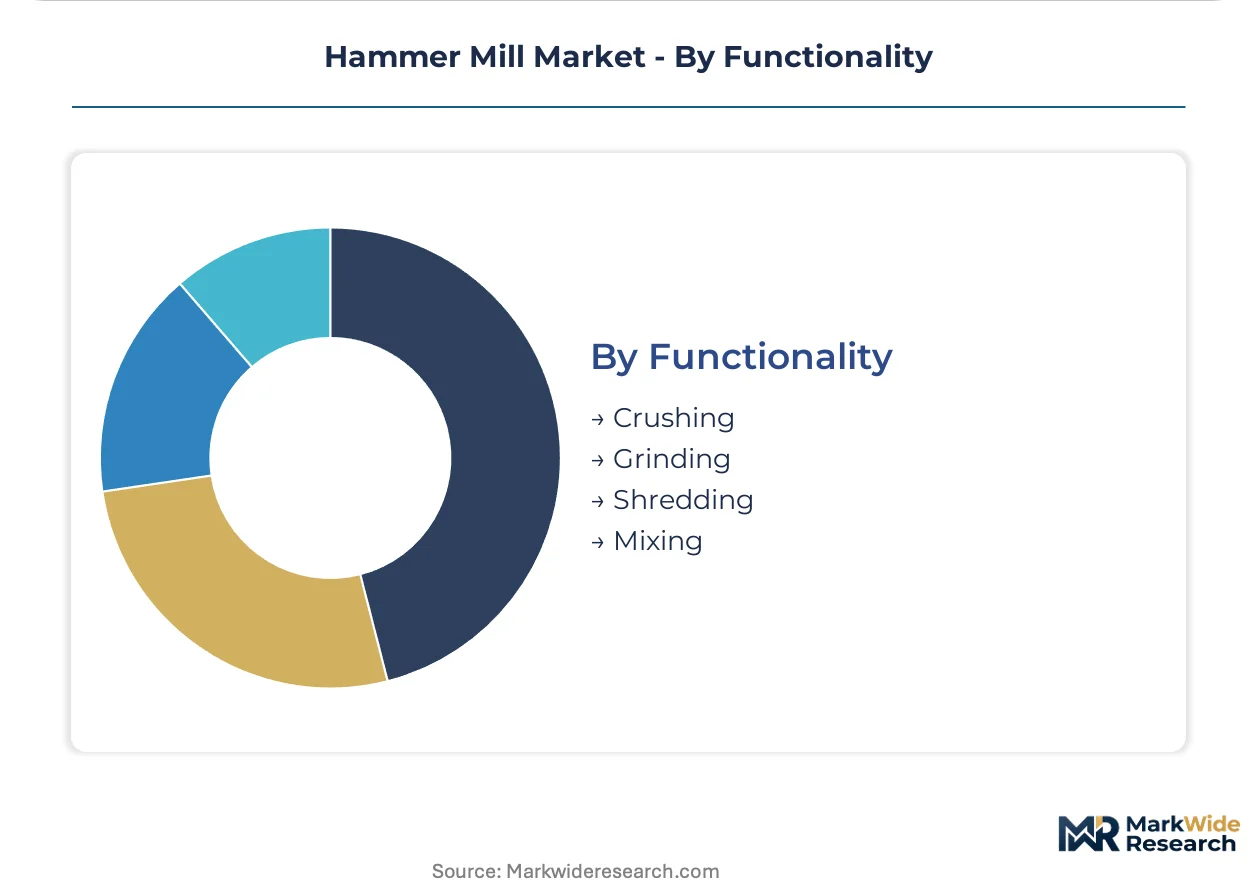
Functionality:
Grinding precision commands premium positioning, while crushing applications compete on capital cost recovery speed.
- Grinding:Controlled particle size reduction through repeated hammer-to-screen impact achieves narrow distribution curves for pharmaceutical and food-grade specifications. Variable rotor speed technology from 1,800 to 3,600 rpm is expanding flexibility for multi-product contract manufacturers.
- Crushing:Primary size reduction of large feedstock chunks prepares material for secondary processing stages. Mining operations in South Africa's platinum belt specify oversized infeed hoppers and reinforced breaker plates for ore fragmentation.
- Shredding:Tear-and-shear action with blunt hammer faces processes fibrous agricultural residues for composting applications.
- Mixing:Integrated hammer-and-paddle configurations homogenize blended feed formulations in integrated poultry operations.
Technology maturity centers on Grinding. Application expansion is fastest in Crushing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in agricultural processing belts where renewable energy mandates and grain milling modernization converge. Germany, the United States, Brazil, India, and China anchor regional demand through distinct policy mechanisms and feedstock specializations.
United States
Iowa's corn belt drives horizontal mill demand as ethanol producers retrofit facilities for diversified feedstock flexibility. The Inflation Reduction Act production tax credits accelerate equipment replacement cycles across Midwestern agricultural cooperatives. Pacific Northwest logging regions concentrate wood biomass processing infrastructure for export pellet markets.
Germany
Baltic Sea pelletizing corridors scale hammer mill procurement to meet binding EU Green Deal bioenergy targets. EMA process analytical technology guidance elevates validation requirements for pharmaceutical-grade installations. Bavarian precision engineering clusters supply high-throughput grain milling systems across European food processors.
Brazil
Mato Grosso soybean corridors demand maximum uptime reliability during compressed seasonal harvest windows. ANVISA sanitary regulations tighten food-contact surface specifications for integrated poultry and pork operations. São Paulo state's consolidated milling operations favor automated screen change systems for large-capacity units.
India
Punjab's agricultural corridor modernizes state-subsidized grain processing infrastructure, forcing carbon steel fleet replacement. FSSAI hygiene standards accelerate cleanable surface adoption in spice grinding operations. Gujarat's chemical manufacturing belt requires explosion-proof configurations for combustible dust environments.
China
Jiangsu province specialty chemical manufacturers drive demand for validated pharmaceutical micronization systems. NMPA and MEE impose dual compliance burdens requiring sanitary design certifications plus emissions controls for domestic assembly. Shandong Peninsula mining operations specify abrasion-resistant chamber liners for mineral pulverization.
Hammer Mill Market Competitive Landscape
Backward integration into pelletizing systems dominates the current landscape as vendors bundle hammer mills with downstream densification equipment. The vendor base separates into three tiers: Swiss-Austrian precision engineering houses commanding premium food-grade segments, North American heavy-duty specialists serving mining and aggregate applications, and Asian fabricators competing on capital cost recovery speed. Strategic archetypes include full-line system integrators, aftermarket service platforms, and niche pharmaceutical validation specialists. M&A activity and outcome-based service contract proliferation represent the dominant competitive vectors reshaping margin capture.
Within the precision engineering tier, Bühler Group and ANDRITZ Group exemplify divergent integration strategies. Bühler leverages its Swiss heritage to occupy premium positioning in high-throughput grain milling, while ANDRITZ anchors its offering through captive supply of pelletizing downstream equipment. Williams Patent Crusher & Pulverizer Co., Inc. represents the heavy-duty mineral processing archetype, sustaining differentiated positioning in abrasive wear applications where reinforced housing specifications command price premiums.
| Leading Market Players |
|---|
| Bühler Group |
| Prater Industries |
| Williams Patent Crusher & Pulverizer Co., Inc. |
| Hosokawa Micron Powder Systems |
| Stedman Machine Company |
| Schutte-Buffalo Hammermill, LLC |
| CPM (California Pellet Mill) |
| Munson Machinery Company, Inc. |
| ANDRITZ Group |
| Others |
Supply & Pricing Matrix
Biomass pellet producers in Germany and the United States concentrate procurement volume, anchoring contract-based long-term offtake pricing for high-throughput agricultural installations while pharmaceutical quality control labs sustain premium tier validation through ISO 17025 calibration requirements.
Pricing Analysis
Volume procurement in agricultural grain processing competes on capital cost recovery speed, while laboratory-scale pharmaceutical units command three-tier pricing structure across premium, standard, and economy levels based on certification grade and calibration traceability. Price differentiation stems from stainless steel chamber specification rates and variable frequency drive integration complexity. Pricing pressure intensifies in the standard tier as Asian fabricators compress delivery timelines for carbon steel agricultural configurations. Feed mill operators in Brazil's Mato Grosso corridor exhibit highest price sensitivity, whereas Swiss drug manufacturers prioritize validation documentation over unit economics.
Supply Chain Analysis
ASME Section IX qualified welder scarcity in Germany, Switzerland, and Austria constrains sanitary design order fulfillment, extending lead times for food-grade chamber fabrication. Raw material sourcing draws from nickel and chromium commodity markets for alloy hammers, permanent magnet synchronous motor components from East Asian electronics suppliers, and precision-machined rotors from Bavarian engineering clusters. Single-source vulnerability concentrates in certified welding labor pools serving EMA-regulated pharmaceutical facilities. Distribution runs through OEM-direct channels for large-capacity agricultural units and specialized validation distributors for laboratory-scale pharmaceutical equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hammer mill sector is consolidating around backward integration into pelletizing systems and downstream densification equipment, with captive supply of complete processing lines emerging as the dominant competitive lever.
For Market Incumbents: To counter Asian fabricator price compression in standard-tier agricultural equipment, Bühler Group and ANDRITZ Group should deepen captive supply of pelletizing downstream systems while locking in multi-year service contracts with US Inflation Reduction Act-subsidized biomass producers. Certification investment in ASME Section IX welding capacity will defend margin position in pharmaceutical-grade segments where labor scarcity creates order backlogs. For New Entrants and Emerging Players: Launch via outcome-based service contracts in North American biomass corridors, where pellet producers prioritize guaranteed throughput over capital expenditure. India's Punjab agricultural modernization program offers the most penetrable geography for mid-capacity grain milling units with state-subsidized financing. Target laboratory-scale pharmaceutical validation equipment through ISO 17025 calibration partnerships with Swiss and German quality control labs. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision engineering specialists with sanitary design certifications in Germany and Austria, where welding labor bottlenecks temporarily depress valuation multiples. Long-term viability over the next decade hinges on electrification technology integration and real-time particle monitoring capabilities. Watch for EU Green Deal bioenergy subsidy phase-out announcements as the critical inflection signal for European pelletizing corridor equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pelletizing Systems | ANDRITZ Group bundles hammer mills with densification equipment to capture lifetime value from biomass producers. |
| Permanent Magnet Synchronous Motor Adoption | Swiss pharmaceutical manufacturers reduce energy intensity while maintaining batch-to-batch particle consistency under EMA guidance. |
| ASME Section IX Welding Certification Investment | Food-grade chamber fabrication capacity alleviates production bottlenecks for sanitary design orders in regulated environments. |
| Outcome-Based Service Contract Proliferation | US pellet producers purchase guaranteed throughput rather than individual hammers and screens under Inflation Reduction Act incentives. |
| Laboratory-Scale ISO 17025 Calibration Partnership | Bench-scale units with traceable particle measurement systems meet intensifying EMA process analytical technology requirements. |
Research Methodology
Document review covered customs and trade data from agricultural processing equipment imports, SEC filings from publicly traded industrial machinery manufacturers, and EU Green Deal implementation progress reports, complemented by interviews with plant engineers at Iowa ethanol facilities, procurement leads at German pellet producers, and aftermarket service heads at Swiss precision engineering houses. Bottom-up equipment installation tracking and top-down market sizing triangulated volume estimates across biomass, grain, and mineral processing verticals.
Segment-level projections incorporate rotor configuration, material specification tier, and end-use regulatory stringency across the analysis window. CAGRs derive from feedstock growth trajectories, equipment replacement cycle acceleration, and subsidy program phase-in schedules. Key inputs include renewable energy mandate binding targets, grain milling modernization subsidy disbursement rates, and pharmaceutical batch validation protocol adoption curves.
Alloy steel commodity price volatility, welding certification labor pool expansion, and bioenergy subsidy program continuity are the dominant revision risks for forecast stability. Material deviation in these triggers warrants pause and re-evaluation of equipment demand intensity assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Commercial Oil Extraction Machine Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market