
 Global Agricultural Equipment Market | 2026-2036
Global Agricultural Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Equipment Market Analysis
Multi-source sourcing for precision agriculture components is hardening across the supplier base. John Deere leverages its captive electronics division to control sensor calibration protocols. CNH Industrial anchors European production through dedicated facilities in Italy and Germany. AGCO Corporation competes via Fendt-brand premium positioning in the high-horsepower tractor segment.
Agricultural equipment encompasses powered and non-powered machinery designed for soil preparation, planting, cultivation, harvesting, and post-harvest processing, with power ratings spanning 20 to 600+ horsepower and implement widths reaching 18 meters for modern air seeders. Its primary commercial purpose is to substitute mechanical energy for human and animal labor, thereby expanding operational acreage per farm unit while compressing seasonal task windows. Tractors occupy the largest value share within product type segmentation, serving as the universal platform for mounted and trailed implements across all farm scales. Precision Agriculture technology commands the fastest expansion trajectory within technology segmentation, driven by variable-rate application hardware and RTK-guided auto-steering retrofits. Robotics remains nascent but carries concentrated R&D investment, particularly in selective harvesting and weed identification systems where labor substitution economics prove most compelling.
The EPA regulates non-road diesel emissions through Tier 4 Final compliance mandates, while the EU enforces Stage V standards via the F-Gas Regulation and Machinery Directive frameworks. ISO 12100 safety standards govern design risk assessment, creating market access barriers for non-certified manufacturers. India's BIS and China's MIIT impose parallel localization requirements that shape regional product configurations. Stakeholders must monitor the divergence between EPA and EU emissions certification pathways, as dual compliance architectures will determine factory allocation and model availability across export markets.
Market Dynamics
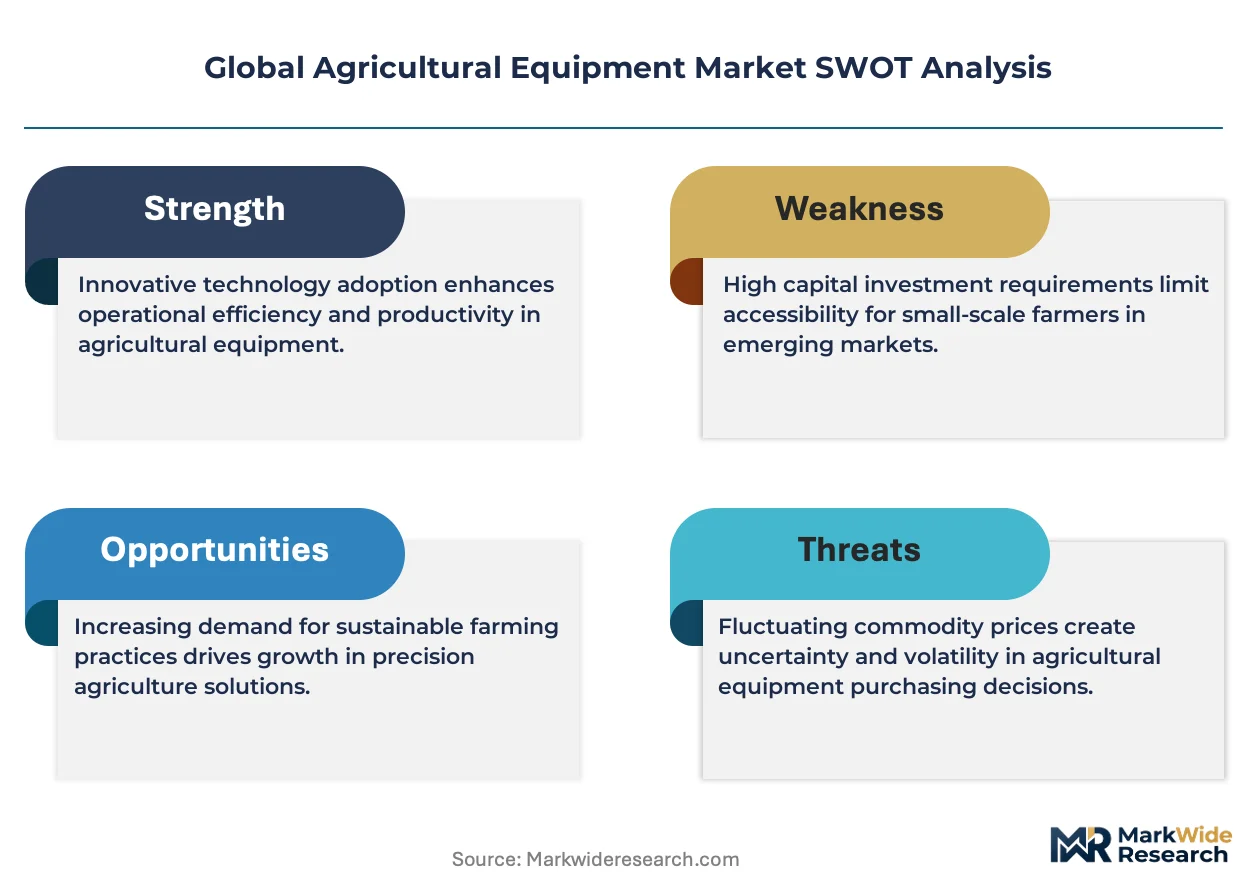
EPA Tier 4 Final and EU Stage V emissions mandates are forcing synchronous engine platform redesigns across all horsepower classes, compressing development cycles while elevating powertrain costs.
Growth Catalysts
- Black Sea Mechanization Wave:Large-scale grain operations in Ukraine and Russia are expanding tractor fleet densities to match North American productivity benchmarks.
- Precision Agriculture Hardware:RTK-guided auto-steering retrofits and variable-rate application systems are penetrating mid-scale farms previously priced out of guidance technology.
- EU F-Gas Regulation:Stage V compliance deadlines are accelerating replacement demand for pre-certified equipment across Eastern European markets.
Market Restraints
- Steel and Semiconductor Input Volatility:Hydraulic component foundries and ECU manufacturers face synchronized price pressure from commodity markets and chip allocation constraints.
- Engine Certification Concentration:EPA and EU Stage V homologation requirements favor vertically integrated powertrain producers, marginalizing smaller engine builders.
- Electrification Timeline Uncertainty:Battery energy density limitations and charging infrastructure gaps stall full-electric tractor commercialization in high-horsepower segments.
Strategic Opportunities
- Sub-Saharan Mechanization Gap:Ethiopia and Nigeria present unconsolidated demand for 40-80 horsepower utility tractors with localized service networks.
- Selective Harvesting Robotics:Computer vision and robotic end-effector convergence targets labor-intensive specialty crops with per-unit economics superior to manual picking.
- India PLI Scheme:Production-linked incentives for agricultural machinery manufacturing are attracting component localization investments in Gujarat and Punjab industrial corridors.
Industry Challenges
- Embedded Software Talent Scarcity:Precision agriculture divisions compete with automotive and consumer electronics sectors for firmware engineers specializing in sensor fusion and edge computing.
- Dual Certification Architecture Complexity:Divergent EPA and EU emissions test cycles force parallel validation protocols that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Equipment Market |
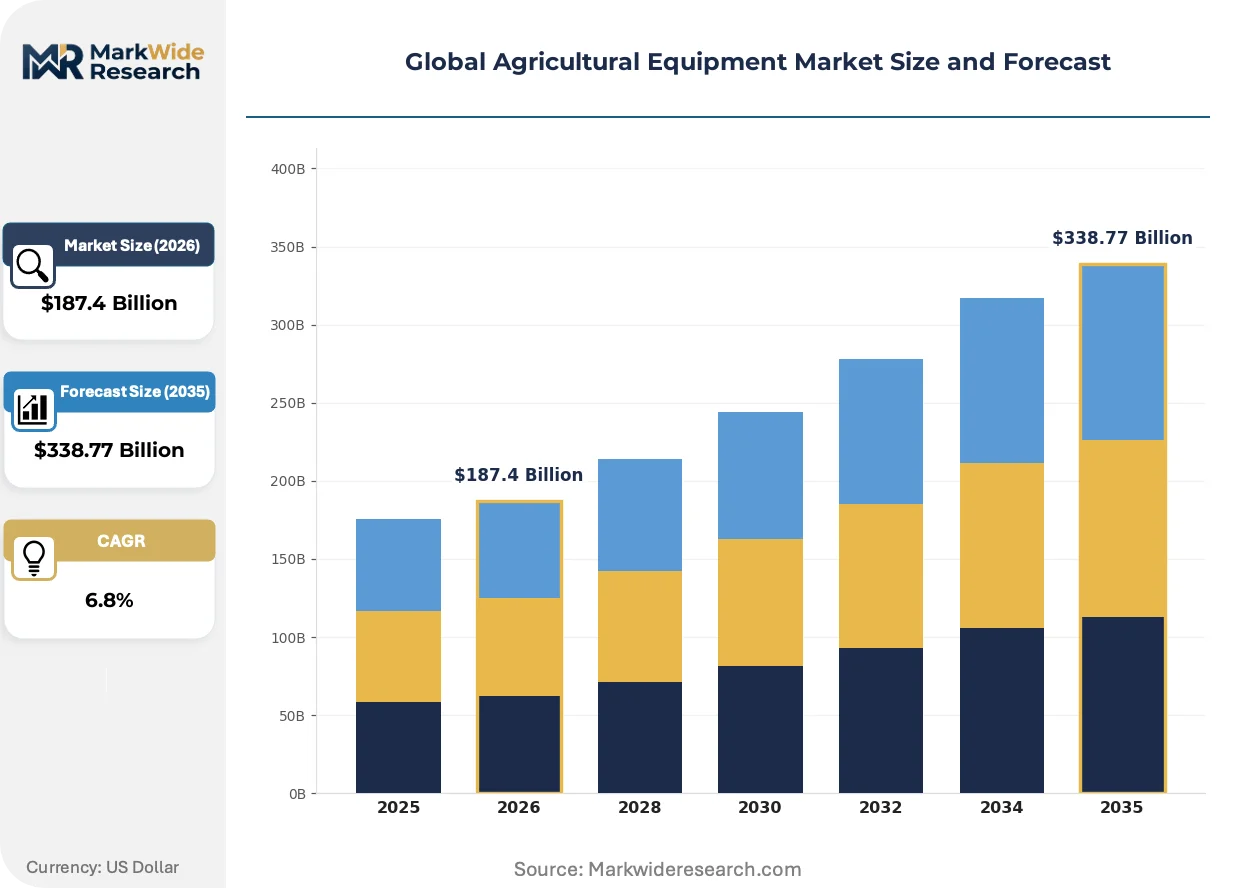
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Plows, Harvesters, Seeders End Use Industry: Crops, Livestock, Horticulture, Forestry Technology: Precision Agriculture, Autonomous Machinery, Internet of Things, Robotics Distribution Channel: Retail, Direct Sales, Online, Dealerships |
| Companies Covered | John Deere, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra & Mahindra, Claas, SDF Group, Caterpillar, JCB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Equipment Market Emerging Trajectories
Electrification architectures, autonomous navigation stacks, and data monetization platforms are simultaneously maturing, creating overlapping investment priorities for equipment manufacturers.
Autonomous tractor platforms are converging with swarm-coordination algorithms to enable multi-machine operations without human operators in cab. Large-scale row-crop enterprises in Brazil's Mato Grosso and the US Corn Belt are piloting these systems for 24-hour planting windows. This convergence is compressing the seasonal labor bottleneck while redefining fleet management software requirements.
EU Stage V standards via the F-Gas Regulation and Machinery Directive are mandating diesel particulate filter and selective catalytic reduction integration across all power classes above 56 kW. Engine manufacturers must reconfigure thermal management architectures to accommodate after-treatment packaging. High-horsepower tractor segments in Germany and France face the steepest compliance cost escalation, accelerating pre-buy activity ahead of enforcement deadlines.
Fleet management subscriptions are displacing outright ownership models among mid-scale cash-grain operators in the US Midwest and Canadian Prairies. Equipment-as-a-service providers bundle telemetry, predictive maintenance, and guaranteed uptime into per-acre pricing. This shift is most visible in soybean and corn operations where balance sheet flexibility outweighs asset control preferences.
Global Agricultural Equipment Market Segmentation
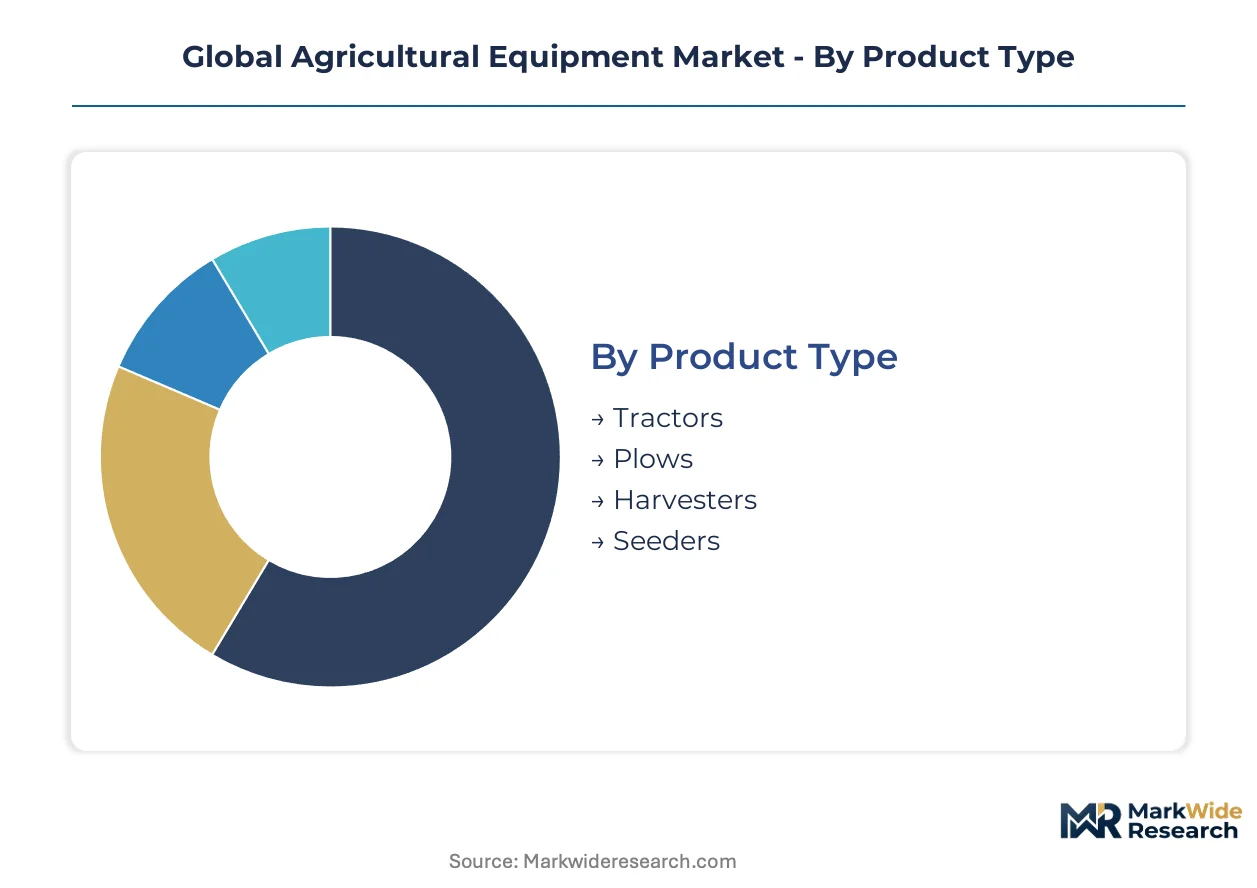
Segmentation in agricultural equipment reveals how certification burdens, application intensity, and channel economics concentrate margin capture. Equipment categories face divergent EPA Tier 4 Final and EU Stage V compliance timelines, while technology tiers separate capital deployment strategies across farm scales.
Product Type:
EPA Tier 4 Final and EU Stage V emissions mandates apply differentially across horsepower classes, with tractors above 56 kW facing the steepest after-treatment integration requirements and homologation costs.
- Tractors:Universal platform spanning 20 to 600+ horsepower serving as the mount point for implements across all farm scales. Fleet renewal in Brazil's Mato Grosso soybean belt and Ukraine's Black Sea grain corridor concentrates demand for 200+ horsepower models with RTK guidance compatibility.
- Harvesters:Self-propelled combines and forage harvesters integrate threshing, cleaning, and grain handling systems with engine ratings routinely exceeding 400 horsepower. Replacement cycles accelerate in Eastern Europe where Stage V pre-buy activity compresses purchasing windows ahead of enforcement deadlines.
- Plows:Trailed and mounted soil inversion implements ranging from 3 to 12 furrow configurations. Demand tracks arable land expansion in Russia and Kazakhstan where conventional tillage persists.
- Seeders:Air seeders and precision planters with implement widths reaching 18 meters for large-scale row-crop operations. Variable-rate application hardware integration drives specification upgrades in North American corn and soybean systems.
Leading the category by volume: Tractors. Growing fastest: Harvesters.
End Use Industry:
Application intensity determines equipment utilization rates and financing structures, with crop operations supporting shorter payback periods on precision technology investments than perennial systems.
- Crops:Annual grain and oilseed production requiring seasonal equipment deployment across soil preparation, planting, cultivation, and harvesting phases. Large-scale operations in Iowa and Illinois generate concentrated demand for high-horsepower tractors and combines with telemetry integration.
- Livestock:Dairy and beef operations utilizing feed handling, manure management, and pasture maintenance equipment. Automated feeding systems and robotic milking installations compete for capital allocation against field machinery in European dairy regions.
- Horticulture:Specialty crop and vegetable production with elevated labor intensity driving selective harvesting robotics development. California's Central Valley and Spain's Almería greenhouse clusters pilot computer-vision guided picking systems.
- Forestry:Logging and biomass operations requiring specialized feller-bunchers, forwarders, and chippers with reinforced structures. Nordic markets enforce stringent emissions compliance for mechanized harvesting in sensitive watersheds.
Dominant by equipment value: Crops. Steepest technology upgrade trajectory: Horticulture.
Technology:
Patent density and firmware development costs create tiered entry barriers, with precision agriculture hardware requiring sensor fusion expertise that competes with automotive and consumer electronics sectors for engineering talent.
- Precision Agriculture:Variable-rate application systems, yield mapping, and RTK-guided auto-steering retrofits enabling sub-inch accuracy. Mid-scale farms in the Canadian Prairies previously priced out of guidance technology now access subscription-based correction services.
- Autonomous Machinery:Operator-less tractor platforms with swarm-coordination algorithms for multi-machine 24-hour operations. Brazil's Mato Grosso pilots these systems for compressed planting windows during optimal soil moisture conditions.
- Internet of Things:Telemetry-enabled predictive maintenance and fleet optimization platforms. Equipment-as-a-service providers bundle uptime guarantees into per-acre pricing for Midwest cash-grain operators.
- Robotics:Selective harvesting and weed identification systems targeting labor substitution economics in specialty crops. R&D investment concentrates on strawberry and apple picking where manual labor costs exceed robotic unit economics.
Widest installed base: Precision Agriculture. Narrowest but fastest-climbing penetration: Robotics.
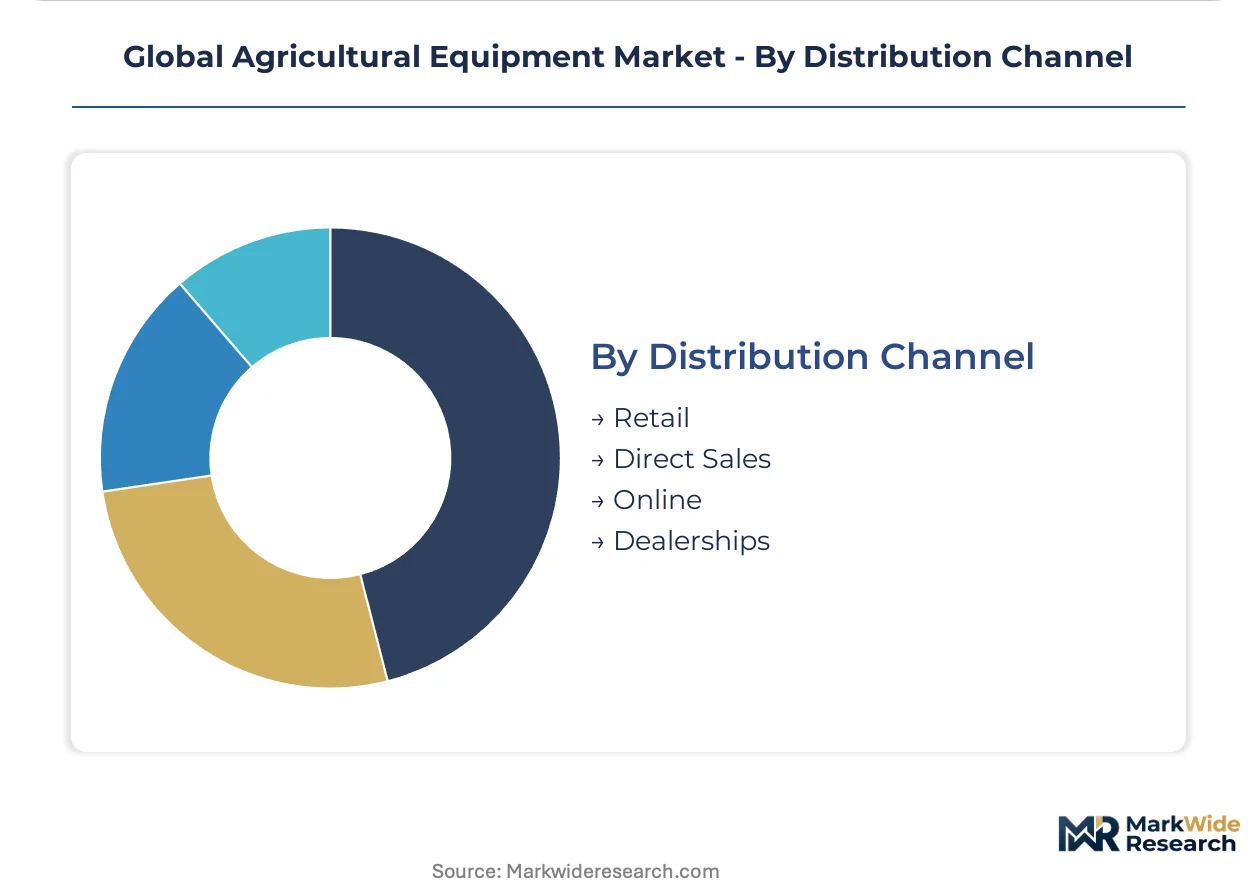
Distribution Channel:
Channel selection reflects customer scale, service dependency, and balance sheet preferences, with fleet operators prioritizing proximity to technical support over transaction efficiency.
- Dealerships:Manufacturer-authorized networks providing sales, financing, parts, and field service integration. John Deere and CNH Industrial anchor competitive positioning through captive dealer financing and certified technician training.
- Direct Sales:Factory-direct relationships for large fleet operators and agricultural cooperatives purchasing 50+ unit orders. Major grain producers in Ukraine and Russia negotiate volume pricing with dedicated account management.
- Retail:General agricultural supply stores serving smallholder and hobby farm segments with compact tractors and implements. India's Punjab and Gujarat corridors distribute 40-80 horsepower utility tractors through localized retail networks.
- Online:Digital platforms for parts, attachments, and used equipment transactions. Secondary market liquidity improves for precision agriculture components with standardized telemetry compatibility.
Highest transaction volume: Dealerships. Most rapid channel shift: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel from Pittsburgh and Dortmund feeds foundries that cast tractor frames. Component sourcing stretches from Stuttgart's precision hydraulics to Seoul's semiconductor packaging plants.
United States
Iowa and Illinois corn-soybean operations drive 300+ horsepower tractor demand with telemetry integration. EPA Tier 4 Final compliance deadlines compress replacement cycles in the Corn Belt. Moline, Illinois anchors John Deere's domestic production footprint for row-crop platforms.
Brazil
Mato Grosso soybean belt fleet renewal outpaces global averages with 24-hour planting window requirements. ANVISA and IBAMA emissions protocols shape equipment import specifications. Ribeirão Preto industrial corridor concentrates assembly capacity for South American distribution.
Germany
EU Stage V F-Gas Regulation accelerates pre-buy activity ahead of enforcement deadlines. KBA homologation requirements favor vertically integrated powertrain producers. Mannheim and Frankfurt-Rhine-Main clusters host CNH Industrial and Claas engineering centers for high-horsepower development.
India
Punjab and Gujarat corridors generate unconsolidated demand for 40-80 horsepower utility tractors with localized service networks. BIS localization requirements and PLI scheme incentives attract component manufacturing investments. Ludhiana industrial belt supplies transmission castings to domestic and export markets.
China
MIIT dual carbon goals and non-road diesel emissions standards reshape domestic equipment specifications. Shandong Peninsula foundries and Henan assembly plants serve mechanization demand in the North China Plain. Zhengzhou and Luoyang clusters concentrate state-owned enterprise production capacity.
Global Agricultural Equipment Market Vendor Landscape
Strategic partnerships dominate the current landscape as powertrain suppliers align with guidance technology developers. The vendor base organizes into three tiers: integrated full-line manufacturers, regional specialists in utility tractor segments, and component suppliers capturing precision agriculture module value. Archetypes include captive electronics divisions controlling sensor calibration, European engineering centers anchoring premium positioning, and Asian scale producers serving price-sensitive smallholder markets. M&A activity and capacity expansion in Eastern European markets represent the dominant competitive moves.
Among integrated full-line manufacturers, John Deere and CNH Industrial exemplify archetypes of captive technology control and European production anchoring respectively. AGCO Corporation occupies a position representing premium-brand positioning through specialized subsidiary structures. These three entities demonstrate how competitive positioning stratifies across precision agriculture capability, emissions certification depth, and regional service network density.
| Leading Market Players |
|---|
| John Deere |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra |
| Claas |
| SDF Group |
| Caterpillar |
| JCB |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps in Italy's Emilia-Romagna and Germany's Baden-Württemberg anchor premium tractor assembly, wielding pricing discipline through captive after-sales networks while sourcing precision hydraulics from Stuttgart and electronics from Seoul.
Pricing Analysis
Warranty and service bundling separates John Deere's telemetry-inclusive subscriptions from unbundled base-unit transactions common in India's Punjab retail corridor. Three-tier pricing structure across premium, standard, and economy levels tracks horsepower class and EPA Tier 4 Final certification status. Cost compression in the mid-horsepower tier is intensifying because semiconductor allocation constraints elevate ECU costs. Smallholder operators in Sub-Saharan Africa exhibit the highest price sensitivity, while large-scale grain producers in Brazil's Mato Grosso prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Reverse-logistics flows for remanufactured transmissions and rebuilt hydraulic pumps concentrate in Moline, Illinois and Mannheim, Germany, feeding secondary markets across the Midwest and Eastern Europe. Steel casting and forging capacity rests on Pittsburgh and Dortmund foundries, while semiconductor packaging draws from Seoul and Taipei. Single-source vulnerability in precision sensor supply threatens RTK guidance system availability. Distribution runs through manufacturer-authorized dealerships with certified technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The agricultural equipment sector occupies a technology-transition phase as precision agriculture hardware and autonomous navigation stacks displace mechanical-hydraulic legacy platforms across all horsepower classes.
For Market Incumbents: To counter embedded software talent scarcity draining engineering teams to automotive and consumer electronics sectors, secure firmware capabilities through acquisition of specialist sensor-fusion developers in Germany's Frankfurt-Rhine-Main cluster. Anchor competitive positioning through backward integration into ECU manufacturing, insulating against semiconductor allocation volatility.
For New Entrants and Emerging Players: Autonomous swarm-coordination algorithms offer a technology-first wedge into Brazil's Mato Grosso and Ukraine's Black Sea grain corridor, where 24-hour planting windows command premium pricing. Target the 40-80 horsepower utility tractor segment in Ethiopia and Nigeria, where unconsolidated demand and absent service networks create white-space entry. Pursue equipment-as-a-service per-acre pricing to bypass capital-constrained smallholder financing barriers.
For Investors and Strategic Acquirers: EPA and EU Stage V homologation deadline pre-buy surges are the leading indicator that replacement cycle compression will concentrate margin capture among vertically integrated powertrain producers. Over the projection horizon, prioritize acquisition targets with captive emissions certification capabilities and established dealer financing arms. Monitor embedded software talent migration rates from agricultural OEMs to automotive for early signals of R&D capacity erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Module Integration | RTK-guided auto-steering retrofits penetrate mid-scale Canadian Prairie farms previously priced out. |
| Emissions Certification Investment | Dual EPA Tier 4 Final and EU Stage V homologation opens export access across North America and Europe. |
| Swarm-Coordination Algorithm Development | Multi-machine 24-hour operations compress seasonal planting windows in Brazil's Mato Grosso. |
| Equipment-as-a-Service Platform Launch | Per-acre pricing with uptime guarantees displaces outright ownership among Midwest cash-grain operators. |
| Selective Harvesting Robotics R&D | Computer vision and robotic end-effector convergence targets labor-intensive California Central Valley specialty crops. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with OEM platform engineers, aftermarket service heads, agricultural cooperative procurement managers, and precision agriculture firmware developers. EPA certification databases, EU Stage V homologation registries, AEM equipment shipment statistics, and OECD agricultural mechanization indices supplied validation layers. Bottom-up equipment unit economics and top-down regional demand aggregation were triangulated against manufacturer production disclosures.
Granularity-level modeling tracked tractors, harvesters, and precision agriculture technology across horsepower tiers, emissions certification status, and farm-scale deployment patterns. CAGRs were derived from replacement cycle compression analysis and mechanization penetration curves. Forecast inputs incorporated EPA Tier 4 Final compliance timelines, EU F-Gas Regulation enforcement windows, and Brazil's ANVISA import specification shifts.
Several conditions sit outside the modeled scope, including geopolitical disruption to Black Sea grain corridor operations and breakthrough battery energy density enabling commercial full-electric high-horsepower tractors. Forecasts reflect assumptions about semiconductor supply normalization and steel price stability. Practitioners should monitor embedded software talent migration rates and dual-certification timeline divergence for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market