
 Asia-Pacific Agricultural Sprayer Market | 2026-2036
Asia-Pacific Agricultural Sprayer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agricultural Sprayer Market Outlook
Precision-grade spraying capability is rotating toward the center of competitive strategy in the Asia-Pacific Agricultural Sprayer Market. Deere & Company leverages its automated guidance systems to dominate premium tractor-mounted configurations across Australian broadacre operations. Mahindra & Mahindra Ltd anchors its position through extensive dealership networks penetrating India's tier-two agrarian districts. Kubota Corporation specializes in compact electric sprayers tailored to Japan's fragmented paddy field geometries.
An agricultural sprayer is a field implement engineered to distribute liquid crop protection agents, fertilizers, or growth regulators through pressurized nozzles with calibrated droplet spectra, typically operating at 1–10 bar working pressure depending on canopy penetration requirements. The device serves the essential commercial purpose of maximizing chemical efficacy while minimizing off-target drift and input waste. Tractor-mounted sprayers command the dominant share of value owing to their integration with high-horsepower platforms serving Australia's expansive wheat belts and China's Northeast Plain corn-soy rotations. Battery-powered technology represents the fastest-expanding segment as lithium-ion pack costs decline and Southeast Asian plantation operators seek to reduce diesel dependency. Knapsack sprayers retain volume significance across India's smallholder plots below two hectares, though margin pools remain thin due to commoditization.
India's BIS certification mandates for agricultural machinery safety and China's GB standards for pesticide application equipment establish baseline technical thresholds that filter out low-quality imports. Australia's TGA-equivalent agricultural chemical regulator, the APVMA, enforces strict drift mitigation labeling that directly shapes nozzle specification requirements for equipment sold into that market. Stakeholders must monitor how Japan's METI energy-efficiency benchmarks for battery-powered farm equipment will cascade into design requirements across ASEAN supply chains.
Market Dynamics
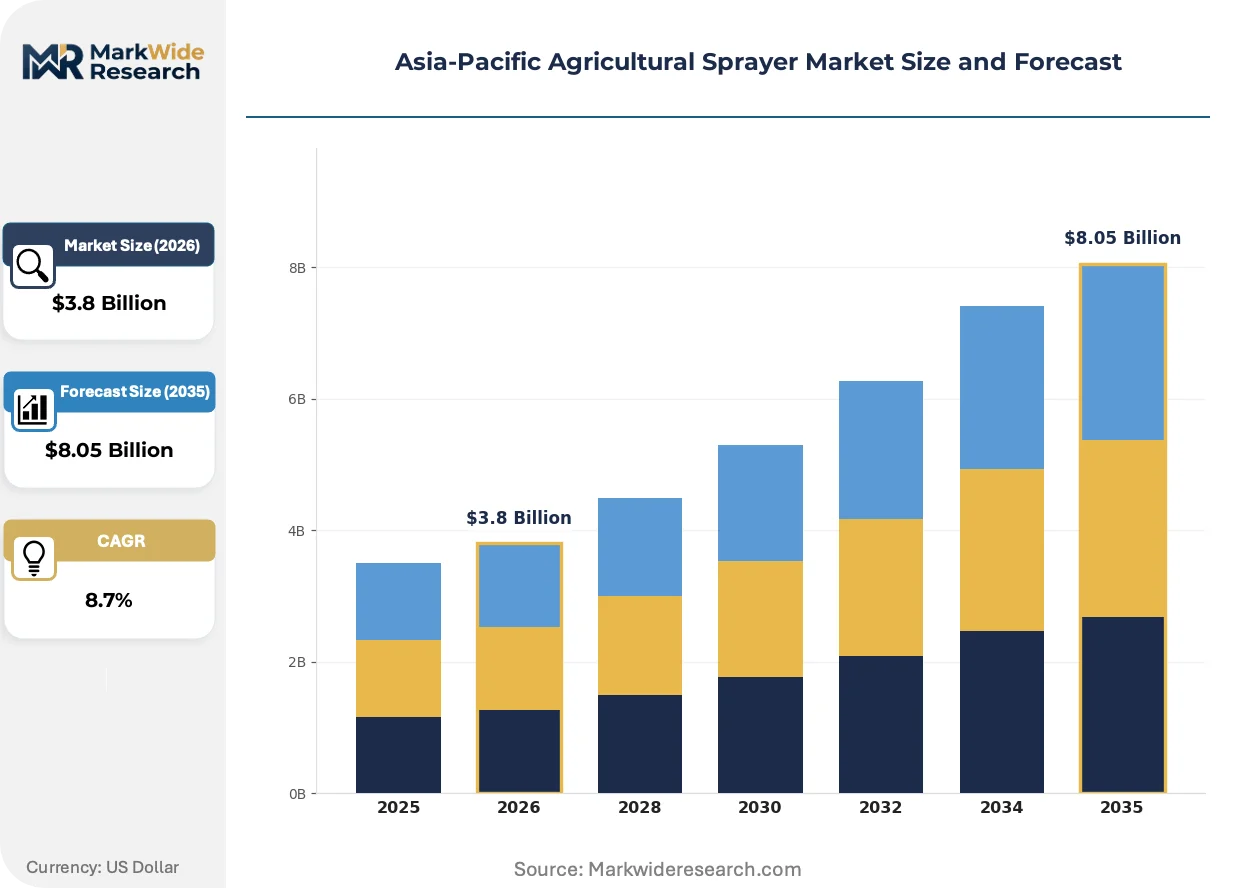
India's PLI scheme for farm mechanization and China's MIIT precision agriculture push are redistributing procurement incentives toward certified equipment, forcing fleet renewal cycles to compress across the Indo-Gangetic Plain and Northeast Plain farming belts.
Growth Catalysts
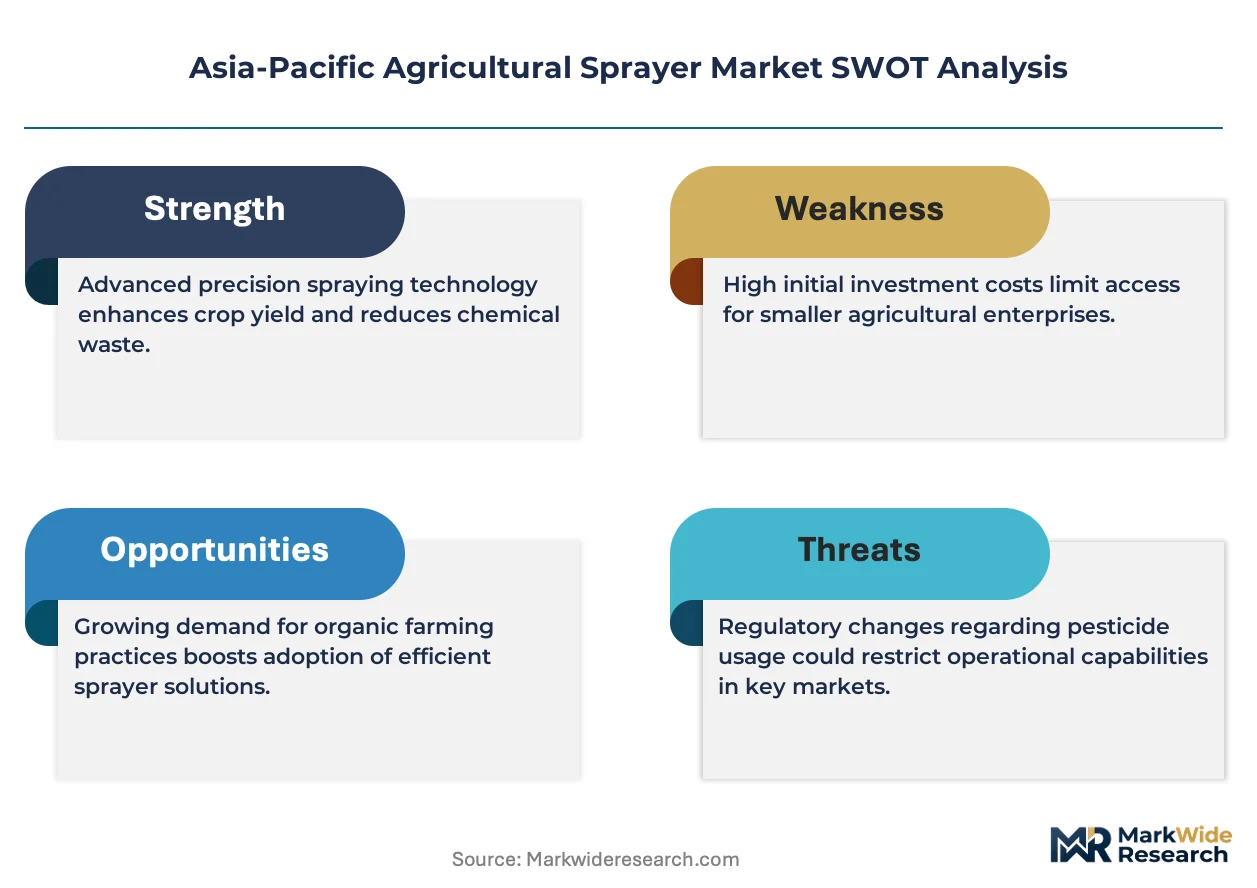
- India's PLI scheme for farm mechanization:Large-scale rice and wheat farming cooperatives in India's Indo-Gangetic Plain states are accelerating sprayer fleet replacement to capture production-linked incentives.
- Li-ion pack cost curves:Southeast Asian plantation operators are pivoting from diesel-powered units to battery-electric sprayers as lithium-ion battery economics improve.
- Canopy penetration requirements:Australia's APVMA drift mitigation labeling is mandating precision nozzle specifications that upgrade equipment across Queensland and New South Wales broadacre operations.
Market Restraints
- Steel and aluminum input volatility:Boom and chassis fabrication costs fluctuate with base metal prices, squeezing margin pools for domestic Indian and Chinese manufacturers.
- BIS certification timelines:India's Bureau of Indian Standards safety mandates for agricultural machinery create 8-14 month approval windows that throttle import velocity from non-compliant suppliers.
- Manual knapsack persistence:India's sub-two-hectare smallholders continue relying on handheld sprayers despite mechanization incentives, capping premium equipment penetration in the volume tier.
Strategic Opportunities
- Vietnam's Mekong Delta plantation consolidation:Corporate farming ventures in Vietnam are creating concentrated demand for tractor-mounted boom sprayers as land holdings scale beyond 50 hectares.
- Japan's METI energy-efficiency benchmarks:Battery-powered farm equipment standards are cascading into ASEAN supply chain design requirements, favoring early-compliant exporters.
- Variable-rate application convergence:Integration of GPS-guided boom control with real-time canopy sensors is opening premium service-contract revenue streams in Australia's wheat belts.
Industry Challenges
- Precision agriculture technician scarcity:Australia's broadacre operations face shortages of operators capable of calibrating automated guidance systems and nozzle control networks.
- Legacy fleet integration friction:Indian farming cooperatives struggle to retrofit older tractor platforms with ISOBUS-compatible sprayer implements, delaying precision upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agricultural Sprayer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knapsack Sprayer, Boom Sprayer, Handheld Sprayer, Tractor Mounted Sprayer End Use Industry: Crops, Horticulture, Forestry, Landscaping Technology: Manual, Automated, Electric, Battery Powered Application: Pesticide, Fertilizer, Herbicide, Others |
| Companies Covered | Deere & Company, Mahindra & Mahindra Ltd, CNH Industrial N.V., AGCO Corporation, Kubota Corporation, ASPEE Agro Equipment Pvt Ltd, Iseki & Co., Ltd, Escorts Limited, Daedong Industrial Co., Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agricultural Sprayer Market Strategic Shifts
Electrification and automation are fragmenting the traditional sprayer value chain, with powertrain substitution and sensing convergence creating distinct competitive arenas across the Asia-Pacific farming belt.
Electrostatic spraying technology is decomposing conventional hydraulic nozzle architectures by inducing charge on droplets to improve deposition efficiency on target leaf surfaces. Australian cotton and vineyard operators are piloting retrofitted electrostatic booms to reduce chemical volumes by 15-30 percent while maintaining coverage uniformity. This charge-assist approach is compressing the addressable market for standard flat-fan nozzles in high-value crop segments.
China's GB standards for pesticide application equipment are tightening drift reduction requirements and mandating droplet spectrum testing for all certified sprayers sold domestically. Equipment manufacturers must redesign nozzle manifolds and pressure regulation systems to meet the revised technical thresholds. The compliance burden falls heaviest on low-cost knapsack producers in Zhejiang and Shandong provinces, accelerating consolidation toward precision-capable suppliers.
Cooperative procurement collectives in India's Punjab and Haryana states are consolidating equipment purchasing through state agricultural machinery corporations, bypassing traditional dealer networks. These bulk tender arrangements prioritize total cost of ownership metrics and standardized service contracts over upfront equipment pricing. The channel shift is most visible in tractor-mounted sprayer categories above 400-liter tank capacity, where cooperative volume now exceeds individual farm purchases.
Asia-Pacific Agricultural Sprayer Market Segmentation
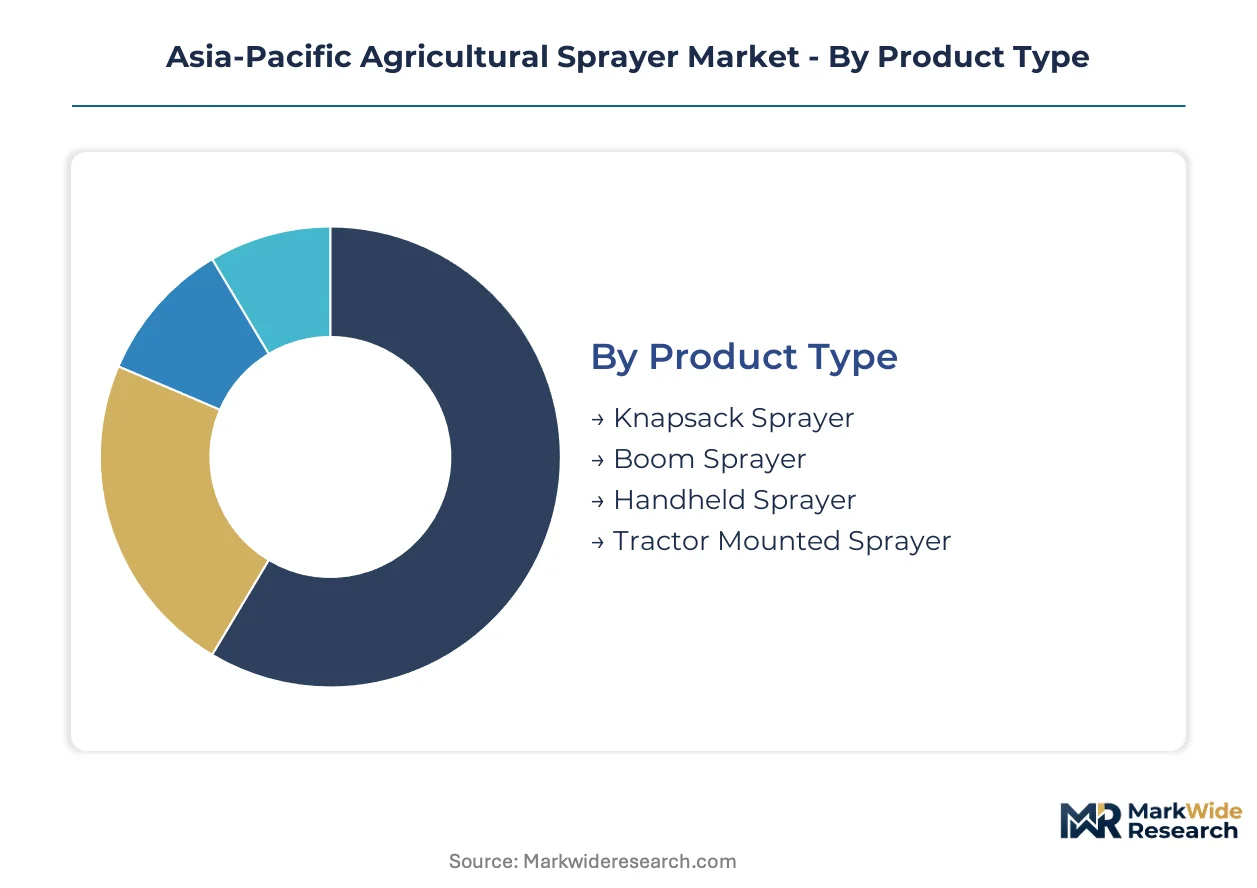
Equipment configuration and powertrain choices fragment the Asia-Pacific Agricultural Sprayer Market into distinct competitive arenas. Each segmentation dimension carries different margin profiles and regulatory exposure across India's cooperative procurement systems, China's precision agriculture mandates, and Australia's drift mitigation enforcement.
Product Type:
Margin pools concentrate most heavily in tractor-integrated configurations where ISOBUS compatibility and precision nozzle control command premium positioning.
- Tractor Mounted Sprayer:These units integrate with high-horsepower platforms through standardized electronic control architectures, serving Australia's Queensland and New South Wales broadacre wheat operations where 400-liter plus tank capacities dominate procurement tenders. India's Punjab and Haryana farming cooperatives are consolidating fleet purchases through state machinery corporations, prioritizing total cost of ownership metrics and standardized service contracts over upfront equipment pricing.
- Boom Sprayer:Articulated boom assemblies with GPS-guided section control enable variable-rate application across Vietnam's Mekong Delta plantation consolidation, where corporate farming ventures scaling beyond 50 hectares generate concentrated demand for precision spraying infrastructure.
- Knapsack Sprayer:India's sub-two-hectare smallholders in Bihar and Uttar Pradesh continue relying on handheld units despite mechanization incentives, capping premium equipment penetration in the volume tier where margin pools remain thin due to commoditization.
- Handheld Sprayer:Compact units serve Japan's fragmented paddy field geometries where field access constraints prevent tractor deployment.
The dominant share belongs to Tractor Mounted Sprayer configurations, while Boom Sprayer is closing the gap fastest as plantation consolidation accelerates.
End Use Industry:
Application intensity and chemical input volumes determine equipment specification requirements across farming systems.
- Crops:Rice and wheat farming cooperatives across India's Indo-Gangetic Plain states drive the heaviest sprayer utilization rates, with irrigation infrastructure expansion triggering fleet renewal cycles that favor certified equipment under PLI scheme incentives.
- Horticulture:Australia's APVMA drift mitigation labeling mandates precision nozzle specifications for vineyard and orchard operators in South Australia and Victoria, where electrostatic spraying retrofits are reducing chemical volumes while maintaining coverage uniformity.
- Forestry:Plantation operators in Indonesia and Malaysia deploy high-clearance boom configurations for oil palm canopy penetration.
- Landscaping:Municipal and golf course maintenance contracts in Japan and South Korea specify compact electric units for noise-sensitive applications.
Crops commands the largest installed base, though Horticulture is expanding most quickly as high-value crop protection intensifies.
Technology:
Powertrain substitution is fragmenting competitive positioning as lithium-ion economics improve and regulatory pressure on diesel emissions intensifies.
- Battery Powered:Southeast Asian plantation operators are pivoting from diesel-powered units as lithium-ion pack costs decline, with Japan's METI energy-efficiency benchmarks for battery-powered farm equipment cascading into ASEAN supply chain design requirements that favor early-compliant exporters.
- Automated:GPS-guided boom control integrated with real-time canopy sensors is opening premium service-contract revenue streams in Australia's wheat belts, though technician scarcity for automated guidance calibration constrains deployment velocity.
- Manual:Knapsack and handheld configurations persist across India's smallholder tier where capital constraints override mechanization incentives.
- Electric:Mains-powered units serve protected cultivation facilities in China's Shandong and Jiangsu provinces where grid access is reliable.
Manual technology retains volume dominance, yet Battery Powered is gaining share fastest as diesel dependency becomes economically and regulatorily costly.
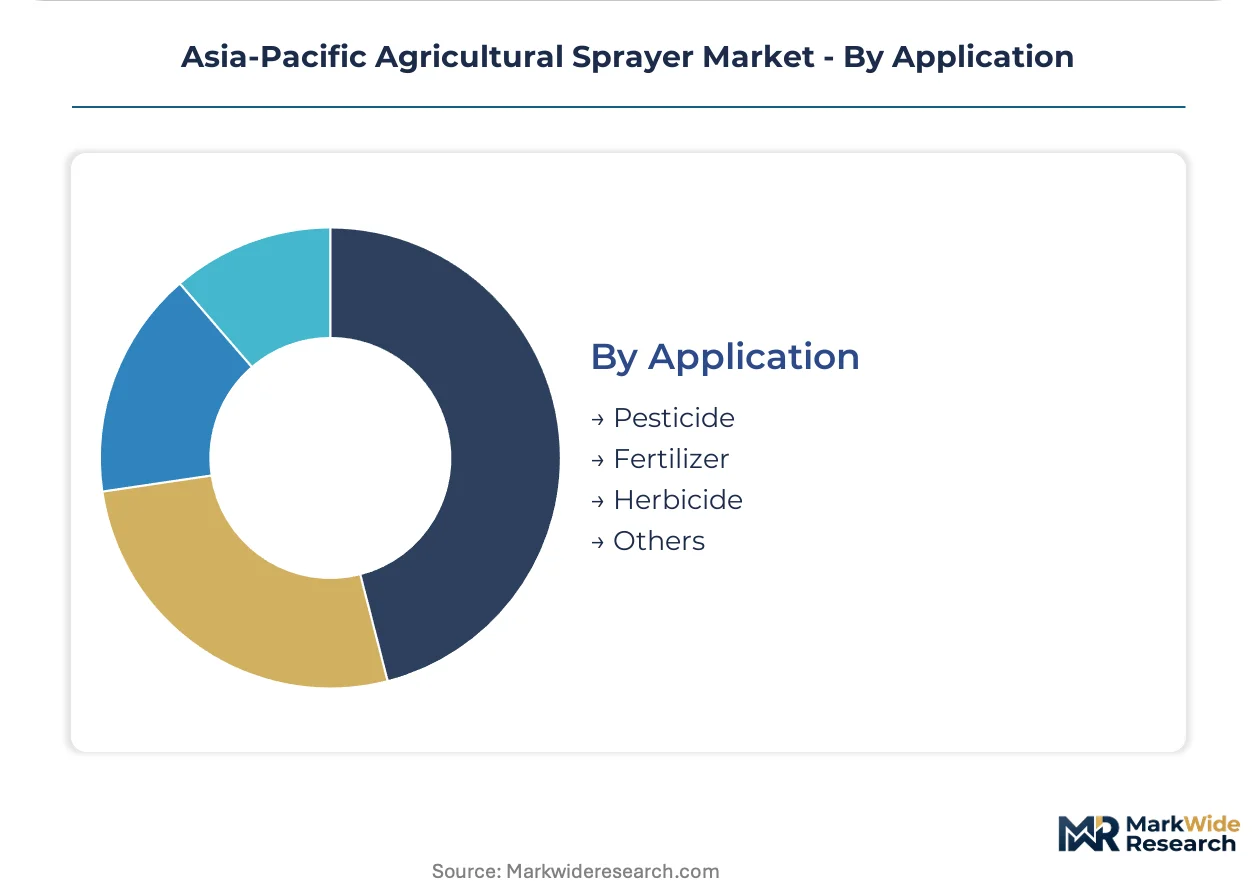
Application:
Chemical efficacy requirements and drift liability exposure shape nozzle specification and pressure regulation system design.
- Pesticide:China's GB standards for pesticide application equipment mandate droplet spectrum testing and drift reduction certification for all domestic sales, forcing redesign of nozzle manifolds and pressure regulation systems that falls heaviest on low-cost producers in Zhejiang and Shandong provinces.
- Herbicide:Glyphosate resistance management protocols in Australian broadacre operations require precision application to minimize off-target damage, driving specification of pulse-width modulation nozzle control.
- Fertilizer:Liquid fertilizer injection systems integrate with variable-rate controllers in China's Northeast Plain corn-soy rotations.
- Others:Growth regulator and micronutrient applications serve specialized horticultural segments in Thailand and the Philippines.
Pesticide application generates the steepest equipment specification requirements, while Herbicide is climbing fastest as resistance management intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics tilt toward domestic manufacturing across the Asia-Pacific Agricultural Sprayer Market, with India and China reducing equipment import dependency while Australia maintains specialized nozzle and precision-component sourcing from European suppliers.
India
Rice and wheat cooperatives across Punjab and Haryana drive fleet renewal through state agricultural machinery corporations. The PLI scheme for farm mechanization compresses procurement timelines toward certified equipment. The Indo-Gangetic Plain corridor concentrates demand for tractor-mounted units above 400-liter capacity.
China
Northeast Plain corn-soy rotations and Yangtze Delta horticulture intensify precision spraying requirements. MIIT's precision agriculture mandates reshape equipment certification through GB standards for pesticide application equipment. Shandong and Zhejiang manufacturing clusters consolidate toward drift-reduction-capable suppliers.
Australia
Queensland and New South Wales broadacre wheat operations specify GPS-guided boom configurations. APVMA drift mitigation labeling mandates precision nozzle specifications that filter equipment eligibility. Melbourne and Adelaide precision-agriculture service hubs calibrate automated guidance networks for section-control deployment.
Japan
Fragmented paddy field geometries in Honshu and Kyushu sustain demand for compact electric configurations. METI energy-efficiency benchmarks for battery-powered farm equipment cascade into ASEAN supply chain design requirements. Osaka-based fabrication clusters specialize in lithium-ion pack integration for confined-field access.
Vietnam
Mekong Delta plantation consolidation beyond 50 hectares generates concentrated demand for tractor-mounted boom sprayers. Corporate farming ventures prioritize variable-rate application infrastructure for intensive rice and fruit production. Ho Chi Minh City distribution channels anchor equipment procurement for southern delta operations.
Asia-Pacific Agricultural Sprayer Market Competitive Environment
Concentration sits with diversified agricultural equipment conglomerates controlling integrated distribution networks. The vendor base stratifies across three tiers: premium precision-technology suppliers, mid-market mechanization specialists, and commodity knapsack fabricators. Strategic moves center on dealership network densification in India's tier-two districts and electrostatic spraying technology licensing for Australian high-value crop segments.
Within the premium precision tier, Deere & Company and Kubota Corporation exemplify technology-forward positioning through automated guidance integration. Mahindra & Mahindra Ltd anchors the mid-market mechanization vector with extensive Indian distribution penetration. Chinese and Korean fabrication houses occupy the scale-driven segment, with Daedong Industrial Co., Ltd representing consolidated East Asian manufacturing capacity for regional export supply.
| Leading Market Players |
|---|
| Deere & Company |
| Mahindra & Mahindra Ltd |
| CNH Industrial N.V. |
| AGCO Corporation |
| Kubota Corporation |
| ASPEE Agro Equipment Pvt Ltd |
| Iseki & Co., Ltd |
| Escorts Limited |
| Daedong Industrial Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization disparities between China's Shandong fabrication clusters and India's domestic assembly plants create divergent cost floors across the Asia-Pacific Agricultural Sprayer Market. Scale advantages in precision nozzle manufacturing concentrate pricing power among integrated suppliers serving Australia's drift-mitigation-certified equipment tier, while fragmented knapsack assembly in Zhejiang province compresses margins through commoditized output.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in tractor-mounted sprayer procurement. Price differentiation rests on ISOBUS certification grade and after-sales service bundling, with Australia's broadacre cooperatives least sensitive due to total-cost-of-ownership contracting. Pricing pressure stems from steel and aluminum input volatility squeezing margin pools for domestic Indian and Chinese manufacturers. India's sub-two-hectare smallholders exhibit highest price sensitivity, perpetuating handheld sprayer reliance despite mechanization incentives.
Supply Chain Analysis
Inventory lead times for lithium-ion battery packs and precision nozzle manifolds extend procurement cycles for electrified configurations across Southeast Asian plantation operators. Manufacturing concentration centers on China, India, and South Korea, with raw material dependencies spanning steel boom fabrication, aluminum chassis casting, and injection-molded tank polymers. Single-source vulnerability in precision guidance sensor supply creates exposure for Australian equipment assemblers. Distribution runs through state agricultural machinery corporations in India's cooperative procurement belt and dealer networks in Australia's broadacre regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Agricultural Sprayer Market is recovering from cyclical compression as irrigation infrastructure investment across India's Indo-Gangetic Plain triggers cooperative fleet renewal waves.
For Market Incumbents: Fortify precision-technology differentiation through ISOBUS compatibility investments and electrostatic spraying licensing for Australian high-value crop segments. Deepen backward integration into lithium-ion pack assembly to offset battery cost volatility threatening margin stability in electrified product lines. For New Entrants and Emerging Players: Lead with battery-electric compact configurations targeting Japan's fragmented paddy field geometries where field access constraints prevent tractor deployment. Penetrate Vietnam's Mekong Delta plantation consolidation through variable-rate application service contracts rather than equipment-only sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision-agriculture service providers with automated guidance calibration capabilities. Long-term viability favors acquisition targets with METI energy-efficiency pre-certification and established ASEAN supply chain relationships. Monitor BIS certification timeline compression as an inflection indicator for import-substitution acceleration in India's equipment market.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium-Ion Pack Assembly | Captures battery cost compression benefits for Southeast Asian electrification demand. |
| ISOBUS Certification Investment | Unlocks premium positioning in India's cooperative procurement tender systems. |
| Electrostatic Spraying Technology Licensing | Addresses APVMA drift mitigation mandates across Australian cotton and vineyard operations. |
| State Machinery Corporation Partnership | Secures volume allocation in India's Punjab and Haryana fleet renewal programs. |
| Precision Nozzle Manufacturing Scale-Up | Meets GB standards compliance burden consolidating China's Zhejiang and Shandong supplier base. |
Study Parameters
Initial hypotheses were tested against primary input from agricultural equipment procurement officers, precision agriculture service technicians, state machinery corporation directors, and plantation operations managers and refined through secondary validation. Primary fieldwork combined structured interviews with equipment manufacturers and cooperative purchasing committees across India's Indo-Gangetic Plain. Secondary sources encompassed BIS certification records, APVMA drift mitigation labeling databases, MIIT precision agriculture equipment filings, and customs trade data for agricultural machinery imports. Bottom-up equipment shipment analysis and top-down agricultural chemical application intensity modeling were triangulated to reconcile volume estimates.
Variance decomposition across the projection horizon isolates technology substitution effects, regulatory compliance cost pass-through, and cooperative procurement channel shifts as primary forecast drivers. Segmentation dimensions modeled include equipment configuration, powertrain architecture, application chemistry, and regional regulatory cluster intensity. CAGRs were derived from equipment replacement cycle compression analysis and lithium-ion cost curve trajectory integration. Industry-specific inputs incorporate PLI scheme incentive qualification rates and METI energy-efficiency benchmark adoption timelines.
Forecasts assume regulatory continuity in India's BIS certification regime, China's GB standards enforcement, and Australia's APVMA labeling requirements; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
United States Agricultural Irrigation Machinery Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Planting Equipment Market